
 PET Containers Market | 2026-2036
PET Containers Market Size, Share, and Industry Trends Forecast 2026-2036
PET Containers Market Outlook
Packaging engineer talent is rotating from rigid formats into circular-design roles faster than universities can replenish specialized polymer technologists, tightening the labor pool for lightweighting and recycled-content integration. Amcor plc leverages captive rPET washing and pelletizing capacity across European plants to secure feedstock certainty. Berry Global anchors North American supply through blow-molding scale in dairy and juice segments. ALPLA Werke Alwin Lehner GmbH & Co KG dominates central European refillable PET systems through long-term bottler partnerships.
PET containers are thermoformed or blow-molded vessels constructed from polyethylene terephthalate resin, typically offering barrier properties against oxygen and carbon dioxide at wall thicknesses of 0.25–0.50 mm for standard bottles. These containers serve primarily to preserve carbonated beverages, edible oils, and personal care formulations while enabling transparent product display. Bottles command the largest volume share within product type segmentation, though trays are gaining fastest in fresh-protein and ready-meal applications where modified-atmosphere compatibility matters. The 500ml to 1L capacity band captures dominant beverage economics, while sub-500ml formats compete with aluminum in on-the-go portability.
The FDA maintains food-contact notification requirements for post-consumer recycled PET, while the EU F-Gas Regulation and REACH restrict certain additives in container manufacturing. Germany's national packaging law enforces minimum rPET quotas that cascade through converter specifications. The EU Green Deal's plastics circularity targets are tightening embodied-carbon thresholds for imported containers. Stakeholders must monitor evolving extended-producer-responsibility fee structures and pre-emptively certify recycled-content claims against emerging audit standards.
Market Dynamics
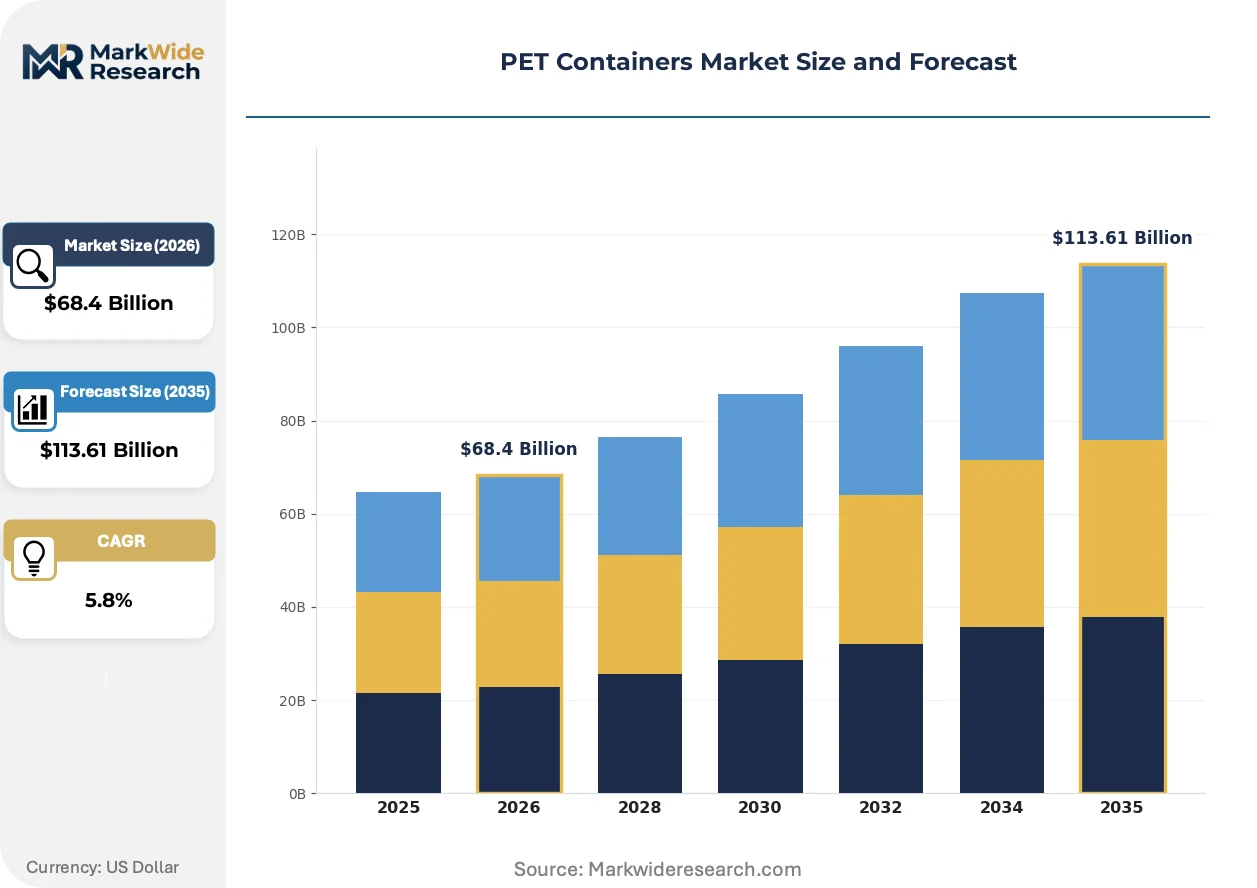
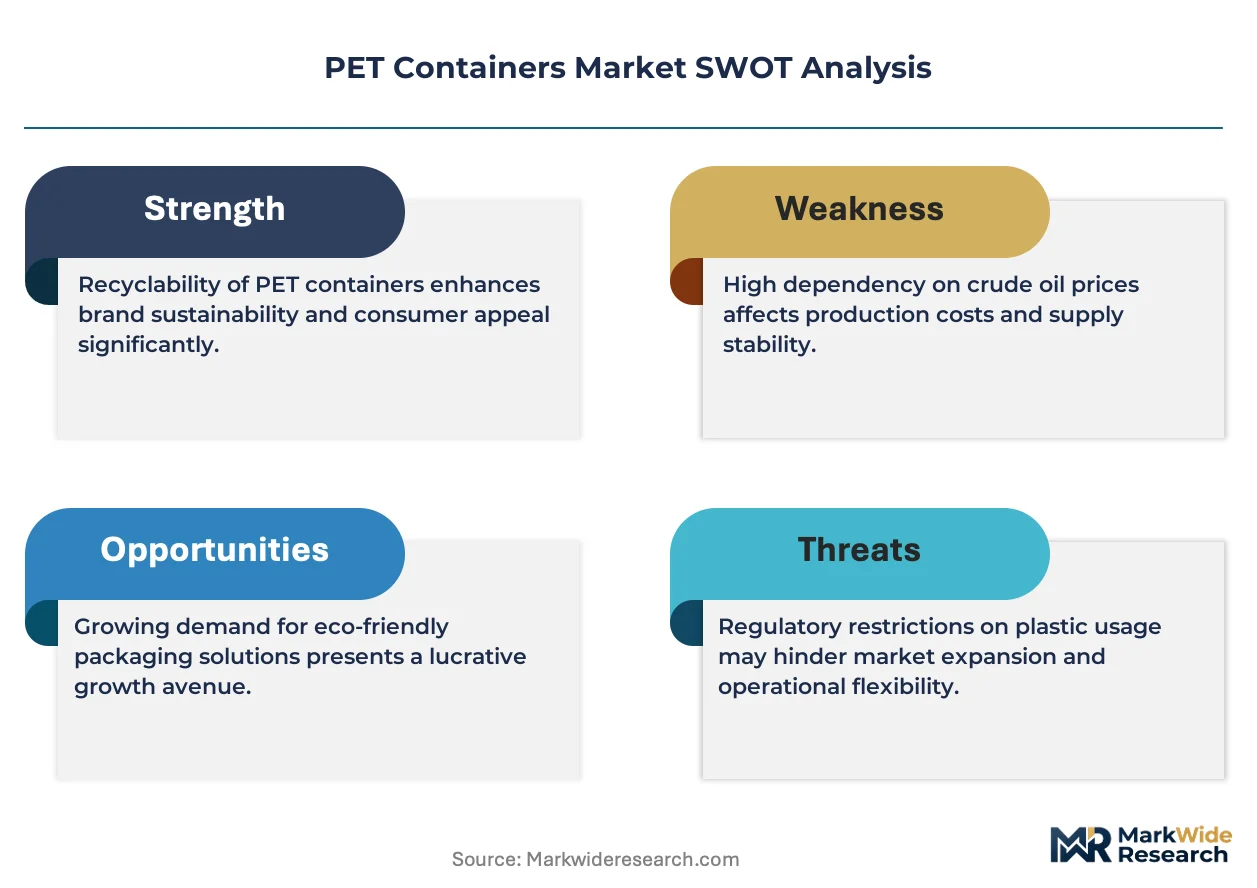
Lightweighting mandates and rPET integration requirements are compressing converter margins while simultaneously raising technical barriers to entry across blow-molding and thermoforming operations.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled-content floors are pulling virgin-PET substitution through beverage supply chains, creating guaranteed offtake for circular container formats.
- Carbonated soft drink bottlers:Brand-level net-zero commitments are accelerating lightweight PET adoption as Scope 3 emission reduction levers.
- Germany's deposit-return infrastructure:High collection rates and centralized washing capacity are generating feedstock certainty that neighboring markets lack.
Market Restraints
- rPET flake price volatility:Post-consumer bale competition from fiber and sheet applications creates input cost instability for bottle-grade converters.
- Food-contact certification timelines:FDA notification requirements for novel recycling processes extend qualification periods to 18-24 months.
- Aluminum can substitution:Sub-500ml beverage formats face displacement where chill-chain infrastructure supports metal packaging economics.
Strategic Opportunities
- Fresh-protein tray segment:Modified-atmosphere compatibility requirements are opening thermoformed PET penetration against expanded polystyrene in European retail.
- Refillable bottle systems:Long-term bottler partnerships in Austria and Switzerland are creating captive demand for durable, multi-trip container designs.
- Digital deposit-return integration:Smartphone-based reverse-vending pilots in Nordic markets are reducing collection infrastructure capital intensity.
Industry Challenges
- Circular-design polymer technologist scarcity:Universities are not replenishing specialized talent as packaging engineers migrate from rigid formats into sustainability roles.
- Legacy blow-molding asset retrofit costs:Existing equipment requires substantial modification to process high-rPET blends without optical or mechanical degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Containers Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tubs, Trays End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Shape: Rectangular, Round, Square, Custom Capacity: Less than 500ml, 500ml to 1L, 1L to 5L, More than 5L |
| Companies Covered | Amcor plc, Berry Global, Silgan Holdings, Graham Packaging Company, Gerresheimer AG, ALPLA Werke Alwin Lehner GmbH & Co KG, Plastipak Holdings, Resilux NV, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Containers Market Strategic Shifts
Active and passive barrier technologies are diverging in application as shelf-life requirements fragment across beverage categories and geographic markets. This divergence is reshaping resin formulation strategies and equipment investment priorities simultaneously.
Barrier-enhanced PET is bifurcating between monolayer scavenger additives for short-shelf carbonated drinks and multilayer structures with oxygen-impermeable interlayers for sensitive juices and functional beverages. Premium beverage brands in Japan and South Korea are adopting the latter at accelerated rates. The technology is bifurcating converter capabilities into high-volume commodity producers versus specialized barrier-film integrators.
REACH restrictions on certain additive chemistries are forcing reformulation of UV stabilizers and colorants used in personal-care PET packaging. ECHA substance evaluation processes are extending approval timelines for novel polymer modifiers. German cosmetic brands are responding by accelerating qualification of mineral-based alternative stabilizers ahead of regulatory deadlines.
Retailers are consolidating container specifications to reduce SKU complexity and simplify reverse-logistics for private-label beverage lines. Discounters in France and Belgium are driving standardization around three neck-finish diameters across still and carbonated water categories. This concentration is squeezing mid-tier converters unable to achieve scale economics on standardized formats.
PET Containers Market Segmentation
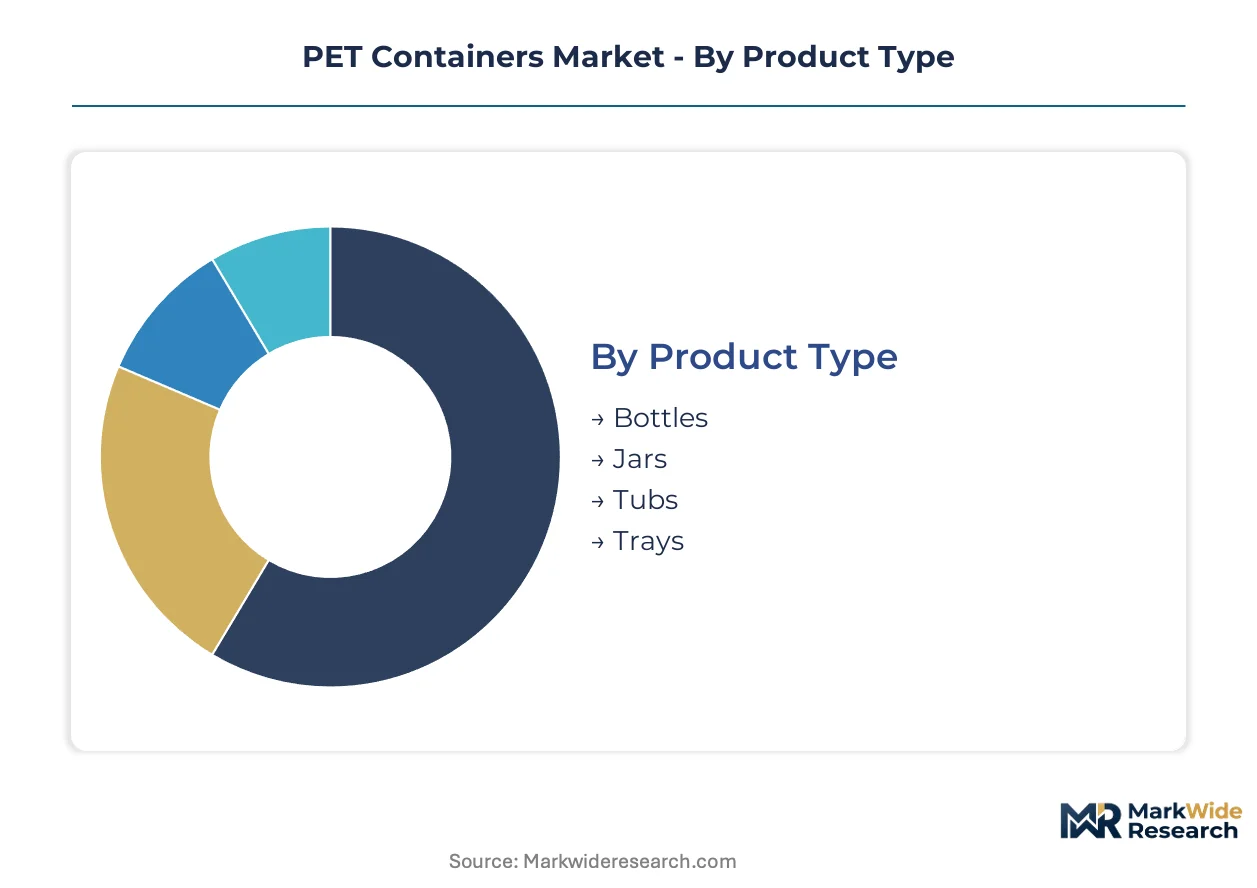
PET container converters segment demand across four structural dimensions that dictate equipment investment, resin formulation, and geographic sales strategy. Each category reveals distinct margin profiles and technical barriers that shape competitive positioning among blow-molding and thermoforming specialists.
Product Type:
Bottles dominate export-led demand from centralized European and North American production hubs, while trays and tubs serve more fragmented domestic fresh-protein and dairy markets.
- Bottles:Blow-molded vessels with 0.25–0.50 mm wall thickness provide carbonation barrier and transparent display for beverages and edible oils. Carbonated soft drink bottlers in Germany and Austria are consolidating specifications around lightweight, high-rPET formats to meet EU Single-Use Plastics Directive mandates.
- Trays:Thermoformed structures with modified-atmosphere compatibility penetrate European retail meat and ready-meal segments. French and Belgian discounters are standardizing tray specifications to simplify reverse-logistics, pulling volume from expanded polystyrene incumbents.
- Jars:Wide-mouth containers serve spreads, sauces, and personal care creams with reclosure requirements. Domestic production clusters in Italy and Spain supply regional food brands.
- Tubs:Shallow cylindrical formats target dairy, confectionery, and industrial lubricants. Margins compress where commodity converters compete on cycle time.
Bottles command the established base. The steepest expansion runs through trays.
End Use Industry:
Application-driven cost tiers separate premium certified formats from commodity volume plays, with food-contact compliance timelines creating divergent margin structures.
- Food & Beverage:The largest demand pool spans carbonated drinks, bottled water, juices, and edible oils with strict oxygen and CO2 barrier requirements. FDA food-contact notifications and EU rPET quotas are extending qualification periods and raising technical barriers for new entrants.
- Personal Care:UV stabilizers and colorants face REACH reformulation pressures, forcing mineral-based alternatives ahead of ECHA deadlines. German cosmetic brands are accelerating qualification timelines.
- Household Products:Detergents and cleaning chemicals tolerate higher recycled content without optical constraints. Price sensitivity dominates procurement.
- Pharmaceuticals:Child-resistant closures and moisture barriers require specialized validation. Regulatory scrutiny from FDA and EMA limits supplier switching.
Food & Beverage anchors volume concentration. Personal Care is climbing the fastest on sustainability-driven premiumization.
Shape:
Volume economics and shelf-space efficiency drive standardization, with custom formats reserved for brand-differentiated premium positioning.
- Round:The dominant blow-molding format for beverages offers uniform wall distribution and efficient palletization. German deposit-return systems favor standardized round geometries for washing-line compatibility.
- Rectangular:Trays and dairy tubs maximize retail shelf density. French retailers are consolidating private-label specifications around rectangular fresh-protein formats.
- Square:Space-efficient shipping configurations appeal to e-commerce detergent and household chemical brands. Asian logistics hubs favor cube utilization.
- Custom:Ergonomic grips and proprietary silhouettes command design fees from premium cosmetic and functional beverage marketers.
Round shapes hold the volume base. Rectangular formats are gaining share fastest in European retail consolidation.
Capacity:
Customer type fragmentation separates on-the-go portability from household stock-up economics, with aluminum substitution threatening the smallest formats.
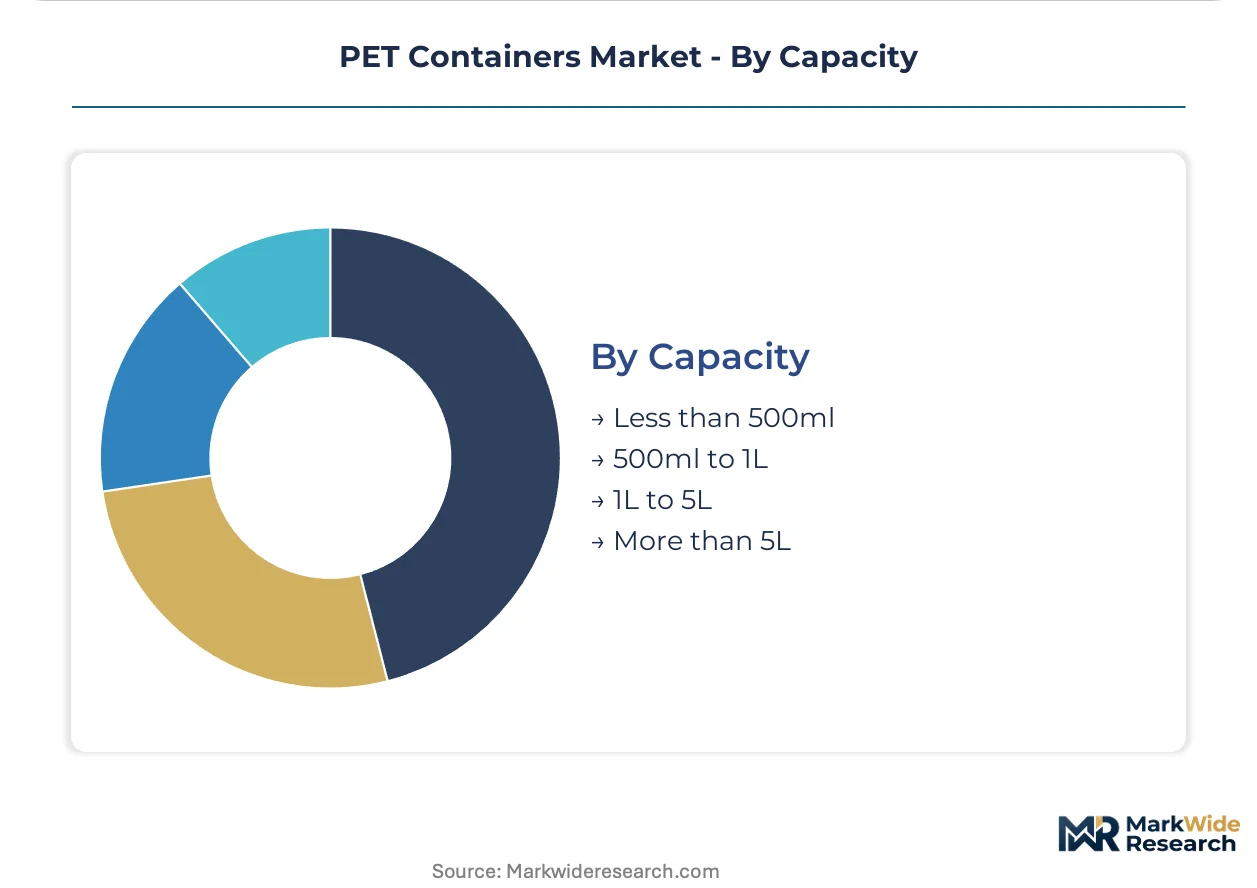
- 500ml to 1L:The dominant beverage economics band balances portability with per-unit profitability. German and Austrian refillable systems concentrate demand in this range.
- Less than 500ml:Sub-500ml formats compete directly with aluminum cans where chill-chain infrastructure supports metal packaging economics. Japanese convenience stores drive premium miniaturization.
- 1L to 5L:Family-size and food-service formats require reinforced handles and stacking strength. Italian olive oil and North American juice brands anchor demand.
- More than 5L:Industrial and institutional bulk containers face pressure from bag-in-box and rigid HDPE alternatives. Limited growth trajectory.
The 500ml to 1L band commands the established base. The sub-500ml segment faces the most volatile competitive dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's deposit-return infrastructure pulls rPET feedstock toward beverage bottlers, while the United States and China concentrate demand in divergent end-use mixes—household chemicals and industrial bulk versus premium beverage exports.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia consolidate lightweight, high-rPET specifications to meet EU Single-Use Plastics Directive mandates. The national packaging law enforces minimum recycled-content quotas that cascade through converter procurement. Hamburg anchors northern European rPET washing and pelletizing capacity, securing feedstock certainty for circular container formats.
United States
Household product and industrial lubricant demand tolerates higher recycled content without optical constraints, concentrating procurement in the Midwest and Gulf Coast. FDA food-contact notification requirements extend qualification timelines for novel recycling processes. Chicago and Houston host blow-molding scale operations serving private-label detergent and cleaning chemical brands.
China
Premium beverage export manufacturing clusters in the Yangtze River Delta and Pearl River Delta, with modified-atmosphere tray production expanding for domestic fresh-protein retail. The country's national standards regulator maintains evolving food-contact specifications for post-consumer recycled materials. Shanghai and Shenzhen converters invest in barrier-enhanced multilayer structures for sensitive juice and functional beverage exports to Japan and South Korea.
France
Discounters drive standardization around three neck-finish diameters across still and carbonated water categories, consolidating SKU complexity for private-label lines. REACH restrictions on additive chemistries force reformulation of UV stabilizers ahead of ECHA deadlines. The Île-de-France region anchors retail procurement headquarters that cascade specification requirements through converter networks.
Japan
Premium beverage brands accelerate adoption of multilayer oxygen-impermeable structures for extended shelf-life requirements. METI guidelines shape container recycling targets that influence converter investment priorities. The Kanto region around Tokyo concentrates demand for miniaturized sub-500ml formats competing with aluminum in convenience store channels.
PET Containers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale-driven commodity producers differentiated from barrier-film integrators and regional refillable-system operators. The market structure concentrates blow-molding capacity among vertically positioned resin processors and captive brand suppliers. Three archetypes dominate: integrated resin-to-container converters, specialized barrier-technology licensors, and deposit-return system operators with long-term bottler partnerships. Competitive moves center on backward integration into rPET washing capacity and strategic partnerships for refillable bottle system deployment.
Within the integrated converter tier, Amcor plc and Berry Global exemplify scale-driven positioning across European and North American production networks. ALPLA Werke Alwin Lehner GmbH & Co KG occupies a distinctive position in central European refillable systems through durable, multi-trip container designs. These three entities represent divergent strategic vectors—captive rPET feedstock security, blow-molding scale in dairy and juice segments, and long-term bottler partnerships in deposit-return markets.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Silgan Holdings |
| Graham Packaging Company |
| Gerresheimer AG |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Plastipak Holdings |
| Resilux NV |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German beverage bottlers and rPET converters lock in feedstock access and price visibility against virgin-PET volatility, embedding EU Single-Use Plastics Directive compliance costs into contract structures before spot markets clear.
Pricing Analysis
Contract-based long-term offtake dominates converter-bottler relationships, with pricing stratifying across premium food-contact-certified, standard industrial-grade, and economy non-food tiers. Price differentiation hinges on rPET content percentage and FDA notification status, with virgin-PET substitution mandates compressing margins in the standard tier. Cost compression in economy grades intensifies because fiber and sheet applications compete for post-consumer bale supply. Household chemical buyers exhibit highest price sensitivity, while pharmaceutical and premium beverage segments absorb certification premiums.
Supply Chain Analysis
Strategic stockpiling of post-consumer bales during seasonal collection peaks distinguishes German and Austrian converters from just-in-time competitors elsewhere in Europe. Feedstock concentration centers on Germany, France, and Spain, where deposit-return infrastructure generates bottle-grade flake. Raw material dependencies encompass virgin-PET resin, rPET flake, and scavenger additives for barrier formulations. Single-source vulnerability runs through centralized European rPET washing capacity. Distribution feeds from converter plants directly to bottler filling lines under vendor-managed inventory arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET container economics are approaching a platform inflection as deposit-return interoperability across EU member states creates network effects for circular-format suppliers, with Germany's infrastructure serving as the interoperability template.
For Market Incumbents: Consolidate rPET washing capacity in Hamburg and Bavaria to secure feedstock certainty before EU Green Deal quotas tighten. Anchor blow-molding scale through long-term bottler partnerships in refillable systems, neutralizing aluminum substitution threats in sub-500ml formats via lightweighting R&D investment. For New Entrants and Emerging Players: FDA food-contact notification fast-track positions converters for US beverage market entry ahead of 18-24 month qualification timelines. White-space targets include fresh-protein trays in French retail and barrier-enhanced multilayer structures for Japanese functional beverage exports. Go-to-market leverage rests on mineral-based UV stabilizer qualification ahead of REACH deadlines. For Investors and Strategic Acquirers: Capital is best deployed toward captive rPET infrastructure operators with deposit-return system partnerships, given five-to-ten year visibility on EU recycled-content mandates. Acquisition archetype: regional blow-molding specialists with unutilized thermoforming capacity for tray expansion. Signal to monitor: rPET flake price spreads against virgin-PET as feedstock competition from fiber applications intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Washing | Secures feedstock certainty against fiber-application competition under EU quotas. |
| Refillable System Partnership | Creates captive demand through multi-trip container designs in German-speaking markets. |
| Barrier-Enhanced Multilayer Investment | Captures premium Japanese and South Korean functional beverage shelf-life requirements. |
| Fresh-Protein Tray Capacity Expansion | Displaces expanded polystyrene in French and Belgian retail consolidation. |
| Digital Deposit-Return Pilot | Reduces collection infrastructure capital intensity in Nordic smartphone-based reverse-vending. |
Study Parameters
Desk research of EU regulatory filings, FDA food-contact notifications, and trade association capacity databases preceded structured interviews with blow-molding plant managers, beverage procurement leads, rPET washing operators, and retail category buyers. Primary fieldwork combined with secondary validation from customs records and resin producer disclosures. Bottom-up capacity modeling triangulated against top-down demand aggregation across end-use segments.
Variance decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions encompassed product type, end-use industry, capacity band, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, rPET infrastructure buildout timelines, and substitution elasticity estimates for aluminum displacement in sub-500ml formats.
Decision-makers should treat outputs as directional under assumptions of sustained EU Single-Use Plastics Directive enforcement and stable deposit-return collection rates; material deviation in rPET flake availability or REACH additive restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Compartment Trays Market
Containers
Car Lube Container Market
Containers
Trigger Sprayer Market
Containers
Concentrate Containers Market
Containers
Light Resistant Containers Market
Containers
Oblong Tub Lids Market
Containers
Mini Spray Bottles Market
Containers
Stainless Steel Cask Market
Containers
Tottle Containers Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Compartment Take-Out Container Market
Containers
Global Container Monitoring Market
Containers
Multi Cavity Tray Market
Containers
Global Styrene Compartment Boxes Market
Containers
Lift-Off Lid Box Market
Containers
Canning Jars Market