
 North America Insulated Shipping Containers Market | 2026-2036
North America Insulated Shipping Containers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulated Shipping Containers Market Analytics
Pharmaceutical logistics is broadening its share of insulated container procurement across North America. Sonoco Products Company leverages its structural packaging expertise to serve temperature-sensitive drug distribution networks. Sealed Air Corporation anchors its position through advanced barrier foam technologies that protect payload integrity during extended transit. Cold Chain Technologies specializes in reusable thermal packaging systems that reduce waste for biopharmaceutical shippers.
Insulated shipping containers are enclosed thermal-protection units engineered with foam-injected walls, vacuum-insulated panels, or phase-change materials to maintain specified temperature ranges between minus eighty degrees Celsius and plus twenty-five degrees Celsius for perishable cargo. Their primary commercial purpose centers on eliminating temperature excursions that degrade pharmaceutical efficacy, spoil fresh produce, or destabilize chemical reagents during ground and air transit. Rigid containers dominate current procurement volumes due to their crush resistance and stackability in pharmaceutical distribution, while flexible containers capture expanding share among last-mile meal-kit and grocery delivery services seeking lower cube utilization on return legs. Palletized solutions concentrate margin pools in high-value biologics lanes where thermal mass and payload density justify premium positioning.
The FDA enforces strict Current Good Manufacturing Practice guidelines that mandate documented cold-chain integrity for vaccines and biologics moving through interstate commerce. The EPA regulates foam blowing agents and refrigerant phase-change materials under evolving ozone-depletion and global-warming-potential frameworks that compel material substitutions. Health Canada and Transport Canada jointly oversee cross-border temperature-controlled shipments through harmonized hazardous materials and food safety protocols. Stakeholders must monitor how overlapping federal and provincial requirements reshape material compliance costs and container certification pathways.
Market Dynamics
FDA serialization mandates and temperature integrity rules are compressing procurement timelines across pharmaceutical distribution networks. Shippers now face dual pressure to validate thermal performance while documenting chain-of-custody at the unit level.
Growth Catalysts
- Biologics cold-chain expansion:Cell and gene therapies require minus eighty degrees Celsius stability, driving specialized container specifications across United States distribution corridors.
- EPA refrigerant phase-down mandates:Hydrofluorocarbon restrictions under AIM Act timelines are forcing material substitutions toward lower global-warming-potential blowing agents.
- Meal-kit channel proliferation:Direct-to-consumer fresh food platforms in Canadian urban centers are absorbing flexible pouch formats for last-mile temperature control.
Market Restraints
- Polyurethane foam input volatility:Isocyanate and polyol feedstock prices fluctuate with crude oil indices, compressing margins for rigid container manufacturers.
- Vacuum-insulated panel supply concentration:Core material production clusters in East Asian manufacturing zones create single-source vulnerability for North American assemblers.
- Cross-border harmonization friction:Divergent Health Canada and FDA validation protocols force redundant testing for containers serving transcontinental lanes.
Strategic Opportunities
- Reusable system penetration in Great Lakes corridor:Pharmaceutical manufacturing clusters around Chicago and Detroit present density for closed-loop container pooling models.
- Phase-change material convergence with IoT sensing:Integration of thermal mass media with real-time temperature loggers enables predictive excursion alerts.
- USDA BioPreferred procurement preference:Federal purchasing guidelines for bio-based content create specification tailwinds for plant-derived insulation formulations.
Industry Challenges
- Thermal engineering talent scarcity:Container design requires cross-disciplinary expertise in materials science and cold-chain logistics that outpaces academic pipeline output.
- Validation protocol timeline compression:ISTA 7E summer and winter profile testing cycles extend new product introduction schedules by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulated Shipping Containers Market |
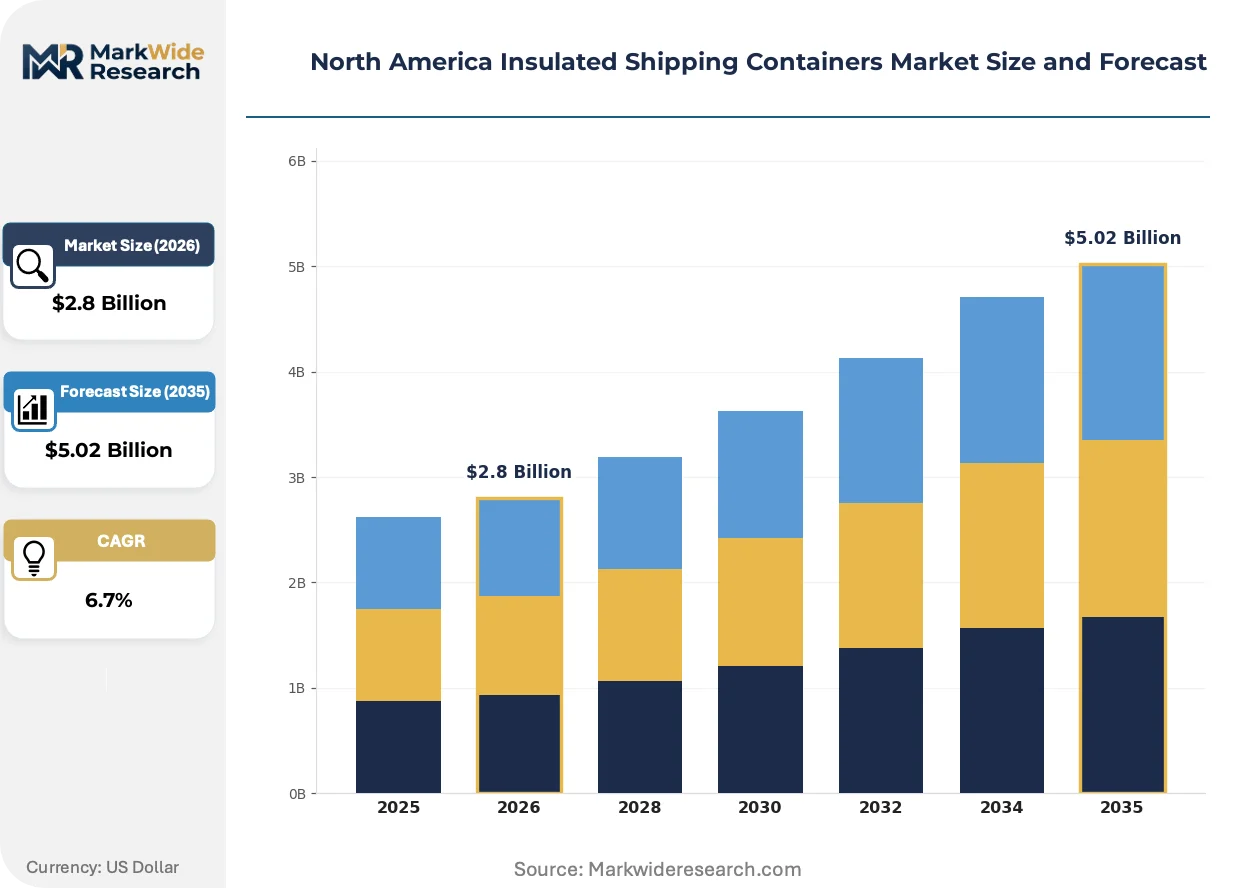
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Flexible Containers, Palletized Solutions, Bulk Containers Material: Foam, Polyethylene, Polystyrene, Composite Materials End User: Food Industry, Pharmaceuticals, Chemicals, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | Sonoco Products Company, Sealed Air Corporation, Berry Global, Inc., Pactiv Evergreen Inc., WestRock Company, Cold Chain Technologies, Therapak, Polar Tech Industries, Softbox Systems Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulated Shipping Containers Market Evolving Landscape
Active thermal management systems are displacing passive insulation in high-value pharmaceutical lanes. Sensor-integrated containers now command specification preference among biologics shippers seeking real-time visibility.
Vacuum-insulated panel technology is unifying extreme-temperature performance with reduced dimensional mass. Gene therapy distributors in Massachusetts and North Carolina are specifying VIP-core containers for minus eighty degrees Celsius stability during extended transit. This convergence is unifying payload density optimization with regulatory compliance documentation, compressing total cost-per-shipment for temperature-critical biologics.
The EPA Significant New Alternatives Policy program is accelerating hydrofluorocarbon transitions in foam blowing agents. Container manufacturers must reformulate polyurethane systems to meet declining global-warming-potential thresholds under AIM Act phase-down schedules. Rigid container assemblers in the United States are responding by qualifying hydrocarbon and hydrofluoroolefin-based alternatives ahead of 2025 compliance windows.
Shippers are consolidating supplier relationships around integrated validation service capabilities. Large pharmaceutical distributors are replacing transactional container procurement with multi-year performance contracts bundling equipment, monitoring, and documentation. This consolidation is most visible in Northeast corridor distribution hubs where FDA inspection intensity drives preference for single-accountability thermal partners.
North America Insulated Shipping Containers Market Segmentation
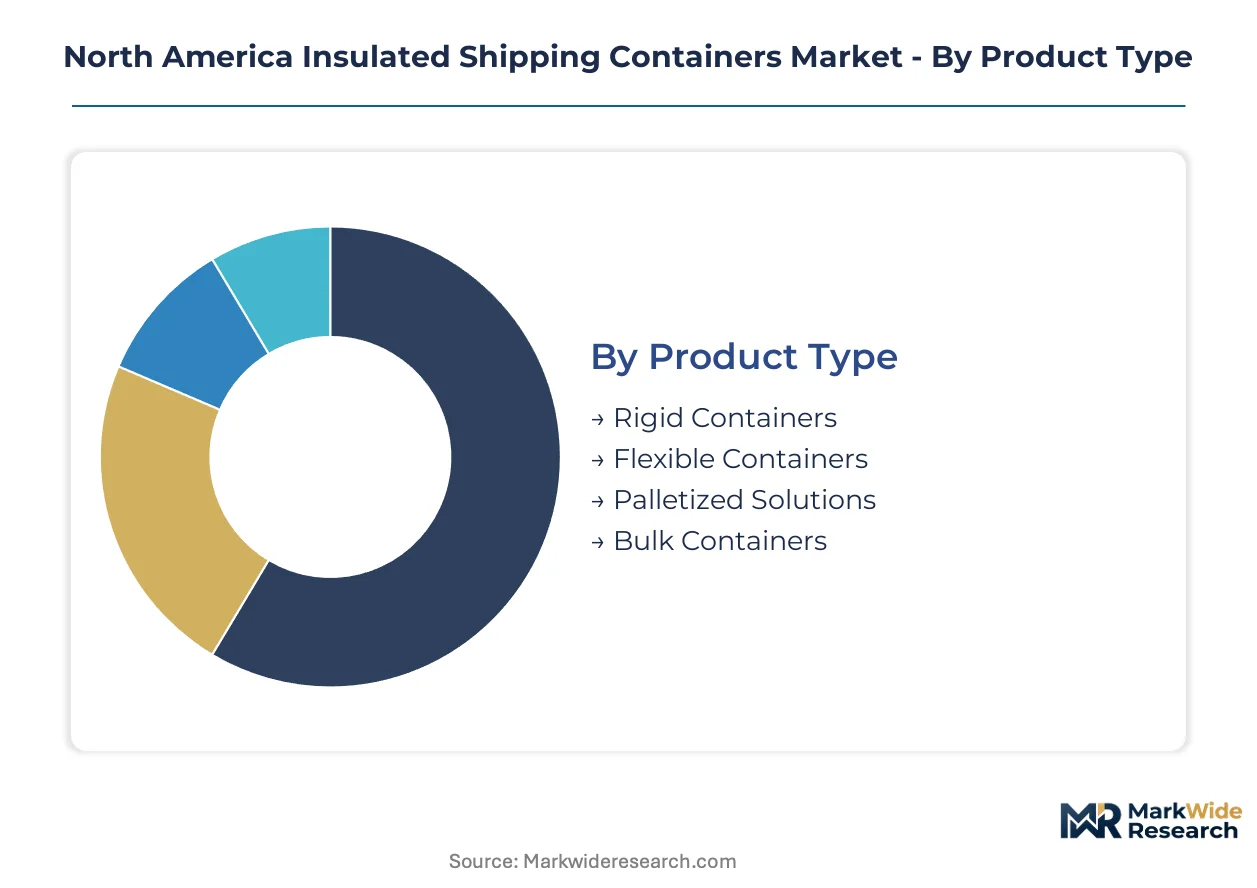
Insulated shipping container procurement across North America fragments along thermal performance requirements and regulatory validation burdens. Pharmaceutical shippers demand FDA-compliant documentation trails while food distributors prioritize cube efficiency and return logistics.
Product Type:
FDA serialization mandates and temperature integrity rules impose distinct certification pathways across container formats, with pharmaceutical lanes requiring ISTA 7E validation and food channels accepting simplified thermal testing.
- Rigid Containers:Foam-injected walls with crush-resistant exteriors withstand stacking pressures in pharmaceutical distribution centers. FDA-regulated biologics corridors around Boston and Research Triangle Park concentrate procurement of validated rigid formats with documented chain-of-custody capabilities.
- Flexible Containers:Lightweight pouch constructions with reflective barrier films reduce dimensional weight for last-mile meal-kit delivery. Canadian urban centers including Toronto and Vancouver absorb expanding volumes from direct-to-consumer fresh food platforms seeking lower return-trip cube utilization.
- Palletized Solutions:Thermal mass systems for high-value biologics with payload densities justifying premium positioning.
- Bulk Containers:Large-format insulated totes for agricultural commodity movements across Midwest processing corridors.
Leading the category by volume: Rigid Containers. Growing fastest: Flexible Containers.
Material:
EPA AIM Act phase-down schedules are forcing material substitutions that fragment cost structures across insulation chemistries, with hydrocarbon and hydrofluoroolefin alternatives commanding specification preference in federal procurement.
- Foam:Polyurethane systems dominate rigid container fabrication, though reformulation pressures under declining global-warming-potential thresholds are compressing margin structures for United States-based assemblers.
- Polyethylene:Rotomolded shells with expanded foam cores serve reusable pharmaceutical pooling models in Great Lakes manufacturing clusters.
- Polystyrene:Expanded bead insulation for economy-tier single-use food distribution with limited regulatory documentation requirements.
- Composite Materials:Vacuum-insulated panel cores with fiberglass or aerogel substrates for extreme-temperature gene therapy stability at minus eighty degrees Celsius.
Highest specification intensity: Composite Materials. Steepest volume expansion: Polyethylene.
End User:
Customer procurement patterns diverge sharply between regulated pharmaceutical networks requiring validation documentation and commodity food channels prioritizing unit economics.
- Food Industry:Fresh produce processors and meal-kit assemblers drive flexible container absorption across Canadian and United States urban delivery zones.
- Pharmaceuticals:Cell and gene therapy distributors mandate minus eighty degrees Celsius stability with real-time temperature logging, concentrating demand in Massachusetts and North Carolina biomanufacturing hubs.
- Chemicals:Temperature-sensitive reagent suppliers with moderate cold-chain requirements and reduced documentation burdens.
- Agriculture:Seed and biological input distributors with seasonal procurement patterns tied to planting cycles.
Dominant procurement value: Pharmaceuticals. Expanding most quickly: Food Industry.
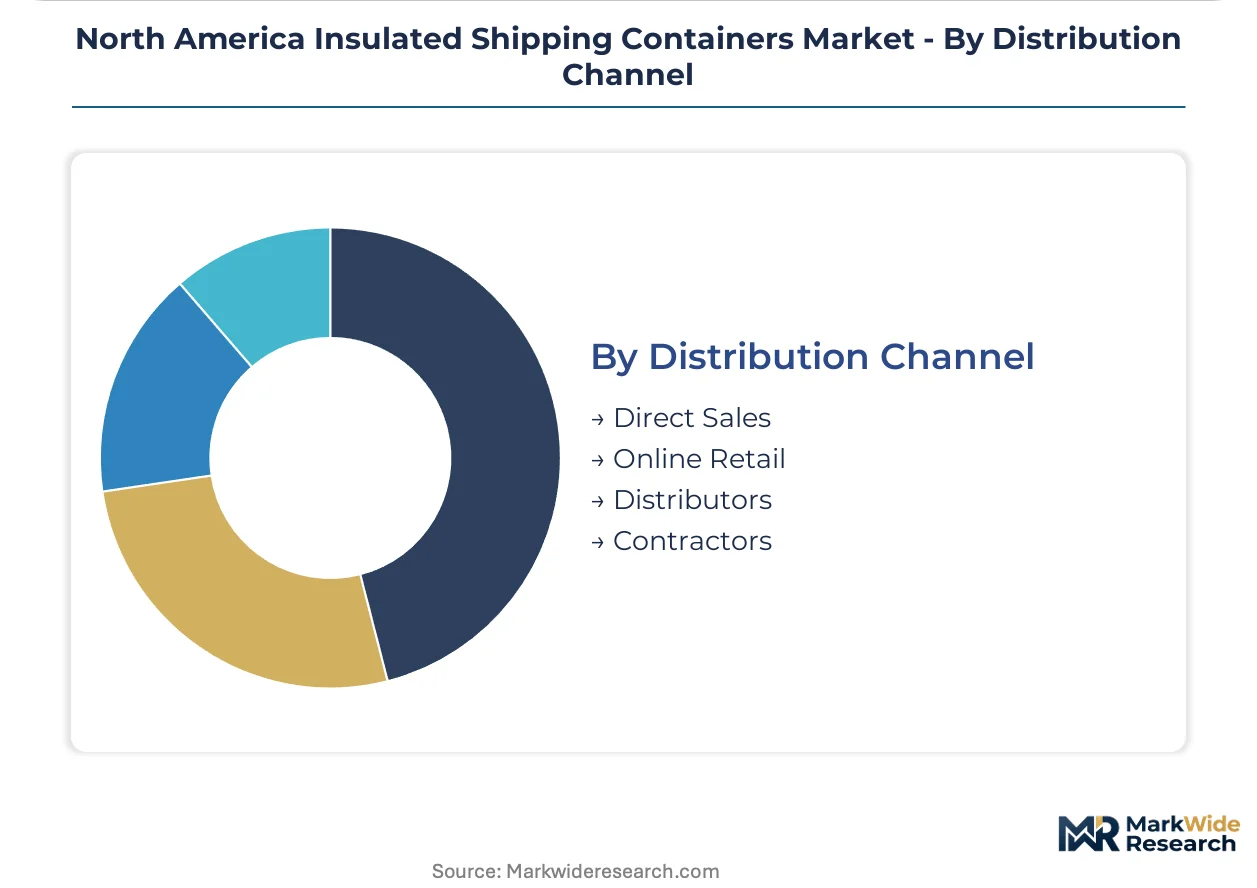
Distribution Channel:
Channel selection correlates with customer scale and validation complexity, with large pharmaceutical distributors consolidating around integrated service contracts.
- Direct Sales:Multi-year performance contracts bundling equipment, monitoring, and documentation dominate Northeast corridor pharmaceutical procurement, replacing transactional container purchasing.
- Distributors:Regional stocking networks serve mid-tier food processors and agricultural suppliers with standardized thermal products.
- Online Retail:Self-service procurement for small-scale meal-kit operators and specialty chemical shippers with limited customization requirements.
- Contractors:Project-based container supply for temporary cold-chain infrastructure in seasonal agricultural windows.
Capturing highest margin pools: Direct Sales. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container fabrication concentrates in Great Lakes industrial zones while consumption spreads across coastal pharmaceutical corridors and Canadian urban delivery networks. Domestic assembly serves temperature-critical logistics without heavy import dependence. Cross-border harmonization friction persists between FDA and Health Canada validation protocols.
United States
Cell and gene therapy distributors in Massachusetts and North Carolina drive demand for minus eighty degrees Celsius stability systems. FDA serialization mandates compress procurement timelines while requiring documented chain-of-custody at the unit level. Boston and Research Triangle Park biomanufacturing hubs concentrate specification of vacuum-insulated panel containers for extended transit.
Canada
Direct-to-consumer meal-kit platforms in Toronto and Vancouver absorb expanding volumes of flexible pouch formats for last-mile temperature control. Health Canada and Transport Canada jointly oversee cross-border temperature-controlled shipments through harmonized hazardous materials protocols. Ontario pharmaceutical manufacturing clusters near Toronto generate demand for reusable thermal packaging with reduced waste profiles.
Mexico
Fresh produce exporters in Sinaloa and Jalisco require insulated containers for cross-border agricultural commodity movements to United States processing facilities. Mexico's federal sanitary regulator enforces temperature integrity standards for perishable exports under harmonized trade protocols. Guadalajara logistics corridors serve as consolidation points for temperature-sensitive pharmaceutical imports destined for domestic distribution.
North America Insulated Shipping Containers Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade thermal systems, while mid-tier fabricators compete on food-service and agricultural formats. The vendor base stratifies across validation-intensive biologics lanes and commodity perishables with reduced documentation burdens. Three archetypes dominate: integrated packaging conglomerates with structural foam expertise, specialized cold-chain technology firms, and diversified materials science operators. Consolidation pressures favor multi-year performance contracts bundling equipment and monitoring services, while material substitution mandates under EPA phase-down schedules force reformulation investments.
Among United States-based packaging specialists, Sonoco Products Company and Sealed Air Corporation occupy positions reflecting structural packaging and barrier technology archetypes respectively. Cold Chain Technologies exemplifies the specialized cold-chain segment focused on reusable thermal systems. These three entities represent distinct competitive vectors within a market where pharmaceutical validation capabilities and sustainability credentials increasingly determine specification preference.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Sealed Air Corporation |
| Berry Global, Inc. |
| Pactiv Evergreen Inc. |
| WestRock Company |
| Cold Chain Technologies |
| Therapak |
| Polar Tech Industries |
| Softbox Systems Ltd |
| Others |
Value Network & Pricing Analysis
Isocyanate and polyol feedstock indices cascade through North American rigid container manufacturing, compressing margins at mid-tier fabricators while concentrating pricing power among integrated suppliers with captive foam production. This cost pass-through dynamic stratifies procurement tiers between pharmaceutical validators absorbing premium positioning and food-service buyers negotiating spot-market flexibility.
Pricing Analysis
Margin tightening in economy-tier polystyrene formats reflects crude oil linkage and expanded bead insulation competition from Asian imports. Three-tier pricing structure across pharmaceutical-grade VIP systems, standard polyurethane rigid containers, and economy polystyrene pouches separates FDA-validated performance from commodity thermal protection. Cost-down pressure on flexible pouch formats accelerates as Canadian meal-kit platforms consolidate volumes and demand return-logistics efficiency. Food distributors exhibit highest price sensitivity, while gene therapy shippers prioritize thermal assurance over unit cost.
Supply Chain Analysis
Freight cost differentials between Great Lakes manufacturing zones and coastal pharmaceutical corridors amplify landed cost spreads for vacuum-insulated panel cores. Supply concentrates in United States polyurethane foam fabrication, Canadian flexible film converting, and East Asian VIP core material production. Raw material dependencies span isocyanate feedstocks, phase-change material formulations, and reflective barrier films. Single-source vulnerability in East Asian VIP substrate production creates chokepoint exposure. Distribution runs through direct sales contracts for pharmaceutical accounts and regional distributor networks for food-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America insulated shipping containers market operates as a cost-of-compliance arena where FDA serialization mandates and temperature integrity documentation erect formidable barriers to non-validated entrants, entrenching incumbent positions among ISTA-certified suppliers.
For Market Incumbents: Anchor defensive positioning through backward integration into foam blowing agent reformulation and VIP core assembly capacity in the Great Lakes corridor. Consolidate multi-year performance contracts bundling equipment, real-time monitoring, and chain-of-custody documentation to lock out transactional competitors. Counter emerging flexible pouch entrants by emphasizing validation protocol depth and FDA inspection readiness. For New Entrants and Emerging Players: Mid-tier Canadian meal-kit operators with limited customization requirements represent the most penetrable buyer archetype for flexible container specialists lacking pharmaceutical validation infrastructure. Target Ontario and Vancouver urban delivery zones with lightweight pouch formats optimized for return-trip cube efficiency. Pursue USDA BioPreferred certification to access federal procurement preference tailwinds. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap rigid container fabricators with established FDA validation protocols and underutilized Great Lakes manufacturing capacity. Long-term viability hinges on successful navigation of EPA AIM Act phase-down schedules and material substitution investments. Monitor Health Canada-FDA harmonization progress as inflection signal for cross-border consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Reformulation | Captures margin from EPA-mandated HFC phase-down transitions in polyurethane systems. |
| VIP Core Assembly Capacity Addition | Reduces East Asian single-source exposure for gene therapy minus eighty degrees Celsius containers. |
| Multi-Year Performance Contracting | Locks pharmaceutical distributors into bundled equipment, monitoring, and documentation relationships. |
| USDA BioPreferred Certification | Unlocks federal procurement preference for plant-derived insulation formulations. |
| IoT Sensor Integration Development | Enables predictive excursion alerts that differentiate premium thermal packaging offerings. |
Research Methodology
Trade databases, EPA regulatory filings, and pharmaceutical cold-chain white papers formed the secondary backbone, supplemented by customs records and industry association publications. Primary interviews with thermal packaging engineers, pharmaceutical logistics directors, FDA regulatory consultants, and food-service procurement managers validated demand assumptions. Bottom-up and top-down triangulation reconciled container shipment volumes with end-user procurement patterns across the analysis window.
Bottom-up modeling aggregated segment-level demand across rigid, flexible, palletized, and bulk container formats, while top-down cross-checks validated aggregate market scale against macro cold-chain infrastructure indicators. Segmentation dimensions spanned product type, material chemistry, end-user industry, and distribution channel complexity. CAGR derivation incorporated historical volume trajectories, regulatory timeline impacts, and substitution elasticity between passive and active thermal systems. Phase-change material cost curves and VIP panel supply constraints informed price trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity, Health Canada-FDA protocol harmonization, and biologics pipeline expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
North America Plastic Bottles and Containers Market
Containers
Container Mouth Inner Seal Market
Containers
Cylindrical Cans Market
Containers
Lever Lid Tinplate Containers Market
Containers
Global Multi Pack Carriers Market
Containers
Feeder Containers Market
Containers
Acrylic Container Market
Containers
Disposable Lids Market
Containers
Corrugated Bin Boxes Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Trigger Sprayer Market
Containers
Metal IBC Market
Containers
Canning Jars Market
Containers
Slip Lid Can Market
Containers
Vacuum Formed Tray Market
Containers
Chest-Style Insulated Containers Market