
 Medical Metal Tubing Market | 2026-2036
Medical Metal Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Metal Tubing Market Insights
Aftermarket service revenue for precision tubing refurbishment and re-certification is tilting toward original equipment manufacturers with captive metallurgical labs. Cook Group Incorporated leverages vertical integration across catheter assembly and raw tube sourcing to capture margin pools that formerly sat with third-party converters. Sandvik AB anchors its position through captive powder metallurgy and seamless extrusion capabilities for superalloy grades. TE Connectivity Ltd. competes on geometric tolerance control for micro-diameter stent delivery systems.
Medical metal tubing comprises hollow cylindrical sections fabricated from biocompatible alloys, typically ranging from 0.005 to 0.5 inch outer diameter, produced through seamless extrusion, welded forming, or precision drawing to achieve wall thickness tolerances below 0.0005 inch for vascular access and minimally invasive instrument applications. Stainless steel tubing dominates volume across catheter and guidewire shafts where fatigue resistance and radiopacity balance cost, while titanium tubing commands premium positioning in orthopedic and neurovascular implants due to modulus matching with bone and superior magnetic resonance imaging compatibility. Drawn tubing occupies the fastest-growing form segment as manufacturers demand tighter dimensional control for next-generation drug-eluting stent platforms.
FDA enforces biocompatibility testing under ISO 10993 for all implantable metal tubing, while EMA's Medical Device Regulation mandates notified body oversight for Class III cardiovascular applications, creating compliance barriers that favor established suppliers with dedicated regulatory affairs functions. The EU F-Gas Regulation indirectly shapes material selection by restricting fluorinated process gases used in certain titanium refining pathways, pushing converters toward vacuum arc remelt alternatives. Stakeholders must monitor evolving MDR clinical evidence requirements and FDA guidance on nitinol shape memory devices to anticipate qualification timelines and capital allocation decisions.
Market Dynamics
FDA and EMA biocompatibility certification timelines are compressing supplier qualification windows, forcing converters to front-load metallurgical documentation and captive testing infrastructure ahead of commercial scale-up.
Growth Catalysts
- Cardiovascular catheterization volumes:Aging demographics in Germany and Japan are expanding addressable procedure counts for minimally invasive interventions requiring precision tubing.
- ISO 10993-5 cytotoxicity testing harmonization:Standardized biocompatibility frameworks are reducing regulatory duplication across US and EU markets, accelerating multi-region product launches.
- Nitinol shape-memory alloys:Self-expanding stent platforms are consuming increasing tonnage of superelastic tubing as neurovascular indications broaden.
Market Restraints
- Vacuum arc remelt titanium sponge costs:EU F-Gas Regulation restrictions on fluorinated process gases are elevating input costs for implantable-grade titanium tubing.
- German precision engineering cluster concentration:Seamless extrusion capacity for superalloy grades concentrates in Baden-Württemberg and Bavaria, creating geographic supply vulnerability.
- Polymer catheter shaft substitution:Pebax and thermoplastic elastomer alternatives are capturing peripheral vascular access applications where radiopacity requirements relax.
Strategic Opportunities
- India CDSCO Class C device registration pathway:Streamlined approval timelines for cardiovascular implants are opening import substitution opportunities for domestic tubing converters.
- Robotic surgical instrument sheaths:Minimally invasive robotic platforms require multi-lumen stainless configurations with sub-micron surface finishes.
- Japan METI medical device reimbursement acceleration:Faster national health insurance listing for innovative stent systems is shortening commercialization cycles for tubing suppliers.
Industry Challenges
- Electron beam welding technician scarcity:Micro-diameter titanium tubing fabrication requires specialized operators with vacuum chamber experience that outpaces vocational training output.
- ISO 13485 quality management system recertification:MDR transition in Europe is forcing supplier audits and documentation updates that consume 12-18 month compliance bandwidth.
- Legacy ERP integration with batch-level traceability:US FDA UDI requirements demand serialization that conflicts with decades-old manufacturing execution systems at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Metal Tubing Market |
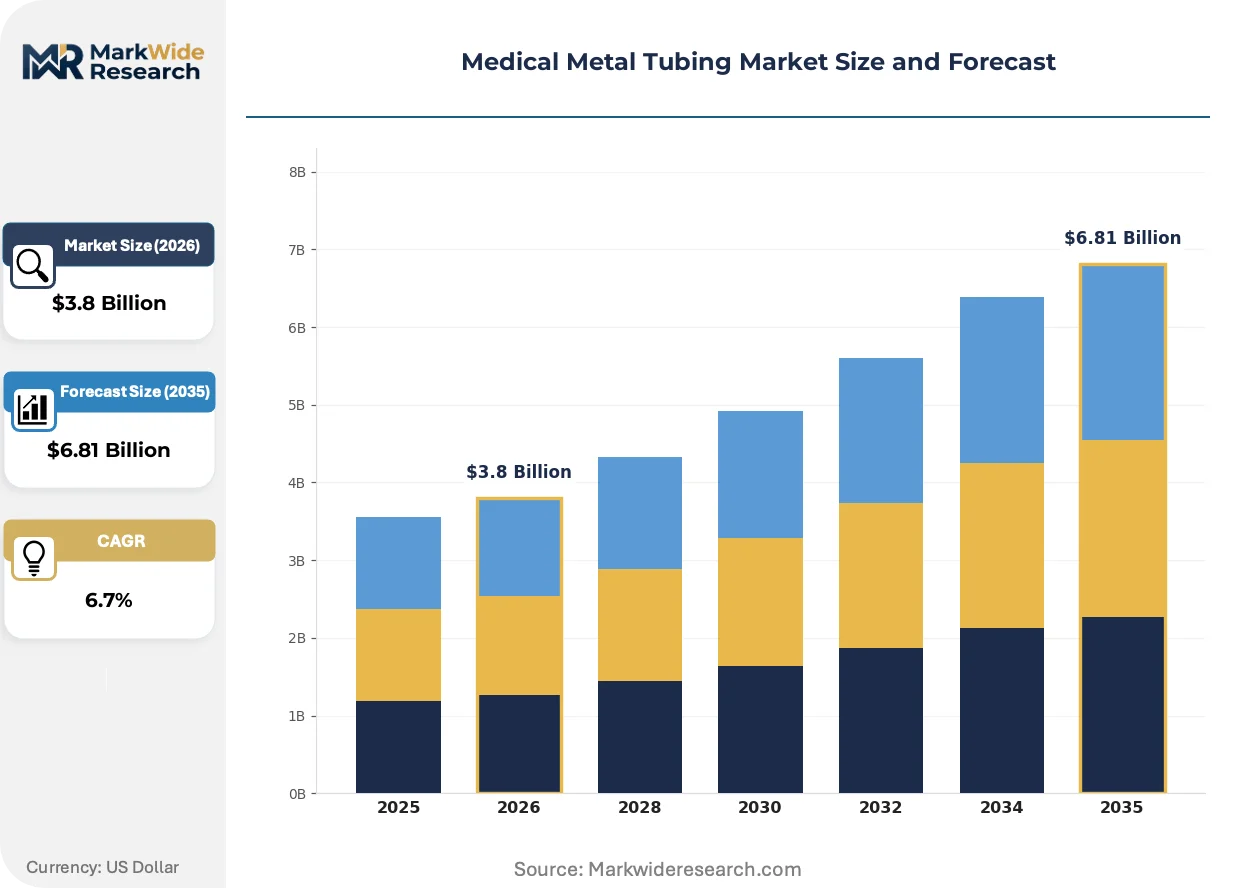
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel Tubing, Titanium Tubing, Nickel Alloys, Cobalt Alloys Application: Catheters, Stents, Surgical Instruments, Diagnostic Devices Form: Seamless Tubing, Welded Tubing, Drawn Tubing, Coiled Tubing End User: Hospitals, Medical Device Manufacturers, Research Laboratories, Clinics |
| Companies Covered | Cook Group Incorporated, TE Connectivity Ltd., Sandvik AB, K-Tube Technologies, MicroGroup, Inc., AMETEK, Inc., Accu-Tube Corporation, Vita Needle Company, New England Small Tube Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Metal Tubing Market Trends and Innovations
Laser micromachining and additive manufacturing are redrawing process boundaries for complex lumen geometries, while regulatory data requirements are shifting from material certificates to full supply chain transparency.
Continuous laser welding with real-time seam monitoring is rendering obsolete traditional TIG welding for micro-diameter hypotube applications. Stent delivery system manufacturers in Switzerland and Ireland are adopting this technology to achieve wall thickness consistency below 0.0003 inch. The process is compressing downstream grinding and polishing steps, collapsing total cost per part by eliminating secondary operations.
EMA's Medical Device Regulation clinical evidence requirements are elevating burden on tubing suppliers to provide batch-level biocompatibility documentation. Class III cardiovascular device notified bodies now demand extended material characterization data that previously sat with finished device manufacturers. German and French converters are responding by building in-house ISO 17025 testing laboratories to retain margin rather than outsourcing to third-party certifiers.
Hospital procurement consolidation through centralized implantable device committees is compressing supplier rosters to pre-qualified tier-one vendors. Cardiology departments in US integrated delivery networks are mandating single-source contracts for catheter platforms, pushing tubing converters into exclusive supply agreements with finished device OEMs. This concentration is most visible in Texas and Florida health systems where private equity-backed hospital rollups have standardized purchasing protocols.
Medical Metal Tubing Market Segmentation
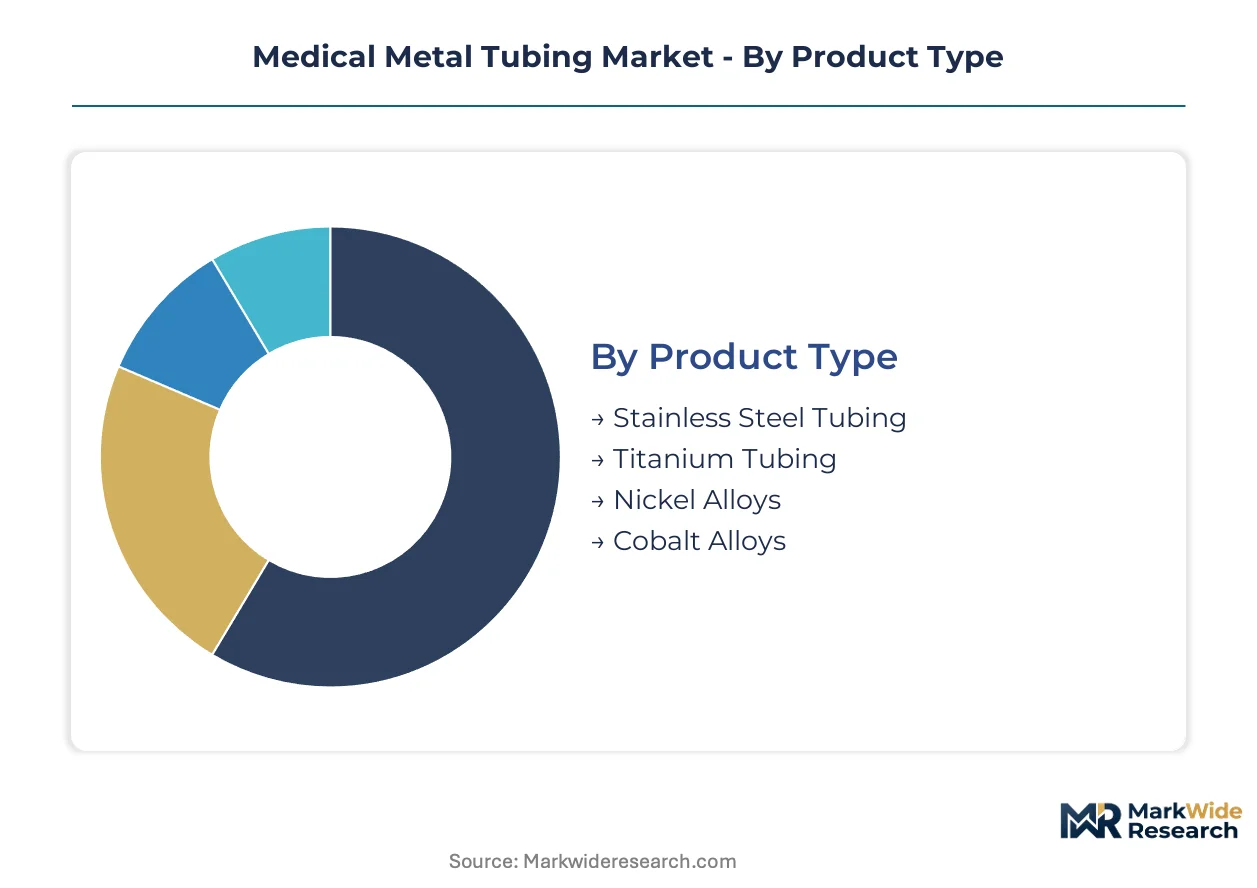
Medical metal tubing segmentation reflects divergent technical requirements across cardiovascular, orthopedic, and diagnostic platforms. Material selection and forming processes directly determine regulatory pathways, manufacturing cycle times, and margin structures for converters serving finished device OEMs.
Product Type:
Cycle times vary dramatically by alloy family, with stainless steel converting in days while titanium and superalloys require weeks of metallurgical certification.
- Stainless Steel Tubing:300-series austenitic grades dominate catheter shaft and guidewire applications where fatigue resistance and radiopacity balance unit economics. German precision engineering clusters in Baden-Württemberg process the majority of European volume for cardiovascular access devices. FDA 510(k) clearance timelines for stainless-based devices run shorter than implantable-grade alternatives, accelerating inventory turns.
- Titanium Tubing:Commercially pure and Ti-6Al-4V ELI grades command premium positioning in orthopedic and neurovascular implants due to modulus matching with bone and MRI compatibility. Vacuum arc remelt processing under EU F-Gas Regulation constraints extends lead times versus stainless alternatives.
- Nickel Alloys:Nitinol shape-memory tubing enables self-expanding stent platforms with superelastic recovery properties.
- Cobalt Alloys:Cobalt-chromium compositions deliver high radial strength for coronary stent applications requiring thin-wall mechanical performance.
Stainless steel tubing anchors the volume base while titanium tubing gains share at the steepest rate.
Application:
End-use concentration determines margin tier, with implantable devices capturing value pools that diagnostic accessories cannot access.
- Catheters:Multi-lumen configurations for electrophysiology and interventional cardiology require sub-micron tolerance control. Texas and Florida health systems drive demand through private equity-backed purchasing consolidation.
- Stents:Drug-eluting and bare-metal platforms consume the tightest-tolerance tubing for coronary and peripheral vascular indications.
- Surgical Instruments:Laparoscopic and robotic instrument sheaths specify multi-lumen stainless configurations with electropolished surfaces.
- Diagnostic Devices:Biopsy needles and fluid collection systems utilize standard-drawn tubing with less stringent dimensional control.
Catheter applications command the highest unit values while stent tubing exhibits the most rapid technology turnover.
Form:
Forming method selection trades capital intensity against geometric complexity and downstream processing requirements.
- Drawn Tubing:Cold-drawing through precision dies achieves wall thickness consistency below 0.0005 inch for next-generation drug-eluting stent platforms. Swiss and Irish stent delivery system manufacturers are compressing downstream grinding steps through tighter upstream dimensional control.
- Seamless Tubing:Extruded-and-pierced construction eliminates weld seams for high-pressure fluid delivery and rotating instrument applications.
- Welded Tubing:Continuous laser welding with real-time seam monitoring is displacing TIG processes for micro-diameter hypotube production.
- Coiled Tubing:Spooled configurations serve automated catheter assembly lines requiring continuous feedstock without joint interruptions.
Drawn tubing commands expanding share in high-precision cardiovascular applications while welded tubing retains cost advantages at larger diameters.
End User:
Customer type shapes order patterns, with OEMs demanding batch-level traceability that hospitals and clinics rarely require.
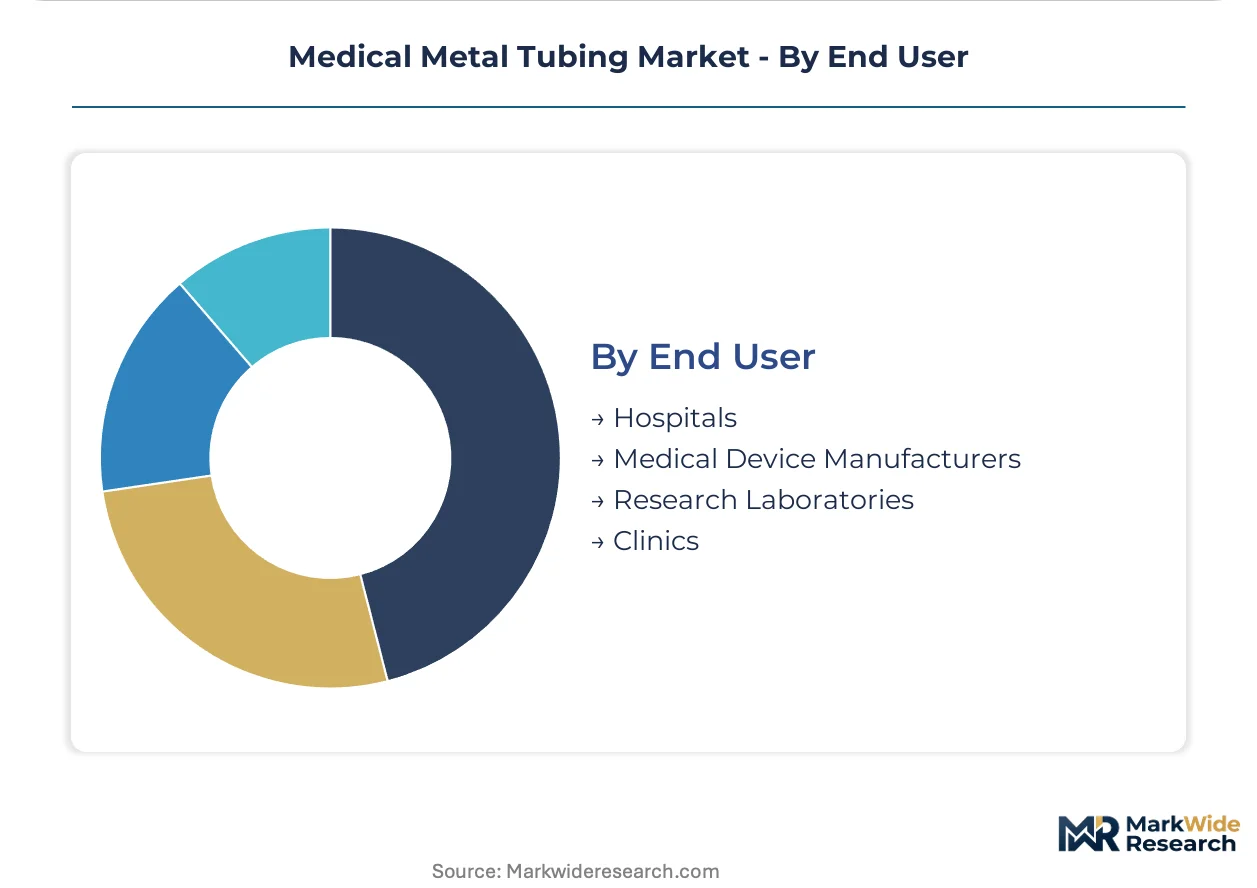
- Medical Device Manufacturers:Finished device OEMs specify captive metallurgical documentation and ISO 13485 quality systems. Cook Group and comparable vertically integrated players internalize tube sourcing to capture margin pools.
- Hospitals:Integrated delivery networks in the US are consolidating procurement through centralized implantable device committees, compressing supplier rosters.
- Research Laboratories:Academic and preclinical facilities purchase small-lot custom geometries for prototype development and device testing.
- Clinics:Outpatient settings consume standard-dimension tubing for minor surgical instruments and disposable accessories.
Medical device manufacturers dominate absolute consumption while hospital procurement consolidation is reshaping supplier relationships most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit acute price sensitivity for standard-grade stainless tubing, while German purchasers absorb titanium premiums for implantable applications without volume elasticity.
United States
Texas and Florida health systems drive catheter demand through private equity-backed purchasing consolidation. FDA 510(k) clearance timelines for stainless-based cardiovascular devices run shorter than implantable-grade alternatives, accelerating inventory turns. Minneapolis and Boston clusters host precision tubing converters serving stent delivery system OEMs.
Germany
Baden-Württemberg and Bavaria precision engineering clusters process the majority of European volume for cardiovascular access devices. EMA Medical Device Regulation mandates notified body oversight for Class III applications, creating compliance barriers that favor established suppliers with dedicated regulatory affairs functions. Stuttgart-area seamless extrusion capacity for superalloy grades concentrates supply risk geographically.
Switzerland
Swissmedic oversight of stent delivery systems elevates documentation requirements for batch-level biocompatibility. Swiss manufacturers adopt continuous laser welding with real-time seam monitoring to achieve wall thickness consistency below 0.0003 inch. Geneva and Zurich clusters serve neurovascular device innovators with sub-micron tolerance control.
Japan
METI medical device reimbursement acceleration shortens commercialization cycles for innovative stent systems. PMDA biocompatibility standards align with ISO 10993 frameworks, reducing regulatory duplication for multi-region launches. Kanto region hosts precision tubing converters supplying catheter shaft manufacturers in Tokyo and Osaka medical device corridors.
India
CDSCO Class C device registration pathway streamlines approval timelines for cardiovascular implants, opening import substitution opportunities for domestic tubing converters. Central Drugs Standard Control Organization harmonization with ISO 13485 quality management systems reduces audit burden for export-oriented manufacturers. Maharashtra and Gujarat clusters develop stainless steel drawing capacity for diagnostic device accessories.
Medical Metal Tubing Market Competitive Landscape
Capability concentration sits with metallurgical specialists commanding premium positioning for implantable-grade alloys; scale advantage sits with diversified industrial conglomerates serving high-volume catheter applications. The vendor base stratifies across three tiers: integrated device OEMs with captive tube sourcing, dedicated precision tubing converters with ISO 17025 laboratories, and commodity-drawn suppliers competing on cycle time. Dominant competitive moves include backward integration into powder metallurgy for superalloy control and exclusive supply agreements with finished device manufacturers responding to hospital procurement consolidation.
Among North American fabricators, Cook Group Incorporated exemplifies vertical integration across catheter assembly and raw tube sourcing, while TE Connectivity Ltd. occupies a position emphasizing geometric tolerance control. Sandvik AB anchors the European tier through captive metallurgical capabilities. These three entities represent divergent strategic postures: device OEM integration, precision component specialization, and materials science dominance.
| Leading Market Players |
|---|
| Cook Group Incorporated |
| TE Connectivity Ltd. |
| Sandvik AB |
| K-Tube Technologies |
| MicroGroup, Inc. |
| AMETEK, Inc. |
| Accu-Tube Corporation |
| Vita Needle Company |
| New England Small Tube Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Baden-Württemberg seamless extrusion for superalloy grades is compressing supplier margins while elevating pricing power for converters with captive metallurgical infrastructure. FDA and EMA biocompatibility certification timelines are forcing buyers to absorb premium positioning for implantable-grade tubing as qualification windows narrow.
Pricing Analysis
Aftermarket service revenue for precision tubing refurbishment and re-certification drives lifetime value capture for original equipment manufacturers with captive metallurgical labs. Three-tier pricing structure across implantable-grade, interventional-grade, and diagnostic-grade certification levels separates premium titanium and nitinol offerings from standard stainless steel catheter shafts. Cost compression in peripheral vascular access applications is intensifying because Pebax and thermoplastic elastomer alternatives relax radiopacity requirements. Hospital procurement committees in Texas and Florida health systems exhibit acute price sensitivity for standard-drawn stainless configurations, while German purchasers absorb titanium premiums for orthopedic implants without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration for micro-diameter hypotube production sits with Swiss and Irish stent delivery system specialists employing continuous laser welding with real-time seam monitoring. Raw material supply draws from vacuum arc remelt titanium sponge in Germany, 300-series austenitic stainless feedstock in India, and nitinol shape-memory alloy precursor in the United States. Single-source vulnerability concentrates in Baden-Württemberg and Bavaria superalloy extrusion capacity. Distribution runs through finished device OEMs with exclusive supply agreements responding to hospital procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement committees in Texas and Florida, fragmenting supplier rosters to pre-qualified tier-one vendors with captive regulatory affairs functions.
For Market Incumbents: Entrench positioning by deepening upstream control over powder metallurgy for superalloy grades and expanding ISO 17025 testing laboratory capacity to retain margin pools threatened by EMA batch-level biocompatibility documentation requirements. Defend against polymer catheter shaft substitution by emphasizing fatigue resistance and radiopacity in cardiovascular access applications where dimensional tolerances exclude thermoplastic alternatives. For New Entrants and Emerging Players: Robotic surgical instrument sheaths requiring multi-lumen stainless configurations with sub-micron surface finishes represent the most penetrable entry point for converters without legacy ERP constraints. CDSCO Class C device registration pathway in India offers streamlined approval timelines for cardiovascular implants with lower regulatory bandwidth than FDA or EMA pathways. Target go-to-market angle: ISO 13485 quality system implementation ahead of commercial scale-up to capture import substitution demand from domestic device manufacturers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision tubing converters with captive metallurgical laboratories serving implantable-grade applications through exclusive OEM supply agreements. Long-term viability over the five-to-ten year window favors targets with backward integration into seamless extrusion capacity and demonstrated EMA notified body relationship management. Monitor electron beam welding technician training program output as inflection indicator for supply-side capability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | Captures margin from outsourced biocompatibility testing as EMA batch-level documentation requirements tighten. |
| Continuous Laser Welding Adoption | Compresses downstream grinding steps for Swiss and Irish stent delivery system manufacturers below 0.0003 inch wall thickness. |
| CDSCO Class C Registration | Opens import substitution opportunities in Maharashtra and Gujarat clusters for cardiovascular implant tubing converters. |
| Exclusive OEM Supply Agreements | Responds to hospital procurement consolidation in Texas and Florida private equity-backed health systems. |
| Electron Beam Welding Training Programs | Addresses technician scarcity constraining micro-diameter titanium tubing fabrication capacity expansion. |
Research Methodology
Operator-level perspectives from catheter shaft procurement managers, biomedical engineers at integrated delivery networks, GPO contracts administrators, and precision tubing converter plant managers anchored the qualitative base. Primary interview insights combined with FDA 510(k) filing databases, EMA notified body guidance documents, CDSCO registration records, and ISO 13485 certification registries for secondary validation. Bottom-up demand modeling across cardiovascular, orthopedic, and diagnostic applications triangulated against top-down alloy consumption estimates from seamless extrusion and precision drawing capacity assessments.
Scenario-bracketing around regulatory timeline compression and polymer substitution risk shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include alloy family, forming process, application platform, and end-user procurement archetype. CAGRs derived from procedure volume trajectories, device approval pipelines, and material substitution elasticity parameters. Nitinol consumption for neurovascular self-expanding stents and titanium modulus-matching requirements for orthopedic implants served as industry-specific forecast anchors.
Practitioners should monitor EMA MDR clinical evidence requirement evolution and FDA guidance on nitinol shape memory devices for early signals of qualification timeline extension. Forecasts reflect assumptions regarding vacuum arc remelt capacity expansion under EU F-Gas Regulation constraints and polymer catheter shaft technical limitations in high-radiopacity applications. Quarterly review of electron beam welding technician vocational training output and hospital procurement committee vendor roster decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Nickel Powder Plating Market
Metals
Europe Metal Casting Market
Metals
Aluminum Welding Wires Market
Metals
Metal Finishing Market
Metals
Crude Steel Market
Metals
Aluminum Extrusion Market
Metals
Global Aluminum Market
Metals
Global Copper Sputtering Target Market
Metals
Rubidium Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Grain Oriented Electrical Steel Market
Metals
Seamless Stainless Steel Products Market
Metals
India Steel Market
Metals
Colloidal Metal Particles Market
Metals
Global Bronze Market