
 Steel Sheet for Home Appliances Market | 2026-2036
Steel Sheet for Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Sheet for Home Appliances Market Insights
The divergence between premium appliance-grade steel and commodity construction sheet is shifting procurement patterns across OEM supply chains. ArcelorMittal leverages its integrated European mills to sustain tight tolerance deliveries for refrigerator panel programs. POSCO anchors its position through captive cold-rolling capacity serving Korean appliance exports. Tata Steel competes on chromium-passivated galvanized lines tailored to Indian washing machine fabricators.
Steel sheet for home appliances denotes flat-rolled carbon or alloy steel processed to precise thickness ranges, typically 0.3–1.5 mm, with surface finishes engineered for corrosion resistance, paint adhesion, and deep-draw formability in stamped appliance shells. Galvanized steel dominates volume flows into refrigerator and washing machine cabinets where zinc coating extends service life in humid kitchen environments. Stainless steel commands premium positioning in microwave oven cavities and dishwasher interiors where heat cycling and chloride exposure degrade coated alternatives. Cold rolled steel sustains cost-sensitive air conditioner chassis fabrication across Southeast Asian contract manufacturers.
China's SAMR enforces GB standards for appliance energy efficiency that cascade into material thickness and coating weight specifications. India's BIS certification mandates corrosion testing protocols for imported coated steel used in domestic appliance assembly. The EU's REACH framework restricts hexavalent chromium in conversion coatings, pushing coating type migration toward organic and phosphate alternatives. Stakeholders must monitor how dual regulatory pressure on chemical content and carbon intensity reshapes supplier qualification criteria and regional sourcing decisions.
Market Dynamics
China's tightening GB standards for appliance energy efficiency are cascading into material thickness and coating weight specifications, forcing mills to recalibrate cold-rolling tolerances and OEMs to requalify supplier bases across multiple continents.
Growth Catalysts
- Energy Efficiency Mandates:China's SAMR enforces GB standards that mandate thinner, higher-strength steel shells for refrigerators, directly expanding procurement of advanced high-strength grades by appliance manufacturers in Shandong and Guangdong provinces.
- India's Western Industrial Corridor:Concentrated washing machine and refrigerator assembly near Gujarat and Maharashtra manufacturing clusters is generating localized demand spikes for chromium-passivated galvanized sheet.
- Coating Technology Advancement:Organic and phosphate conversion coatings are displacing hexavalent chromium treatments under EU REACH restrictions, creating upgrade cycles across European appliance supply chains.
Market Restraints
- Zinc Price Volatility:Fluctuations in zinc ingot costs directly compress margins on galvanized steel production for refrigerator cabinets, forcing mills to implement surcharge mechanisms that strain OEM relationships.
- Supply Concentration Risk:Cold-rolling capacity for appliance-grade tolerances concentrates in Northeast Asian integrated mills, creating vulnerability to regional logistics disruptions or trade policy shifts.
- Stainless Substitution Ceiling:Premium nickel-bearing grades for dishwasher interiors face cost barriers that limit penetration beyond high-end product lines, constraining volume expansion.
Strategic Opportunities
- Southeast Asian Contract Manufacturing:Vietnam and Thailand-based air conditioner chassis fabricators remain undersupplied with cost-optimized cold rolled steel, presenting volume expansion paths for regional distributors.
- India PLI Scheme Tailwinds:Production-linked incentive schemes for white goods assembly are accelerating localized steel procurement requirements for component suppliers establishing operations near Chennai and Pune.
- Digital Procurement Platforms:B2B marketplaces for specialty coated steel are disintermediating traditional distributor networks, enabling direct mill-to-fabricator transactions with real-time specification matching.
Industry Challenges
- Surface Quality Certification Delays:BIS corrosion testing protocols for imported coated steel extend qualification timelines by 4-6 months, freezing supplier switches during peak procurement windows.
- Legacy Equipment Retrofit Costs:Indian mid-scale fabricators face capital intensity barriers in upgrading stamping presses to handle thinner, higher-strength grades required by new efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Sheet for Home Appliances Market |
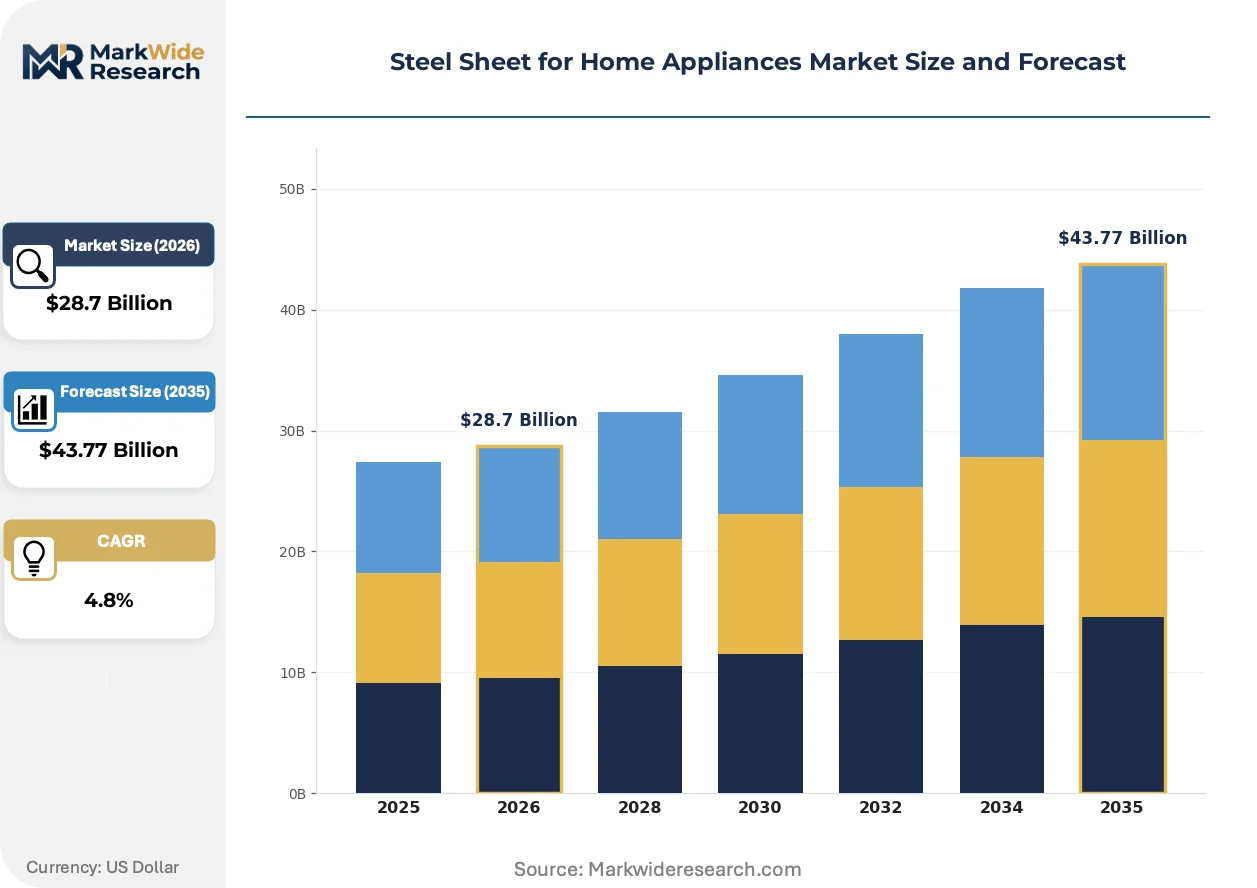
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Rolled Steel, Hot Rolled Steel, Galvanized Steel, Stainless Steel, Electrolytic Tinplate Coating Type: Zinc Coating, Chromate Coating, Organic Coating, Phosphate Coating, Polyvinylidene Fluoride Application: Refrigerators, Washing Machines, Microwave Ovens, Air Conditioners, Dishwashers End User: Original Equipment Manufacturers, Contract Manufacturers, Aftermarket Suppliers, Component Fabricators |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, Tata Steel, ThyssenKrupp Steel, JFE Steel Corporation, United States Steel Corporation, Baosteel Group Corporation, BlueScope Steel Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Sheet for Home Appliances Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape surface treatment protocols and forming characteristics across appliance-grade steel supply chains.
Advanced high-strength steel grades with optimized manganese and microalloy content are integrating into refrigerator panel programs to enable thinner gauges without sacrificing dent resistance. Korean and Chinese OEMs are adopting these grades fastest, compressing traditional mild steel volumes in premium appliance segments and forcing mills to reconfigure annealing line parameters.
EU REACH framework restrictions on hexavalent chromium conversion coatings are mandating wholesale chemistry transitions across European coating lines. Appliance manufacturers in Germany and Poland are accelerating qualification of trivalent chromium and silane-based alternatives, with dishwasher interior applications facing the most stringent corrosion performance recertification requirements.
Consolidation among major appliance OEMs is compressing supplier qualification cycles and favoring steel mills with integrated technical service capabilities. Direct mill-fabricator technical partnerships are displacing traditional trading house intermediation in high-volume refrigerator programs across China and India, with specification lock-ins extending across multi-year procurement agreements.
Steel Sheet for Home Appliances Market Segmentation
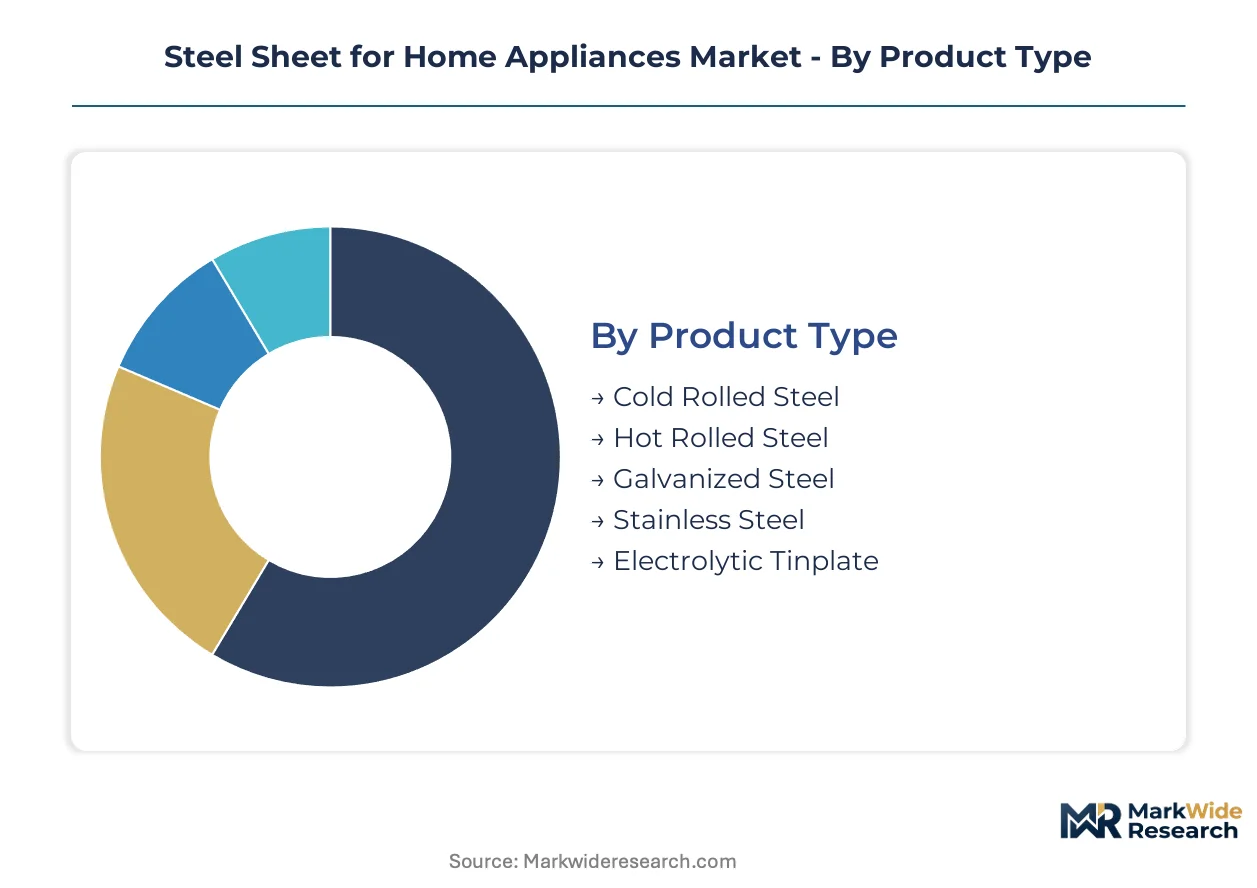
Steel sheet procurement for home appliances fragments across material grades, surface treatments, and customer types with divergent certification burdens. Each segment carries distinct regulatory requirements from GB standards in China to BIS protocols in India, reshaping supplier qualification timelines and regional sourcing patterns.
Product Type:
Certification intensity varies sharply by material chemistry and forming characteristics, with corrosion-resistant grades facing extended BIS corrosion testing and energy-efficiency-linked specifications triggering SAMR recalibration mandates.
- Galvanized Steel:Zinc-coated carbon steel processed to 0.4–1.2 mm thickness ranges dominates refrigerator cabinet fabrication across humid kitchen environments. Demand concentrates in Shandong and Guangdong provinces where Chinese OEMs source volumes for export-oriented appliance programs under tightening GB energy-efficiency standards.
- Cold Rolled Steel:Annealed low-carbon sheet with tight thickness tolerances serves cost-sensitive air conditioner chassis across Southeast Asian contract manufacturers. Procurement clusters near Vietnam and Thailand assembly plants where distributors compete on specification-matching speed rather than metallurgical differentiation.
- Stainless Steel:Chromium-nickel austenitic grades withstand heat cycling and chloride exposure in dishwasher interiors.
- Hot Rolled Steel:Thicker gauge material with scaled surfaces finds limited appliance use in structural brackets and base frames.
- Electrolytic Tinplate:Tin-coated sheet serves niche food-contact applications in small appliance components requiring solderability.
Leading the category by volume: Galvanized Steel. Growing fastest: Cold Rolled Steel.
Coating Type:
Surface treatment selection directly determines REACH compliance pathways in Europe and corrosion certification outcomes under Indian BIS mandates.
- Zinc Coating:Hot-dip and electrolytic zinc layers provide sacrificial corrosion protection for refrigerator and washing machine cabinets. Price volatility in zinc ingot markets forces mills to implement surcharge mechanisms that strain OEM relationships across Korean and Chinese supply chains.
- Organic Coating:Polymer-based pre-painted finishes eliminate post-forming painting steps for appliance OEMs. Adoption accelerates in European programs where trivalent chromium alternatives face performance gaps against REACH-restricted hexavalent treatments.
- Chromate Coating:Conversion coatings with hexavalent or trivalent chromium chemistry face regulatory phase-out pressures.
- Phosphate Coating:Crystalline zinc or iron phosphate layers improve paint adhesion for painted appliance panels.
- Polyvinylidene Fluoride:Fluoropolymer coatings command premium positioning in high-durability exterior applications.
Volume concentration: Zinc Coating. Steepest expansion trajectory: Organic Coating.
Application:
End-use appliance categories impose distinct forming severity, surface finish, and thermal cycling requirements that filter material grade selection.
- Refrigerators:Deep-drawn door panels and cabinet shells demand optimized manganese grades for dent resistance at thinner gauges. Procurement volumes concentrate near Gujarat and Maharashtra clusters where Indian PLI scheme incentives accelerate localized steel sourcing.
- Air Conditioners:Chassis and heat exchanger support structures utilize cost-optimized cold rolled grades across Thailand and Vietnam contract manufacturing bases. Fabricators prioritize thickness consistency over surface aesthetics in this price-sensitive segment.
- Washing Machines:Drum and cabinet applications require chromium-passivated galvanized sheet for wet-environment durability.
- Microwave Ovens:Cavity interiors specify stainless or specially coated steel for food-contact heat resistance.
- Dishwashers:Interior panels face the most stringent corrosion recertification under EU REACH coating transitions.
Dominant procurement volume: Refrigerators. Fastest material specification evolution: Dishwashers.
End User:
Customer type determines order scale, technical service intensity, and supplier relationship structure across appliance supply chains.
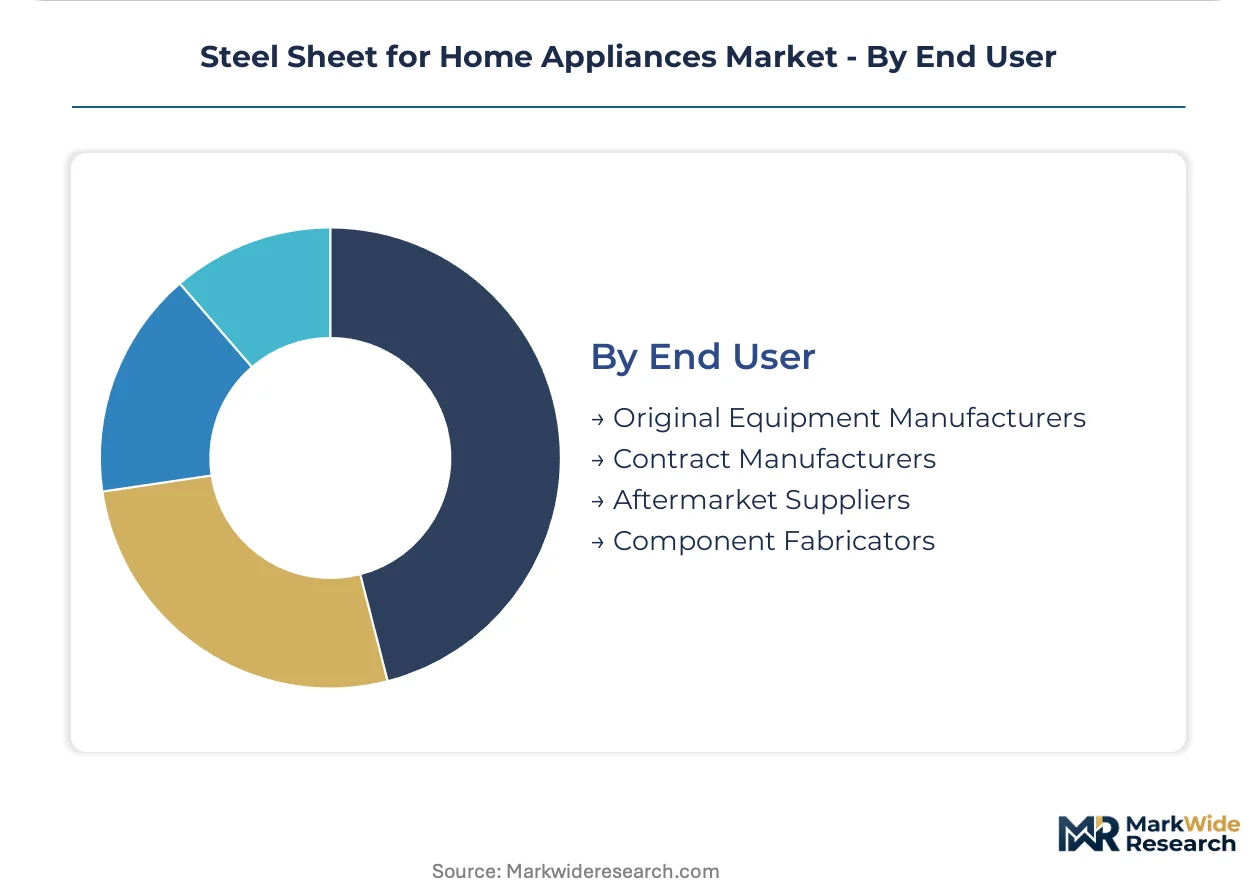
- Original Equipment Manufacturers:Integrated appliance brands like Haier, Whirlpool, and LG Electronics drive specification-setting for multi-year procurement agreements. Direct mill partnerships displace distributor intermediation as technical service capabilities become qualification criteria.
- Contract Manufacturers:Flextronics and Jabil-equivalent electronics manufacturing services source standardized grades for air conditioner and small appliance assembly. Digital procurement platforms enable real-time specification matching that compresses traditional distributor margins.
- Component Fabricators:Tier-2 stampers and formers purchase coil stock for downstream OEM supply.
- Aftermarket Suppliers:Replacement panel and repair part distributors serve fragmented service networks.
Procurement volume leadership: Original Equipment Manufacturers. Fastest platform adoption: Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Guangdong provinces concentrate China's refrigerator panel procurement volumes, with SAMR's GB energy-efficiency standards cascading into material thickness specifications that reshape mill calibration priorities across the Pearl River Delta.
China
Refrigerator OEMs in Shandong and Guangdong provinces drive expanding procurement of advanced high-strength grades. SAMR enforces GB standards that mandate thinner steel shells, forcing cold-rolling tolerance recalibration. Procurement clusters near Qingdao and Foshan manufacturing bases anchor multi-year supply agreements with integrated mills.
India
Washing machine and refrigerator assembly concentrates near Gujarat and Maharashtra clusters, generating localized demand spikes for chromium-passivated galvanized sheet. BIS certification mandates corrosion testing protocols that extend qualification timelines. PLI scheme incentives accelerate localized steel sourcing requirements near Chennai and Pune.
South Korea
POSCO's captive cold-rolling capacity serves export-oriented appliance programs for global OEMs. MFDS-aligned material specifications govern food-contact applications. Busan-Ulsan industrial corridor anchors specialized coating line investments for premium dishwasher interior grades.
Germany
EU REACH restrictions on hexavalent chromium conversion coatings mandate chemistry transitions across coating lines. ECHA compliance pathways favor trivalent chromium and silane-based alternatives. Ruhr industrial region and Bavarian manufacturing zones concentrate qualification activity for corrosion-resistant appliance grades.
United States
EPA-aligned environmental standards shape coating chemistry selection for domestic appliance assembly. United States Steel Corporation and regional distributors serve refrigerator cabinet fabricators. Midwest industrial corridor near Ohio and Michigan anchors stamping press capacity for deep-drawn panel production.
Steel Sheet for Home Appliances Market Competitive Landscape
Capital-heavy integrated mills compete with regional distributors on specification-matching speed and technical service intensity. Market structure concentrates around Northeast Asian producers with captive cold-rolling capacity, while European and Indian players compete on coating customization and regulatory compliance pathways. Three archetypes dominate: integrated steelmakers with in-house technical service capabilities, regional distributors with logistics optimization platforms, and specialty coating specialists with REACH-compliant chemistry portfolios. Competitive moves center on direct mill-fabricator partnerships displacing traditional intermediation, and coating line retrofits to meet hexavalent chromium phase-out deadlines.
Within the integrated mill tier, ArcelorMittal and POSCO exemplify capital-intensive positioning through European and Korean production bases respectively. Tata Steel occupies a distinct archetype as an India-domiciled competitor with chromium-passivated galvanized lines tailored to western industrial corridor demand. These three anchors demonstrate how geographic proximity to appliance manufacturing clusters shapes competitive differentiation more than pure scale metrics.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| Tata Steel |
| ThyssenKrupp Steel |
| JFE Steel Corporation |
| United States Steel Corporation |
| Baosteel Group Corporation |
| BlueScope Steel Limited |
| Others |
Pricing and Supply Chain Analysis
Zinc ingot cost volatility cascades through galvanized steel production tiers, with Northeast Asian integrated mills passing surcharges to refrigerator OEMs while Southeast Asian distributors absorb margin compression to retain air conditioner chassis contracts.
Pricing Analysis
Yield-optimized pricing anchors contract negotiations, with mills charging premiums for advanced high-strength grades that reduce material thickness without sacrificing dent resistance. Three-tier pricing structure separates premium appliance-grade tolerances from standard commercial quality and economy construction sheet. Pricing pressure stems from zinc ingot volatility forcing surcharge mechanisms that strain multi-year procurement relationships. Contract manufacturers in Vietnam and Thailand exhibit highest price sensitivity, while integrated OEMs in Shandong and Guangdong prioritize specification consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume refrigerator panel demand from Haier and LG Electronics, while regional distributors serve fragmented component fabricators with specification-matching services. Cold-rolling capacity concentrates in China, South Korea, and Japan, with mills drawing from Australian iron ore and Mongolian coking coal inputs. Single-source vulnerability threatens European appliance programs dependent on Korean coating line output for REACH-compliant alternatives. Distribution runs through mill-direct technical partnerships displacing traditional trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic and phosphate conversion coatings are displacing hexavalent chromium treatments, forcing coating line retrofits and supplier requalification across European and Asian supply chains.
For Market Incumbents: Hedge against REACH compliance divergence by qualifying trivalent chromium and silane-based alternatives across European coating lines before phase-out deadlines. Backward integration into captive zinc coating capacity insulates margin structures from ingot volatility. ArcelorMittal and POSCO demonstrate how technical service capabilities lock in multi-year OEM agreements. For New Entrants and Emerging Players: The mid-tier price gap between premium Korean cold-rolled output and Indian domestic galvanized sheet creates entry space for Southeast Asian distributors with logistics optimization platforms. Target Vietnam and Thailand air conditioner chassis fabricators undersupplied by Northeast Asian mills. Deploy digital procurement marketplaces offering real-time specification matching to compress traditional distributor margins. For Investors and Strategic Acquirers: BIS certification timeline extensions are the leading indicator that Indian import-dependent fabricators face supplier switching constraints, creating acquisition opportunities for coating specialists with pre-qualified corrosion protocols. Five-to-ten year viability favors mills with integrated technical service capabilities over pure commodity traders. Watch for PLI scheme acceleration triggering localized steel procurement mandates near Chennai and Pune clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retrofit | REACH-compliant chemistry transitions secure European appliance program eligibility under ECHA mandates. |
| Backward Integration | Captive cold-rolling capacity anchors POSCO's Korean appliance export positioning against Chinese competition. |
| Digital Procurement Platform | B2B marketplaces disintermediate traditional distributors serving Vietnam contract manufacturers. |
| Technical Service Partnership | Direct mill-fabricator collaboration locks in multi-year refrigerator panel agreements with Shandong OEMs. |
| Regional Distribution Hub | Localized inventory near Gujarat clusters accelerates chromium-passivated galvanized sheet delivery to washing machine fabricators. |
Research Methodology
Independent corroboration across procurement directors at Indian washing machine OEMs, coating line engineers at European mills, and regulatory affairs specialists at SAMR-affiliated standards bodies underwrites the qualitative findings. Primary interviews with plant managers at Shandong refrigerator factories, technical directors at Korean cold-rolling operations, and channel partners in Vietnam's air conditioner supply chain combined with secondary validation from customs trade data, BIS certification registries, and SEC filings from listed steel producers. Bottom-up volume estimates triangulated against top-down industry capacity assessments.
Rate-of-change decomposition across material grade, coating chemistry, and end-use appliance category shaped the analytical framework. Segmentation dimensions modeled include product type, surface treatment protocol, application severity, and customer procurement scale. CAGRs derived from historical shipment trajectories adjusted for regulatory mandate acceleration and manufacturing cluster expansion. Industry-specific inputs incorporated GB standard revision timelines and PLI scheme disbursement velocity.
Inputs from BIS corrosion testing protocols and ECHA REACH amendment drafts were available through the study window; gaps in real-time zinc inventory positioning at Southeast Asian ports introduce uncertainty bands around quarterly procurement forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Brazil Aluminum Market
Metals
Ruthenium Market
Metals
Aluminum Sheet Market
Metals
Gold Smelting Market
Metals
Nickel Foam Market
Metals
Heat-Treated Steel Plates Market
Metals
Stainless Steel Market
Metals
Aluminum Wire Market
Metals
Global Copper Market
Metals
Seamless Stainless Steel Products Market
Metals
China Copper Market
Metals
Vietnam Aluminum Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Silver Powder and Flakes Market
Metals
Copper Smelting Market
Metals
Industrial Metal Strips Market