
 Household Cleaning Robotics Market | 2026-2036
Household Cleaning Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Household Cleaning Robotics Market Insights
AI-driven simultaneous localization and mapping is reshaping how household cleaning robots perceive residential environments and execute coverage patterns. iRobot Corporation anchors its competitive position through proprietary navigation software and deep North American brand recognition. Ecovacs Robotics leverages integrated manufacturing in China to control component costs across its Deebot product lines. Roborock Technology specializes in premium lidar-equipped units that compete on suction power and mopping precision.
Household cleaning robotics encompasses autonomous electromechanical devices designed for floor, surface, and window maintenance in domestic settings, typically incorporating brushroll mechanisms with 2,000–6,000 Pascal suction ratings, rechargeable lithium-ion battery packs, and docking stations for automated debris emptying or water replenishment. The primary commercial purpose is labor substitution for routine hygiene tasks in residential and light commercial environments. Robotic vacuums dominate unit volume as the most mature product category, while robotic mops represent the fastest-expanding margin pool due to higher average selling prices and replacement consumable revenue. Lidar navigation leads the technology hierarchy for mapping accuracy, though camera-based navigation gains traction in mid-tier price bands where cost constraints limit sensor expenditure.
The Federal Communications Commission regulates radio frequency emissions from wireless-connected units sold in the United States, while the EU's CE marking and Ecodesign requirements govern energy consumption and electromagnetic compatibility across European markets. China's GB standards and MIIT certifications shape product specifications for both domestic consumption and export manufacturing from Shenzhen-based facilities. Stakeholders must monitor evolving battery transport regulations and right-to-repair legislation that will determine service revenue models and product lifecycle economics.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is compressing design cycles for household cleaning robotics manufacturers, forcing simultaneous redesigns for repairability, energy efficiency, and battery serviceability across entire product portfolios.
Growth Catalysts
- Lidar Navigation Cost Curves:Solid-state lidar module prices are falling below camera-array alternatives, enabling premium mapping accuracy in mid-tier robotic vacuum units.
- China's Manufacturing Cluster Density:Component suppliers and final assemblers co-locate in Shenzhen and Dongguan, reducing logistics friction and procurement lead times for battery packs and brushroll motors.
- Right-to-Repair Mandates:The EU's repairability index requirements are creating aftermarket service revenue pools and extending product lifecycles through certified spare part channels.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Cathode material processing and cell manufacturing concentrate in China's Jiangsu and Fujian provinces, exposing brands to single-source disruption risk.
- RF Emission Certification Friction:The FCC's Part 15 rules for wireless-connected units impose 12-16 week approval timelines that delay North American product launches.
- Manual Cleaning Substitution Threshold:Robotic mops face performance gaps on textured tile and grout lines that human-operated steam cleaners address more effectively.
Strategic Opportunities
- India's Urban Middle-Class Expansion:Apartment dwellers in Mumbai and Bangalore represent an underpenetrated installed base with rising disposable income for labor-saving appliances.
- Window-Cleaning Robotics:Suction-based vertical surface units for high-rise residential towers in Dubai and Singapore create a nascent product category with limited incumbent competition.
- AI-Enabled Predictive Maintenance:Edge-computing diagnostics that anticipate brushroll wear and filter saturation before performance degradation enable subscription consumable replenishment models.
Industry Challenges
- SLAM Algorithm Talent Scarcity:Simultaneous localization and mapping expertise concentrates in robotics institutes and autonomous vehicle programs, driving compensation inflation for firmware engineering teams.
- Cross-Border Battery Transport Compliance:UN 38.3 lithium-ion testing requirements and IATA dangerous goods regulations complicate direct-to-consumer e-commerce fulfillment from Asian manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Cleaning Robotics Market |
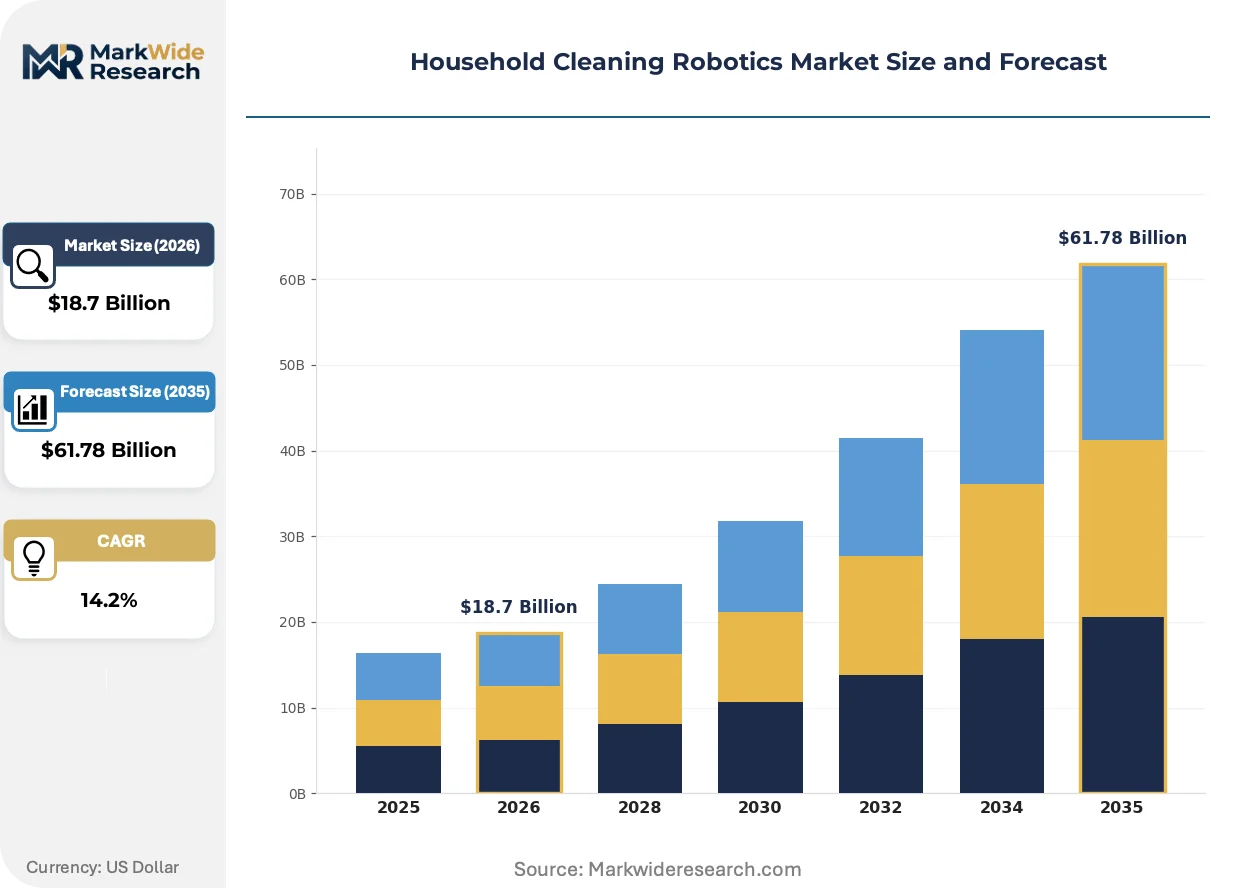
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Vacuums, Robotic Window Cleaners, Robotic Mops, Automated Surface Cleaners Technology: Lidar Navigation, Camera-Based Navigation, Ultrasonic Sensor Technology, AI-Driven Algorithms End User: Residential Consumers, Commercial Facilities, Hospitality Sector, Elderly Care Institutions Distribution Channel: Online Retail, Brick-and-Mortar Stores, Specialty Outlets, Direct Sales |
| Companies Covered | iRobot Corporation, Ecovacs Robotics, Samsung Electronics, Roborock Technology, Neato Robotics, LG Electronics, SharkNinja Operating LLC, Dyson Ltd, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Cleaning Robotics Market Trends and Innovations
Navigation hardware commoditization and software-defined feature differentiation are redefining competitive moats in household cleaning robotics, compressing traditional hardware-centric business models.
Lidar sensor miniaturization is collapsing the cost barrier between premium and standard navigation tiers. Solid-state arrays from automotive surplus supply chains now enable sub-$400 robotic vacuums to execute room-by-room mapping previously reserved for flagship units. Suburban North American buyers are upgrading replacement cycles as perceived performance parity erases price-premium justification for historical market leaders.
REACH substance restrictions and the EU Battery Regulation are mandating removable cell designs and recycled content quotas. Manufacturers must reengineer sealed battery packs into tool-free replaceable modules while documenting supply chain due diligence for cobalt and lithium provenance. German and French retailers are demanding CE conformity documentation before shelf placement, filtering out brands lacking compliance infrastructure.
Direct-to-consumer subscription models are displacing traditional retail attachment for consumable replenishment. Robotic mop brands now offer automated detergent pod and microfiber pad delivery tied to usage telemetry rather than calendar schedules. This shift concentrates customer lifetime value data with manufacturers and reduces price transparency for replacement parts compared to third-party retail channels.
Household Cleaning Robotics Market Segmentation
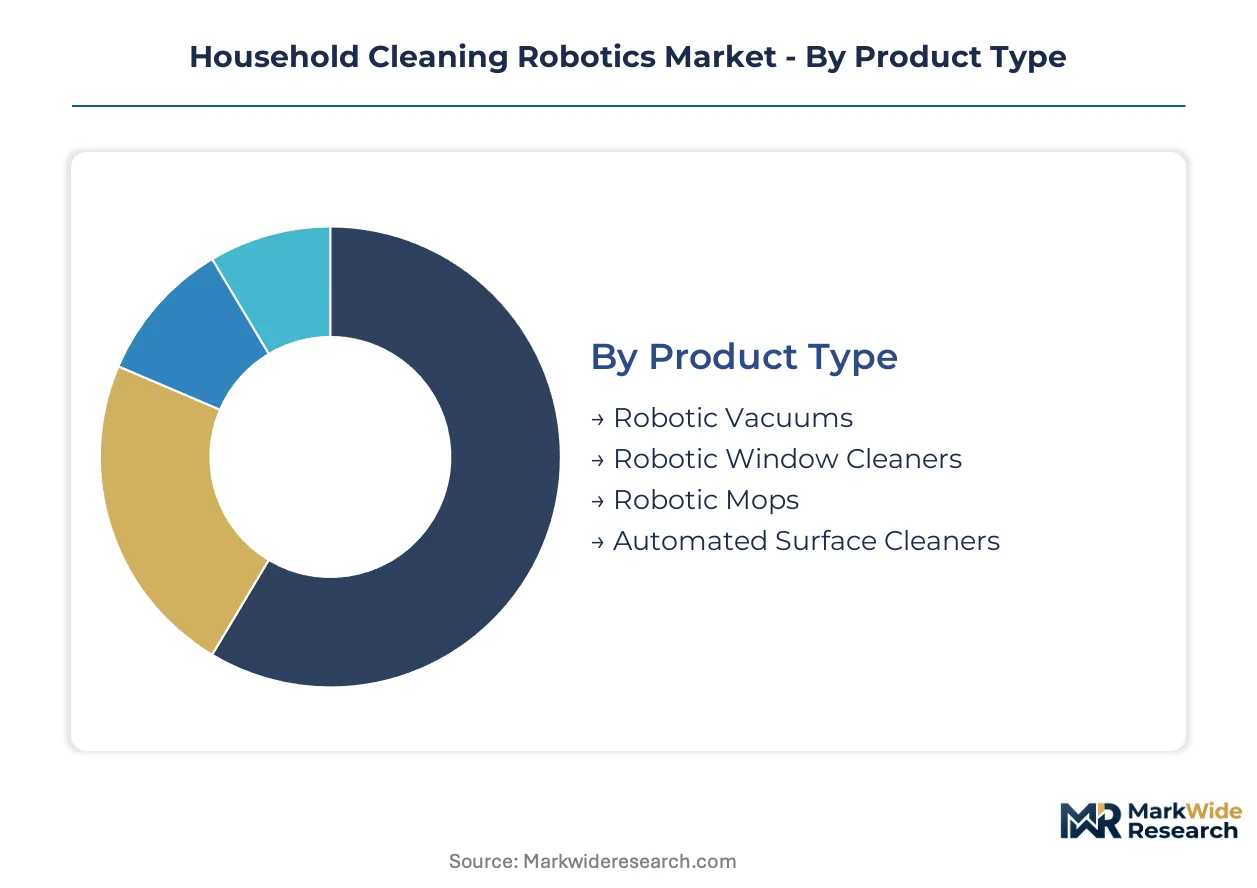
Segmentation in household cleaning robotics reveals how technology tiers, user environments, and procurement channels create distinct margin pools and lifecycle economics. Manufacturers configure component specifications and service models differently across these boundaries.
Product Type:
Application environment determines motor specifications, battery capacity, and debris handling architecture across robotic cleaning platforms.
- Robotic Vacuums:Brushroll mechanisms with 2,000–6,000 Pascal suction ratings and lithium-ion battery packs dominate residential floor maintenance. Suburban North American households are upgrading replacement cycles as lidar navigation commoditizes into mid-tier price bands.
- Robotic Mops:Oscillating pad systems with automated water dispensing and detergent integration command premium positioning. China's manufacturing clusters around Shenzhen are scaling microfiber consumable production to match expanding installed bases.
- Robotic Window Cleaners:Suction-based vertical traversal units with safety tether systems address high-rise residential maintenance. Dubai and Singapore tower complexes are piloting deployment for exterior glass surfaces.
- Automated Surface Cleaners:UV-C and electrostatic disinfection modules target kitchen and bathroom hard surfaces. Elderly care institutions in Japan are evaluating adoption for hygiene-sensitive environments.
Robotic vacuums command the established base. The steepest expansion runs through robotic mops.
Technology:
Navigation hardware cost curves are collapsing traditional tier boundaries and forcing software-defined differentiation.
- Lidar Navigation:Solid-state laser arrays generate millimeter-accurate room mapping and obstacle avoidance. Automotive surplus supply chains are driving module prices below camera-array alternatives.
- Camera-Based Navigation:Visual simultaneous localization and mapping leverages existing smartphone image sensor supply chains. Mid-tier robotic vacuums in European markets are adopting this architecture to meet CE marking cost constraints.
- Ultrasonic Sensor Technology:Time-of-flight proximity detection supplements primary navigation for cliff detection and furniture approach. Budget product lines in India's urban markets rely on this simpler sensory stack.
- AI-Driven Algorithms:Edge-computing pattern recognition optimizes coverage paths and identifies floor surface transitions. Firmware engineering talent scarcity in robotics institutes is inflating development costs for this layer.
Lidar navigation retains the premium positioning. AI-driven algorithms are climbing the fastest as the primary competitive differentiator.
End User:
Customer type shapes service intensity, replacement cycle velocity, and regulatory compliance burden for manufacturers.
- Residential Consumers:Individual household purchasers prioritize labor substitution and scheduling convenience. Apartment dwellers in Mumbai and Bangalore represent underpenetrated demand with rising appliance expenditure.
- Commercial Facilities:Office and retail environments demand fleet management software and centralized maintenance contracts. The EU's Ecodesign repairability requirements are extending product lifecycles in this segment.
- Hospitality Sector:Hotels and resorts require silent operation modes and rapid turnaround cleaning protocols. Battery serviceability mandates are forcing sealed-pack redesigns into tool-free replaceable modules.
- Elderly Care Institutions:Assisted living facilities value fall-risk reduction and predictable maintenance scheduling. Japan's METI guidelines on service robot safety are shaping product specifications for this user class.
Residential consumers anchor unit volume. Commercial facilities are gaining share fastest through fleet standardization.
Distribution Channel:
Channel selection determines pricing transparency, customer data ownership, and aftermarket revenue capture.
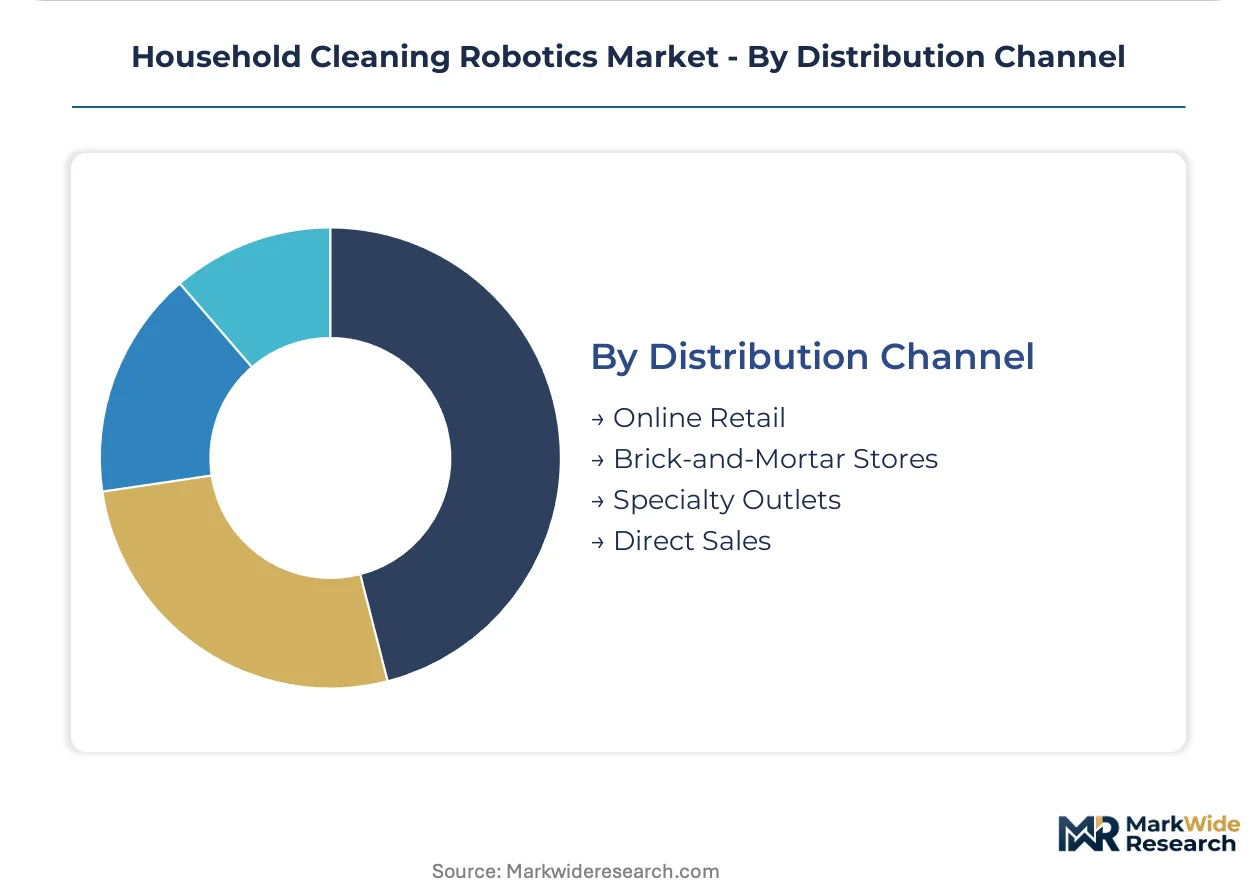
- Online Retail:E-commerce platforms enable direct-to-consumer subscription models for consumable replenishment. UN 38.3 lithium-ion testing requirements complicate cross-border fulfillment from Asian manufacturing hubs.
- Brick-and-Mortar Stores:Physical retail maintains importance for first-time purchasers seeking tactile product comparison. German and French retailers are demanding CE conformity documentation before shelf placement.
- Specialty Outlets:Appliance-focused chains provide installation support and extended warranty services. FCC Part 15 certification delays are pushing brands toward established import partners with compliance infrastructure.
- Direct Sales:Manufacturer-owned channels concentrate customer lifetime value data and reduce price transparency. Robotic mop brands are leveraging this route for automated detergent pod delivery tied to usage telemetry.
Online retail leads transaction volume. Direct sales are expanding most quickly through subscription attach models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters in Shenzhen and Dongguan export finished household cleaning robotics to suburban North American buyers, while European regulatory tightening reshapes import specifications across multiple compliance regimes.
United States
Suburban households in Texas and Florida are upgrading replacement cycles for autonomous floor-care units. The FCC enforces Part 15 radio frequency emission rules that impose 12-16 week certification timelines for wireless-connected models. Distribution concentrates through e-commerce fulfillment centers in California and Illinois despite cross-border battery transport complications.
Germany
Retailers in Berlin and Munich demand CE conformity documentation and repairability index scores before shelf placement. The EU Ecodesign for Sustainable Products Regulation mandates tool-free battery replacement modules and energy efficiency thresholds. Engineering talent for SLAM firmware concentrates in Baden-Württemberg automotive technology corridors.
China
Shenzhen and Dongguan manufacturing clusters co-locate component suppliers with final assemblers to compress procurement lead times for brushroll motors and lithium-ion packs. MIIT certifications and GB standards govern domestic product specifications and export manufacturing protocols. Solid-state lidar module production is scaling through automotive surplus supply chain integration.
Japan
Elderly care institutions in Osaka and Nagoya evaluate UV-C surface disinfection modules for hygiene-sensitive environments. METI guidelines on service robot safety shape product specifications for assisted living facility procurement. Kanto region engineering centers focus on edge-computing diagnostics for predictive maintenance algorithms.
India
Apartment dwellers in Mumbai and Bangalore represent underpenetrated demand with rising disposable income for labor-saving appliances. BIS certification requirements filter import quality tiers for mid-market navigation technologies. Tamil Nadu and Karnataka electronics manufacturing zones are attracting component assembly investments for regional supply chain localization.
Household Cleaning Robotics Market Competitive Landscape
Channel-controlling players compete with product-specialist players for shelf placement and direct-to-consumer data ownership. The vendor base separates into three tiers: premium lidar-equipped specialists, integrated manufacturing scale operators, and consumer electronics conglomerates with appliance portfolio breadth. Dominant competitive moves include geographic certification pre-positioning to compress launch timelines and subscription model deployment for consumable replenishment revenue capture.
Among North American-origin players, iRobot Corporation anchors the premium navigation software tier, while SharkNinja Operating LLC occupies the mid-market appliance channel position. Chinese fabricators Ecovacs Robotics and Roborock Technology exemplify integrated manufacturing scale, with Xiaomi Corporation representing the consumer electronics conglomerate archetype leveraging ecosystem cross-sell. Samsung Electronics and LG Electronics sit within the diversified technology holding structure, using appliance division R&D budgets to fund cleaning robotics product line expansion.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics |
| Samsung Electronics |
| Roborock Technology |
| Neato Robotics |
| LG Electronics |
| SharkNinja Operating LLC |
| Dyson Ltd |
| Xiaomi Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen lidar module fabrication is compressing supplier margins and enabling aggressive pricing postures across mid-tier robotic vacuum tiers, while simultaneously pressuring brands to absorb cost savings into feature upgrades rather than price reductions.
Pricing Analysis
The technology-generation pricing gap separates solid-state lidar-equipped units from camera-array predecessors and experimental next-gen multimodal navigation systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor suite sophistication and battery serviceability design. Pricing pressure stems from automotive surplus lidar supply flooding consumer robotics channels. Residential apartment dwellers in emerging markets exhibit highest price sensitivity, while hospitality sector fleet buyers prioritize total cost of ownership over upfront unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American-bound inventory. Component manufacturing concentrates in China, South Korea, and Taiwan, with final assembly tethered to Shenzhen and Dongguan clusters. Brushroll motors, solid-state lidar arrays, and lithium-ion cell packs constitute critical input dependencies. Single-source vulnerability persists in cathode material processing. Distribution runs through direct-to-consumer e-commerce fulfillment centers and specialty appliance retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against human-operated cleaning services and professional facility management contracts that retain performance advantages on specialized surfaces.
For Market Incumbents: Pre-empt margin erosion by securing captive supply of solid-state lidar modules through backward integration into automotive surplus channels. Accelerate certification investment for EU repairability index compliance before German and French retailer documentation mandates harden. Counter emerging camera-navigation entrants by emphasizing mapping accuracy differentiation in suburban North American replacement cycles. For New Entrants and Emerging Players: Build out white-space presence in India's underpenetrated apartment-dweller segment through BIS-certified mid-tier ultrasonic navigation products. Target window-cleaning robotics for Dubai and Singapore high-rise towers where incumbent competition remains sparse. Deploy direct-to-consumer subscription models for consumable replenishment to capture customer lifetime value data and reduce price transparency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled predictive maintenance firmware development as SLAM algorithm talent scarcity inflates engineering compensation. Long-term viability favors acquirers of integrated manufacturing scale operators with established Shenzhen component supplier relationships. Monitor EU Battery Regulation implementation velocity as inflection indicator for service revenue model profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lidar Supply | Automotive surplus channel access secures mapping hardware cost advantage against camera-array rivals. |
| EU Repairability Certification Investment | CE conformity documentation satisfies German and French retailer pre-shelf placement requirements. |
| Direct-to-Consumer Subscription Launch | Automated detergent pod delivery tied to usage telemetry concentrates customer lifetime value data. |
| Predictive Maintenance Firmware Development | Edge-computing diagnostics enable subscription consumable replenishment before performance degradation. |
| India Market Localization Partnership | Tamil Nadu and Karnataka electronics zones support regional supply chain assembly for BIS-certified units. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, and hyperscaler component procurement disclosures. Primary interviews engaged robotics firmware engineering directors, appliance category buyers at major retailers, lithium-ion cell procurement managers, and FCC certification consultants. Secondary validation drew from EIA energy consumption data, EU Ecodesign regulatory filings, and Shenzhen manufacturing cluster export records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs incorporate product type segmentation by robotic vacuum, mop, window cleaner, and surface disinfection categories; technology tier by navigation architecture; end user classification across residential, commercial, hospitality, and elderly care segments; and distribution channel by online retail, brick-and-mortar, specialty outlet, and direct sales routes. CAGRs were derived from regression analysis of historical replacement cycle velocity and penetration rate trajectories across suburban North American, EU, and Chinese urban markets. Industry-specific inputs include lidar module cost curve slopes and EU repairability index compliance adoption curves.
Stress conditions across lithium-ion cell supply disruption, FCC certification timeline extension, and EU Ecodesign enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding navigation hardware commoditization velocity and subscription model attach rate evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Robot Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Internet of Robotic Things Market
Robotics and Automation
Robot Label Applicators Market