
 LAMEA Demolition Robot Market | 2026-2036
LAMEA Demolition Robot Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Demolition Robot Market Analytics
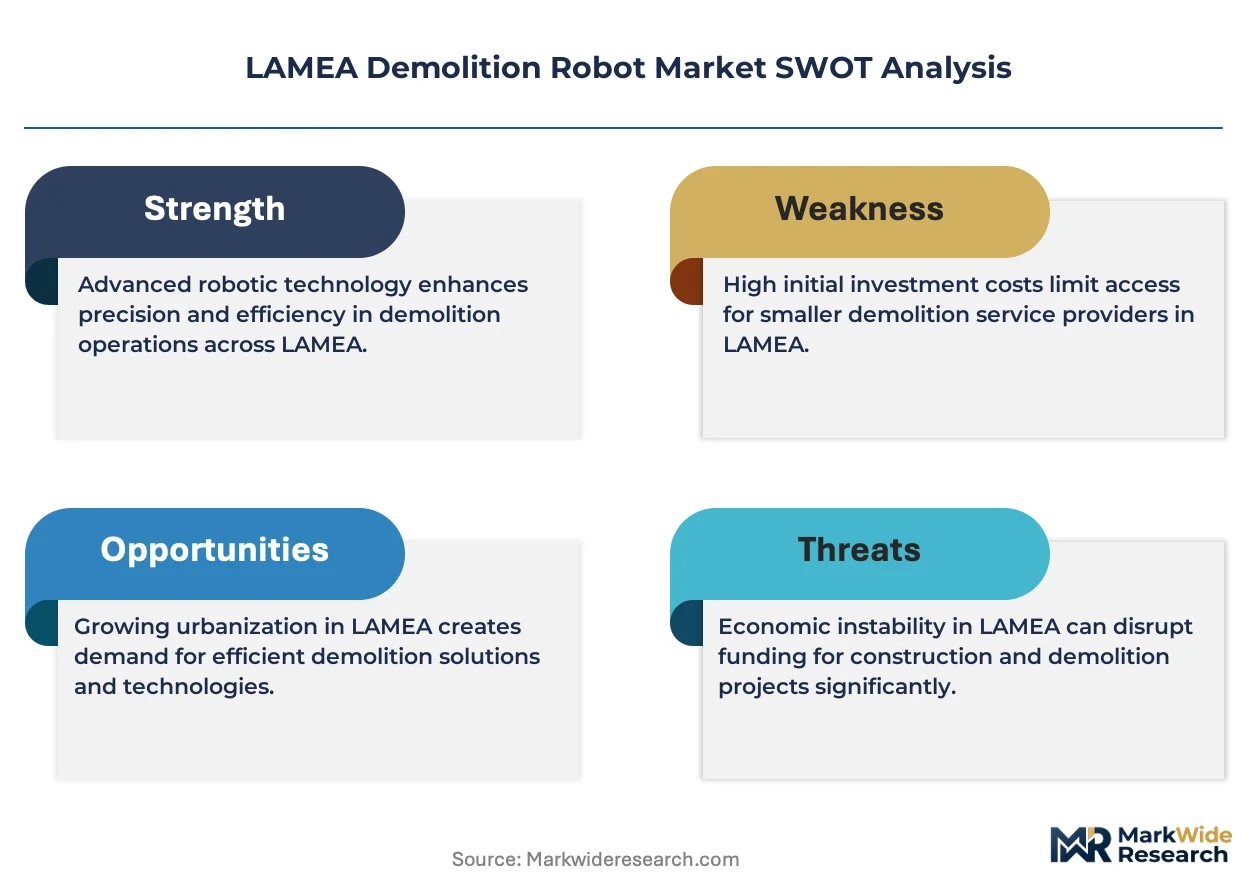
Steel-reinforced concrete demolition is shifting toward precision robotic breaking as labor costs and safety liabilities mount across LAMEA job sites. Brokk AB leverages its hydraulic breaker specialization to dominate high-reach interior demolition contracts in the Middle East. Husqvarna AB anchors its position through battery-powered compact units suited for urban noise restrictions. Epiroc AB competes in mining crossover applications where autonomous loading and breaking converge.
A demolition robot is a remotely operated or autonomous tracked machine carrying hydraulic, pneumatic, or electric tool attachments for controlled structural dismantling, typically rated by reach extension, tool weight capacity, and remote operating range exceeding 100 meters for operator safety. Its primary purpose is to deconstruct buildings, bridges, and industrial facilities where human entry risks collapse, airborne silica, or confined-space hazards. Remote-controlled units lead current LAMEA deployment because contractors prioritize proven reliability over algorithmic navigation in unpredictable debris fields. Autonomous systems represent the fastest-growing robot type as South African platinum mines and Chilean copper smelters pilot self-directed wall-sawing sequences. Diesel power sources still occupy the majority of installed base due to energy density requirements for continuous hydraulic breaking, though battery-powered variants are capturing municipal contracts with strict emissions rules.
South Africa's Department of Employment and Labour enforces Construction Regulations 2014 amendments that mandate fall-arrest and dust-suppression protocols favoring robotic substitution for manual jackhammer teams. The UAE's Ministry of Energy and Infrastructure applies green building dismantling credits that accelerate electric and battery-powered unit procurement. Saudi Arabia's Saudi Building Code and municipal authorities in Riyadh now require pre-demolition engineering surveys specifying remote methods for structures exceeding four stories. Stakeholders must monitor how rapidly evolving autonomous navigation standards from ISO and local mining regulators redefine insurability and liability frameworks for unsupervised demolition operations.
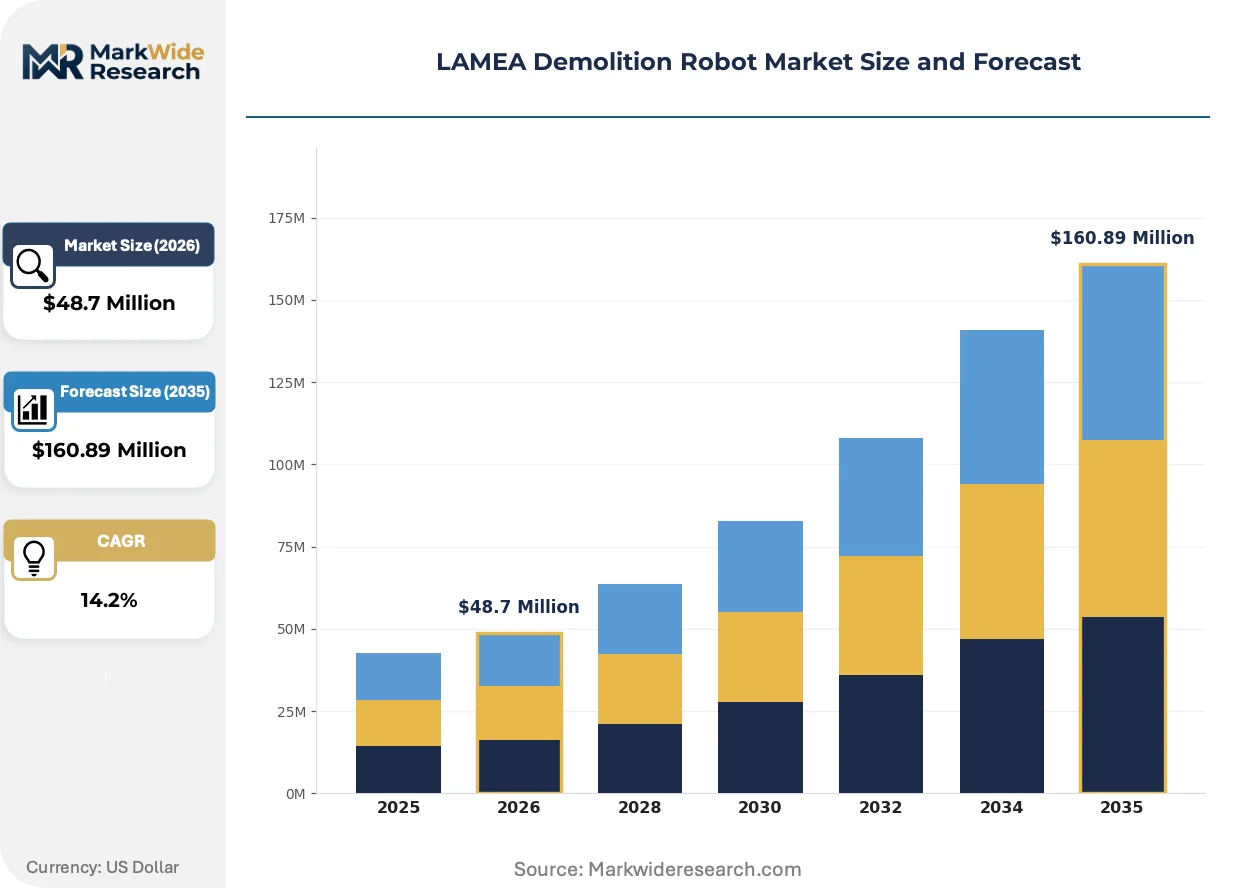
Market Dynamics
Steel-reinforced concrete demolition across LAMEA job sites is pivoting toward precision robotic breaking as labor costs climb and safety liabilities from manual jackhammer teams become unsustainable for contractors.
Growth Catalysts
- South Africa's Occupational Health and Safety Act:Enforcement of Construction Regulations 2014 amendments mandates dust-suppression protocols that favor remote-controlled demolition systems over manual crews in confined-space operations.
- UAE commercial deconstruction:Dubai and Abu Dhabi prioritize high-rise dismantling projects where robotic reach extension exceeds 15 meters, creating concentrated demand among demolition contractors.
- Battery-electric powertrains:Municipal contracts with strict emissions rules in Riyadh and São Paulo are accelerating procurement of zero-emission units for urban noise-restricted zones.
Market Restraints
- High-density battery supply concentration:Lithium-ion cell production for compact demolition units remains concentrated in East Asian suppliers, exposing LAMEA contractors to freight cost volatility and extended lead times.
- Diesel-to-electric infrastructure gap:Job sites in secondary Brazilian cities lack grid capacity for continuous charging of battery-powered breakers, forcing hybrid fleet maintenance.
- ISO 17757 autonomous navigation standards:Incomplete local adoption frameworks delay insurability for unsupervised demolition operations, freezing capital deployment for self-directed systems.
Strategic Opportunities
- Chilean copper smelter decommissioning:Mining crossover applications where autonomous loading and breaking converge represent underpenetrated demand for demolition robot OEMs with underground navigation expertise.
- Saudi Building Code remote-method mandates:Pre-demolition engineering surveys now specify remote methods for structures exceeding four stories in Riyadh, creating regulatory tailwind for high-reach unit procurement.
- Telematics-integrated rental channels:Equipment-as-a-service platforms with usage-based billing are emerging as distribution innovations that reduce upfront capex barriers for mid-tier demolition contractors.
Industry Challenges
- Remote operator certification timelines:South Africa's Department of Employment and Labour lacks standardized competency frameworks for robotic demolition equipment, extending workforce onboarding periods.
- Legacy hydraulic attachment interoperability:Contractors face integration complexity when mating third-party breakers to new OEM control systems, requiring custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Demolition Robot Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Remote-Controlled, Autonomous, Semi-Autonomous, Teleoperated Application: Construction, Waste Management, Infrastructure, Mining End User: Contractors, Government Agencies, Industrial Plants, Demolition Companies Power Source: Battery-Powered, Diesel, Electric, Hydraulic |
| Companies Covered | Brokk AB, Conjet AB, Husqvarna AB, Komatsu Ltd., ABB Ltd, Ekso Bionics Holdings, Inc., Autonomous Solutions, Inc., Epiroc AB, Cyberdyne, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Demolition Robot Market Evolving Landscape
Autonomous navigation and electric powertrains are actively compressing the operational boundaries between mining automation and building demolition across LAMEA, reshaping how contractors evaluate equipment procurement.
Machine vision-guided wall-sawing sequences are rewriting the risk calculus for structural dismantling in unpredictable debris fields. South African platinum mines and Chilean copper smelters pilot these systems for self-directed cutting operations. The technology is compressing insurance premiums for remote demolition contracts by reducing operator exposure to collapse zones.
REACH-equivalent chemical substance restrictions in the UAE's green building dismantling credits are accelerating electric and battery-powered unit procurement. The policy industrializes emissions accountability across commercial deconstruction tenders. High-rise contractors in Dubai respond by specifying zero-emission breakers for interior demolition phases.
Performance-based equipment leasing is displacing traditional capex purchase models among mid-tier demolition contractors. Rental platforms with telematics-linked uptime guarantees capture growing share from distributor direct sales. São Paulo's urban renewal contractors exhibit the strongest preference for this procurement evolution.
LAMEA Demolition Robot Market Segmentation
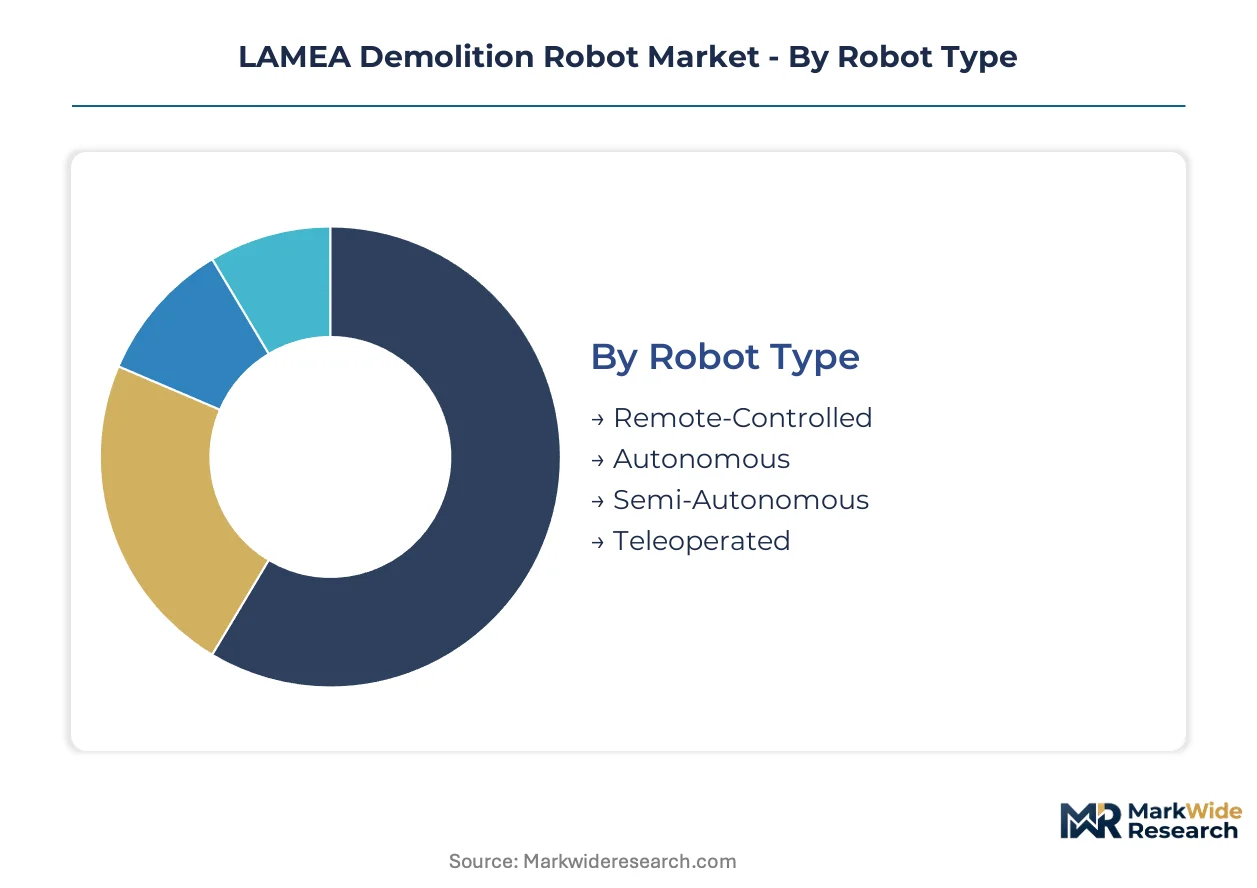
Demolition robot procurement across Latin America, Middle East, and Africa follows distinct specification logics that separate mature hydraulic fleets from emerging electric and autonomous alternatives. Contractors align robot selection with site constraints, regulatory exposure, and power infrastructure availability rather than universal performance metrics.
Robot Type:
Control architecture determines operational risk profiles and workforce certification requirements across LAMEA job sites.
- Remote-Controlled:Operators manipulate tracked units via radio link with 100-meter-plus separation from collapse zones. South Africa's Construction Regulations 2014 amendments favor these systems for confined-space concrete breaking where dust suppression is mandatory.
- Autonomous:Machine vision and LiDAR enable self-directed wall-sawing sequences without continuous human oversight. Chilean copper smelter decommissioning projects pilot these systems where operator exposure to structural instability is unacceptable.
- Semi-Autonomous:Human supervisors set cutting boundaries while onboard sensors handle tool positioning and force feedback. These units bridge reliability gaps in unpredictable debris fields where full autonomy remains uninsurable.
- Teleoperated:Low-latency video feeds enable real-time control from off-site command centers, reducing travel costs for specialist operators serving dispersed Brazilian urban renewal contracts.
Mature deployment sits with Remote-Controlled systems. Newer deployment is concentrated in Autonomous configurations.
Application:
Structural context dictates reach requirements, attachment specifications, and debris handling protocols.
- Construction:High-rise interior demolition in Dubai and Abu Dhabi demands 15-meter reach extension with zero-emission breakers for enclosed ventilation-limited spaces. UAE green building dismantling credits accelerate electric unit procurement for this vertical.
- Infrastructure:Bridge deck removal and tunnel widening require precision breaking to preserve adjacent structural elements. Saudi Building Code mandates for structures exceeding four stories create regulatory tailwind for robotic methods in Riyadh infrastructure renewal.
- Mining:Underground cross-cutting and stope backfilling convergence with surface demolition techniques. South African platinum operations pilot autonomous loading-breaking integration.
- Waste Management:Post-demolition sorting and hazardous material extraction from mixed debris streams. São Paulo municipal contracts specify battery-powered compact units for noise-restricted recycling facilities.
Volume concentration rests with Construction. Steepest expansion trajectory appears in Mining crossover applications.
End User:
Procurement authority separates fleet-owning specialists from project-specific renters.
- Demolition Companies:Specialist contractors in Brazil's urban renewal sector maintain diversified fleets spanning diesel breakers for heavy concrete and battery units for emissions-restricted phases. These firms drive attachment standardization across OEM platforms.
- Contractors:General construction firms increasingly specify robotic demolition in subcontracts to transfer liability for silica exposure and structural collapse. Mid-tier players favor telematics-integrated rental channels over capital purchase.
- Industrial Plants:Mining and smelting operators with captive maintenance divisions deploy autonomous systems for scheduled facility decommissioning. These end users prioritize underground navigation expertise from mining automation suppliers.
- Government Agencies:Municipal authorities in São Paulo and Riyadh write zero-emission and remote-method requirements into public demolition tenders, indirectly shaping contractor fleet composition.
Established purchasing power resides with Demolition Companies. Emerging demand concentrates in Industrial Plants.
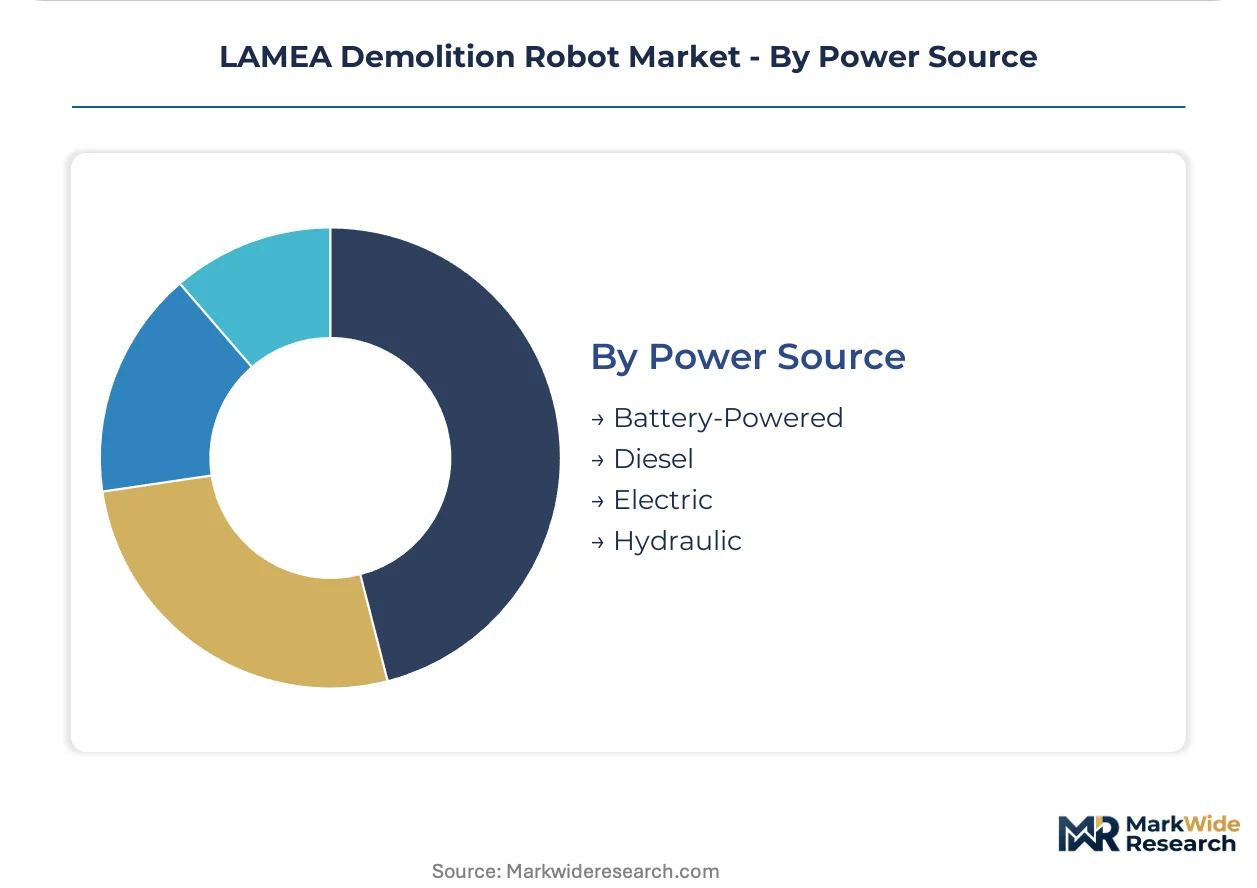
Power Source:
Energy density and emissions compliance trade off across site infrastructure conditions.
- Diesel:Continuous hydraulic breaking for steel-reinforced concrete demands energy density that battery systems cannot yet match. These units dominate Brazilian secondary cities where grid capacity for charging remains insufficient.
- Battery-Powered:Lithium-ion cells enable zero-emission operation for municipal contracts with strict noise and air quality rules. Riyadh and São Paulo urban zones exhibit strongest procurement preference, though East Asian cell supply concentration exposes contractors to freight volatility.
- Electric:Tethered cable power eliminates battery weight and range constraints for fixed-site industrial demolition. UAE commercial deconstruction projects specify these for high-rise phases where generator emissions are prohibited.
- Hydraulic:External power packs deliver breaking force independent of onboard engine or battery capacity. Legacy systems persist in mining crossover applications where autonomous loading and breaking convergence is prioritized.
Installed base dominance belongs to Diesel. Gaining share fastest are Battery-Powered variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial deconstruction across Dubai and Abu Dhabi concentrates the highest-value procurement, while Brazilian urban renewal and South African mining applications anchor volume demand. Regulatory divergence between emissions-focused Gulf states and safety-driven African jurisdictions shapes distinct specification requirements.
United Arab Emirates
Dubai's high-rise dismantling pipeline demands 15-meter reach extension with zero-emission breakers for enclosed ventilation-limited spaces. MOHAP green building dismantling credits accelerate electric unit procurement among demolition contractors. Abu Dhabi's commercial deconstruction sector concentrates the region's premium equipment deployment.
Brazil
São Paulo's urban renewal contractors drive the strongest preference for telematics-integrated rental channels over capital purchase. ANVISA-equivalent municipal emissions rules in secondary cities force hybrid fleet maintenance due to insufficient grid capacity. Rio de Janeiro's port infrastructure decommissioning generates sustained demand for precision breaking applications.
South Africa
The Department of Employment and Labour enforces Construction Regulations 2014 amendments that mandate dust-suppression protocols favoring remote-controlled systems. Johannesburg's platinum mining operations pilot autonomous loading-breaking integration for stope backfilling convergence. Cape Town's confined-space demolition contracts prioritize radio-link separation exceeding 100 meters.
Saudi Arabia
SFDA-equivalent municipal authorities in Riyadh now require pre-demolition engineering surveys specifying remote methods for structures exceeding four stories. The Saudi Building Code creates regulatory tailwind for high-reach unit procurement among infrastructure contractors. NEOM construction sites test battery-powered compact units for emissions-restricted phases.
Chile
Copper smelter decommissioning projects pilot autonomous wall-sawing sequences where operator exposure to structural instability is unacceptable. Mining crossover applications converge surface demolition techniques with underground navigation expertise. Santiago's industrial facility renewal generates demand for precision robotic breaking in steel-reinforced concrete environments.
LAMEA Demolition Robot Market Competitive Landscape
Portfolio diversification dominates the current landscape as established construction equipment manufacturers and mining automation specialists converge on demolition applications. The vendor base spans three tiers: hydraulic breaker specialists with decades of European heritage, diversified industrial conglomerates leveraging mining technology crossover, and emerging electric powertrain entrants from East Asian manufacturing clusters. Strategic archetypes separate reach-extension leaders, battery-compact innovators, and autonomous navigation pioneers. Technology licensing agreements and geographic expansion through distributor partnerships represent the two dominant competitive vectors reshaping market access.
Within the hydraulic specialization tier, Brokk AB and Husqvarna AB exemplify contrasting approaches to powertrain evolution. Brokk AB anchors high-reach interior demolition positioning through its Swedish heritage and breaker-focused engineering culture. Husqvarna AB occupies the battery-compact vector, representing Nordic innovation in emissions-restricted urban environments. Epiroc AB sits within the mining crossover archetype, where autonomous loading and breaking convergence creates distinctive underground navigation credibility.
| Leading Market Players |
|---|
| Brokk AB |
| Conjet AB |
| Husqvarna AB |
| Komatsu Ltd. |
| ABB Ltd |
| Ekso Bionics Holdings, Inc. |
| Autonomous Solutions, Inc. |
| Epiroc AB |
| Cyberdyne, Inc. |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery cell costs cascade through three pricing tiers for demolition robot OEMs, compressing margins on battery-powered compact units while diesel-hydraulic systems retain pricing power in Brazilian secondary cities lacking grid infrastructure for charging.
Pricing Analysis
Volume concentration in diesel-hydraulic breakers trades off against margin expansion in battery-electric and autonomous configurations. Pricing stratifies across premium autonomous navigation, standard remote-controlled electric, and economy diesel-hydraulic tiers based on certification grade and after-sales service bundling. Cost compression in battery-powered segments is intensifying because East Asian cell supply concentration exposes LAMEA contractors to freight volatility. Demolition companies exhibit highest price sensitivity due to fleet refresh cycles, while industrial plant operators with captive maintenance divisions show lowest sensitivity to upfront capital outlay.
Supply Chain Analysis
Regional distribution centers in Dubai and São Paulo operate hub-and-spoke patterns that position finished units within 48-hour delivery windows of major deconstruction sites. Manufacturing concentrates in Sweden, Japan, and China for hydraulic breakers, battery cells, and machine vision sensors respectively. Raw material dependencies span high-grade steel for breaker attachments, lithium carbonate for powertrains, and rare earth elements for electric drive motors. Single-source vulnerability in East Asian battery cell production creates supply chain risk for electric unit procurement. Distribution runs through OEM-direct sales for large fleet purchases and telematics-integrated rental platforms for mid-tier contractor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around OEMs with captive battery supply agreements and autonomous navigation IP, as ISO 17757 compliance costs force smaller hydraulic specialists toward acquisition or exit.
For Market Incumbents: Cement dominance in high-reach interior demolition through backward integration into breaker attachment manufacturing, reducing third-party adapter fabrication costs. Lock in long-term lithium supply offtake with Korean cell producers to insulate against freight volatility threatening battery-powered unit margins. Prioritize certification investment for autonomous navigation systems ahead of South African mining regulator adoption timelines. For New Entrants and Emerging Players: Capture share in Chilean copper smelter decommissioning where mining automation expertise converges with surface demolition demand and incumbent presence remains thin. Target telematics-integrated rental channels in São Paulo's urban renewal sector, where mid-tier contractors favor usage-based billing over capital purchase. Lead with battery-compact units for municipal noise-restricted contracts in Riyadh and Dubai. For Investors and Strategic Acquirers: Saudi Building Code remote-method mandates for structures exceeding four stories is the leading indicator that regulatory tailwinds will concentrate procurement authority among fleet-scale specialists. Frame long-term viability around 5-10 year autonomous navigation standardization windows. Target acquisition profiles at mining automation suppliers with underground LiDAR expertise transferable to structural dismantling. Watch for South African platinum mine pilot completions as inflection signals for autonomous loading-breaking integration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breaker Manufacturing | Reduces adapter fabrication costs for legacy hydraulic attachment interoperability. |
| Battery Supply Agreement with Korean Producers | Insulates margin compression from East Asian lithium-ion cell freight volatility. |
| Autonomous Navigation Certification Investment | Positions ahead of ISO 17757 local adoption frameworks freezing unsupervised deployment. |
| Telematics-Integrated Rental Platform Launch | Captures São Paulo mid-tier contractor preference for usage-based procurement. |
| Mining Automation Technology Licensing | Accelerates underground navigation credibility for Chilean smelter decommissioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across demolition company fleet managers, mining plant maintenance directors, municipal procurement officers, and OEM distribution channel heads. Bottom-up unit shipment tracking across robot type, power source, and application segments triangulated against top-down market value estimates derived from equipment transaction databases and rental platform disclosures.
Granularity-level modeling specified reach extension tiers, powertrain configurations, and control architectures at the country-market level across the projection horizon. CAGRs derived from regression analysis against urban renewal project pipelines, mining decommissioning schedules, and regulatory enforcement timelines. Industry-specific forecast inputs included Construction Regulations 2014 amendment implementation rates and Saudi Building Code pre-demolition survey mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous navigation standardization pace and battery supply chain restructuring. Outputs reflect documented assumptions around regulatory enforcement intensity and infrastructure buildout schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Bot Services Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Robot Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Global Robot Teach Pendant Market