
 Global Smart Robots Market | 2026-2036
Global Smart Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Robots Market Outlook
China is narrowing its dependency on imported robotic components through domestic foundry investments and subsidized automation parks. FANUC Corporation leverages its CNC heritage to anchor precision control systems across Asian automotive lines. ABB competes through its Ability digital platform, which extends predictive maintenance capabilities to fleet operators. Boston Dynamics differentiates via legged locomotion patents that occupy niche terrain-navigation contracts for defense and inspection clients.
Smart robots integrate actuators, sensors, and onboard processors to execute tasks with minimal human intervention, typically operating through SLAM navigation and force-torque feedback loops for collision avoidance. Their primary purpose centers on augmenting labor in hazardous, repetitive, or precision-critical environments. Industrial robots sustain the largest revenue pool due to established automotive and electronics deployment, while collaborative robots represent the fastest structural expansion as safety-rated force-limiting arms penetrate small-batch manufacturing. Humanoid robots concentrate venture funding but remain pre-commercial, with margin pools currently captured by sensor and AI software suppliers rather than integrators.
The EU Machinery Directive and CE marking framework shape product liability and safety certification requirements for robot deployment across European facilities. Japan's METI publishes roadmap standards for human-robot coexistence, while China's MIIT enforces GB standards for industrial robot reliability and interoperability. The US FDA and FAA maintain parallel oversight for surgical robots and aerial drones respectively, fragmenting compliance pathways for multi-application vendors. Stakeholders must monitor which jurisdiction's certification timeline becomes the critical-path bottleneck for cross-border product launches.
Market Dynamics
Precision assembly demands from Germany's automotive sector are compressing robot deployment cycles, while China's domestic foundry investments are rewiring component sourcing patterns across Asian supply chains.
Growth Catalysts
- EU Machinery Directive compliance mandates:German manufacturing facilities must certify precision assembly robots under updated CE marking frameworks, accelerating replacement of legacy industrial arms.
- Japan's aging demographics:METI roadmap standards for human-robot coexistence are channeling service robot deployment into healthcare and eldercare facilities facing acute labor shortages.
- SLAM navigation maturation:Simultaneous localization and mapping algorithms are reducing deployment costs for autonomous mobile robots in warehouse fulfillment operations.
Market Restraints
- High-purity sensor input costs:Force-torque sensors and LiDAR modules depend on concentrated rare earth processing capacity, creating margin volatility for mid-tier integrators.
- CE marking timeline friction:EU Machinery Directive certification pathways for collaborative robots extend commercialization cycles by 8-14 months versus non-certified industrial alternatives.
- Humanoid pre-commercialization:Bipedal locomotion platforms remain technically constrained by battery energy density limits, deferring revenue capture to sensor and AI software suppliers.
Strategic Opportunities
- India's automation parks:PLI scheme subsidies for electronics manufacturing are creating first-mover entry points for collaborative robot vendors in smartphone assembly lines.
- Surgical robotics regulatory tailwind:FDA 510(k) pathway refinements for minimally invasive systems are compressing approval timelines for haptic feedback-enabled platforms.
- Digital twin convergence:Integration of predictive maintenance software with fleet management systems is virtualizing service revenue models for automotive line operators.
Industry Challenges
- Multi-jurisdiction certification bottlenecks:Vendors deploying surgical and aerial drone variants must sequence FDA, FAA, and EU MDR timelines, fragmenting product launch coordination.
- Legacy system integration complexity:Force-limiting collaborative arms require retrofitting of existing PLC architectures in small-batch manufacturing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Robots Market |
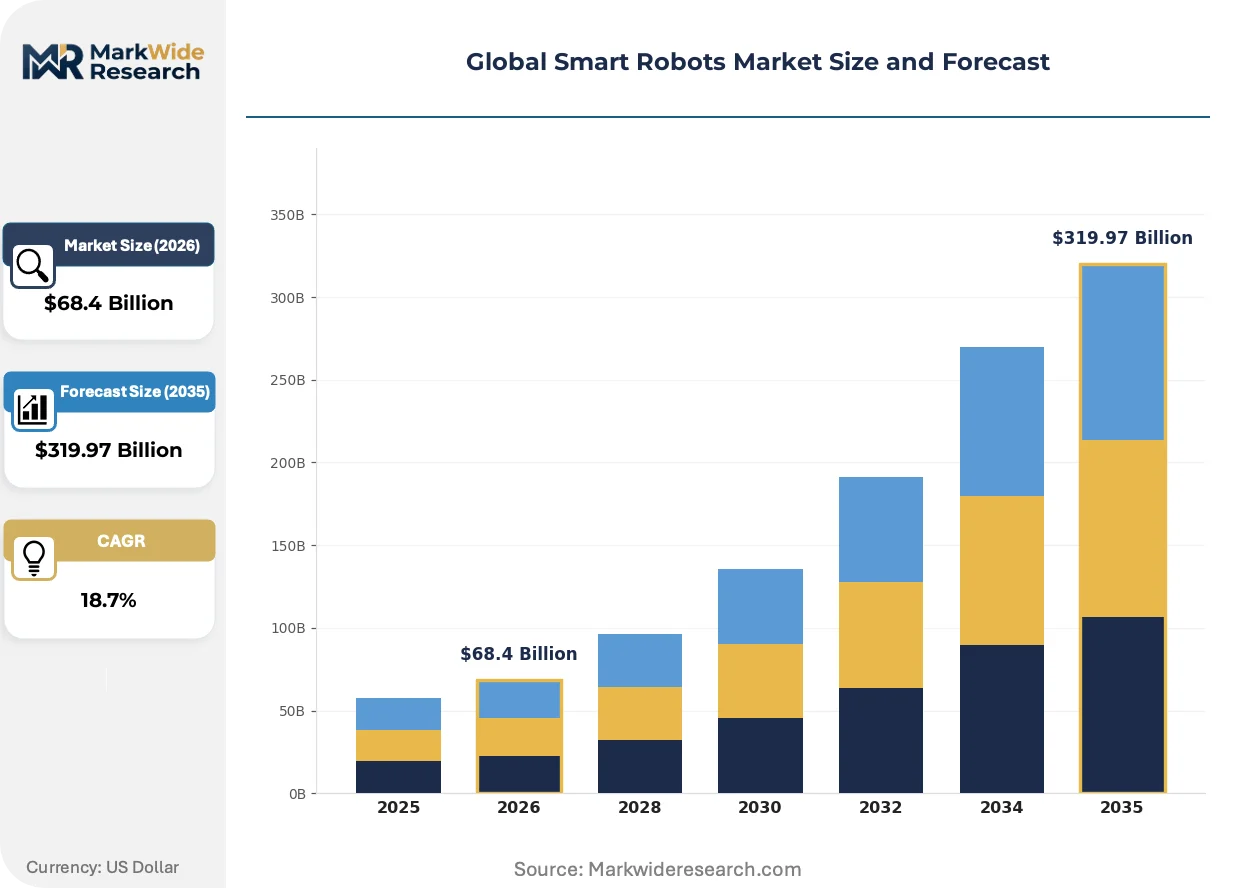
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Humanoid Robots Technology: AI, Machine Learning, Computer Vision, Sensor Technology End User: Manufacturing, Healthcare, Retail, Hospitality Application: Logistics, Surveillance, Assembly, Cleaning |
| Companies Covered | KUKA AG, Yaskawa Electric Corporation, iRobot Corporation, Boston Dynamics, Teradyne Inc., SoftBank Robotics Group, FANUC Corporation, UBTECH, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Robots Market Strategic Shifts
Edge computing architectures and synthetic training environments are compressing robot learning curves, while regulatory fragmentation across medical and industrial applications is forcing modular certification strategies.
Digital twin environments are virtualizing robot deployment planning for automotive and electronics manufacturers. BMW and Foxconn operations teams are simulating line configurations before physical installation, reducing commissioning time by eliminating hardware-in-the-loop testing iterations. This virtualization is compressing the traditional integration service revenue pool while shifting margin capture to software licensing.
China's MIIT enforcement of GB standards for industrial robot interoperability is mandating open communication protocols across domestic automation parks. Foreign vendors must reengineer controller architectures to comply, raising non-recurring engineering costs for European and Japanese entrants. Domestic integrators in Shenzhen and Suzhou are capturing retrofit contracts from multinationals seeking compliance shortcuts.
Japanese automotive buyers are unbundling after-sales service contracts from initial robot procurement, pressuring FANUC and Yaskawa to compete with independent maintenance providers on predictive analytics capabilities. Tier-2 suppliers in Nagoya and Toyota City are piloting subscription-based uptime guarantees, displacing traditional spare parts revenue with performance-based pricing in precision welding applications.
Global Smart Robots Market Segmentation
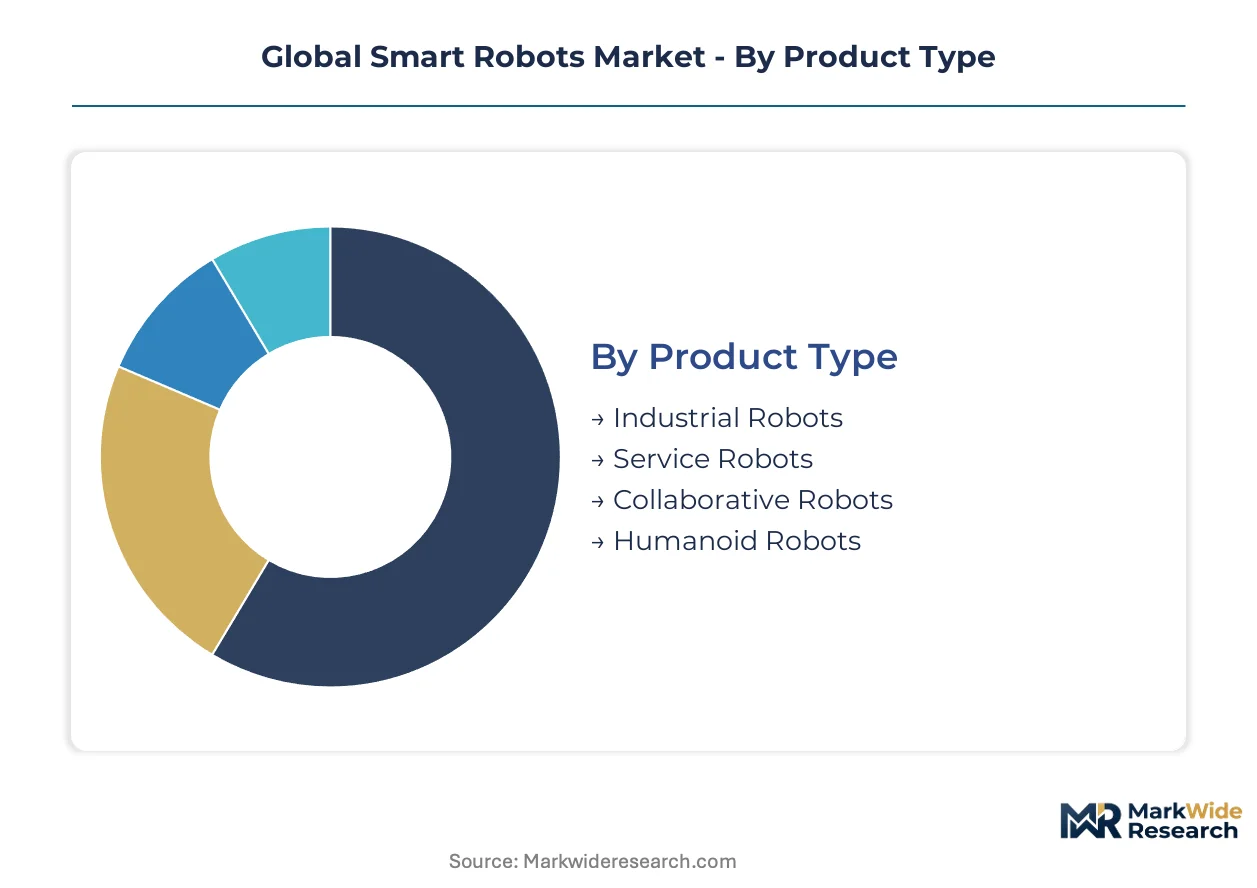
Segmentation reveals how revenue pools concentrate across robot architectures and how service intensity varies by deployment complexity. Procurement patterns diverge sharply between precision-manufacturing buyers seeking uptime guarantees and healthcare operators prioritizing regulatory compliance pathways.
Product Type:
After-sales-service intensity escalates with mechanical complexity and safety-critical deployment environments, creating divergent margin structures across robot categories.
- Industrial Robots:Six-axis articulated arms with payload capacities exceeding 20 kilograms dominate automotive welding and electronics assembly. German automotive OEMs in Stuttgart and Wolfsburg unbundle maintenance contracts, pressuring vendors toward predictive analytics subscriptions. Industrial robots hold the largest share; momentum sits with collaborative variants.
- Service Robots:Autonomous mobile platforms navigate healthcare corridors and warehouse aisles through SLAM-enabled LiDAR arrays. Japan's eldercare facilities in Osaka and Fukuoka deploy these units under METI human-robot coexistence standards to offset acute nursing shortages.
- Collaborative Robots:Force-limiting arms with ISO/TS 15066 safety ratings enable human-robot workspace sharing without physical guarding. India's PLI-subsidized electronics parks in Noida and Sri City attract first-mover deployments for smartphone assembly.
- Humanoid Robots:Bipedal platforms remain pre-commercial, constrained by battery energy density and actuator cost structures. Venture funding concentrates on sensor and AI software suppliers rather than integrated hardware vendors.
Industrial robots capture established revenue pools; collaborative platforms are gaining share fastest.
Technology:
Technology stack composition determines differentiation durability and switching costs for fleet operators.
- AI:Deep learning frameworks enable real-time task adaptation without explicit reprogramming. China's MIIT-mandated GB standards for industrial interoperability force foreign vendors to reengineer controller architectures, raising non-recurring engineering costs.
- Machine Learning:Reinforcement learning algorithms compress robot training cycles through synthetic environment simulation. Edge computing deployments in Shenzhen automation parks reduce latency for vision-guided pick-and-place operations.
- Computer Vision:Convolutional neural networks process 2D and 3D sensor feeds for defect detection and bin picking. German precision assembly lines leverage these systems under updated EU Machinery Directive CE marking frameworks.
- Sensor Technology:Force-torque sensors and solid-state LiDAR modules depend on concentrated rare earth processing capacity in Chinese foundries, creating input cost volatility for mid-tier integrators.
Sensor technology anchors hardware bill-of-materials; AI software layers command expanding margin capture.
End User:
End-use concentration shapes certification requirements and sales cycle duration across vertical markets.
- Manufacturing:Automotive and electronics sectors drive precision assembly demand with compressed deployment cycles. BMW operations teams in Munich simulate line configurations through digital twin environments before physical installation.
- Healthcare:Surgical robotics and eldercare assistance platforms face multi-jurisdiction FDA and PMDA approval pathways. Japan's aging demographics channel METI roadmap investments into hospital and nursing facility automation.
- Retail:Warehouse fulfillment robots navigate inventory aisles for e-commerce order consolidation. SLAM navigation maturation is reducing deployment costs for autonomous mobile platforms in distribution centers.
- Hospitality:Cleaning and concierge robots encounter fragmented procurement authority across hotel chains and facility management contractors.
Manufacturing absorbs the highest unit volumes; healthcare commands premium pricing through regulatory barriers.
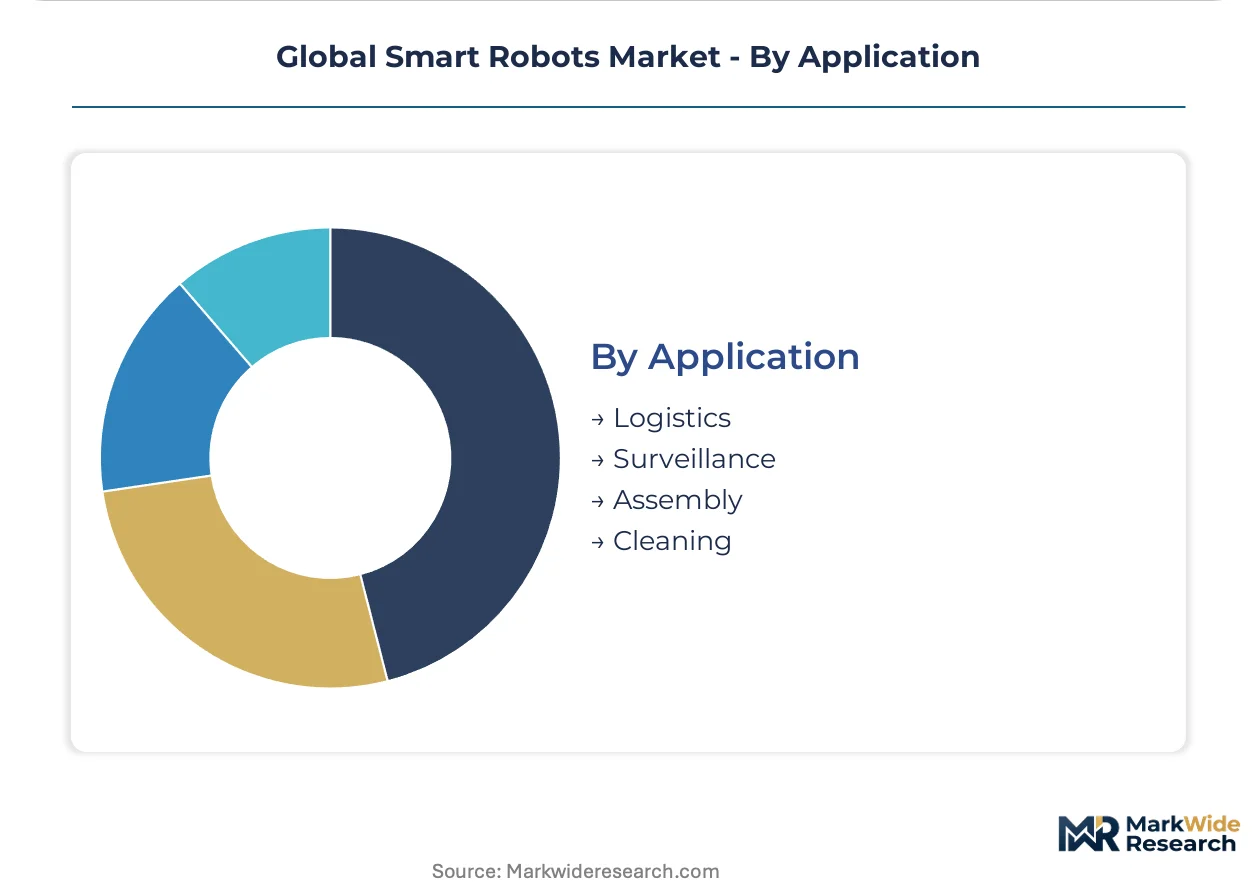
Application:
Application specificity determines sensor payload requirements and software customization depth.
- Logistics:Autonomous mobile robots traverse warehouse environments for goods-to-person fulfillment. Amazon and Alibaba distribution networks in Nevada and Zhejiang drive fleet standardization pressures.
- Surveillance:Aerial and ground-based inspection platforms monitor critical infrastructure under FAA and EASA operational constraints. Boston Dynamics legged locomotion patents occupy niche terrain-navigation contracts for defense and energy sector clients.
- Assembly:Precision joining operations in automotive and electronics manufacturing demand sub-millimeter repeatability. FANUC CNC heritage anchors control system performance across Asian production lines.
- Cleaning:Floor-scrubbing and sanitization robots deploy in commercial facilities with limited technical staffing for maintenance oversight.
Assembly commands the highest average selling prices; logistics applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foundry investments and German precision assembly mandates concentrate component supply and certification demand across two distinct poles. Japanese eldercare automation and American surgical robotics create divergent demand profiles. Indian electronics manufacturing subsidies are emerging as a third demand anchor.
China
Domestic foundry investments in Shenzhen and Suzhou are narrowing dependency on imported robotic components through subsidized automation parks. MIIT enforcement of GB standards for industrial robot interoperability mandates open communication protocols, forcing foreign vendors to reengineer controller architectures. Domestic integrators in the Pearl River Delta capture retrofit contracts from multinationals seeking compliance shortcuts.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are compressing robot deployment cycles for precision assembly under updated EU Machinery Directive CE marking frameworks. German manufacturing facilities must certify precision assembly robots under these mandates, accelerating replacement of legacy industrial arms. Operations teams at BMW in Munich simulate line configurations through digital twin environments before physical installation.
Japan
Aging demographics and acute nursing shortages are channeling service robot deployment into healthcare and eldercare facilities in Osaka and Fukuoka. METI roadmap standards for human-robot coexistence shape procurement specifications for these deployments. Japanese automotive buyers in Nagoya and Toyota City are unbundling after-sales service contracts from initial robot procurement, pressuring vendors toward predictive analytics subscriptions.
United States
Surgical robotics and aerial drone development face parallel FDA and FAA oversight, fragmenting compliance pathways for multi-application vendors. FDA 510(k) pathway refinements for minimally invasive systems are compressing approval timelines for haptic feedback-enabled platforms. Distribution networks in Nevada drive fleet standardization pressures for warehouse fulfillment robots.
India
PLI scheme subsidies for electronics manufacturing are creating first-mover entry points for collaborative robot vendors in smartphone assembly lines. The country's national industrial policy authority channels investment into automation parks in Noida and Sri City. Domestic electronics manufacturers are piloting force-limiting collaborative arms for small-batch assembly operations.
Global Smart Robots Market Competitive Environment
Industrial automation conglomerates and specialized robotics developers split the market along application depth versus breadth axes. The vendor base organizes into three strategic archetypes: diversified industrial conglomerates with CNC heritage, pure-play robotics specialists with legged locomotion or mobility focus, and contract manufacturers scaling through original design relationships. Competitive moves concentrate on predictive maintenance software integration and force-limiting safety architecture licensing.
Within the diversified industrial tier, FANUC Corporation and ABB exemplify archetypes anchored by precision control heritage and digital platform extension respectively. KUKA AG occupies a position representing European automotive line integration expertise. Among mobility-focused specialists, Boston Dynamics exemplifies terrain-navigation patent positioning for defense and inspection applications. Yaskawa Electric Corporation sits within the Japanese industrial cluster alongside FANUC, representing consolidated precision manufacturing supply. These five names illustrate how competitive positioning fragments across heritage-driven control systems, software-layer services, and niche locomotion patents.
| Leading Market Players |
|---|
| KUKA AG |
| Yaskawa Electric Corporation |
| iRobot Corporation |
| Boston Dynamics |
| Teradyne Inc. |
| SoftBank Robotics Group |
| FANUC Corporation |
| UBTECH |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's rare earth foundry clusters anchor global actuator and sensor supply, concentrating upstream pricing power among domestic Chinese processors while forcing foreign integrators into long-term offtake negotiations. This geographic chokepoint propagates downstream into force-torque sensor and solid-state LiDAR module costs, compressing margins for mid-tier European and Japanese robot vendors dependent on these inputs.
Pricing Analysis
EU Machinery Directive CE marking dictates the pricing tier structure across European deployments, separating safety-certified collaborative arms from uncertified industrial alternatives by 8-14 month commercialization timelines. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in mid-tier segments is intensifying because Chinese domestic integrators capture retrofit contracts from multinationals seeking GB standards compliance shortcuts. Small-batch manufacturers in Germany and Japan exhibit highest price sensitivity due to PLC architecture retrofit requirements, while automotive OEMs in Stuttgart and Wolfsburg prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Rare earth processing capacity in Chinese foundries feeds global force-torque sensor and LiDAR module production, with secondary concentration in Japanese precision component manufacturing for CNC heritage controllers. Raw material dependencies center on neodymium-doped magnetic alloys, high-purity silicon for solid-state sensors, and cobalt-based alloys for high-torque actuators. Single-source vulnerability concentrates in Shenzhen and Suzhou automation park ecosystems, where MIIT-mandated GB standards create captive demand for domestic controller architectures. Distribution runs through tier-1 automotive OEM procurement offices, tier-2 electronics manufacturing service providers, and independent system integrators serving small-batch precision assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Robots Market operates as a defensive-moat arena where regulatory certification entrenchment and customer switching costs protect incumbent positions. Network effects in predictive maintenance software ecosystems amplify this structural advantage.
For Market Incumbents: Entrench position through backward integration into sensor foundry capacity in Shenzhen automation parks, securing rare earth processing allocation against Chinese domestic preference policies. Deepen predictive analytics subscription attach rates among Japanese automotive buyers in Nagoya and Toyota City to displace independent maintenance providers. Counter emerging threat from Chinese domestic integrators by accelerating FDA 510(k) pathway investments for surgical robotics variants. For New Entrants and Emerging Players: India's PLI-subsidized electronics parks in Noida and Sri City offer the most penetrable entry corridor, with collaborative robot deployment in smartphone assembly lines running ahead of established vendor presence. Target force-limiting arm pilots with domestic electronics manufacturers seeking small-batch flexibility without legacy PLC retrofit complexity. Go-to-market angle should emphasize rapid GB standards compliance certification to outpace European and Japanese entrants facing reengineering cost disadvantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor and AI software suppliers over integrated hardware vendors, as margin pools concentrate upstream from pre-commercial humanoid platforms. Long-term viability rests on regulatory certification asset accumulation and digital twin software licensing revenue durability. Signal to monitor: FDA 510(k) approval timeline compression for haptic feedback-enabled surgical platforms as inflection indicator for healthcare robotics valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | BMW and Foxconn operations teams virtualize service revenue through digital twin integration. |
| GB Standards Compliance Certification | Foreign vendors reengineer controller architectures for MIIT-mandated interoperability in Chinese automation parks. |
| Force-Limiting Safety Architecture Licensing | ISO/TS 15066 safety ratings enable human-robot workspace sharing in India's PLI-subsidized electronics manufacturing. |
| Surgical Robotics FDA 510(k) Submission | Haptic feedback-enabled platforms compress approval timelines through refined regulatory pathway navigation. |
| Rare Earth Foundry Backward Integration | Shenzhen and Suzhou domestic integrators capture retrofit contracts from multinationals seeking supply security. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at automotive OEMs, procurement leads at electronics manufacturing services, aftermarket service heads at industrial robot vendors, and regulatory affairs specialists at surgical robotics developers, then refined through secondary validation against SEC 10-K filings, customs and trade data for robotic component flows, EU Machinery Directive certification databases, and METI roadmap publication archives. Bottom-up unit deployment estimates triangulated against top-down market sizing derived from automation park investment disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning robot architecture, technology stack composition, end-use vertical, and application specificity. CAGRs emerged from installed base growth curves and replacement cycle compression patterns, cross-referenced against SLAM navigation deployment cost trajectories in warehouse fulfillment and force-torque sensor input cost volatility assumptions.
Practitioners should monitor rare earth processing capacity allocation shifts, FDA 510(k) pathway refinement announcements, and METI human-robot coexistence standard updates for early signals requiring forecast revision. Cross-checking against IHS Markit industrial automation equipment shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Top Robotics Market