
 Assistive Technology Market | 2026-2036
Assistive Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Assistive Technology Market Analysis
Aftermarket service revenue is reshaping profit pools across the assistive technology value chain as manufacturers pivot from one-time hardware sales to recurring maintenance and software subscription models. Invacare Corporation leverages its national technician network to capture recurring revenue from mobility aid servicing. Sonova Holding AG sustains premium positioning through proprietary fitting software that locks audiologists into its ecosystem. Ottobock SE & Co. KGaA anchors its prosthetics business with lifelong patient support contracts that extend customer lifetime value well beyond initial device purchase.
Assistive technology encompasses electromechanical devices, sensory augmentation systems, and adaptive software engineered to restore, compensate, or enhance functional capabilities for users with physical, sensory, or cognitive impairments; specifications span battery endurance thresholds for powered mobility, frequency response ranges for hearing instruments, and calibration precision for eye-tracking interfaces. Hearing aids occupy the most mature margin pool, where GN Store Nord and Demant compete on signal processing algorithms and direct-to-consumer channel expansion. Wearable devices represent the fastest-growing technology segment, with Cochlear Limited specializing in implantable neurostimulation systems that merge hardware miniaturization with real-time neural signal adaptation.
The FDA's Class II medical device framework and the EU Medical Device Regulation (MDR) impose clinical evidence requirements and post-market surveillance obligations that raise barriers for new entrants while validating premium pricing for compliant manufacturers. The WHO's priority assistive products list shapes procurement standards in low- and middle-income markets, redirecting donor funding toward hearing aids, wheelchairs, and low-vision devices that meet international quality benchmarks. Stakeholders must monitor reimbursement code consolidation across public payers, as coverage decisions for emerging categories like augmented reality glasses will determine which technology platforms achieve commercial scale.
Market Dynamics
The pivot toward recurring revenue models is restructuring competitive economics across assistive technology, as manufacturers abandon transactional hardware margins for lifetime patient value captured through software subscriptions and preventive maintenance contracts.
Growth Catalysts
- Japan's aging demographic:The world's oldest population is expanding the installed base for mobility aids and sensory augmentation devices, with METI procurement guidelines prioritizing domestic supplier qualification.
- FDA Breakthrough Device Designation:Expedited review pathways for neurostimulation and brain-computer interfaces are compressing time-to-market for implantable assistive systems.
- EU MDR harmonization:Unified clinical evidence standards across member states are enabling cross-border reimbursement recognition that accelerates manufacturer scale-up.
Market Restraints
- Lithium-ion supply concentration:Powered mobility devices face input cost volatility as cathode material processing clusters in China, exposing manufacturers to export restriction risk.
- Cochlear implant surgical capacity:The pool of qualified otologic surgeons limits implantable hearing device penetration regardless of manufacturing output.
- Medicaid reimbursement fragmentation:State-level coverage variance for augmentative communication devices creates demand discontinuities that distort production planning.
Strategic Opportunities
- Rural India penetration:WHO priority assistive products list alignment is unlocking donor-funded procurement channels for low-cost hearing aids and manual wheelchairs in underserved districts.
- AR-vision convergence:Spatial computing platforms are creating new application white space for low-vision enhancement beyond traditional optical magnification.
- Germany DiGA fast-track:Digital health applications regulation is opening reimbursement pathways for app-based cognitive assistive tools that complement hardware devices.
Industry Challenges
- Embedded software validation:FDA cybersecurity guidance for connected medical devices is extending certification timelines for hearing aid and wheelchair control systems.
- Orthopedic prosthetist training pipelines:The technician shortage for socket fitting and gait calibration is constraining patient throughput for microprocessor-controlled limbs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assistive Technology Market |
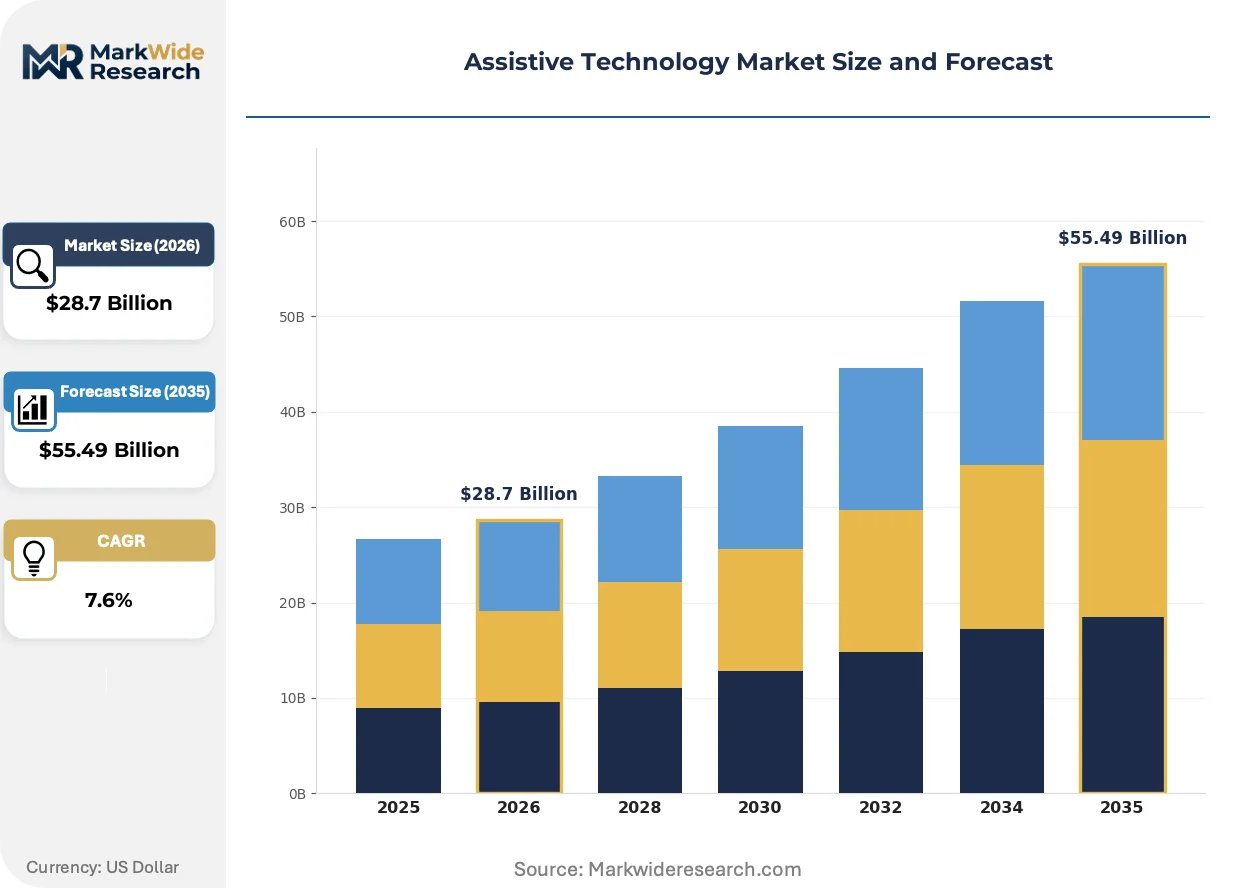
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $55.49 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Communication Devices, Adaptive Software, Hearing Aids End User: Individuals with Disabilities, Elderly, Educational Institutions, Care Facilities Technology: Speech Recognition, Eye-Tracking, Augmented Reality, Wearable Devices Application: Learning, Daily Living, Employment, Healthcare |
| Companies Covered | Invacare Corporation, Sonova Holding AG, Medline Industries, Ottobock SE & Co. KGaA, GN Store Nord, Cochlear Limited, Permobil, Sunrise Medical, Demant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assistive Technology Market Emerging Trajectories
Signal processing miniaturization and cloud-connected device ecosystems are converging to redefine patient-device relationships, shifting competitive advantage from mechanical engineering toward algorithmic personalization and data platform ownership.
On-device machine learning inference is collapsing the latency gap between acoustic environment detection and hearing aid parameter adjustment. Audiologists in Germany and the United States are fitting instruments that train on patient-specific soundscapes within 48 hours of first use. This compression of the adaptation curve is eliminating the traditional multi-visit fitting protocol that previously anchored retail channel economics.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance data collection for Class IIb implantable devices. Manufacturers must now maintain active patient registries that track device function across multi-year horizons. Cochlear implant and neurostimulation suppliers are responding by embedding cellular connectivity as standard, transforming compliance obligation into recurring subscription revenue.
Veterans Affairs procurement in the United States is consolidating purchasing authority for complex rehabilitation technology through national contracting vehicles that bypass regional distributor networks. This buyer concentration is forcing mobility aid manufacturers to restructure field service organizations around direct technician deployment rather than dealer-supported maintenance. The shift is most visible in powered wheelchair and custom seating categories where VA represents concentrated volume.
Assistive Technology Market Segmentation
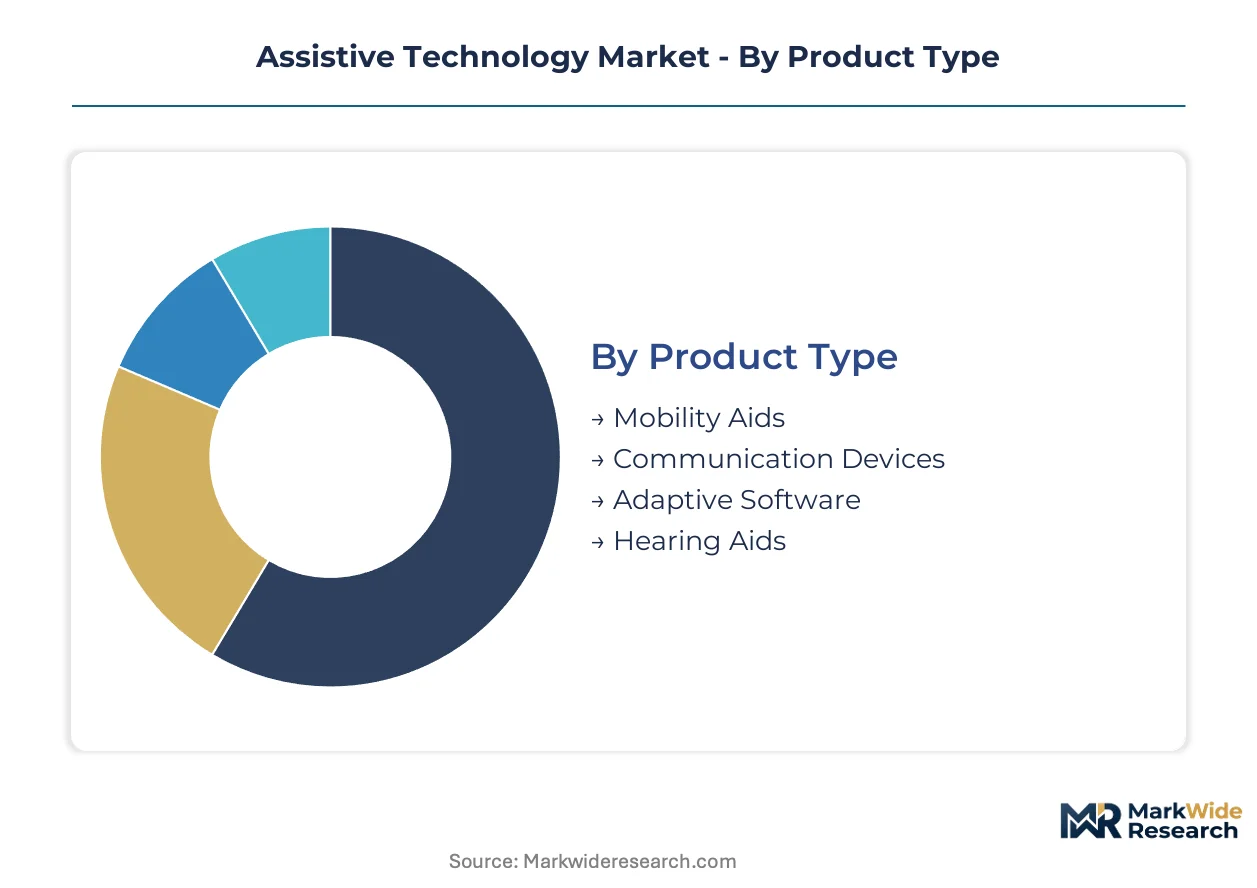
Segmentation in assistive technology reveals divergent replacement cycles and margin structures across hardware, software, and hybrid systems. Product type and technology dimensions expose which categories command recurring revenue versus one-time transactions.
Product Type:
Hearing aids turn over every 4-5 years as firmware obsolescence accelerates, while mobility aids stretch across 8-12 year depreciation horizons.
- Mobility Aids:Powered wheelchairs, manual wheelchairs, and walkers incorporate lithium-ion battery systems and modular seating. Demand concentrates in United States Veterans Affairs procurement channels, where national contracting vehicles now bypass regional distributors and force direct manufacturer service deployment.
- Hearing Aids:Behind-the-ear and in-the-ear instruments with on-device machine learning inference for acoustic environment adaptation. Germany and United States audiologists are fitting instruments that train on patient-specific soundscapes within 48 hours, collapsing traditional multi-visit protocols.
- Communication Devices:Augmentative and alternative communication hardware with symbol-based or text-to-speech output.
- Adaptive Software:Screen readers, voice navigation, and cognitive assistance applications.
Mobility aids dominate installed base. Hearing aids are where expansion concentrates.
End User:
Customer lifetime value varies dramatically across institutional procurement versus individual out-of-pocket purchase.
- Elderly:Japan's aging demographic and Germany's pension-funded procurement are expanding the installed base for sensory augmentation and mobility devices. METI guidelines in Japan prioritize domestic supplier qualification, while German statutory health insurance covers cochlear implants and advanced hearing instruments.
- Individuals with Disabilities:Working-age users accessing vocational rehabilitation funding and private insurance. United States Medicaid fragmentation creates state-level coverage variance for augmentative communication devices, distorting manufacturer production planning.
- Educational Institutions:Schools and universities sourcing adaptive software and alternative input devices under accessibility mandates.
- Care Facilities:Nursing homes and assisted living operators purchasing durable medical equipment under group purchasing organization contracts.
Care facilities dominate installed base. Elderly end users are where expansion concentrates.
Technology:
Hardware miniaturization cycles and software update frequencies create mismatched obsolescence timelines across this dimension.
- Wearable Devices:Implantable neurostimulation systems and external sensory aids with real-time neural signal adaptation. Cochlear Limited specializes in merging hardware miniaturization with adaptive algorithms, while EU MDR post-market surveillance mandates are embedding cellular connectivity as standard to maintain active patient registries.
- Augmented Reality:Spatial computing platforms for low-vision enhancement and cognitive assistance. Germany's DiGA fast-track regulation is opening reimbursement pathways for app-based cognitive assistive tools that complement hardware deployment.
- Speech Recognition:Natural language processing engines for command-and-control and dictation applications.
- Eye-Tracking:Gaze-based input systems for users with motor impairment requiring calibration precision specifications.
Speech recognition dominates installed base. Augmented reality is climbing the fastest.
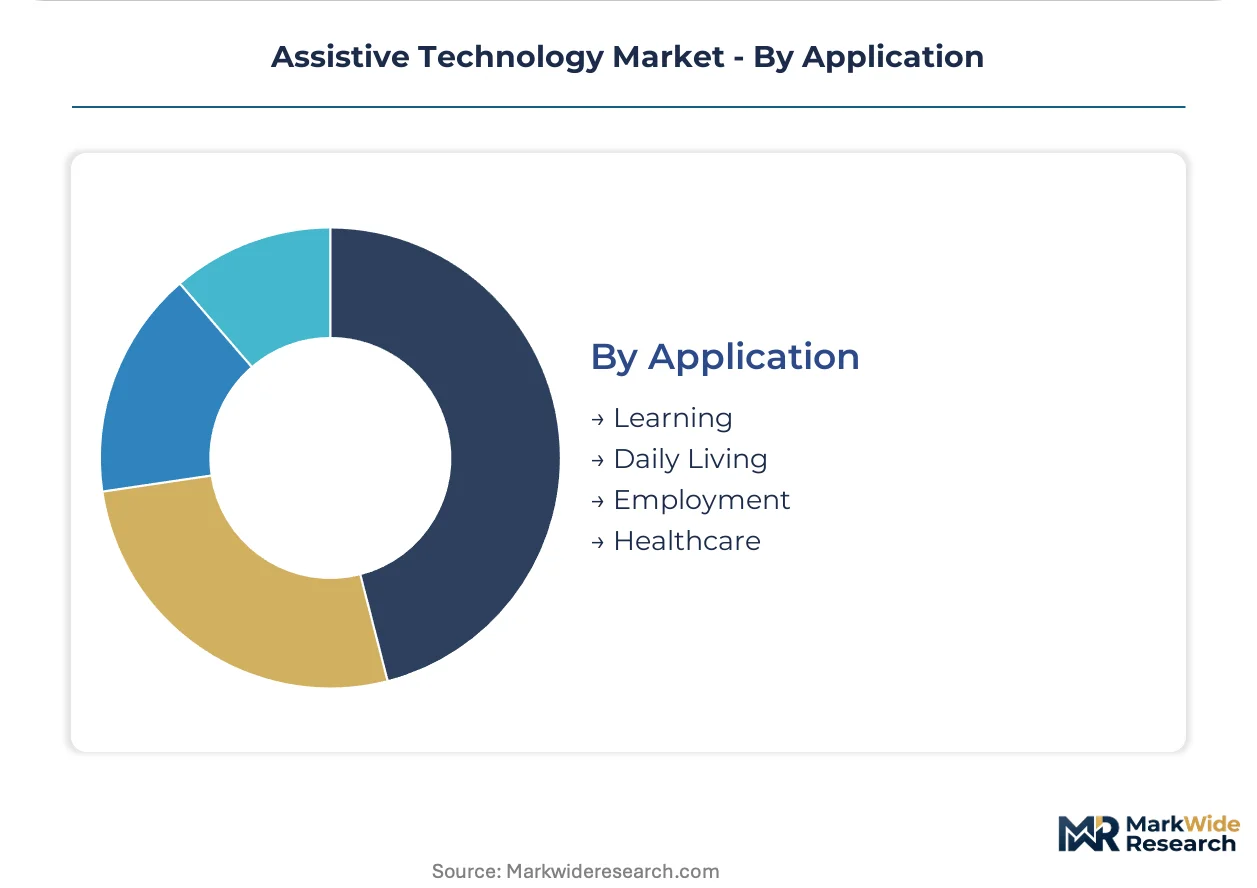
Application:
Reimbursement code consolidation and regulatory classification diverge sharply across medical versus non-medical use cases.
- Healthcare:Clinical settings and home health monitoring where FDA Class II medical device framework and EU MDR impose clinical evidence requirements. Post-market surveillance obligations raise barriers for new entrants while validating premium pricing for compliant manufacturers.
- Daily Living:Independent living aids for meal preparation, hygiene, and environmental control. WHO priority assistive products list is shaping procurement standards in low- and middle-income markets, redirecting donor funding toward wheelchairs and low-vision devices meeting international quality benchmarks.
- Learning:Educational accommodations under disability access mandates.
- Employment:Vocational rehabilitation and workplace accommodation technologies.
Daily living dominates installed base. Healthcare is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Japan deploys sensory augmentation devices at density levels unmatched elsewhere, while India sources basic mobility aids through donor-funded procurement channels that bypass retail distribution entirely.
United States
Veterans Affairs procurement concentrates demand for powered wheelchairs and custom seating through national contracting vehicles that eliminate regional distributor layers. FDA Breakthrough Device Designation accelerates neurostimulation and brain-computer interface approvals. The Minneapolis-St. Paul corridor anchors complex rehabilitation technology manufacturing with direct-to-VA field service deployment.
Germany
Statutory health insurance covers cochlear implants and advanced hearing instruments, creating predictable reimbursement for premium sensory devices. EU MDR harmonization enables cross-border recognition of clinical evidence standards. The Tübingen-Stuttgart cluster concentrates hearing instrument R&D alongside university audiology research programs.
Japan
The world's oldest population expands installed base for mobility aids and hearing devices at per-capita rates exceeding any major economy. METI procurement guidelines prioritize domestic supplier qualification for public sector purchases. The Kanto region around Tokyo hosts concentrated manufacturing of powered mobility devices aligned with elder-care facility specifications.
India
WHO priority assistive products list alignment unlocks donor-funded procurement for low-cost hearing aids and manual wheelchairs in underserved rural districts. The central government's national health mission channels funding through state-level distribution networks. Gujarat and Maharashtra host emerging manufacturing clusters for basic mobility aids serving domestic and export markets.
United Kingdom
NHS procurement consolidation for hearing services creates volume concentration that favors suppliers with national fitting network coverage. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, adding compliance complexity for cross-channel suppliers. The Southeast England corridor maintains hearing instrument distribution hubs serving the combined NHS and private audiology channels.
Assistive Technology Market Vendor Landscape
Capability concentration sits with specialized implantable device manufacturers; scale advantage sits with diversified hearing instrument and mobility aid producers. The market structures around three tiers: premium implantable neurostimulation specialists, mid-tier hearing instrument manufacturers competing on algorithmic signal processing, and value-tier mobility aid suppliers serving institutional procurement. Dominant competitive moves include M&A to capture audiology clinic networks and vertical integration into preventive maintenance services.
Within the premium implantable tier, Cochlear Limited exemplifies hardware miniaturization merged with real-time neural adaptation capabilities. Sonova Holding AG and GN Store Nord occupy positions at the algorithmic personalization frontier, where proprietary fitting software locks professional channels into recurring revenue ecosystems. These three anchors demonstrate how competitive advantage migrates from mechanical engineering toward data platform ownership and patient lifetime value capture.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sonova Holding AG |
| Medline Industries |
| Ottobock SE & Co. KGaA |
| GN Store Nord |
| Cochlear Limited |
| Permobil |
| Sunrise Medical |
| Demant |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's lithium-ion cathode processing facilities is compressing input costs for powered mobility manufacturers while simultaneously exposing them to export restriction volatility that reshapes pricing posture across tiers.
Pricing Analysis
Long-term service contracts dominate the premium tier, with manufacturers bundling preventive maintenance and software subscriptions into multi-year patient agreements that lock in recurring revenue. Three-tier pricing structure across premium, standard, and economy levels separates FDA Breakthrough Device Designation holders from MDR-compliant mid-tier suppliers and basic WHO-list-aligned products. Cost compression in the economy tier is intensifying because donor-funded procurement in India and state-level Medicaid fragmentation in the United States concentrate buyer power. Educational institutions and rural Indian distributors exhibit the highest price sensitivity; Veterans Affairs national contracting vehicles and German statutory health insurance demonstrate the least.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment are constraining flows of neural signal processing chips critical to next-generation cochlear implants and brain-computer interfaces. Component supply concentrates in China for lithium-ion battery systems, Germany for precision sensor modules, and the United States for FDA-regulated neurostimulation firmware. Critical dependencies include rare earth magnets for hearing aid miniaturization, medical-grade titanium for implantable housings, and specialized ASICs for real-time acoustic processing. Single-source vulnerability around Chinese cathode material processing threatens production continuity for powered wheelchair manufacturers. Distribution runs through audiology clinic networks for hearing instruments, direct-to-facility deployment for VA procurement, and state-level health mission channels for Indian rural penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Breakthrough Device Designation and EU MDR harmonization are accelerating neurostimulation approvals, creating a regulatory inflection that rewards pre-certified platforms with compressed time-to-market.
For Market Incumbents: Harden software ecosystem lock-in by embedding proprietary fitting algorithms that require ongoing subscription access, insulating against direct-to-consumer disintermediation. Deepen backward integration into lithium-ion battery cell production to reduce exposure to Chinese export restriction volatility. Prioritize certification investment in Germany's DiGA fast-track pathway for cognitive assistive applications.
For New Entrants and Emerging Players: Augmentative communication devices for working-age vocational rehabilitation users in fragmented Medicaid states represent the most penetrable entry point, as coverage variance creates service gaps that agile software-first competitors can exploit. AR-vision platforms for low-vision enhancement in German statutory health insurance reimbursement channels offer secondary white-space. A hospital system partnership model bypassing traditional distributor networks provides the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across app-based cognitive assistive tools as cloud infrastructure commoditizes development costs, shifting returns toward software-heavy business models. Target audiology clinic networks with captive patient bases and established reimbursement relationships for acquisition, as these channel assets appreciate under consolidated purchasing trends. Monitor FDA cybersecurity guidance enforcement timelines as the critical signal for certification cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Early alignment with CMS Medicare coverage expansion and VA national contracting vehicles secures volume commitments before competitor qualification. |
| Software Companion Development | DiGA-compliant cognitive assistive apps in Germany unlock parallel reimbursement streams that complement hardware revenue. |
| Hospital System Partnership | Direct relationships with NHS procurement consolidation in the United Kingdom bypass distributor margin extraction. |
| CE Marking Pathway | EU MDR post-market surveillance mandates favor manufacturers with embedded cellular connectivity infrastructure. |
| Backward Integration | In-house lithium-ion cell production reduces exposure to Chinese cathode material export restrictions. |
Methodological Framework
A standing panel of rehabilitation technology procurement officers, biomedical engineers at Veterans Affairs medical centers, audiology clinic practice managers, and GPO contracts administrators provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) and Breakthrough Device Designation filings, CMS Medicare reimbursement code databases, EU MDR notified body approval registries, and METI procurement guideline publications. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Scenario-bracketing around regulatory approval timelines, reimbursement code consolidation trajectories, and lithium-ion supply disruption probabilities framed the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, application setting, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to installed base turnover rates and expansion coefficients across elderly demographic projections. Forecast inputs incorporated WHO priority assistive products list adoption curves and state-level Medicaid coverage variance indices.
Practitioners should monitor FDA cybersecurity guidance finalization, EU MDR notified body capacity constraints, and Chinese rare earth export policy shifts for early signals requiring forecast revision. Forecasts reflect assumptions about continued Medicare coverage expansion and VA procurement consolidation. Material shifts in lithium-ion supply chain configuration or breakthrough neurostimulation regulatory pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Global Robotics Market