
 Handheld Robotics Market | 2026-2036
Handheld Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Robotics Market Foresight
Skilled surgical robotics operators is rotating from general laparoscopy toward handheld-assisted microsurgery, tightening labor pools in advanced healthcare systems. ABB leverages its automation heritage to anchor European hospital networks with precision gripper platforms. FANUC sustains manufacturing-scale advantages in Japan's industrial robotics corridors. Yaskawa Electric differentiates through sensor-integrated control architectures for delicate tissue handling.
Handheld robotics denotes compact, operator-guided manipulator systems integrating force-feedback sensors, servo-actuated joints, and wireless command interfaces for direct human-robot collaboration in constrained workspaces. These devices typically operate at sub-kilogram payloads with millimeter-scale repeatability, enabling precise intervention across surgical suites and factory floors. Exoskeletons occupy mature rehabilitation segments where reimbursement pathways stabilize margins, while robotic grippers capture expanding value in minimally invasive surgery where instrument dexterity commands premium pricing. AI-enabled control systems represent the fastest-expanding technology layer, though sensor integration retains the deepest installed base across manufacturing applications.
FDA device classification frameworks govern surgical handheld robotics through 510(k) and De Novo pathways in the United States, while the EU AI Act imposes conformity obligations on autonomous surgical decision support. ISO 13485 quality management standards and IEC 60601 electrical safety requirements shape product development timelines and market access costs across both jurisdictions. Stakeholders must weigh regulatory premarket investment against the pace of algorithmic capability gains in competing systems.
Market Dynamics
The EU AI Act's conformity obligations for autonomous surgical decision support are compressing product development timelines while elevating compliance costs across European hospital procurement cycles.
Growth Catalysts
- Minimally Invasive Surgery Expansion:Surgical suites in Germany's precision manufacturing clusters around Stuttgart and Munich are prioritizing instrument dexterity in procurement specifications.
- EU AI Act Compliance Pathways:The regulation's risk-based classification for medical devices is creating standardized validation frameworks that accelerate hospital network adoption.
- Force-Feedback Sensor Maturation:Sub-kilogram payload systems with millimeter-scale repeatability are enabling direct human-robot collaboration in constrained surgical workspaces.
Market Restraints
- Premarket Regulatory Investment Burden:FDA 510(k) and De Novo pathways impose multi-year timelines and substantial capital requirements before commercialization.
- ISO 13485 Certification Complexity:Quality management system audits create bottlenecks for smaller manufacturers seeking market access.
- IEC 60601 Electrical Safety Compliance:Testing protocols for wireless command interfaces add development cost layers that disadvantage emerging entrants.
Strategic Opportunities
- Rehabilitation Exoskeleton Reimbursement Stabilization:Mature segments with established payment pathways offer margin predictability absent from emerging surgical applications.
- AI-Enabled Control System Convergence:Integration of sensor architectures with algorithmic capability gains creates premium pricing power in tissue handling applications.
- Japan's Industrial Robotics Corridors:Manufacturing-scale advantages in precision actuator production offer supply chain anchoring potential for handheld platform vendors.
Industry Challenges
- Skilled Operator Pipeline Constraints:Surgical teams rotating from general laparoscopy toward handheld-assisted microsurgery are tightening labor availability in advanced healthcare systems.
- Algorithmic Validation Bottlenecks:Demonstrating safety and efficacy for autonomous decision support functions prolongs regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Robotics Market |
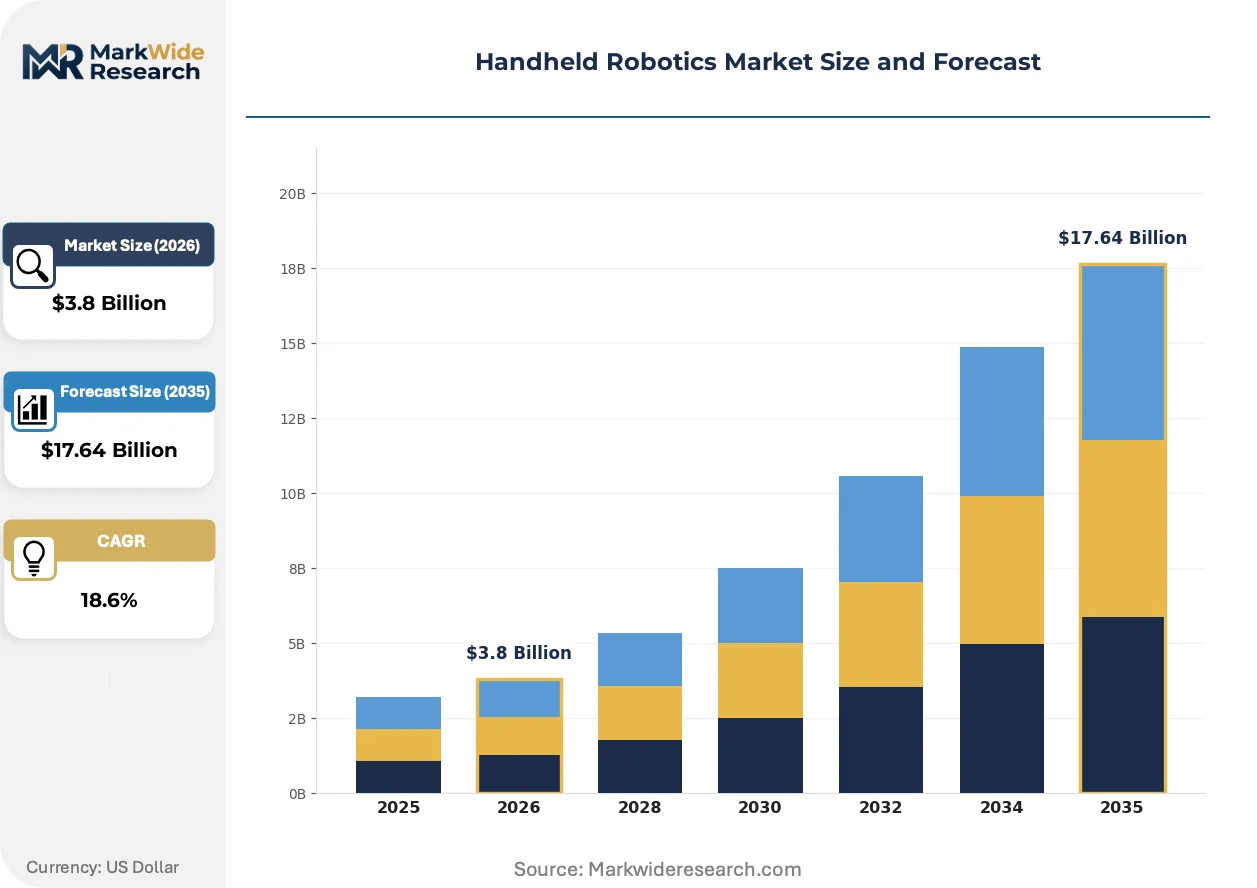
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Robotic Arms, Grippers, Drones Application: Manufacturing, Healthcare, Agriculture, Defense End User: OEMs, Hospitals, Farms, Research Institutions Technology: AI, Machine Learning, Sensor Integration, Wireless Control |
| Companies Covered | ABB, FANUC, Yaskawa Electric, KUKA, Universal Robots, DENSO, Seiko Epson, Schunk, Robotiq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Robotics Market Shifts & Advancements
Control architectures are converging with sensing modalities to enable real-time tissue response, while regulatory frameworks harden around algorithmic transparency requirements.
Haptic feedback interfaces are supplanting traditional joystick-based command systems in microsurgical applications. Tertiary care centers in Germany and Switzerland are adopting these platforms at accelerating rates. The shift is compressing training timelines for complex procedures while reducing cognitive load during delicate tissue manipulation.
The EU AI Act's high-risk system obligations are reshaping clinical validation requirements for surgical decision support modules. Manufacturers must now document algorithmic decision pathways with interpretability standards that exceed prior CE marking thresholds. European hospital procurement committees are prioritizing vendors with established conformity assessment records.
Service unbundling is fragmenting traditional capital equipment sales models. Leasing arrangements with per-procedure fees are displacing outright purchase contracts in hospital networks facing budget constraints. This pattern is most visible in German precision manufacturing clusters where Stuttgart-based health systems are piloting outcome-linked payment structures.
Handheld Robotics Market Segmentation
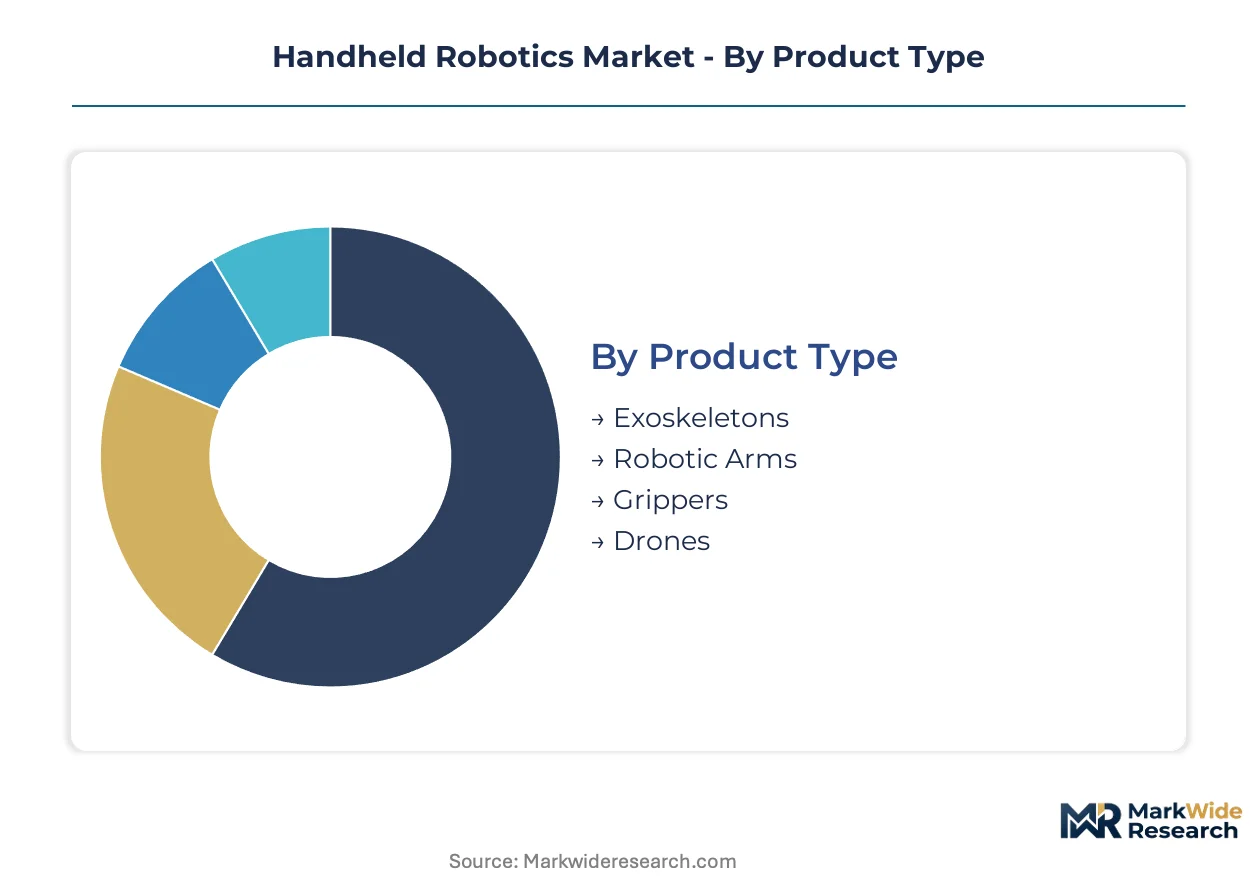
Segmentation in handheld robotics reveals divergent commercial logics across product architectures and deployment contexts. Product type determines payload specifications and regulatory pathways. Application focus shapes sensor integration requirements and procurement cycles. Understanding these divides clarifies where capital concentrates versus where margins compress.
Product Type:
Domestic demand concentrates in surgical grippers across German precision clusters, while exoskeletons and drones follow export-led patterns into North American rehabilitation and Asian agricultural markets.
- Exoskeletons:Powered wearable frames with servo-actuated joints support gait rehabilitation and load-bearing logistics. Demand concentrates in US Veterans Affairs hospital networks and Japanese manufacturing facilities where reimbursement pathways and aging workforce policies stabilize procurement volumes.
- Robotic Arms:Compact articulated manipulators with sub-kilogram payloads enable precision assembly and microsurgical intervention. Stuttgart-based OEMs and Munich-area surgical suites drive domestic absorption, while export sales target Taiwanese electronics contract manufacturers seeking dexterity upgrades.
- Grippers:Force-feedback end-effectors with millimeter-scale repeatability dominate minimally invasive surgical suites. The EU AI Act's high-risk system obligations are elevating validation costs for autonomous tissue handling variants.
- Drones:Aerial platforms with wireless command interfaces serve crop monitoring and tactical reconnaissance. Agricultural deployment concentrates in Australian broadacre farming operations and Brazilian soybean belts where terrain scale favors airborne coverage.
Grippers command the established base. The steepest expansion runs through robotic arms.
Application:
Cost tier stratification separates capital-intensive healthcare deployments from volume-driven manufacturing integrations, with agriculture and defense occupying intermediate investment bands.
- Manufacturing:Precision assembly and quality inspection applications leverage force-feedback architectures for delicate component handling. German automotive suppliers in Baden-Württemberg embed these systems into flexible production cells where lot sizes contract and retooling frequency rises.
- Healthcare:Surgical suites and rehabilitation centers demand ISO 13485-certified platforms with IEC 60601 electrical safety documentation. Swiss tertiary hospitals and Dutch academic medical centers prioritize vendors with established EU AI Act conformity assessment records.
- Agriculture:Crop monitoring and selective harvesting applications favor ruggedized sensor-integrated platforms. Israeli drip-irrigation technology providers and Dutch greenhouse operators drive adoption in controlled-environment settings.
- Defense:Tactical reconnaissance and explosive ordnance disposal require hardened wireless command interfaces with jam-resistant protocols. Procurement concentrates in national security budgets with multi-year development timelines.
Healthcare absorbs the premium tier. Manufacturing delivers volume scale.
End User:
Customer type determines procurement sophistication, with hospitals and research institutions demanding full regulatory documentation while farms and OEMs prioritize total cost of ownership.
- OEMs:Industrial equipment manufacturers integrate handheld robotics as subsystems within larger capital goods. German machine tool builders around Stuttgart source precision grippers for incorporation into automated assembly lines exported globally.
- Hospitals:Surgical suites and rehabilitation departments require clinical validation data and training infrastructure. Procurement committees in Munich and Cologne health systems evaluate algorithmic transparency documentation under EU AI Act high-risk system obligations.
- Farms:Agricultural operators prioritize field durability and minimal maintenance intervals. Australian wheatbelt cooperatives and Brazilian soybean producers drive demand for weather-resistant aerial platforms.
- Research Institutions:Academic and government laboratories tolerate longer integration cycles in exchange for customization flexibility. ETH Zurich and TU Munich robotics departments anchor European R&D demand for experimental control architectures.
Hospitals anchor the premium segment. Research institutions enable technology transfer.
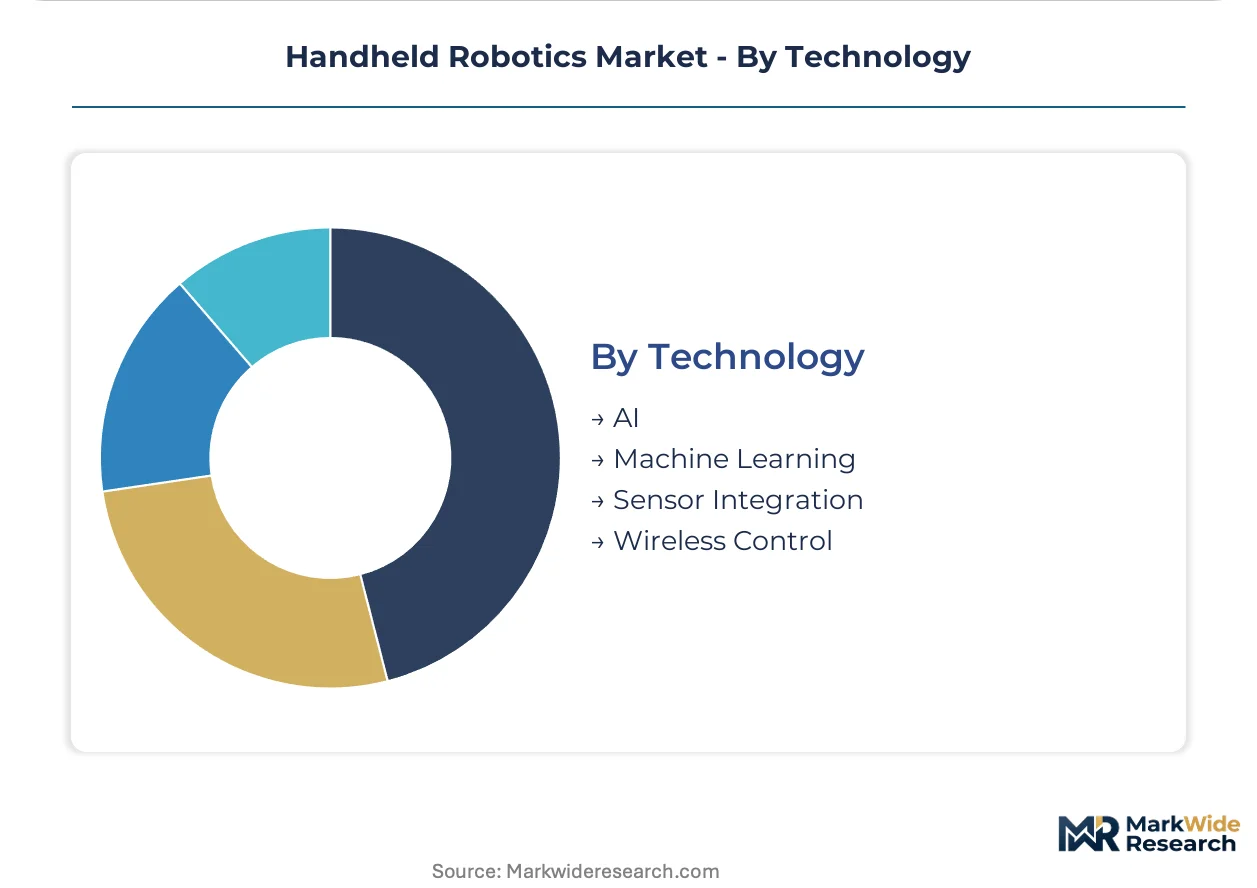
Technology:
Technology maturity curves separate established sensor integration from emerging AI control layers, with wireless protocols occupying an intermediate deployment phase.
- AI:Algorithmic decision support modules for autonomous tissue response and adaptive gripping force. EU AI Act interpretability requirements are extending validation timelines for surgical applications beyond prior CE marking thresholds.
- Machine Learning:Pattern recognition systems for defect detection and crop health assessment. German precision manufacturing clusters deploy these for inline quality verification where training data availability exceeds healthcare constraints.
- Sensor Integration:Force, torque, and proximity sensing arrays with real-time feedback loops. This layer retains the deepest installed base across manufacturing applications where millimeter-scale repeatability predates autonomous decision support.
- Wireless Control:Command interfaces enabling operator mobility and multi-device coordination. IEC 60601 testing protocols for surgical applications add development cost layers that disadvantage emerging entrants.
Sensor integration commands the established base. AI-enabled control systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks deploy handheld robotics for precision microsurgery, while Japanese automotive suppliers integrate force-feedback grippers into flexible assembly cells. This consumption-mix differential separates healthcare-intensive European adoption from manufacturing-led Asian deployment patterns.
United States
Veterans Affairs hospital networks and private surgical centers drive demand for haptic-enabled microsurgical platforms. FDA 510(k) and De Novo pathways govern device classification, compressing premarket timelines for established manufacturers. Minneapolis-based medical technology clusters anchor rehabilitation exoskeleton development, with procurement concentrating in Midwest tertiary care systems.
Germany
Stuttgart and Munich precision manufacturing clusters absorb robotic grippers for automotive component assembly and minimally invasive surgical suites. EU AI Act conformity obligations elevate validation costs for autonomous tissue handling systems. Baden-Württemberg health systems pilot outcome-linked leasing structures, displacing traditional capital equipment purchases.
Japan
Aging workforce policies and automotive export demand sustain industrial robotics corridors around Nagoya and Osaka. METI standards shape sensor-integrated control architecture development. FANUC and Yaskawa Electric anchor domestic precision actuator supply chains, feeding handheld platform vendors across Kanto and Kansai manufacturing belts.
Switzerland
Swissmedic regulations and ISO 13485 certification requirements position Zurich and Geneva as validation hubs for European market entry. ETH Zurich robotics departments drive experimental control architecture R&D. Tertiary hospitals in Basel and Lausanne prioritize vendors with established EU AI Act interpretability documentation.
South Korea
Seoul Capital Area electronics contract manufacturers deploy compact articulated manipulators for precision assembly retooling. MFDS medical device regulations create parallel compliance tracks for surgical applications. Busan-Ulsan industrial zones source sub-kilogram payload systems from domestic automation suppliers serving Samsung and LG production networks.
Handheld Robotics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital network procurement relationships and the lower tier competing on customization velocity. The structure rewards vertical control over precision actuator supply and regulatory documentation capabilities. Three archetypes dominate: diversified industrial automation conglomerates, medical device specialists with ISO 13485 certification depth, and sensor-integrated control architecture developers. Competitive moves concentrate on M&A for regulatory dossier accumulation and strategic partnerships with German precision manufacturing clusters.
Within the diversified industrial tier, ABB leverages its automation heritage to anchor European hospital networks, while FANUC exemplifies manufacturing-scale advantages in Japanese robotics corridors. Yaskawa Electric occupies a position emphasizing sensor-integrated architectures for delicate tissue handling applications. These three represent contrasting geographic anchoring strategies—Swiss-Swedish, Japanese, and Japanese respectively—each mapping to distinct procurement committee priorities across healthcare and manufacturing verticals.
| Leading Market Players |
|---|
| ABB |
| FANUC |
| Yaskawa Electric |
| KUKA |
| Universal Robots |
| DENSO |
| Seiko Epson |
| Schunk |
| Robotiq |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day component lead times for precision servo actuators tie pricing power directly to Nagoya-Osaka supply chain density, compressing margins for vendors without captive actuator production or long-term offtake agreements with Japanese tier-one suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between German hospital networks and established gripper manufacturers, while spot purchasing governs smaller OEM orders for compact robotic arms. Price differentiation rests on ISO 13485 certification tier and force-feedback sensor density, with EU AI Act interpretability documentation commanding substantial premiums. Pricing pressure intensifies in the standard tier as Taiwanese electronics contract manufacturers consolidate procurement volumes. Research institutions exhibit lowest price sensitivity due to customization requirements, whereas agricultural cooperatives drive hardest bargain on total cost of ownership.
Supply Chain Analysis
Shin-Etsu Chemical's silicon wafer facilities outside Nagoya constitute a critical chokepoint for force sensor substrate supply, with any disruption rippling through Stuttgart and Munich precision manufacturing clusters within weeks. Manufacturing concentrates in Japan, Germany, and South Korea, drawing from rare earth magnet feedstocks anchored in Chinese processing facilities and Swiss MEMS foundry output. Single-source vulnerability runs through precision harmonic drive gearing where HDSI's Hamamatsu facilities supply multiple competing gripper OEMs. Distribution runs through German machine tool builders for industrial applications and GPO contracts for US hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Handheld robotics sits in early-cycle expansion as EU AI Act standardization creates first-mover advantages for conformity-assessed vendors, with reimbursement pathway maturation in rehabilitation exoskeletons providing cash flow anchors for cross-subsidizing surgical platform development.
For Market Incumbents: Consolidate gripper platform architectures around modular sensor-integrated control systems to deflect emerging entrants specializing in narrow AI-enabled tissue handling applications. Deepen backward integration into precision actuator supply through strategic partnerships with Nagoya-area component houses, securing inventory priority during supply constraints. Accelerate EU AI Act technical documentation dossiers to capture German hospital procurement committee preference for established conformity records. For New Entrants and Emerging Players: Differentiate on haptic feedback algorithm specialization for microsurgical applications where incumbent platforms retain joystick-legacy interfaces. Target Australian agricultural drone deployments as the most penetrable geography, where terrain scale favors airborne coverage and incumbent medical-focused vendors maintain limited presence. Pursue direct-to-farm sales models bypassing traditional industrial distribution channels. For Investors and Strategic Acquirers: Long-term, this sits as a medical-device convergence play because surgical robotics and industrial automation control architectures are collapsing toward common sensor-integrated platforms. Acquisition targets should emphasize ISO 13485-certified developers with interpretable AI documentation pipelines rather than pure-play hardware vendors. Watch FDA De Novo submission velocity as the critical inflection signal for autonomous tissue handling capability maturation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Accelerates hospital network procurement in Stuttgart and Munich precision clusters. |
| Precision Actuator Backward Integration | Secures supply priority from Nagoya-Osaka manufacturing corridors during constraint periods. |
| Rehabilitation Exoskeleton Reimbursement Strategy | Stabilizes cash flows through US Veterans Affairs and Japanese aging workforce policies. |
| Hospital System Outcome-Linked Leasing | Displaces capital purchase models in Baden-Württemberg health system pilots. |
| Haptic Feedback Platform Integration | Compresses training timelines for Swiss tertiary care microsurgical adoption. |
Research Methodology
The analysis maps surgical grippers, rehabilitation exoskeletons, and precision assembly robotic arms, each validated through hospital procurement committee interviews, biomedical engineering directors, GPO contracts managers, and precision manufacturing OEM sourcing leads. Secondary sources include FDA 510(k) and De Novo filing databases, EU AI Act technical documentation registries, hospital procurement databases, and German automotive supplier SEC disclosures. Bottom-up unit demand estimates triangulate against top-down healthcare capital expenditure and industrial automation investment flows.
Consistency checks validate volume and value outputs against precision actuator production disclosures from Japanese robotics corridors and EU medical device import statistics. Segmentation models incorporate product architecture, application vertical, end-user procurement sophistication, and technology maturity layer across the projection horizon. CAGRs derive from procedure volume growth in minimally invasive surgery, workforce aging demographics, and manufacturing lot size contraction trends. Force-feedback sensor cost curves and wireless protocol certification timelines feed directly into adoption elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or reimbursement pathway stability would require recalibration. Forecasts reflect assumptions regarding clinical validation timeline compression and algorithmic interpretability standard convergence. Practitioners should keep alternative scenarios live as FDA De Novo pathway velocity and Japanese actuator supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
AI Assisted Robots Market