
 Wearable Patch Market | 2026-2036
Wearable Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Patch Market Intelligence
Hospital procurement consortiums is reconfiguring how wearable patch vendors secure long-term supply contracts across integrated delivery networks. Abbott Laboratories leverages in-house sensor fabrication to control unit economics for continuous glucose systems. DexCom sustains R&D intensity through dedicated manufacturing facilities that anchor its position in ambulatory glucose monitoring. iRhythm Technologies specializes in algorithm-driven cardiac event detection, differentiating its service model from hardware-centric rivals.
A wearable patch integrates flexible substrate electronics with biocompatible adhesives to enable non-invasive physiological data acquisition over extended wear periods, typically functioning through Bluetooth or NFC transmission protocols to relay metrics such as cardiac rhythm, glucose levels, or motion patterns to centralized monitoring platforms. Smart patches now lead product type revenue contribution due to embedded microprocessor capabilities that support real-time analytics at the edge, while therapeutic patches represent the fastest-expanding category as pharmaceutical companies pursue transdermal delivery alternatives to oral dosing regimens. Biometric patches command margin concentration in professional settings where FDA-cleared accuracy thresholds justify premium positioning against consumer-grade fitness alternatives.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines, with the former governing 510(k) clearances for cardiac and glucose monitoring patches and the latter imposing post-market surveillance obligations across European Economic Area distribution. Japan's PMDA enforces localized clinical data requirements that extend registration cycles for foreign manufacturers seeking reimbursement listing under the national health insurance framework. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC standards committees as connected patch architectures expand attack surfaces for healthcare delivery organizations.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing wearable patch vendors to restructure pricing and service models around multi-year enterprise agreements rather than transactional device sales.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for cardiac and glucose monitoring patches compress time-to-market for novel sensor technologies, incentivizing R&D investment in algorithm-driven diagnostic platforms.
- Chronic Disease Management Protocols:Hospital networks in the United States, Germany, and Japan now mandate continuous glucose monitoring patches as standard ambulatory care, embedding hardware into reimbursement frameworks.
- EU MDR Compliance Timelines:Post-market surveillance obligations under the Medical Device Regulation are raising clinical validation standards, filtering out undercapitalized entrants and concentrating market position among established players with robust quality systems.
Market Restraints
- Silver Nanoparticle Cost Volatility:Conductive ink formulations depend on precious metal supply chains concentrated in South American mining operations, exposing manufacturers to input price swings that compress gross margins on disposable patch components.
- Biocompatible Adhesive Supply Concentration:Three specialty chemical suppliers dominate medical-grade silicone acrylate production, creating single-source vulnerability for patch manufacturers scaling output.
- Skin Irritation Thresholds:Extended wear periods beyond fourteen days trigger dermatological adverse events that limit patient compliance and narrow addressable populations for metabolic monitoring applications.
Strategic Opportunities
- Transdermal Drug Delivery Convergence:Therapeutic patches combining biosensing with active pharmaceutical ingredient release represent unpenetrated white space as pharmaceutical companies seek alternatives to oral dosing regimens for biologics.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of electronics components create cost-competitive substrate fabrication capacity for export-oriented patch producers.
- Edge Computing Integration:Embedded microprocessor architectures enabling real-time analytics at the patch surface reduce cloud dependency and open remote monitoring applications in bandwidth-constrained rural healthcare settings.
Industry Challenges
- Embedded Firmware Security Certification:FDA and IEC cybersecurity guidance for connected medical devices requires specialized engineering talent scarce outside established hubs in Boston and Basel.
- Multi-Site Clinical Trial Coordination:Japan's PMDA mandates localized physiological data for reimbursement listing, forcing foreign manufacturers to replicate validation studies across three or more domestic hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Patch Market |
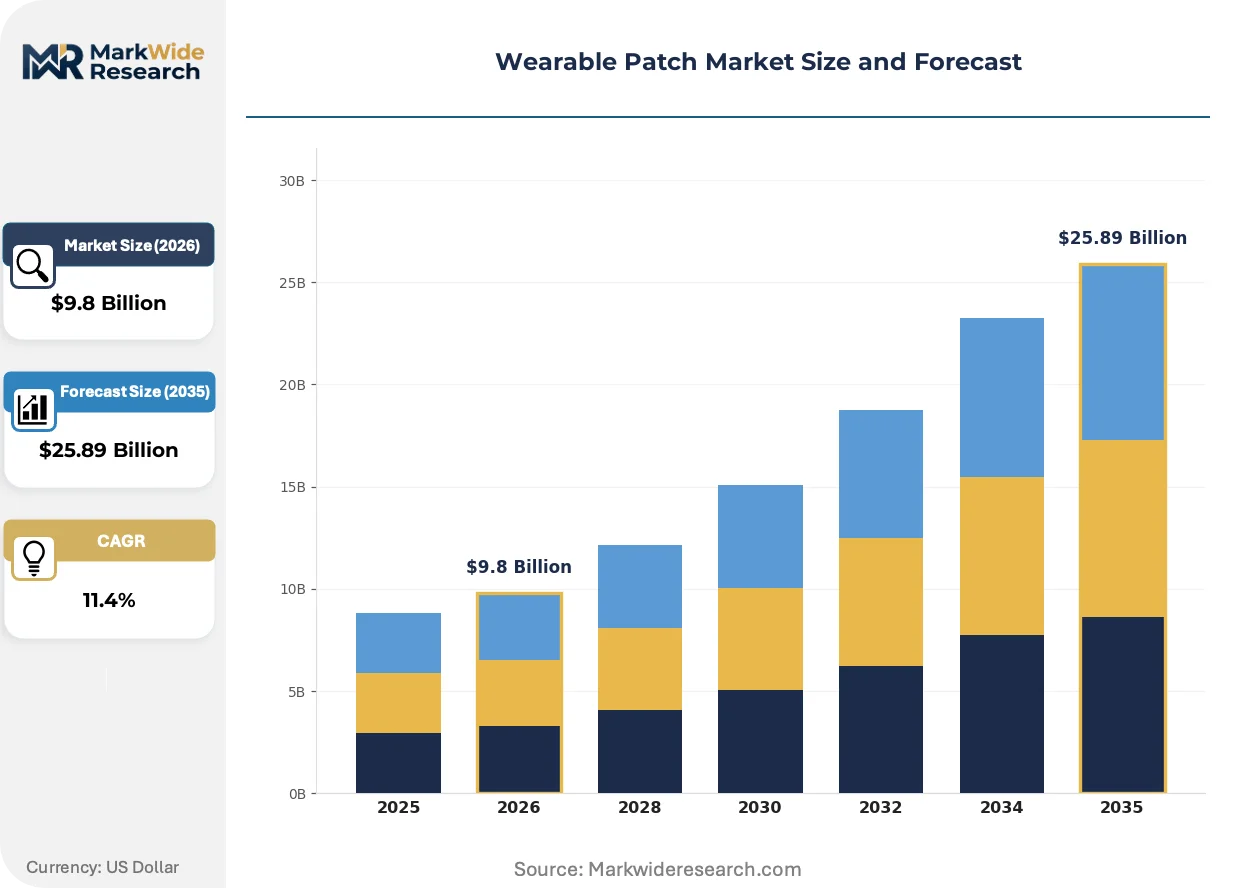
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Patches, Adhesive Patches, Biometric Patches, Therapeutic Patches Application: Health Monitoring, Pain Management, Drug Delivery, Fitness Tracking End User: Clinics, Home Users, Hospitals, Sports Teams Technology: Bluetooth, NFC, RFID, Wireless |
| Companies Covered | iRhythm Technologies, Masimo, Abbott Laboratories, Boston Scientific Corporation, Senseonics, Medtronic, Philips, Texas Instruments, DexCom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Patch Market Strategic Shifts & Innovations
Flexible hybrid electronics are collapsing the boundary between diagnostic and therapeutic modalities, enabling single-patch platforms that simultaneously monitor physiological markers and deliver pharmacological intervention.
Printed graphene electrode arrays are migrating from laboratory prototyping to scaled manufacturing for cardiac event detection patches. Abbott Laboratories and iRhythm Technologies have both qualified roll-to-roll gravure printing processes for high-resolution electrophysiological signal acquisition. This manufacturing shift is compressing unit costs for ambulatory monitoring hardware while maintaining FDA-cleared accuracy thresholds.
The EU MDR's post-market surveillance obligations are forcing patch manufacturers to implement automated adverse event reporting systems integrated with national health registries. Germany's BfArM now requires real-time transmission of skin reaction data for all reimbursed glucose monitoring devices. This regulatory architecture is accelerating investment in predictive dermatological risk algorithms across European Economic Area distribution channels.
Hospital procurement teams are consolidating vendor relationships around full-service partnerships that bundle hardware, algorithm licensing, and clinical decision support. Integrated delivery networks in the United States now prioritize single-source accountability for patient outcomes over lowest-unit-cost sourcing. This behavioral shift is visible most acutely in cardiac monitoring contracts, where multi-year enterprise agreements displace quarterly device purchasing cycles.
Wearable Patch Market Segmentation
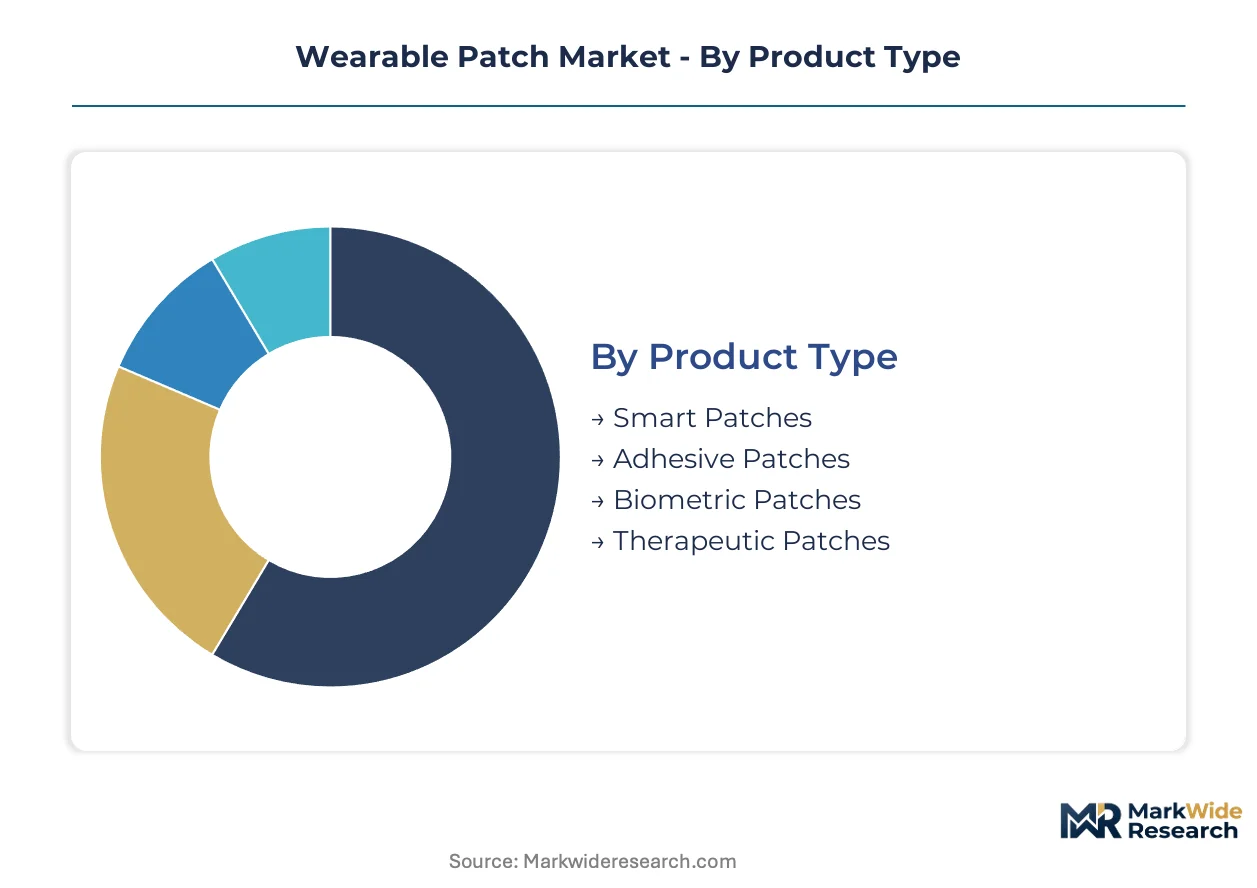
Wearable patch segmentation reveals divergent replacement cycles across product architectures, with disposable adhesive formats turning over in days while embedded sensor platforms persist for years. Procurement teams in hospital networks and consumer channels prioritize different performance tiers, creating parallel demand structures that vendors must address through distinct manufacturing footprints.
Product Type:
Replacement velocity varies dramatically across this category, with single-use disposable formats cycling in under a week and rechargeable diagnostic platforms operating on multi-year depreciation schedules.
- Smart Patches:Embedded microprocessor architectures enable real-time edge analytics for cardiac rhythm and glucose trending without cloud dependency. United States hospital procurement consortiums now mandate these capabilities for enterprise cardiac monitoring contracts, compressing margins for hardware-only vendors.
- Therapeutic Patches:Transdermal drug delivery substrates combine biosensing with active pharmaceutical ingredient release for biologics administration. Pharmaceutical companies in Germany and Japan are advancing clinical programs for hormone and pain management applications, creating unpenetrated white space beyond diagnostic monitoring.
- Adhesive Patches:Single-use disposable substrates with conductive ink traces dominate glucose monitoring volumes through lower unit economics and simplified supply chains.
- Biometric Patches:FDA-cleared accuracy thresholds for professional settings command premium positioning against consumer-grade fitness alternatives in ambulatory care networks.
Adhesive patches anchor the volume base while therapeutic patches gain share at the steepest rate.
Application:
Clinical validation requirements and reimbursement maturity create sharp cost tier differentiation across use cases, with regulated medical indications commanding five-fold price multiples over wellness-oriented fitness tracking.
- Health Monitoring:Continuous cardiac and metabolic surveillance for chronic disease management in United States, German, and Japanese hospital networks. EU MDR post-market surveillance obligations now mandate automated adverse event reporting for reimbursed glucose devices in Germany.
- Drug Delivery:Transdermal administration of biologics and small molecules bypassing hepatic first-pass metabolism. Japan's PMDA localized clinical data requirements extend registration cycles for foreign manufacturers seeking national health insurance reimbursement listing.
- Pain Management:Lidocaine and opioid alternative patches for post-operative and chronic pain protocols in ambulatory surgical centers.
- Fitness Tracking:Consumer-grade motion and biometric sensing without FDA clearance requirements, sold through direct-to-consumer channels and sporting goods retail.
Health monitoring commands the revenue concentration while drug delivery climbs the fastest as pharmaceutical pipelines mature.
End User:
Procurement authority and reimbursement pathway maturity determine customer segmentation, with integrated delivery networks consolidating purchasing power while home users remain fragmented across direct-to-consumer channels.
- Hospitals:Multi-year enterprise agreements for cardiac and glucose monitoring now displace quarterly device purchasing cycles in United States integrated delivery networks. Abbott Laboratories and iRhythm Technologies compete for algorithm-driven diagnostic platform contracts with bundled clinical decision support.
- Home Users:Direct-to-consumer glucose monitoring and fitness tracking applications bypass institutional procurement, with DexCom sustaining R&D intensity through dedicated manufacturing facilities.
- Clinics:Ambulatory care centers with intermediate reimbursement pathways for diagnostic monitoring between hospital and home settings.
- Sports Teams:Performance optimization and injury prevention applications without regulatory clearance requirements, serving professional and collegiate athletic programs.
Hospitals concentrate purchasing volume while home users expand most quickly as reimbursement broadens for ambulatory glucose monitoring.
Technology:
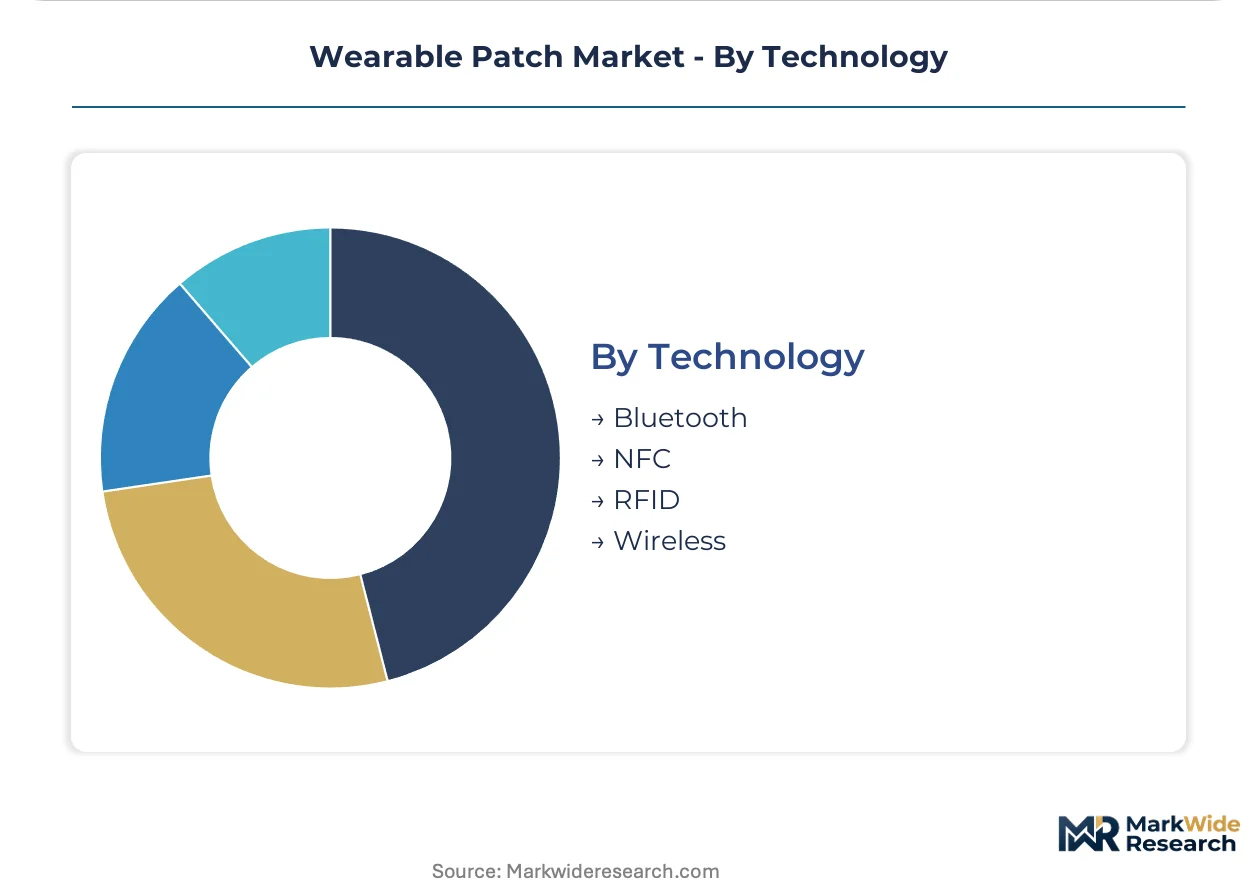
Transmission protocol selection drives power consumption, security architecture, and interoperability requirements, with Bluetooth dominating continuous monitoring while NFC serves single-scan diagnostic applications.
- Bluetooth:Continuous low-energy transmission for real-time cardiac and glucose data streaming to centralized monitoring platforms. FDA and IEC cybersecurity guidance for connected medical devices requires specialized firmware engineering talent concentrated in Boston and Basel.
- Wireless:Proprietary radio frequency protocols enabling extended range transmission for rural healthcare settings with limited cellular infrastructure.
- NFC:Near-field communication for single-scan glucose and medication adherence verification without battery requirements.
- RFID:Passive identification and tracking applications for inventory management and patient matching in hospital workflows.
Bluetooth carries the installed base while wireless protocols gain traction for bandwidth-constrained deployment environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific electronics distribution for wearable patch substrate materials, while Rotterdam's Europoort terminal handles EU MDR-compliant device imports into European Economic Area distribution channels.
United States
FDA breakthrough device designations for cardiac and glucose monitoring patches compress regulatory review timelines, incentivizing R&D investment in algorithm-driven diagnostic platforms. Hospital procurement consortiums across integrated delivery networks now mandate multi-year enterprise agreements for continuous glucose monitoring hardware. The Boston-Cambridge corridor concentrates firmware engineering talent for embedded security certification under FDA and IEC cybersecurity guidance.
Germany
BfArM requires real-time transmission of skin reaction data for all reimbursed glucose monitoring devices, accelerating investment in predictive dermatological risk algorithms. EU MDR post-market surveillance obligations filter undercapitalized entrants from European Economic Area distribution. The Rhine-Ruhr metropolitan region hosts specialty chemical suppliers dominating medical-grade silicone acrylate production for biocompatible adhesives.
Japan
PMDA enforces localized clinical data requirements that extend registration cycles for foreign manufacturers seeking national health insurance reimbursement listing. METI production-linked incentives support domestic electronics component fabrication for export-oriented patch producers. The Kansai region around Osaka anchors pharmaceutical company clinical programs for transdermal drug delivery applications.
India
PLI scheme incentives for medical devices manufacturing create cost-competitive substrate fabrication capacity for export-oriented patch producers. CDSCO regulatory harmonization with IMDRF standards accelerates market entry timelines for cardiac monitoring devices. Karnataka's Bengaluru-Tumkur electronics cluster attracts flexible hybrid electronics prototyping facilities serving European and North American device developers.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel sensor technologies while maintaining CE marking recognition for EU market access. NHS integrated care systems pilot continuous ambulatory cardiac monitoring patches in heart failure management protocols. The Cambridge-London corridor concentrates printed graphene electrode array research migrating from laboratory prototyping to scaled manufacturing.
Wearable Patch Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying conductive inks, flexible substrates, and biocompatible adhesives. The vendor base stratifies across three tiers: diversified medical technology conglomerates with captive sensor fabrication, pure-play diagnostic patch developers with algorithm-centric service models, and specialty chemical suppliers controlling adhesive formulation intellectual property. Competitive moves concentrate on backward integration into sensor manufacturing and strategic partnerships bundling hardware with clinical decision support licensing.
Within the diversified medical technology tier, Abbott Laboratories exemplifies platform integration through in-house sensor fabrication control, while DexCom occupies a position emphasizing dedicated manufacturing facility investment. iRhythm Technologies anchors the pure-play diagnostic segment with algorithm-driven cardiac event detection specialization. Among component suppliers, Texas Instruments represents the semiconductor layer enabling embedded microprocessor architectures for edge analytics capability.
| Leading Market Players |
|---|
| iRhythm Technologies |
| Masimo |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Senseonics |
| Medtronic |
| Philips |
| Texas Instruments |
| DexCom |
| Others |
Cost & Logistics Intelligence
Rhine-Ruhr metropolitan region specialty chemical suppliers anchor biocompatible adhesive production, concentrating formulation intellectual property among three dominant players and transmitting pricing power downstream to patch manufacturers negotiating multi-year hospital procurement contracts.
Pricing Analysis
Volume-discount tiering structures separate FDA-cleared biometric patches for professional hospital networks from consumer-grade fitness alternatives and economy disposable glucose monitoring formats. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales algorithm licensing bundling. Cost compression in the adhesive patch segment intensifies because silver nanoparticle input volatility squeezes gross margins on disposable components. Home users exhibit highest price sensitivity while integrated delivery networks prioritize outcome accountability over unit cost minimization.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities have become standard for specialty chemical procurement, with medical-grade silicone acrylate suppliers in Germany, Japan, and the United States anchoring global adhesive formulation capacity. Conductive ink production draws from South American precious metal mining operations, while flexible substrate fabrication concentrates in India's PLI-supported electronics clusters. Single-source vulnerability in biocompatible adhesive supply creates structural risk for scaling manufacturers. Distribution runs through hospital procurement consortiums and direct-to-consumer channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm licensing and clinical decision support subscriptions expand faster than hardware sales, transforming wearable patch economics from transactional device revenue toward recurring service-attach models.
For Market Incumbents: Entrench market position through backward integration into sensor fabrication and captive control of biocompatible adhesive supply chains. Hospital procurement consortiums consolidating purchasing power threaten margin compression for hardware-only vendors unable to bundle algorithm-driven diagnostic platforms with multi-year service agreements. For New Entrants and Emerging Players: Therapeutic patches combining biosensing with transdermal drug delivery represent the most penetrable entry point, with pharmaceutical partnerships in Germany and Japan offering regulatory co-development pathways. Edge computing integration for bandwidth-constrained rural healthcare settings provides differentiated go-to-market positioning against cloud-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core patch manufacturing assets. Long-term viability in this market hinges on software companion development capabilities and reimbursement strategy execution. FDA breakthrough device designation velocity serves as the critical inflection indicator for portfolio allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Abbott Laboratories and iRhythm Technologies leverage accelerated review timelines to compress time-to-market for novel cardiac monitoring platforms. |
| Hospital System Partnership | Integrated delivery networks in the United States now mandate multi-year enterprise agreements bundling hardware with clinical decision support licensing. |
| CE Marking Pathway | EU MDR post-market surveillance obligations filter undercapitalized entrants from European Economic Area distribution channels. |
| Software Companion Development | Embedded microprocessor architectures enabling real-time edge analytics reduce cloud dependency for remote monitoring applications. |
| Reimbursement Strategy | Japan's PMDA localized clinical data requirements extend registration cycles for foreign manufacturers seeking national health insurance listing. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit economics modeling triangulated with top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with CAGRs derived from segment-level replacement cycle velocity and reimbursement pathway maturity trajectories. Modeled dimensions included product architecture durability, clinical validation tier, transmission protocol power requirements, and regional regulatory cluster adoption curves. Forecast inputs incorporated silver nanoparticle cost volatility indices and biocompatible adhesive supplier concentration metrics.
Macroeconomic conditions sit as an overlay; deviation in precious metal commodity prices, healthcare reimbursement policy, or cybersecurity regulatory guidance would shift the trajectory. Forecasts reflect assumptions about hospital procurement consolidation pace and pharmaceutical partnership formation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Sports Headbands Market