
 Wearable Devices Market | 2026-2036
Wearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Devices Market Intelligence
Subscription-based health analytics is restructuring value capture in wearable devices, shifting revenue from hardware transactions to recurring software revenue. Apple leverages its ecosystem integration to sustain premium positioning across smartwatch and health monitor categories. Samsung Electronics anchors Android-compatible wearable distribution through retail channel control and component verticalization. Garmin specializes in GPS-enabled outdoor and aviation segments where ruggedized specifications command durable margin pools.
Wearable devices encompass body-worn electronic systems integrating sensors, wireless transceivers, and embedded software to capture physiological or environmental data with continuous monitoring capability. These systems typically incorporate accelerometers, gyroscopes, and Bluetooth Low Energy modules to transmit biometric streams to paired smartphones or cloud platforms for fitness, medical, or enterprise productivity applications. Smartwatches now dominate value generation as health monitors and fitness trackers converge toward clinical-grade sensing architectures. Hearables represent the fastest-expanding product category as audio devices absorb biometric monitoring and gesture control functionality. Remote patient monitoring applications command the highest margin profiles where FDA-cleared algorithms justify reimbursement and enterprise contracting.
FDA Software as a Medical Device frameworks and HIPAA interoperability standards shape product development roadmaps and market access requirements for clinical-grade wearables in the United States. FCC Part 15 regulations govern radiofrequency emissions across Bluetooth and Wi-Fi connectivity modules, while EU MDR and GDPR compliance determine CE marking eligibility for European distribution. Stakeholders must monitor evolving reimbursement codes and data sovereignty requirements as health systems integrate wearable-derived biomarkers into formal care pathways.
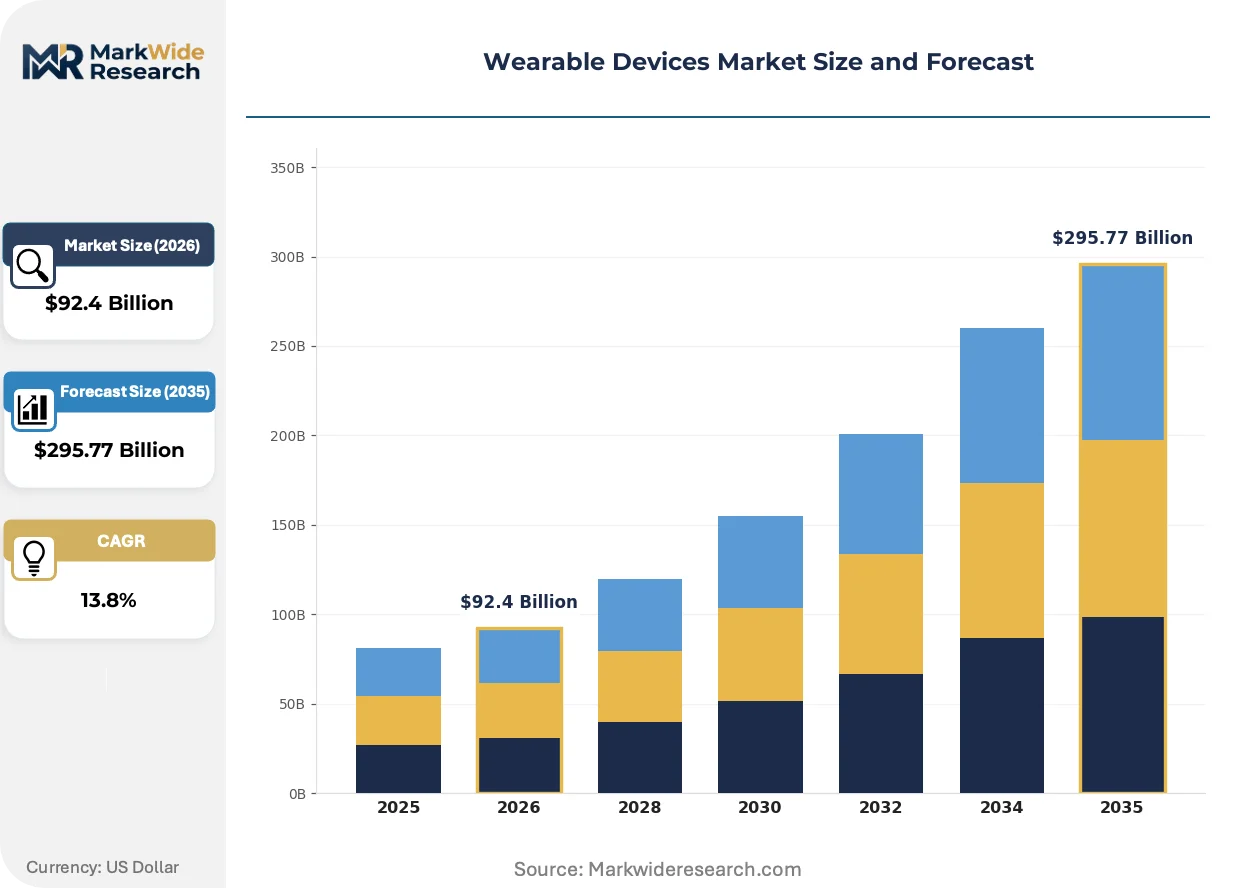
Market Dynamics
Subscription-based health analytics is restructuring value capture in wearable devices, shifting revenue from hardware transactions to recurring software revenue and forcing incumbents to rebuild their monetization architectures around longitudinal patient data relationships.
Growth Catalysts
- FDA SaMD Pathways:Accelerated FDA clearance for Software as a Medical Device compresses clinical-grade feature deployment timelines for remote patient monitoring applications in the United States.
- Employer Wellness Mandates:United States enterprises facing rising healthcare premiums expand wearable procurement as preventive health infrastructure, sustaining enterprise volume commitments.
- Decentralized Care Delivery:Healthcare systems prioritize remote patient monitoring to reduce acute care utilization, pulling clinical-grade sensing into outpatient workflows.
Market Restraints
- Sensor Supply Concentration:MEMS accelerometer and optical heart rate module production concentrates among Asian contract manufacturers, creating single-source vulnerability for mid-tier device vendors.
- Reimbursement Code Gaps:CMS and private payor coverage for wearable-derived biomarkers remains fragmented, limiting clinical adoption beyond pilot contracts.
- Battery Chemistry Constraints:Lithium-polymer cell energy density plateaus constrain always-on sensing architectures, forcing tradeoffs between form factor and monitoring frequency.
Strategic Opportunities
- Underpenetrated Rural Health Networks:Federally Qualified Health Centers in the United States lack remote monitoring infrastructure, creating whitespace for clinical-grade wearable deployment.
- Hearable Biometric Convergence:Audio devices integrating photoplethysmography and inertial measurement open new form factors beyond wrist-worn architectures.
- HIPAA Interoperability Mandates:Regulatory pressure for health data portability creates competitive advantage for platforms with native electronic health record integration.
Industry Challenges
- FDA 510(k) Timeline Compression:Clinical validation requirements for novel sensing modalities extend clearance cycles, consuming R&D runway for algorithm-dependent features.
- Biomedical Engineering Talent Scarcity:Shortage of professionals bridging hardware design, signal processing, and clinical validation slows product pipeline velocity.
- Legacy Health IT Integration:Hospital systems running outdated HL7 interfaces require costly middleware development to ingest wearable data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Devices Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $295.77 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors, Hearables Technology: Bluetooth, Wi-Fi, NFC, GPS, Accelerometer, Gyroscope Application: Fitness Tracking, Remote Patient Monitoring, Gesture Control, Navigation, Sleep Analysis End User: Consumers, Sports Enthusiasts, Medical Practitioners, Corporate Employees, Military Personnel |
| Companies Covered | Fitbit, WHOOP, Apple, Huami, Amazfit, Samsung Electronics, Oura, BoAt, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Devices Market Strategic Shifts & Innovations
Clinical-grade sensing architectures are migrating from specialized medical devices into consumer form factors, blurring regulatory boundaries and forcing vendors to rebuild quality systems around FDA and EU MDR compliance.
Photoplethysmography combined with machine learning inference is consolidating cardiovascular monitoring capabilities into smartwatch platforms. Cardiology practices and value-based care organizations are adopting these devices for arrhythmia screening programs. The technology is consolidating previously discrete monitoring categories—Holter monitors, event recorders, and consumer fitness trackers—into single-platform solutions that compress equipment procurement budgets.
EU MDR Class IIa certification requirements for software-driven diagnostic functions are tightening clinical evidence standards for wearable algorithms. Manufacturers must now submit prospective validation studies rather than retrospective database analyses. Hearable and wrist-worn categories targeting European distribution are restructuring development roadmaps to accommodate eighteen-to-twenty-four-month certification timelines.
Employer-sponsored wellness programs are unbundling device subsidies from health plan premiums, shifting procurement decision rights from benefits administrators to individual employees. This fragmentation is redirecting volume through retail and direct-to-consumer channels rather than enterprise contracting. The United States exhibits the most pronounced channel rotation as self-insured employers test consumption-based wellness incentives.
Wearable Devices Market Segmentation
Wearable device segmentation reveals how hardware specifications, connectivity protocols, and user workflows create distinct margin architectures. Understanding these boundaries helps vendors allocate R&D resources toward segments commanding premium pricing or recurring revenue potential.
Product Type:
Replacement cycles vary dramatically across form factors, with wrist-worn devices refreshing every two to three years while hearables and eyewear accelerate toward annual cadences driven by battery degradation and style turnover.
- Smartwatches:Full-featured wrist-worn platforms integrating clinical-grade photoplethysmography, electrocardiography, and blood oxygen sensing. Demand concentrates in the United States where employer wellness mandates and reimbursement pathway development for remote patient monitoring sustain enterprise procurement at premium price tiers.
- Hearables:Ear-worn audio devices absorbing biometric monitoring through photoplethysmography and inertial measurement units. Sports enthusiasts and corporate wellness programs in the United States drive fastest expansion as gesture control and health analytics migrate from wrist to ear form factors.
- Fitness Trackers:Simplified wrist-worn devices emphasizing step counting, calorie estimation, and basic heart rate monitoring. Price-sensitive consumer segments in retail channels sustain volume despite feature convergence toward smartwatch categories.
- Smart Glasses:Optical head-mounted displays with augmented reality overlay capabilities and environmental sensing. Enterprise productivity applications and specialized industrial workflows sustain niche deployment despite consumer adoption constraints.
- Health Monitors:Dedicated medical-grade devices for continuous glucose monitoring, blood pressure tracking, or pulse oximetry. FDA 510(k) clearance requirements and CMS reimbursement code development shape market access timelines in the United States.
Volume placements concentrate in smartwatches; the faster expansion belongs to hearables.
Technology:
Component selection determines power budgets, data throughput ceilings, and interoperability with existing smartphone and health IT infrastructures.
- Bluetooth:Low-energy wireless protocol dominating short-range connectivity between wearables and paired smartphones. FCC Part 15 emission compliance and interference management in dense urban environments shape implementation requirements.
- Accelerometer:MEMS inertial sensor enabling step detection, fall recognition, and gesture classification. Asian contract manufacturers concentrate production capacity, creating supply vulnerability for mid-tier device vendors.
- GPS:Satellite positioning module enabling outdoor navigation, geofencing, and location-based health analytics. Garmin and specialized outdoor vendors command durable margin pools in aviation and ruggedized expedition segments.
- Wi-Fi:Higher-throughput wireless enabling direct cloud synchronization without smartphone intermediation. Battery chemistry constraints limit deployment to larger form factors with expanded cell capacity.
- NFC:Near-field communication enabling contactless payments and access credential storage. Financial services integration and transit authority partnerships determine regional deployment velocity.
- Gyroscope:Rotational motion sensor complementing accelerometer data for orientation tracking and activity classification. Sensor fusion with machine learning inference enables gesture control interfaces.
Bluetooth and accelerometer combinations dominate unit economics; GPS-enabled architectures climb the fastest as outdoor and clinical applications expand.
Application:
Workflow integration depth determines pricing power, with surface-level fitness tracking commoditizing while clinical-grade monitoring commands reimbursement-linked premiums.
- Remote Patient Monitoring:Continuous biometric streaming into electronic health records for chronic disease management. Federally Qualified Health Centers in the United States represent underpenetrated whitespace where clinical-grade wearable deployment lags decentralized care delivery priorities.
- Fitness Tracking:Activity quantification for calorie expenditure, workout intensity, and recovery metrics. Consumer self-purchase through retail channels sustains volume as employer wellness programs fragment procurement decision rights.
- Sleep Analysis:Nocturnal heart rate variability, blood oxygen, and movement pattern assessment. Algorithm-dependent features face extended FDA 510(k) timelines as clinical validation requirements tighten for novel sensing modalities.
- Gesture Control:Motion-based interface navigation for hands-free device operation. Hearable form factors absorb this functionality as audio platforms expand beyond playback into spatial computing interfaces.
- Navigation:Turn-by-turn guidance and location logging for outdoor recreation and industrial logistics. Specialized vendors maintain positioning through ruggedized specifications and aviation certification requirements.
Revenue concentrates in remote patient monitoring; sleep analysis gains share fastest as clinical validation studies accumulate.
End User:
Procurement authority and budget source create distinct sales motion requirements, from retail consumer marketing to enterprise contracting and defense procurement.
- Consumers:Individual purchasers selecting devices through retail, direct-to-consumer, and carrier channels. Subscription-based health analytics is restructuring value capture, shifting revenue from hardware transactions toward recurring software relationships.
- Medical Practitioners:Clinical professionals prescribing or recommending devices for patient monitoring. HIPAA interoperability mandates and FDA Software as a Medical Device frameworks determine platform selection criteria.
- Corporate Employees:Workforce populations receiving devices through employer-sponsored wellness programs. United States enterprises facing healthcare premium inflation expand wearable procurement as preventive health infrastructure.
- Sports Enthusiasts:Amateur and professional athletes demanding performance optimization and injury prevention metrics. Specialized outdoor and endurance segments sustain premium pricing for GPS-enabled and ruggedized specifications.
- Military Personnel:Defense forces procuring devices for health monitoring, navigation, and situational awareness. Procurement runs through specialized defense contracting channels with distinct cybersecurity and operational security requirements.
Consumer channels dominate unit placements; medical practitioner adoption accelerates fastest as reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Asian contract foundries contrasts sharply with consumption gravity in Western healthcare reimbursement markets. Component fabrication clusters dominate East Asian supply chains while clinical-grade deployment concentrates where FDA pathways and employer wellness mandates align.
United States
Employer-sponsored wellness programs and Federally Qualified Health Center procurement sustain enterprise volume commitments for remote patient monitoring devices. FDA Software as a Medical Device frameworks accelerate clearance timelines for clinical-grade algorithms. Greater Boston hosts concentrated biomedical engineering talent pools where signal processing and clinical validation capabilities cluster.
China
Domestic demand for fitness trackers and hearables expands through retail channel penetration and component verticalization advantages. NMPA medical device registration requirements shape market access timelines for clinical-grade wearables targeting hospital procurement. Shenzhen manufacturing clusters supply MEMS accelerometer and optical sensor modules to mid-tier global vendors.
Germany
EU MDR Class IIa certification requirements tighten clinical evidence standards for software-driven diagnostic functions entering European distribution. Industrial wearable applications for logistics and manufacturing sustain niche demand through occupational safety mandates. Bavaria anchors precision engineering capabilities where sensor fusion and embedded systems development concentrate.
South Korea
Seoul Capital Area conglomerates leverage display and semiconductor component advantages to integrate wearable platforms with smartphone ecosystem architectures. MFDS medical device approvals determine reimbursement eligibility for clinical-grade sensing features. Government-backed digital health initiatives accelerate pilot deployments in aging population care networks.
India
Price-sensitive consumer segments drive fitness tracker volume through retail and direct-to-consumer channels as urban health awareness expands. CDSCO medical device regulations are evolving to accommodate Software as a Medical Device classifications for emerging clinical applications. Karnataka technology corridors host emerging design houses bridging hardware development and health analytics software.
Wearable Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the wearable devices landscape. The market structures around three tiers: vertically integrated technology conglomerates controlling component supply and ecosystem distribution; specialized health analytics platforms commanding subscription recurring revenue; and regional assemblers competing on cost-optimized hardware specifications. Strategic moves concentrate on algorithm licensing partnerships and clinical validation study investments that compress FDA clearance timelines.
Within the ecosystem-integrated tier, Apple and Samsung Electronics exemplify platform leverage strategies where smartphone distribution anchors wearable attach rates. Garmin occupies a position among specialized outdoor and aviation vendors where ruggedized specifications and certification requirements sustain durable margin pools. WHOOP represents the subscription-native archetype, anchoring recurring revenue models built on longitudinal biometric data relationships rather than hardware transaction economics.
| Leading Market Players |
|---|
| Fitbit |
| WHOOP |
| Apple |
| Huami |
| Amazfit |
| Samsung Electronics |
| Oura |
| BoAt |
| Garmin |
| Others |
Cost & Logistics Intelligence
Captive component production across MEMS sensors and optical modules anchors supply positioning for tier-one vendors while insulating them from foundry margin capture. This backward integration into semiconductor fabrication sustains pricing power in clinical-grade segments where FDA 510(k) clearance requirements create certification moats.
Pricing Analysis
Margin tightening in mid-tier wrist-worn devices reflects MEMS accelerometer supply concentration among Asian contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Apple and Samsung ecosystem-integrated offerings from Garmin's specialized outdoor specifications and Huami's cost-optimized fitness trackers. Cost-down pressure on basic fitness trackers accelerates because feature convergence toward smartwatch architectures erodes differentiation. Corporate wellness programs in the United States exhibit lowest price sensitivity where reimbursement pathways justify premium procurement, while retail consumers in India drive volume through aggressive economy-tier positioning.
Supply Chain Analysis
FDA Software as a Medical Device qualification requirements gate supply relationships for clinical-grade algorithm providers, forcing foundry partnerships with ISO 13485-certified manufacturing sites. Component fabrication clusters center on Shenzhen for optical heart rate modules, Seoul for display and semiconductor integration, and Taiwan for MEMS sensor wafers. Lithium-polymer cell supply draws from Chinese and South Korean chemical producers where energy density constraints tether form factor design to battery chemistry limitations. Single-source vulnerability concentrates in photoplethysmography optical sensor supply where Asian contract manufacturers dominate capacity. Distribution runs through enterprise contracting channels for remote patient monitoring devices and retail partnerships for consumer fitness trackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA 510(k) clearance timelines and EU MDR Class IIa certification requirements erect barrier-to-entry moats favoring incumbent algorithm developers with established quality systems.
For Market Incumbents: Deepen clinical validation study investments to compress FDA Software as a Medical Device clearance cycles and preempt emerging subscription-native competitors like WHOOP. Defensive consolidation should prioritize captive supply of MEMS accelerometer capacity amid Asian foundry concentration, while channel control through hospital system GPO contracts protects against employer wellness program fragmentation redirecting volume to retail. For New Entrants and Emerging Players: Begin with underpenetrated Federally Qualified Health Center networks in the United States where clinical-grade wearable deployment lags decentralized care delivery priorities. Rural health infrastructure represents the most penetrable whitespace, with hearable biometric convergence offering a differentiated form factor entry angle against wrist-worn saturation. A direct-to-clinician go-to-market motion bypasses enterprise contracting barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ecosystem-integrated technology conglomerates seeking algorithm capabilities and FDA-cleared quality systems. Long-term viability favors platforms with native electronic health record integration and recurring subscription revenue architectures over hardware-transaction-dependent vendors. The signal to watch is CMS reimbursement code development for wearable-derived biomarkers as inflection indicator for clinical adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for Software as a Medical Device features unlock enterprise contracting in United States reimbursement markets. |
| CE Marking Pathway Investment | EU MDR Class IIa certification for diagnostic algorithms sustains European distribution access amid tightening clinical evidence standards. |
| Hospital System Partnership | Direct electronic health record integration with Epic and Cerner platforms creates competitive advantage under HIPAA interoperability mandates. |
| Software Companion Development | Subscription-native health analytics platforms shift revenue from hardware transactions toward recurring longitudinal patient data relationships. |
| Reimbursement Strategy | CMS coverage pathway development for remote patient monitoring codes determines clinical adoption beyond pilot contracts. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and FDA regulatory affairs leads with secondary validation from FDA 510(k) databases, EU MDR notified body submissions, CMS reimbursement code filings, and hospital procurement databases. Bottom-up unit shipment modeling triangulated against top-down healthcare expenditure allocation produced convergent market sizing.
Granularity-level modeling deployed product type, application, and end-user segmentation across the projection horizon with geographic resolution at country level for United States, China, Germany, South Korea, and India. CAGRs were derived from fitted growth curves incorporating technology adoption S-cycles and reimbursement framework maturation timelines. Forecast inputs included employer wellness program penetration rates, FDA Software as a Medical Device clearance velocity, and MEMS sensor foundry capacity expansion plans.
Underlying measurement precision varies by segment; remote patient monitoring applications carry tighter precision than fitness tracking commoditization due to reimbursement-linked visibility. Forecasts reflect documented assumptions regarding regulatory pathway timelines and employer procurement behavior. A model refresh is warranted upon material change in CMS reimbursement code development for wearable-derived biomarkers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Australia Wearables Market