
 Wearable Devices in Sports Market | 2026-2036
Wearable Devices in Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Devices in Sports Market Analysis
Multi-source component procurement is rebalancing toward vertically integrated in-house sensor production as supply chain resilience becomes a priority. Apple leverages its semiconductor design capabilities to sustain proprietary chip architectures across its wearable portfolio. Garmin anchors its position through specialized GPS and altimeter integration for outdoor endurance applications. WHOOP competes on subscription-based recovery analytics, differentiating through continuous heart rate variability monitoring.
Wearable devices in sports encompass sensor-embedded hardware that captures physiological and kinematic data during athletic activity, typically incorporating accelerometers, gyroscopes, photoplethysmography sensors, and Bluetooth Low Energy transmitters with power consumption below 10 milliamps. These systems transmit real-time biometrics to coaching dashboards or cloud platforms for performance analysis and load management. Smartwatches and fitness trackers lead unit volume, while GPS watches command premium pricing through multi-band satellite positioning and barometric altimetry. Heart rate monitors represent a mature segment with stable replacement cycles, though chest-strap variants retain accuracy advantages over optical wrist sensors for high-intensity interval training.
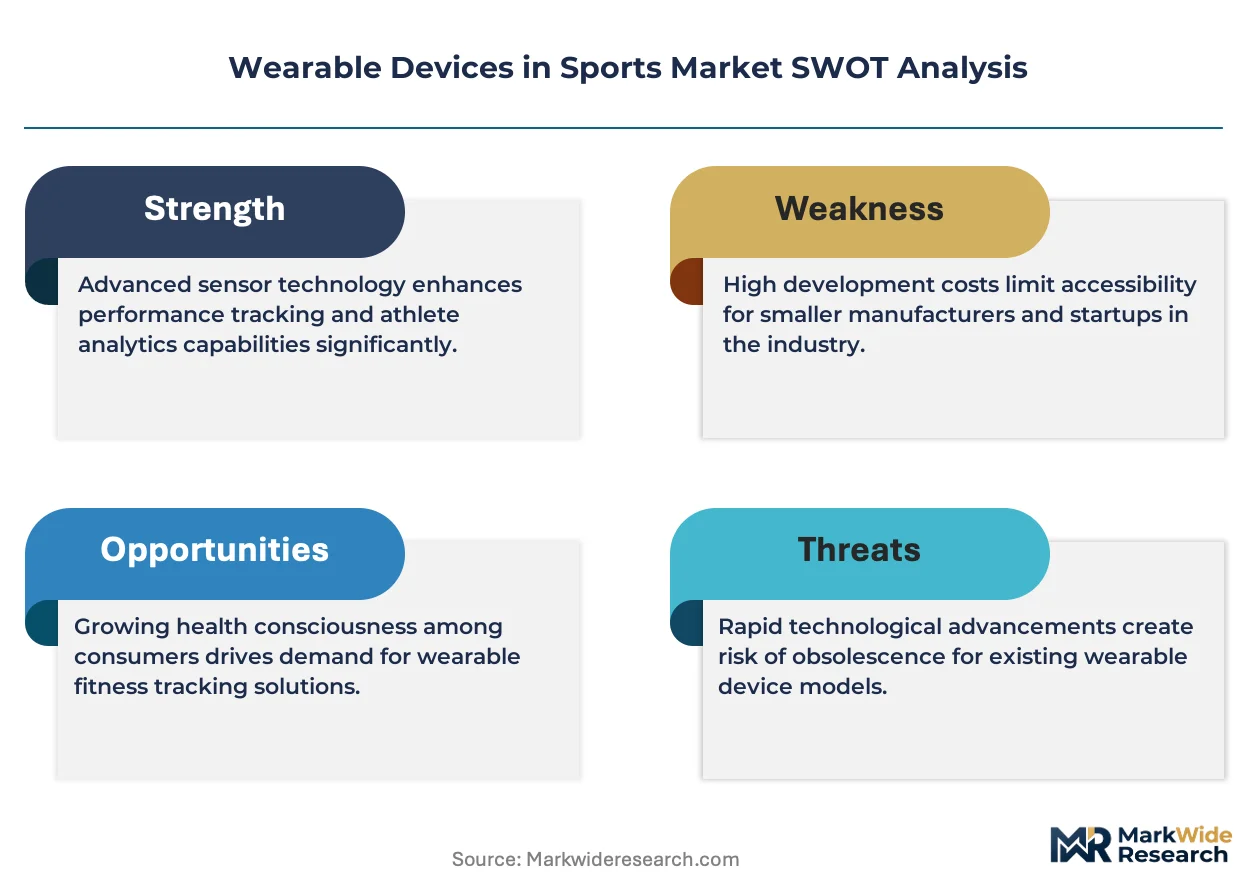
FDA clearance requirements for medical-adjacent claims are constraining marketing language around arrhythmia detection and blood oxygen diagnostics. FCC Part 15 rules govern radio frequency emissions from Bluetooth and Wi-Fi connectivity modules embedded in training devices. ISO 13485 quality management standards are becoming a de facto barrier for suppliers seeking partnerships with Olympic federations and professional leagues. Stakeholders must monitor evolving liability frameworks as real-time injury alert algorithms transition from coaching tools to duty-of-care obligations.
Market Dynamics
ISO 13485 certification is tightening as Olympic federations and professional leagues mandate medical-grade quality management, forcing suppliers to restructure manufacturing workflows and documentation protocols.
Growth Catalysts
- FCC Part 15 compliance:Radio frequency emission standards for Bluetooth and Wi-Fi modules enable seamless real-time data transmission to coaching dashboards without interference penalties.
- Professional sports franchises:Biometric monitoring program expansion across NBA, NFL, and Premier League clubs drives institutional procurement of continuous heart rate variability systems.
- Photoplethysmography miniaturization:Optical sensor shrinkage below 3mm enables wrist-form-factor devices to match chest-strap accuracy for endurance training applications.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea dominate accelerometer and gyroscope wafer production, exposing supply chains to geopolitical disruption.
- FDA 510(k) pathway:Medical-adjacent arrhythmia detection claims require 12-18 month clearance timelines that constrain marketing velocity.
- Lithium-polymer volatility:Battery raw material price swings above 40% annually compress hardware margins below 15% for mid-tier manufacturers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing attract assembly relocation from China with 4-6% cost arbitrage.
- Recovery analytics monetization:Subscription-based sleep and strain modeling creates recurring revenue streams independent of hardware refresh cycles.
- EU AI Act alignment:Proactive algorithmic transparency documentation opens procurement channels with Bundesliga and Eredivisie clubs.
Industry Challenges
- Biomechanical engineering talent scarcity:Universities produce fewer than 2,000 graduates annually with sport-specific sensor integration expertise.
- Multi-band GNSS certification:Galileo, GLONASS, and BeiDou interoperability testing extends product development timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Devices in Sports Market |
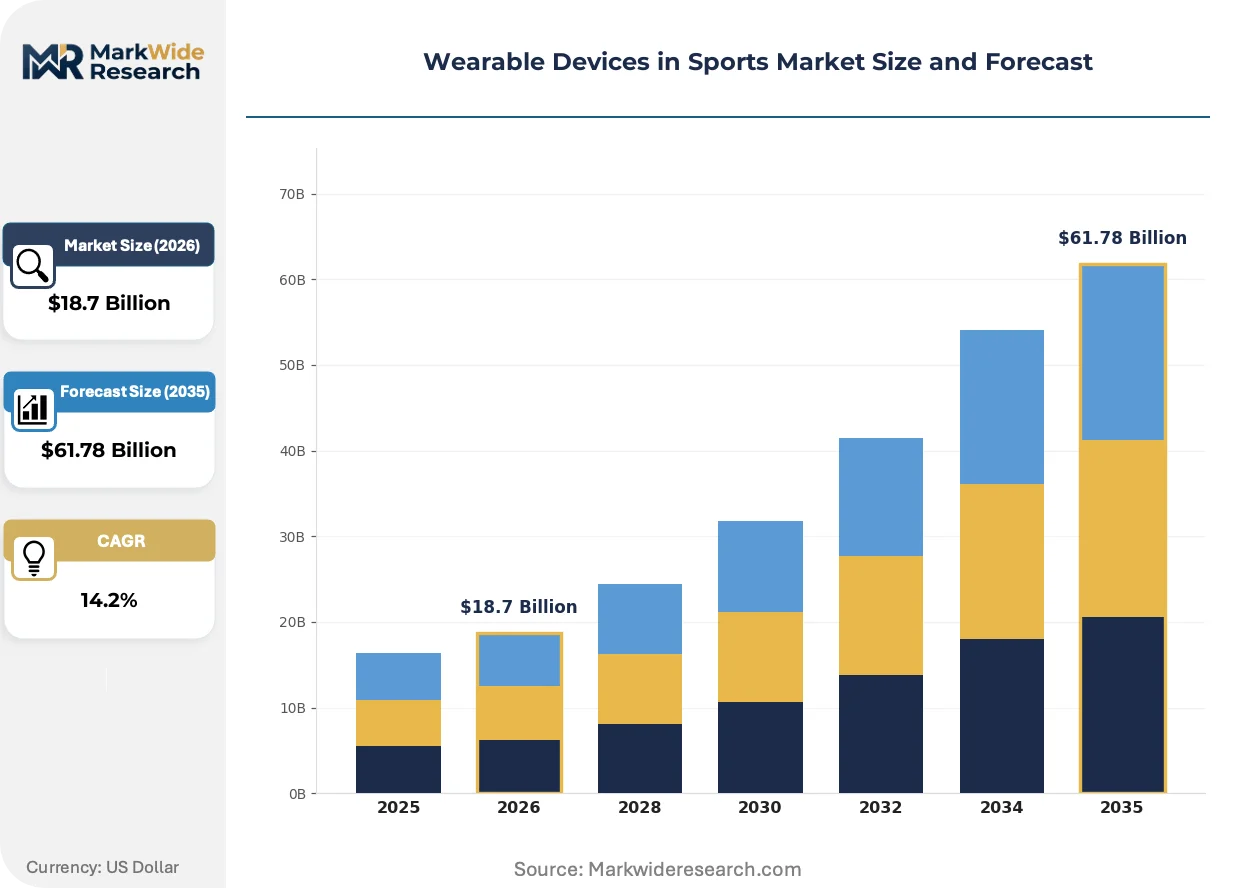
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Heart Rate Monitors, GPS Watches End User: Athletes, Coaches, Sports Teams, Fitness Enthusiasts Technology: Bluetooth, NFC, Wi-Fi, Accelerometer Application: Performance Tracking, Health Monitoring, Training Optimization, Injury Prevention |
| Companies Covered | Fitbit, Samsung, WHOOP, Plantiga, Orangetheory Fitness, Oura, Apple, Orreco, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Devices in Sports Market Emerging Trajectories
Solid-state sensor architectures and algorithmic personalization are compressing development cycles while regulatory convergence around medical-adjacent claims is reshaping competitive positioning.
Photoplethysmography with multi-wavelength LED arrays is electrifying optical heart rate monitoring by penetrating tissue at depths previously requiring chest-strap electrodes. NCAA Division I athletic departments are replacing legacy polar systems at 200+ universities annually. This is electrifying the mid-market segment as accuracy thresholds converge with convenience demands.
EU MDR Class IIa reclassification is capturing wearable devices with diagnostic claims under stricter clinical evidence requirements. Manufacturers must submit post-market surveillance data every two years. GPS watches with blood oxygen features face 18-month recertification delays in Germany and France.
Direct-to-consumer subscription bundling is replacing retail channel dependency for recovery-focused platforms. Athletes purchase hardware at cost while committing to 24-month analytics contracts. This pattern concentrates in the United States where credit-based financing normalizes recurring payment acceptance.
Wearable Devices in Sports Market Segmentation
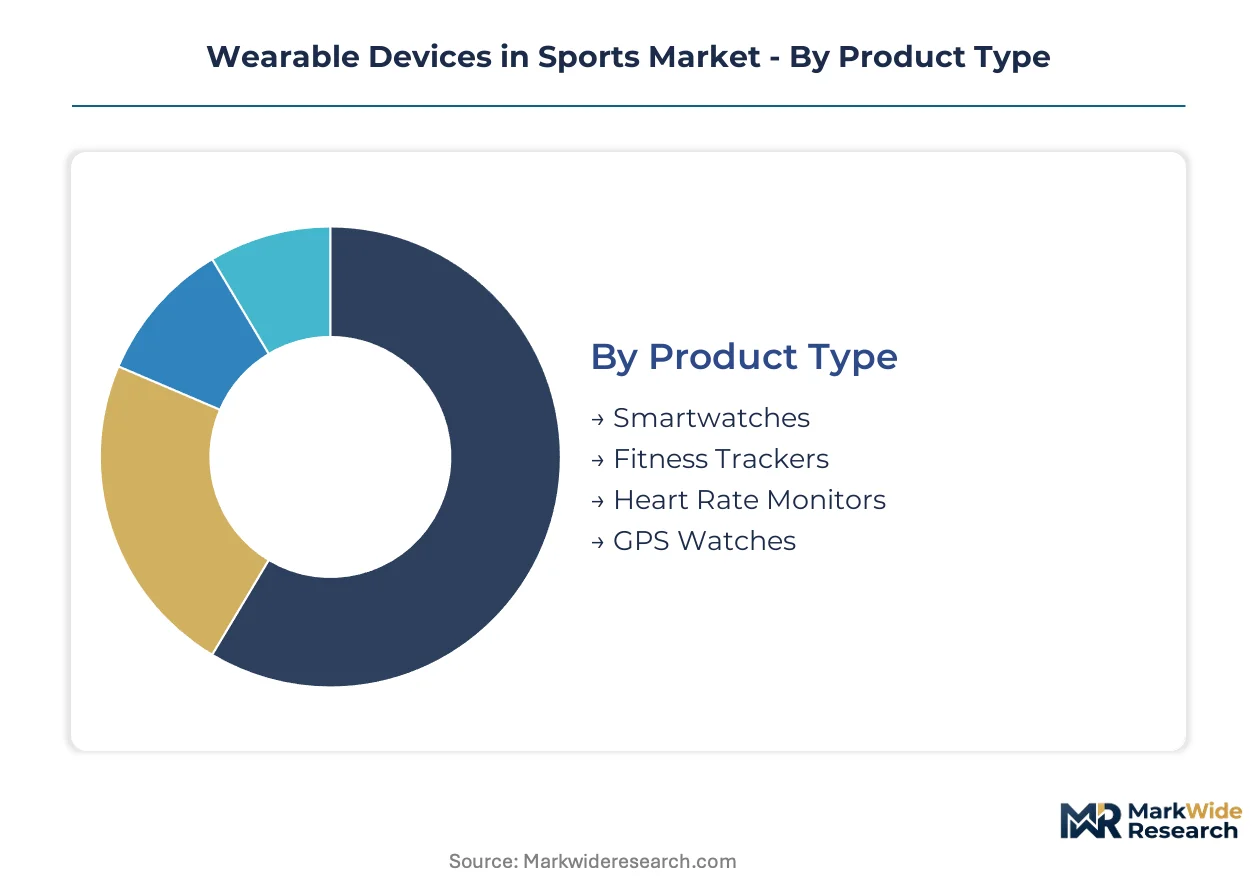
Wearable devices in sports fragment across hardware form factors, user workflows, and data transmission protocols. Each segmentation axis reveals distinct margin structures and replacement-cycle dynamics that shape supplier strategy.
Product Type:
Upgrade cycles vary dramatically by form factor, with GPS watches commanding 3-4 year replacement windows versus 18-month refresh rates for fitness trackers.
- Smartwatches:Multi-function wrist-worn devices integrating cellular connectivity, contactless payment, and third-party app ecosystems. Demand concentrates among recreational athletes in the United States seeking consolidated device consolidation, constrained by battery life limitations below 48 hours under continuous GPS tracking.
- GPS Watches:Specialized units with multi-band satellite positioning, barometric altimetry, and breadcrumb navigation for trail and ultra-endurance applications. Germany and Switzerland drive procurement through Bundesliga club partnerships and Alpine sports culture, with ISO 13485 certification becoming mandatory for medical-adjacent training load claims.
- Fitness Trackers:Entry-level bands with step counting, sleep staging, and basic heart rate monitoring for wellness-oriented consumers.
- Heart Rate Monitors:Chest-strap and optical variants delivering ECG-grade accuracy for interval training and lactate threshold testing.
Fitness trackers sit at the top of the volume ranking, with GPS watches climbing the fastest.
End User:
Procurement authority and budget scale diverge sharply between individual purchasers and institutional buyers with duty-of-care obligations.
- Sports Teams:Professional franchises and Olympic federations deploying continuous biometric monitoring for squad load management. NCAA Division I athletic departments in the United States drive institutional procurement, with liability frameworks shifting real-time injury alerts from coaching tools to legal obligations.
- Coaches:Individual practitioners purchasing dashboard subscriptions and athlete-worn hardware for remote training oversight. Concentration in Australia's high-performance institute network and China's provincial sports bureaus reflects state-funded talent development programs.
- Athletes:Competitive individuals self-funding hardware and analytics subscriptions for performance optimization.
- Fitness Enthusiasts:Recreational users prioritizing wellness metrics and social sharing features over training specificity.
Fitness enthusiasts generate the highest unit volumes, while sports teams deliver the steepest expansion trajectory.
Technology:
Connectivity and sensor choices determine power budgets, data granularity, and interoperability with third-party training platforms.
- Bluetooth:Low-energy protocols dominating real-time data transmission to smartphones and coaching dashboards. FCC Part 15 compliance enables interference-free operation across United States collegiate and professional facilities, with sub-10 milliamp power consumption extending wearable battery life.
- Accelerometer:MEMS-based motion sensing enabling cadence analysis, impact detection, and sleep staging algorithms. Taiwan and South Korea foundry concentration creates supply vulnerability, driving backward integration strategies among tier-one manufacturers.
- Wi-Fi:High-bandwidth connectivity for bulk data offload and firmware updates in training facility environments.
- NFC:Contactless pairing and payment authentication in smartwatch and fitness tracker form factors.
Bluetooth sits at the top of the volume ranking, with accelerometer integration climbing the fastest.
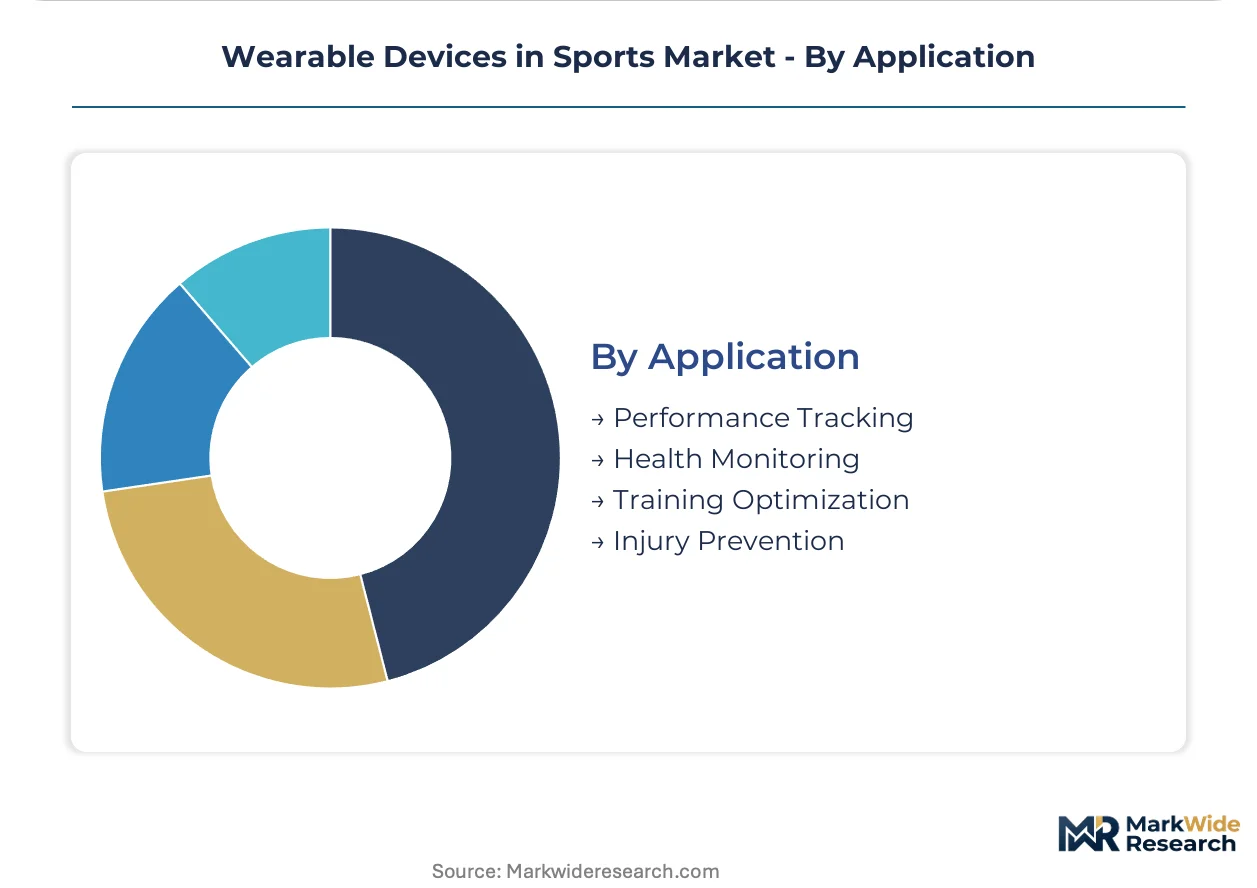
Application:
Use-case specificity determines sensor fusion requirements, algorithm complexity, and regulatory exposure for diagnostic claims.
- Health Monitoring:Continuous tracking of resting heart rate, blood oxygen saturation, and arrhythmia indicators. FDA 510(k) clearance requirements constrain marketing velocity for United States vendors, while EU MDR Class IIa reclassification imposes 18-month recertification delays in Germany and France.
- Training Optimization:Load management, recovery scoring, and periodization guidance based on heart rate variability and sleep quality data. WHOOP and comparable platforms monetize through subscription bundling rather than hardware margins, with 24-month contract structures normalizing in United States direct-to-consumer channels.
- Performance Tracking:Real-time and post-session analysis of speed, power, and technique metrics for competitive benchmarking.
- Injury Prevention:Biomechanical load monitoring and acute-to-chronic workload ratio alerting for soft-tissue risk mitigation.
Performance tracking sits at the top of the volume ranking, with health monitoring climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors wearable device manufacturing through vertically integrated sensor assembly and Bluetooth module production serving global sports technology brands.
United States
NCAA Division I athletic departments drive institutional procurement of continuous biometric monitoring systems for squad load management. FDA 510(k) clearance requirements constrain marketing velocity for arrhythmia detection claims. Austin and Boston clusters concentrate subscription-based recovery analytics platforms with 24-month contract structures normalizing in direct-to-consumer channels.
Germany
Bundesliga club partnerships and Alpine sports culture sustain demand for GPS watches with multi-band satellite positioning and barometric altimetry. EU MDR Class IIa reclassification imposes 18-month recertification delays for blood oxygen diagnostic features. Munich and Stuttgart engineering centers specialize in ISO 13485-certified manufacturing workflows for medical-adjacent training load claims.
China
Domestic brands capture mid-market fitness tracker volume through cost-optimized photoplethysmography sensor integration. MIIT radio frequency certification governs Bluetooth and Wi-Fi module deployment in training devices. Shenzhen and Dongguan production corridors supply MEMS accelerometers and gyroscopes to tier-one manufacturers pursuing backward integration strategies.
India
State-funded talent development programs at provincial sports bureaus drive coach-level procurement of dashboard subscriptions and athlete-worn hardware. PLI scheme production-linked incentives attract assembly relocation from China with 4-6% cost arbitrage. Bangalore and Hyderabad clusters concentrate firmware development and cloud platform engineering for remote training oversight applications.
Australia
High-performance institute networks institutionalize biometric monitoring for Olympic pathway athlete development. TGA therapeutic goods frameworks influence medical-adjacent device classification for diagnostic claim wearables. Melbourne and Brisbane sports science facilities deploy continuous heart rate variability systems for load management across swimming and cycling programs.
Wearable Devices in Sports Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue subscription-based recovery analytics and specialized coaching dashboard platforms. The vendor base stratifies across consumer electronics conglomerates, dedicated sports technology specialists, and vertically integrated sensor manufacturers. Three archetypes dominate: semiconductor-design-capable ecosystem players, GPS-navigation-specialized endurance equipment makers, and algorithm-centric subscription platforms. Competitive moves concentrate on backward integration into in-house sensor production and direct-to-consumer channel bypass of retail intermediaries.
Within the ecosystem-integrated tier, Apple and Samsung exemplify semiconductor-design-capable positioning through proprietary chip architectures across wearable portfolios. Garmin anchors the navigation-specialized archetype through multi-band satellite positioning integration for outdoor endurance applications. WHOOP occupies the subscription-centric segment, monetizing recovery analytics through 24-month contract structures independent of hardware refresh cycles.
| Leading Market Players |
|---|
| Fitbit |
| Samsung |
| WHOOP |
| Plantiga |
| Orangetheory Fitness |
| Oura |
| Apple |
| Orreco |
| Garmin |
| Others |
Supply Flow & Price Mechanics
Captive sensor production strategies anchor both supply security and margin defense for tier-one wearable manufacturers. Apple and Samsung deploy proprietary chip architectures to buffer against MEMS foundry volatility while commanding premium positioning through hardware-software integration.
Pricing Analysis
Lithium-polymer battery cost pass-through compresses hardware margins below 15% for mid-tier manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical-grade units from consumer wellness bands. Pricing pressure stems from raw material swings above 40% annually. Fitness enthusiasts exhibit highest price sensitivity, while professional sports franchises absorb premium for duty-of-care liability coverage.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries dominating accelerometer and gyroscope wafer production. Component sourcing draws from Chinese Bluetooth module assemblers, German precision sensor houses, and Japanese battery cell manufacturers. Geopolitical disruption risk concentrates in Taiwan Strait logistics corridors. Distribution runs through Shenzhen export hubs, regional brand warehouses, and direct-to-consumer subscription platforms bypassing retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable devices in sports function as a stable compounder anchored by institutional procurement expansion across NCAA and professional league franchises. Subscription-based recovery analytics create recurring revenue insulation from hardware refresh cycles.
For Market Incumbents: Lock in backward integration into photoplethysmography sensor production to neutralize Taiwan foundry concentration risk. Deepen ISO 13485 certification moats as Olympic federations mandate medical-grade quality management, raising barriers against algorithm-centric subscription entrants lacking manufacturing scale.
For New Entrants and Emerging Players: India's state-funded provincial sports bureaus represent an underserved buyer archetype with unmet demand for coach-level dashboard subscriptions. Target PLI scheme assembly corridors for 4-6% cost arbitrage. Lead with remote training oversight platforms bundling hardware at cost with 24-month analytics contracts.
For Investors and Strategic Acquirers: Roll-up economics work for algorithm-centric recovery analytics platforms because fragmented sleep and strain modeling specialists lack the capital to achieve FDA 510(k) clearance independently. Five-to-ten year viability hinges on regulatory compliance scale. Monitor EU MDR Class IIa recertification timelines as inflection signal for diagnostic-claim wearable valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Medical-grade quality management opens procurement channels with Olympic federations and Bundesliga clubs. |
| Backward Integration into Sensor Production | In-house MEMS fabrication neutralizes Taiwan foundry concentration and secures supply continuity. |
| Direct-to-Consumer Subscription Launch | Credit-based financing normalizes 24-month analytics contracts independent of hardware margins. |
| Multi-band GNSS Certification | Galileo, GLONASS, and BeiDou interoperability enables premium GPS watch positioning in Alpine markets. |
| EU AI Act Alignment Documentation | Algorithmic transparency compliance opens Bundesliga and Eredivisie institutional procurement channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged wearable device engineering leads, NCAA athletic department procurement officers, professional sports franchise performance directors, and FDA regulatory consultants. Secondary validation drew from FCC Part 15 equipment authorization databases, ISO 13485 certification registries, EU MDR notified body filings, and MIIT radio frequency approval records. Bottom-up sensor shipment modeling and top-down subscription revenue aggregation were cross-referenced for triangulation.
Segment-weighting approaches distributed value estimates across hardware form factors, end-user archetypes, connectivity protocols, and application workflows. CAGRs were derived from fitted growth curves calibrated against institutional procurement expansion rates and consumer replacement cycle compression. Forecast inputs incorporated photoplethysmography accuracy convergence timelines and EU MDR recertification delay distributions.
Underlying measurement precision varies by segment; GPS watches and heart rate monitors carry tighter precision than emerging recovery analytics platforms. Forecasts reflect assumptions around regulatory clearance velocity, supply chain relocation patterns, and subscription renewal rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Sports Technology Market