
 Flexible Wearable Device Market | 2026-2036
Flexible Wearable Device Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Wearable Device Market Insights
Modular sensor-strap configurations that separate the core processing unit from disposable biometric patches is rebalancing procurement economics for hospital systems and corporate wellness buyers. Samsung Electronics leverages its semiconductor foundry scale to control in-house production of flexible AMOLED drivers. Apple Inc. anchors premium positioning through proprietary health-algorithm ecosystems. Xiaomi Corporation competes on manufacturing scale to occupy entry-tier price bands in emerging markets.
Flexible wearable devices integrate bendable substrates, stretchable conductive traces, and low-power microcontrollers into garments or accessories that conform to skin curvature while transmitting physiological data. These systems typically employ polyimide or silicone-based substrates with printed silver nanowire circuits to maintain signal integrity under mechanical deformation. Smartwatches currently dominate revenue contribution due to established consumer familiarity and broad retail distribution, while smart clothing represents the fastest-expanding category as textile-embedded sensor costs decline. Health monitoring applications command the deepest margin pools because FDA and MDR certification requirements create barriers that specialized vendors exploit.
FDA clearance pathways for Class II wearable diagnostics shape product development timelines and clinical validation budgets in the United States. The EU MDR and REACH substance restrictions jointly determine material selection and biocompatibility testing protocols for devices sold across Europe. Stakeholders must monitor evolving reimbursement codes from CMS and national health authorities, as payment parity between wearable-derived data and traditional diagnostics will determine whether enterprise healthcare adoption sustains its current trajectory or retreats to consumer-only segments.
Market Dynamics
Modular sensor-strap architectures are redrawing procurement economics across hospital systems and corporate wellness programs, separating reusable processing cores from disposable biometric patches to lower per-patient costs.
Growth Catalysts
- CMS Reimbursement Codes:Medicare payment parity for wearable-derived diagnostics is pulling enterprise healthcare adoption beyond consumer segments in the United States.
- Silver Nanowire Circuits:Printed conductive traces on polyimide substrates now maintain signal fidelity under repeated mechanical deformation, unlocking textile-embedded form factors.
- Germany:The EU MDR's tightened biocompatibility requirements are accelerating hospital procurement of certified continuous monitoring bands for remote patient management.
Market Restraints
- Palladium Price Volatility:Conductive ink formulations depend on palladium catalysts, exposing manufacturers to precious metal cost swings that compress margin pools.
- Taiwan Semiconductor Concentration:Flexible AMOLED driver fabrication concentrates in a single geography, creating single-source vulnerability for display-integrated wearables.
- REACH Substance Restrictions:ECHA's evolving restricted substance list forces reformulation of silicone-based skin-contact adhesives, extending R&D timelines.
Strategic Opportunities
- India:BIS certification pathways for Class A medical electronics remain underpenetrated, offering first-mover positioning for remote cardiac monitoring.
- Garment-Integrated Hydration Sensing:Textile-embedded capacitive sensors that track electrolyte balance through sweat represent an unoccupied application white space.
- Japan's METI Green Innovation Fund:Subsidies for low-power edge AI chips are converging with stretchable electronics to enable battery-free physiological monitoring.
Industry Challenges
- FDA 510(k) Validation Timelines:Clinical evidence requirements for Class II wearable diagnostics extend product development cycles by 18-24 months.
- Biomedical Algorithm Talent Scarcity:Signal processing engineers capable of artifact rejection in motion-corrupted PPG data command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Wearable Device Market |
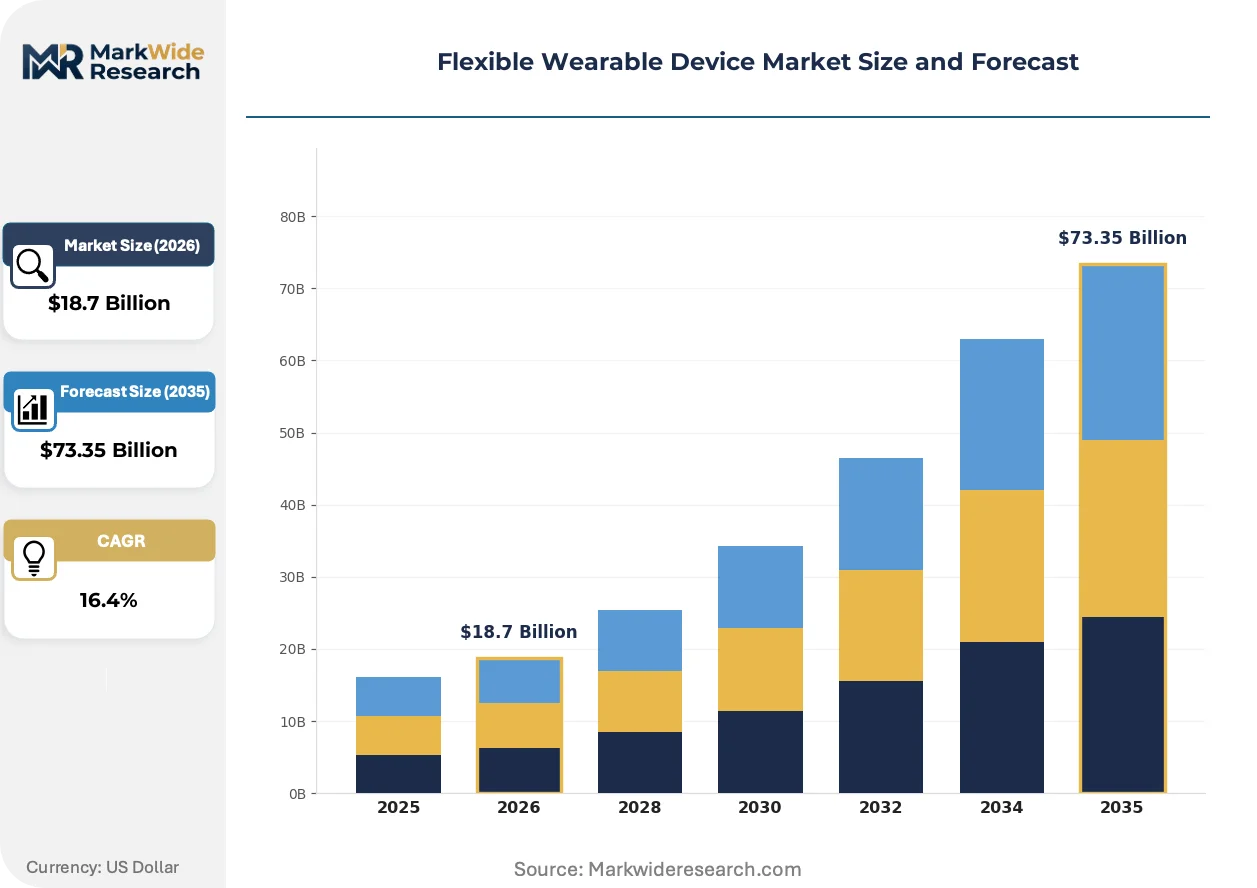
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Clothing, Health Monitors Technology: Flexible Sensors, Wireless Connectivity, NFC, Bluetooth End User: Fitness Enthusiasts, Healthcare Providers, Tech Savvy Consumers, Corporate Wellness Programs Application: Health Monitoring, Fitness Tracking, Sleep Analysis, Payment Solutions |
| Companies Covered | Samsung Electronics, Apple Inc., DuPont, Panasonic, Celanese, Garmin Ltd., Huawei Technologies Co. Ltd., Xiaomi Corporation, StretchSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Wearable Device Market Trends and Innovations
Stretchable hybrid electronics are collapsing the boundary between consumer accessories and clinical-grade monitors, forcing vendors to choose between FDA investment and mass-market volume.
Printed silver nanowire networks on thermoplastic polyurethane substrates enable multiaxial stretchability without conductivity loss. Hospital procurement teams in the United States are piloting these materials for post-surgical monitoring bands. The technology is expanding into insurance-funded remote patient management programs that previously relied on rigid pulse oximeters.
The EU MDR's 2021 recast tightened biocompatibility testing for devices with prolonged skin contact. Manufacturers must now submit cytotoxicity and sensitization data for every substrate-adhesive combination. Smart clothing vendors targeting European hospital systems are responding by consolidating suppliers to reduce validation burden.
Corporate wellness buyers are unbundling hardware acquisition from data analytics subscriptions, treating sensors as consumables rather than capital equipment. This pattern compresses vendor switching costs and rewards modular architectures. The shift is most visible in United States self-insured employer plans, where annual device refresh cycles are replacing three-year procurement agreements.
Flexible Wearable Device Market Segmentation
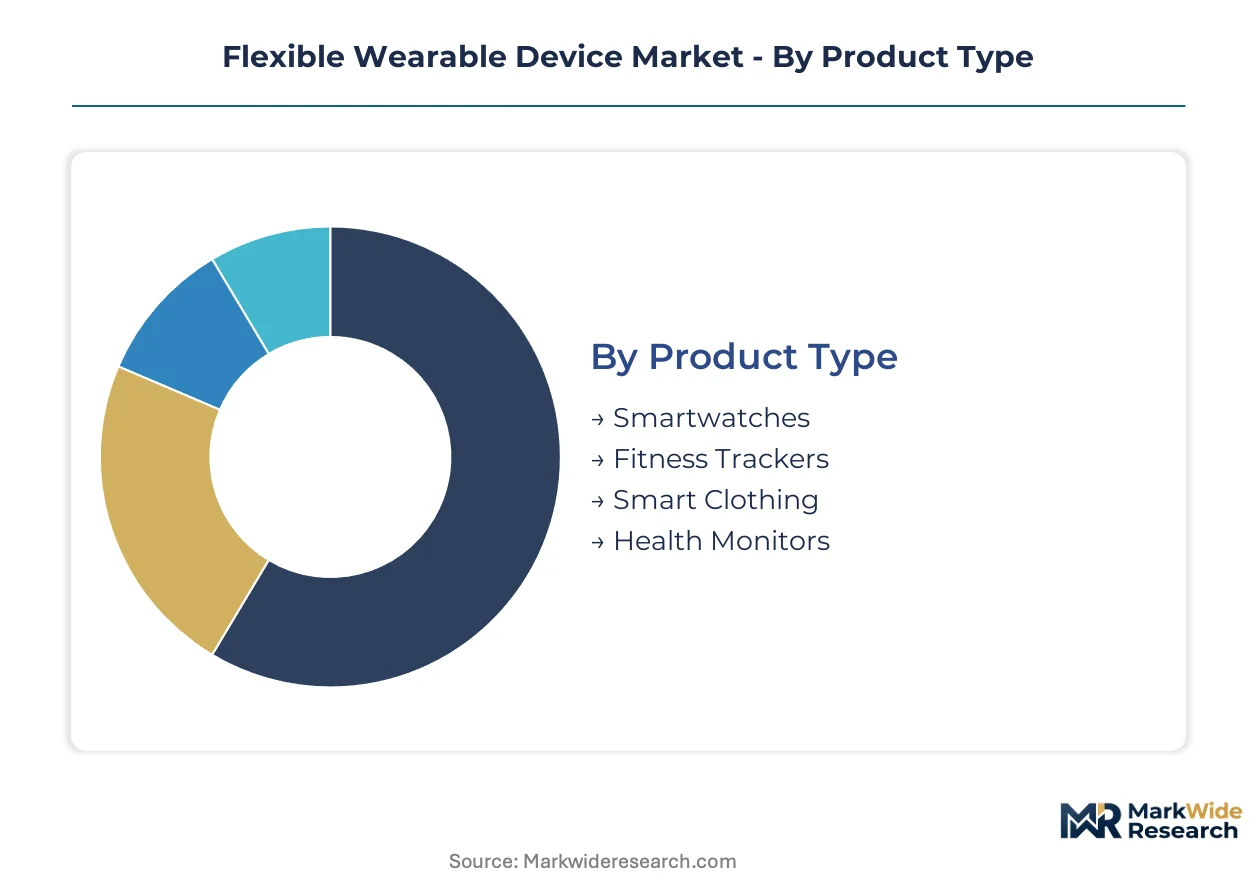
Segmentation in flexible wearables reveals how procurement economics diverge across hospital systems, corporate buyers, and consumer channels. Each dimension—product form, underlying technology, end-user profile, and use case—carries distinct margin structures and regulatory requirements that reshape competitive positioning.
Product Type:
Supply concentration in AMOLED driver fabrication and printed circuit manufacturing favors vendors with captive semiconductor capacity or long-term foundry partnerships.
- Smartwatches:These devices integrate rigid-flex hybrid substrates with polyimide-based flexible circuits around curved display edges. Hospital procurement teams in the United States prioritize FDA-cleared models for remote patient management, while consumer channels reward rapid industrial design refresh cycles.
- Smart Clothing:Textile-embedded silver nanowire networks on thermoplastic polyurethane substrates enable multiaxial stretchability without signal degradation. Post-surgical monitoring bands in Germany are piloting these materials under EU MDR-certified supplier consolidations.
- Fitness Trackers:Entry-tier wristbands compete on manufacturing scale and algorithm-licensing costs.
- Health Monitors:Specialized continuous monitoring bands command premium pricing through clinical validation investments.
Today's leader: Smartwatches. Tomorrow's challenger: Smart Clothing.
Technology:
Cost tier separation between premium proprietary stacks and commodity wireless modules determines which vendors capture enterprise versus consumer margins.
- Flexible Sensors:Printed conductive traces on silicone or polyimide substrates maintain signal fidelity under mechanical deformation. REACH substance restrictions are forcing reformulation of skin-contact adhesives in European markets.
- Wireless Connectivity:Low-power Bluetooth Low Energy and proprietary protocols enable continuous data streaming to edge devices. Medicare reimbursement pathways in the United States are pulling hospital adoption toward certified connectivity standards.
- NFC:Contactless payment authentication chips integrate with wearable form factors for transit and retail applications.
- Bluetooth:Standardized radio modules face margin compression from chipset commoditization.
Flexible Sensors anchor current revenue. Wireless Connectivity is gaining share fastest through enterprise healthcare deployment.
End User:
Application maturity separates established consumer segments from emerging clinical channels with divergent validation timelines.
- Healthcare Providers:Hospital systems and remote patient management programs demand FDA 510(k) or EU MDR certification. CMS reimbursement codes in the United States are creating institutional pull beyond consumer-only segments.
- Corporate Wellness Programs:Self-insured employers treat sensors as consumables with annual refresh cycles rather than capital equipment. Modular architectures that separate reusable cores from disposable patches reduce per-employee costs.
- Fitness Enthusiasts:Performance-oriented consumers drive algorithm differentiation in motion-corrupted biometric signal processing.
- Tech Savvy Consumers:Early adopters reward industrial design innovation and ecosystem integration.
Healthcare Providers dominate margin pools. Corporate Wellness Programs show steepest expansion trajectory through procurement unbundling.
Application:
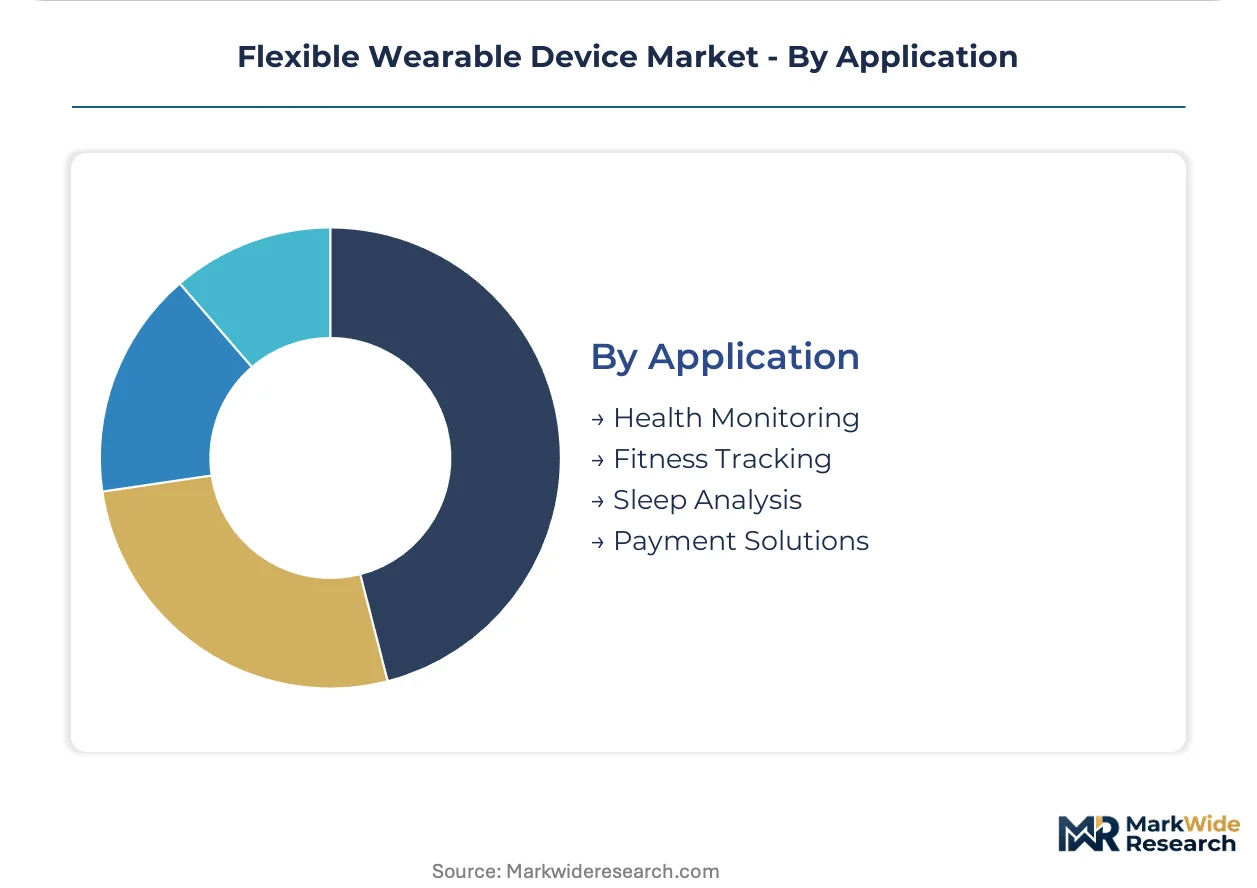
Volume concentration in health monitoring reflects reimbursement parity decisions by national health authorities that determine enterprise adoption sustainability.
- Health Monitoring:Continuous physiological tracking through PPG, ECG, and temperature sensors requires FDA Class II clearance in the United States. Biomedical algorithm talent scarcity for artifact rejection in motion-corrupted data extends development timelines.
- Fitness Tracking:Step counting, calorie estimation, and workout classification represent the most penetrated use case with established consumer familiarity.
- Sleep Analysis:Overnight SpO2 and heart rate variability monitoring demands power-optimized sensor fusion.
- Payment Solutions:Tokenized secure elements for contactless transactions integrate with wearable form factors.
Health Monitoring commands deepest margins. Sleep Analysis is climbing the fastest as textile-embedded sensors reduce hardware costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flexible wearable device industry traces its commercial origins to Japanese materials science breakthroughs in the 1990s, with Osaka-based laboratories pioneering polyimide substrate formulations that enabled the first bendable circuits. South Korean display manufacturers subsequently scaled AMOLED driver production, while Silicon Valley software ecosystems transformed hardware into health-data platforms. Today, procurement patterns cluster around reimbursement policy nodes, semiconductor fabrication corridors, and regulatory certification hubs across five distinct national markets.
United States
Hospital systems and self-insured employers drive enterprise procurement of FDA-cleared continuous monitoring bands. CMS reimbursement parity for wearable-derived diagnostics creates institutional pull beyond consumer segments. The FDA's 510(k) pathway for Class II devices shapes clinical validation budgets. Greater Boston's biomedical corridor hosts specialized vendors developing artifact-rejection algorithms for motion-corrupted PPG data.
Germany
Hospital procurement teams accelerate adoption of EU MDR-certified remote patient management systems. The ECHA's REACH substance restrictions force reformulation of silicone-based skin-contact adhesives. Baden-Württemberg's precision engineering clusters supply automated assembly equipment for textile-embedded sensor production. Stuttgart-based research institutes coordinate biocompatibility testing protocols with industrial partners.
China
Manufacturing scale concentration supports entry-tier price band competition across fitness trackers and basic health monitors. The NMPA's medical device classification system determines which products require clinical trial data versus filing exemptions. Shenzhen's electronics corridor integrates flexible circuit fabrication with consumer brand assembly operations. Dongguan suppliers specialize in thermoplastic polyurethane substrate lamination for smart clothing applications.
Japan
METI's Green Innovation Fund subsidizes development of low-power edge AI chips for battery-free physiological monitoring. The PMDA's streamlined approval pathways for software-as-a-medical-device accelerate algorithm deployment. Kansai's materials science heritage persists in Osaka-based laboratories advancing stretchable conductive ink formulations. Nagoya manufacturing clusters produce precision coating equipment for silver nanowire deposition.
India
Remote cardiac monitoring vendors target underpenetrated BIS certification pathways for Class A medical electronics. The CDSCO's evolving device registration framework creates first-mover positioning opportunities. Karnataka's Bangalore-Tumkur corridor hosts contract manufacturers assembling fitness bands for export markets. Hyderabad's life sciences cluster develops signal processing talent for biomedical algorithm development.
Flexible Wearable Device Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification investment and algorithm differentiation dimensions. The vendor base organizes into three tiers: semiconductor-integrated conglomerates with captive display driver production, specialized health-algorithm developers with FDA clearance expertise, and manufacturing-scale assemblers competing on unit economics. Strategic moves concentrate on modular architecture licensing and regional certification partnerships rather than direct capacity competition.
Within the semiconductor-integrated tier, Samsung Electronics and Apple Inc. exemplify divergent approaches to vertical control. Samsung's foundry-scale AMOLED driver production anchors supply security for display-integrated form factors. Apple's proprietary health-algorithm ecosystems represent investment in software differentiation that commands premium positioning. Xiaomi Corporation sits within the manufacturing-scale tier, competing on procurement economics for entry-tier wristbands across emerging markets. StretchSense occupies a specialist position exemplifying textile-embedded sensor development for industrial and clinical applications.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple Inc. |
| DuPont |
| Panasonic |
| Celanese |
| Garmin Ltd. |
| Huawei Technologies Co. Ltd. |
| Xiaomi Corporation |
| StretchSense |
| Others |
Pricing and Supply Chain Analysis
Palladium spot price volatility cascades through conductive ink formulations into tiered pricing structures for flexible wearables, compressing margins at the manufacturing scale tier while amplifying premium capture for FDA-cleared clinical bands. Hospital procurement teams in the United States absorb higher unit costs for certified devices, whereas corporate wellness buyers shift toward modular sensor-strap architectures that treat disposable patches as consumables rather than capital equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared health monitors from uncertified fitness trackers and entry-tier wristbands. Price differentiation hinges on clinical validation investment and captive semiconductor production, with Samsung Electronics and Apple Inc. commanding brand premiums through in-house AMOLED driver fabrication. Cost compression in the economy tier intensifies because Xiaomi Corporation and Shenzhen assemblers compete on procurement economics for emerging market volume. Corporate wellness programs exhibit highest price sensitivity, while hospital systems prioritize certification grade over per-unit cost.
Supply Chain Analysis
Workforce availability for precision coating engineers in Nagoya, Japan and flexible circuit technicians in Dongguan, China anchors silver nanowire deposition capacity for textile-embedded sensors. Manufacturing concentrates in South Korea for AMOLED driver foundries, Taiwan for microcontroller fabrication, and Shenzhen for final assembly integration. Raw material dependencies draw from palladium catalyst suppliers, polyimide substrate manufacturers, and thermoplastic polyurethane lamination specialists. Single-source vulnerability concentrates in Taiwan Semiconductor's flexible display driver production. Distribution runs through hospital GPO contracts, corporate wellness platform aggregators, and consumer electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible wearable procurement has matured into a late-cycle quality story as hospital systems and self-insured employers shift specifications toward FDA-cleared clinical-grade devices with validated artifact-rejection algorithms.
For Market Incumbents: Extend certification moats through accelerated FDA 510(k) submissions for novel biometric modalities, while consolidating supplier bases to reduce EU MDR validation burden for silicone-adhesive combinations. Biomedical algorithm talent scarcity threatens margin sustainability unless incumbents lock signal processing engineers through captive R&D centers in Greater Boston. Backward integration into printed silver nanowire production secures supply continuity against palladium price swings. For New Entrants and Emerging Players: Enter via underpenetrated BIS certification pathways for Class A medical electronics in India, where remote cardiac monitoring demand outpaces domestic supply. Garment-integrated hydration sensing through textile-embedded capacitive electrolyte trackers represents an unoccupied application white space with no established vendor. Partner with Japan's METI-subsidized edge AI chip developers to prototype battery-free physiological monitoring for post-surgical bands. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized health-algorithm developers possessing FDA clearance expertise and existing hospital procurement relationships. Five-to-ten year viability favors vendors who bridge consumer volume with clinical validation rather than pure manufacturing-scale assemblers. Watch CMS reimbursement code expansion for wearable-derived diagnostics as the inflection signal determining whether enterprise healthcare adoption sustains or retreats to consumer-only segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clinical validation investment creates defensible pricing power against uncertified competitors in hospital procurement. |
| EU MDR Supplier Consolidation | Reduced substrate-adhesive validation burden lowers compliance costs for European market entry under REACH restrictions. |
| Modular Architecture Licensing | Separating reusable processing cores from disposable patches captures corporate wellness procurement unbundling trends. |
| Silver Nanowire Backward Integration | In-house conductive ink production insulates margin pools from palladium commodity price volatility. |
| Hospital System Partnership | Direct GPO contracting relationships secure recurring revenue streams beyond consumer retail channel volatility. |
Research Methodology
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and corporate wellness program directors grounded qualitative insights in procurement decision dynamics. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement code databases, EU MDR certification registries, and ECHA REACH substance restriction updates. Bottom-up triangulation across sensor component bill-of-materials and top-down reconciliation against hospital system capital expenditure disclosures produced convergent market sizing estimates.
Segment-level outputs across the analysis window reflect modeled interactions between product form factor, certification tier, end-user procurement channel, and application use case intensity. CAGRs were derived from elasticity-adjusted adoption curves incorporating reimbursement policy trajectory and semiconductor supply constraints. Key forecast inputs included palladium price index projections, FDA validation timeline distributions, and CMS coding expansion probability assessments.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time corporate wellness subscription renewal rates introduce uncertainty bands around enterprise segment trajectories. Forecasts reflect assumptions regarding reimbursement parity sustainability and REACH substance restriction implementation timing. Material deviation in CMS coding decisions or Taiwan semiconductor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market