
 Solar Panel Recycling Management Market | 2026-2036
Solar Panel Recycling Management Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Recycling Management Market Analysis
Modular recycling service bundling is consolidating buyer choice around integrated collection-processing-compliance packages rather than standalone disposal contracts. Veolia Environnement SA leverages its waste management infrastructure across European markets to anchor large-scale photovoltaic recovery operations. First Solar sustains thin-film cadmium-telluride recycling leadership through captive closed-loop systems. ROSI Solar competes on advanced semiconductor material recovery, extracting high-purity silicon and silver from end-of-life panels.
Solar panel recycling management encompasses the collection, dismantling, and material recovery from decommissioned photovoltaic modules, with mechanical separation achieving aluminum frame and glass recovery rates exceeding 95% in commercial operations. Its primary purpose is to reclaim silicon, silver, copper, and rare elements while diverting heavy metals and hazardous compounds from landfill streams. Crystalline silicon dominates processing volumes due to its overwhelming share of installed capacity, though margin pools concentrate in chemical processing and hydrometallurgical methods that recover higher-value semiconductor-grade materials. Thin-film recycling sustains specialized demand through cadmium and telluride recovery, while collection services represent the most fragmented segment with low barriers to regional entry.
The EPA guides hazardous waste classification for photovoltaic modules containing lead or cadmium in the United States, while the EU WEEE Directive mandates producer-financed collection targets and recovery quotas across member states. China's MEE enforces solid waste import restrictions and domestic recycling capacity requirements that reshape regional material flows. Stakeholders must monitor evolving extended producer responsibility frameworks and semiconductor material purity standards as these regulatory instruments determine which recovery technologies achieve commercial scale.
Market Dynamics
First-generation photovoltaic installations installed during the 2000s solar boom are reaching end-of-life en masse, forcing asset owners to confront decommissioning liabilities and material recovery obligations at unprecedented scale.
Growth Catalysts
- EU WEEE Directive recovery quotas:Member states mandate producer-financed collection targets that guarantee feedstock volumes for processing facilities.
- Crystalline silicon module retirement wave:The technology's dominance of installed capacity ensures predictable incoming material streams for recyclers.
- China MEE domestic recycling mandates:Solid waste import restrictions redirect material flows toward indigenous processing capacity expansion.
Market Restraints
- Silver and copper price volatility:Recovered metal values fluctuate with commodity markets, compressing processor margins unpredictably.
- German processor concentration:European recycling capacity clusters in a single jurisdiction, creating geographic supply risk.
- Lead and cadmium hazardous classification:EPA toxicity protocols impose costly handling requirements on crystalline and thin-film modules alike.
Strategic Opportunities
- India's aging installed base:The country's early solar parks enter decommissioning phase ahead of domestic recycling infrastructure maturity.
- Semiconductor-grade silicon recovery:Hydrometallurgical purification enables circular supply to photovoltaic and electronics manufacturers.
- Integrated collection-processing-compliance bundling:Asset owners seek single-contractor solutions spanning logistics through regulatory documentation.
Industry Challenges
- Skilled technician scarcity:Safe module dismantling and hazardous material handling require certified personnel in short supply across processing facilities.
- Fragmented collection infrastructure:Rural solar farms and distributed rooftop systems resist economical logistics consolidation.
- Extended producer responsibility compliance timelines:Evolving state-level mandates in the United States create jurisdictional complexity for national operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Recycling Management Market |
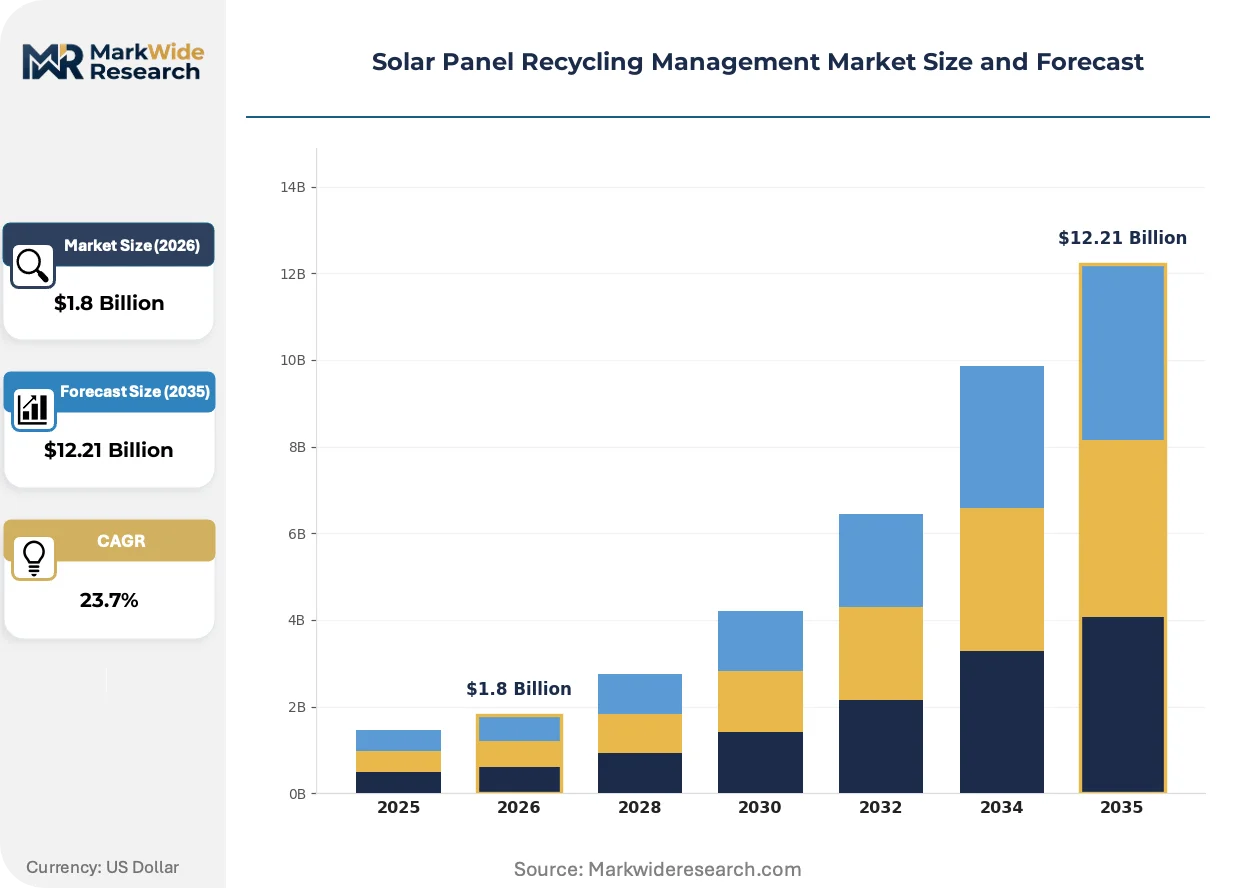
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Silicon, Thin-Film, Bifacial, Concentrated Photovoltaics Recycling Method: Mechanical Separation, Thermal Treatment, Chemical Processing, Hydrometallurgical End User: Manufacturers, Solar Installers, Waste Management Firms, Research Institutions Solution: Collection Services, Processing Technology, Consulting Services, Compliance Services |
| Companies Covered | Reiling GmbH & Co. KG, ROSI Solar, First Solar, SolRecycle, Reclaim PV Recycling, Veolia Environnement SA, We Recycle Solar, The Retrofit Companies, Solarcycle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Recycling Management Market Emerging Trajectories
Mechanical shredding and thermal delamination systems are converging with chemical purification methods, enabling higher-value material streams that alter processor economics and competitive positioning.
Pyrometallurgical recovery of semiconductor-grade silicon is consolidating around integrated furnace systems that simultaneously extract aluminum frames, glass, and precious metals. German and Chinese processors deploy these systems at scale. The technology is consolidating regional processing advantages for operators with capital to deploy multi-stage recovery lines.
REACH substance restrictions and RoHS substance thresholds are tightening allowable heavy metal content in recovered materials destined for re-entry to manufacturing supply chains. European recyclers invest in purification upgrades to maintain material market access. Crystalline silicon module processors face the steepest compliance investment requirements.
Utility-scale solar farm operators are unbundling decommissioning service procurement from original EPC contracts, creating discrete purchasing decisions for end-of-life management. Specialized recyclers compete directly against waste management incumbents for these contracts. This shift is most visible in Germany and the southwestern United States where early utility-scale installations dominate retirement schedules.
Solar Panel Recycling Management Market Segmentation
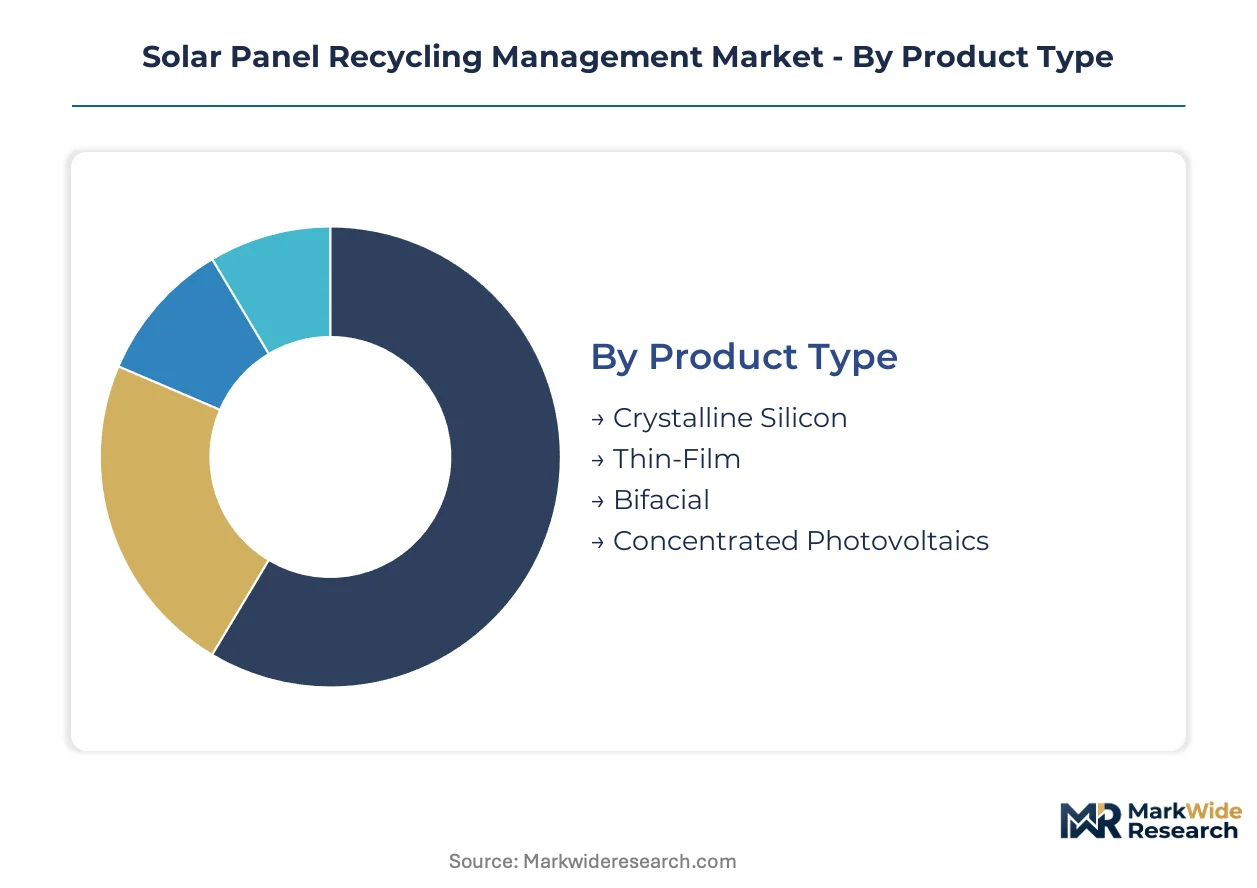
Solar panel recycling management segments around module chemistry, recovery technology, and service configuration. Each axis determines margin structure, regulatory exposure, and competitive entry barriers for operators across the value chain.
Product Type:
Crystalline silicon dominates installed base volumes while thin-film and advanced architectures concentrate specialized recovery margins.
- Crystalline Silicon:Aluminum-framed glass-encapsulated modules containing silicon cells, silver busbars, and copper interconnects. Germany and China host the largest aging crystalline installations reaching decommissioning phase, with EU WEEE Directive quotas guaranteeing feedstock volumes for mechanical and chemical processors.
- Thin-Film:Cadmium-telluride and copper-indium-gallium-selenide architectures requiring hazardous material protocols and specialized thermal recovery. First Solar operates captive closed-loop systems for cadmium-telluride modules in the United States and Germany, extracting semiconductor materials for reuse in new panel manufacturing.
- Bifacial:Double-glass modules with enhanced durability extending operational lifespans but complicating end-of-life delamination. Indian solar parks deploy bifacial technology at scale, though domestic recycling infrastructure lags installation growth.
- Concentrated Photovoltaics:Lens- or mirror-based systems with III-V semiconductor multi-junction cells and active tracking hardware. Concentrated systems concentrate in utility-scale desert installations across Spain, the United States, and Saudi Arabia, with limited decommissioning volumes currently.
Mature deployment sits with crystalline silicon. Newer deployment is concentrated in bifacial architectures.
Recycling Method:
Recovery technology selection hinges on material value targets, hazardous content, and capital intensity thresholds.
- Mechanical Separation:Shredding, crushing, and density-based sorting achieving aluminum and glass recovery rates exceeding 95 percent. German processors deploy mechanical lines at scale for crystalline silicon feedstock, with margins compressing as commodity metal prices fluctuate.
- Thermal Treatment:Pyrometallurgical furnace systems simultaneously extracting frames, glass, and precious metals through high-temperature processing. Chinese operators integrate thermal stages with chemical purification for semiconductor-grade silicon recovery, concentrating regional processing advantages.
- Chemical Processing:Acid leaching and solvent-based dissolution targeting silver, copper, and rare element recovery from cell structures. European REACH substance restrictions tighten allowable heavy metal content in chemically processed outputs, requiring purification upgrades.
- Hydrometallurgical:Aqueous chemistry achieving highest-purity silicon and precious metal recovery for circular re-entry into photovoltaic and electronics manufacturing. Hydrometallurgical purification commands premium pricing but requires skilled technician labor in short supply across processing facilities.
Capital deployment concentrates in thermal treatment. Hydrometallurgical methods are climbing the fastest as semiconductor-grade recovery demands intensify.
End User:
Customer procurement patterns split between integrated service bundling and specialized component sourcing.
- Manufacturers:Panel producers seeking closed-loop material supply and extended producer responsibility compliance documentation. First Solar and European crystalline producers finance recycling infrastructure to secure feedstock for new production.
- Solar Installers:EPC contractors and O&M providers unbundling decommissioning services from original construction contracts. Southwestern United States utility-scale operators now issue discrete RFPs for end-of-life management separate from installation agreements.
- Waste Management Firms:Incumbent disposal operators expanding into photovoltaic recovery through acquisition or partnership. Veolia leverages European waste infrastructure to anchor large-scale collection and preliminary processing.
- Research Institutions:Universities and national laboratories developing novel recovery chemistries and circular material characterization. India's CSIR laboratories partner with domestic recyclers to advance indigenous processing capabilities.
Procurement maturity sits with manufacturers. Installer-driven demand is expanding most quickly as early utility-scale retirements accelerate.
Solution:
Service configuration determines contract structure and customer switching costs across the recycling value chain.
- Collection Services:Logistics networks consolidating modules from distributed rooftop and rural utility-scale sites. Collection remains the most fragmented segment with low regional entry barriers and persistent economies-of-scale challenges.
- Processing Technology:Capital equipment and operational know-how for material separation and purification. German and Chinese processors deploy integrated multi-stage recovery lines that consolidate regional competitive positioning.
- Consulting Services:Decommissioning planning, asset valuation, and circular supply chain advisory for asset owners and financiers. Consulting demand concentrates in Germany and the United States where complex regulatory timelines create jurisdictional complexity.
- Compliance Services:Regulatory documentation, hazardous waste manifests, and extended producer responsibility filing. EU WEEE Directive mandates and emerging state-level United States EPR rules are forcing asset owners to outsource compliance documentation to specialized providers.
Revenue concentration sits with processing technology. Compliance services are gaining share fastest as regulatory fragmentation deepens across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes more end-of-life photovoltaic material than it generates domestically, while China and India confront mounting decommissioning volumes ahead of indigenous recycling capacity maturation. This production-consumption asymmetry shapes cross-border material flows and investment priorities across major solar markets.
United States
Utility-scale solar farms across Arizona, California, and Texas are unbundling decommissioning contracts from original EPC agreements, creating discrete procurement opportunities. EPA hazardous waste classification for lead-containing crystalline modules imposes costly handling protocols that favor specialized processors over general waste operators. The Southwestern cluster around Phoenix anchors the country's most concentrated early retirement activity.
Germany
EU WEEE Directive recovery quotas guarantee feedstock volumes for mechanical and chemical processors operating at commercial scale. REACH substance restrictions and RoHS thresholds tighten allowable heavy metal content in recovered materials, forcing purification upgrades. The country's processing infrastructure concentrates in North Rhine-Westphalia and Bavaria, with integrated multi-stage recovery lines serving cross-border material flows from neighboring member states.
China
The MEE enforces solid waste import restrictions that redirect material flows toward domestic recycling capacity expansion. Crystalline silicon module retirement waves from 2000s-era installations create predictable incoming streams for thermal treatment and hydrometallurgical purification operators. Jiangsu and Zhejiang provinces host the most advanced integrated furnace systems achieving semiconductor-grade silicon recovery.
India
Early solar parks in Rajasthan, Gujarat, and Karnataka enter decommissioning phase ahead of domestic recycling infrastructure maturity. The CEA mandates waste management provisions in solar project approvals, though implementation timelines lag installation growth. CSIR laboratories partner with emerging domestic processors to advance indigenous hydrometallurgical capabilities for high-purity material recovery.
Solar Panel Recycling Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market exhibits moderate consolidation around waste management incumbents with established logistics networks and emerging specialists with proprietary recovery technologies. Three strategic archetypes dominate: integrated waste-to-resource operators leveraging existing collection infrastructure, captive closed-loop systems controlled by panel manufacturers, and technology-focused material recovery specialists. Competitive moves concentrate on geographic expansion through regional partnerships and capacity scaling for semiconductor-grade purification output.
Among European-based specialists, Reiling GmbH & Co. KG and ROSI Solar exemplify contrasting strategic positions. The former occupies a diversified waste-to-resource archetype with cross-material processing capabilities, while the latter represents the technology-focused tier emphasizing advanced semiconductor material extraction. First Solar, identifiable by its corporate structure, anchors the captive closed-loop archetype through manufacturer-controlled recycling systems. These three entities collectively illustrate the competitive segmentation between logistics-driven scale, technology-driven purity, and vertically integrated circularity models.
| Leading Market Players |
|---|
| Reiling GmbH & Co. KG |
| ROSI Solar |
| First Solar |
| SolRecycle |
| Reclaim PV Recycling |
| Veolia Environnement SA |
| We Recycle Solar |
| The Retrofit Companies |
| Solarcycle |
| Others |
Supply Flow & Price Mechanics
Silver recovery yields from crystalline silicon cells trace volatile commodity markets through processor margin tiers, with hydrometallurgical operators commanding premium pricing against mechanical shredders serving landfill-diversion buyers.
Pricing Analysis
Cost-down pressure on mechanical separation tiers accelerates because aluminum and glass commodity values compress baseline recovery economics. Three-tier pricing structure across semiconductor-grade, technical-grade, and bulk material recovery levels separates hydrometallurgical purification from thermal treatment from mechanical shredding. Certification under EU WEEE Directive compliance documentation and REACH substance thresholds commands 15-25% premiums over non-certified collection services. Pricing pressure stems from copper and silver spot market volatility eroding forward contract viability. Utility-scale solar farm operators exhibit highest price sensitivity, while panel manufacturers seeking closed-loop silicon supply show least elasticity.
Supply Chain Analysis
Skilled technician availability in Germany, China, and India constrains furnace system throughput and hydrometallurgical line expansion. Processing equipment manufacturing concentrates in Germany and China, while high-purity chemical reagents for semiconductor-grade recovery draw from Belgian and Japanese specialty suppliers. Supply chain risk centers on single-source dependency for cadmium-telluride thermal recovery furnace technology controlled by First Solar's captive systems. Distribution runs through Veolia's European waste logistics network and emerging regional collection partnerships in India and the southwestern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor-grade silicon purification capacity lags feedstock availability, propping processor margins and creating acquisition premiums for qualified operators.
For Market Incumbents: To counter emerging hydrometallurgical specialists in China, Veolia and Reiling GmbH should anchor multi-year collection-processing contracts with German utility-scale operators and pursue backward integration into chemical purification capabilities through technology licensing rather than greenfield development. For New Entrants and Emerging Players: Capture India's decommissioning wave ahead of domestic infrastructure maturation by partnering with Rajasthan and Gujarat solar park operators for collection-only contracts, then upgrading to integrated processing through CSIR laboratory technology transfer agreements. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydrometallurgical specialists with semiconductor-grade output certification in Germany and China, where EU WEEE Directive quotas guarantee feedstock volumes. Long-term viability hinges on circular supply relationships with photovoltaic and electronics manufacturers. Watch silver price recovery as inflection signal for processor margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Semiconductor-grade silicon output commands premium pricing from electronics manufacturers seeking circular supply. |
| EU WEEE Directive Compliance Certification | Documentation capabilities unlock German utility-scale contracts and cross-border material flows from neighboring states. |
| India Collection Network Partnership | Rajasthan and Gujarat solar park relationships secure feedstock ahead of domestic processing infrastructure buildout. |
| Cadmium-Telluride Thermal Recovery Licensing | Technology access breaks First Solar's captive closed-loop monopoly for thin-film module recycling. |
| REACH Purification Upgrade Investment | Heavy metal content reduction maintains material market access under tightening European substance restrictions. |
Methodological Framework
Document review covered EU WEEE Directive implementation reports, EPA hazardous waste classification guidance, China MEE solid waste regulations, and photovoltaic decommissioning databases, complemented by interviews with recycling plant operations managers, utility-scale solar asset owners, EPC contractor procurement leads, and hazardous waste logistics coordinators. Secondary validation drew from customs trade data for recovered aluminum and glass flows, SEC filings for diversified waste management operators, and national solar association retirement forecasts. Bottom-up feedstock volume estimates triangulated against top-down market size calculations.
Segment-level revenue and volume trajectories across the projection horizon reflect crystalline silicon, thin-film, bifacial, and concentrated photovoltaic module chemistries crossed with mechanical, thermal, chemical, and hydrometallurgical recovery methods. Modeled inputs included retirement schedules from 2000s-era installations, EU recovery quota compliance timelines, and China domestic recycling mandate enforcement intensity. CAGRs derived from regression against historical commodity metal price cycles and processing capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silver and copper price volatility, REACH substance threshold revisions, and India infrastructure buildout delays. Forecasts reflect assumptions around EU WEEE Directive quota maintenance and China MEE enforcement continuity. Material deviation in precious metal markets or extended producer responsibility timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
E-Waste Management Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Release Liner Recycling Market