
 North America E-Waste Management Market | 2026-2036
North America E-Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Waste Management Market Insights
The EPA's R2 certification standard is broadening the cost-of-entry calculus for new e-waste processors across the United States. Waste Management Inc. leverages its national collection network to sustain volume throughput at scale. Republic Services anchors its competitive position through integrated logistics that span collection, transport, and downstream sorting. Clean Harbors Inc. differentiates via specialized handling capabilities for hazardous components found in legacy electronics.
North America e-waste management encompasses the systematic collection, disassembly, recovery, and disposal of discarded electrical and electronic equipment containing precious metals, rare earth elements, and toxic substances such as lead, mercury, and cadmium. The sector operates through pyrometallurgical, hydrometallurgical, and mechanical processing routes to extract copper, gold, palladium, and aluminum while neutralizing environmental contaminants. Consumer electronics and IT equipment together constitute the dominant material intake streams, with IT equipment commanding premium recovery economics due to higher concentrations of recoverable precious metals. Automated recovery technology is gaining traction as labor costs rise and throughput requirements intensify, though manual dismantling persists for complex assemblies where component integrity drives resale value.
EPA enforcement actions, California's SB-20 e-waste recycling fee structure, and Ontario's Waste Electrical and Electronic Equipment Program collectively shape processor economics and collection obligations across the region. These frameworks mandate producer responsibility, restrict landfill disposal of specified devices, and establish downstream due diligence requirements that favor certified operators over informal channels. Stakeholders must track evolving extended producer responsibility legislation at the state and provincial level, as fragmented compliance landscapes will determine which processors can operate across jurisdictional boundaries without duplicating certification investments.
Market Dynamics
Enterprise IT refresh cycles are compressing from five-year to three-year intervals, flooding processors with high-value equipment containing recoverable precious metals while tightening compliance windows for certified destruction.
Growth Catalysts
- California's SB-20 fee structure:Producer responsibility mandates fund collection infrastructure, creating guaranteed feedstock volumes for certified processors operating within the state.
- Cloud data center decommissioning:Hyperscale operators are retiring server fleets on accelerated schedules, delivering concentrated streams of homogeneous IT equipment with premium metal recovery economics.
- Pyrometallurgical processing:High-temperature smelting routes are capturing complex printed circuit board assemblies that mechanical sorting cannot economically disassemble.
Market Restraints
- Rare earth price volatility:Neodymium and dysprosium spot markets swing unpredictably, undermining long-term recovery project economics for magnet-intensive electronics.
- Informal collector networks:Uncertified operators in Mexico divert material flows from formal channels, eroding fee-for-service revenue bases for compliant processors.
- Legacy cathode ray tube glass:Leaded funnel glass stockpiles lack viable downstream outlets, creating indefinite storage liabilities for facilities that accepted television monitors under earlier collection programs.
Strategic Opportunities
- Texas industrial corridor expansion:Centralized recycling parks near Dallas-Fort Worth offer rail-linked distribution advantages for processors serving Gulf Coast manufacturing returns.
- Electric vehicle battery preprocessing:End-of-life lithium-ion packs from automotive OEMs require specialized discharge and dismantling capabilities that generalist e-waste facilities currently lack.
- Ontario's WEEE program expansion:Provincial coverage is extending to small appliances and power tools, opening collection channel partnerships with big-box retailers previously outside scope.
Industry Challenges
- R2 certification audit cycles:Triennial recertification demands sustained documentation investment that strains mid-scale processors with limited compliance staff.
- Automated dismantling integration:Robotic disassembly cells require reconfiguration of facility layouts and retraining of manual sorting teams, creating operational friction during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Waste Management Market |
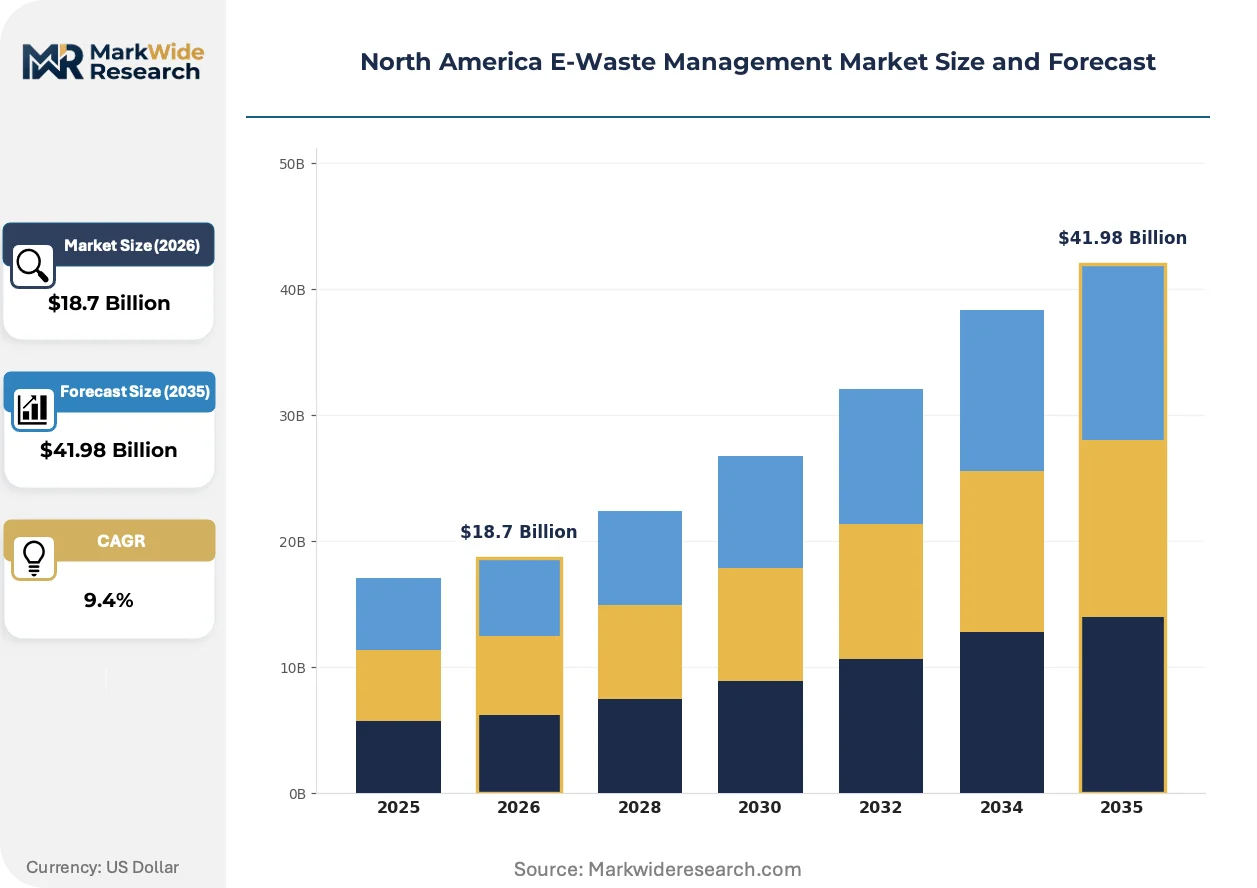
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, IT Equipment, Home Appliances, Lighting Equipment Service Type: Recycling, Repair, Refurbishment, Collection End User: Residential, Commercial, Institutional, Industrial Technology: Manual Dismantling, Automated Recovery, Plasma Arc, Chemical Processing |
| Companies Covered | Waste Management Inc., Waste Connections, Clean Harbors Inc., Republic Services Inc., Electronics Recycling International, Veolia Group, GEEP, Sims Recycling Solutions, Avnet, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Waste Management Market Trends and Innovations
Recovery technology is pivoting from labor-intensive manual disassembly toward automated mechanical routes, while regulatory frameworks harden downstream due diligence requirements that favor integrated operators over fragmented value chains.
Sensor-based sorting systems combining X-ray fluorescence and near-infrared detection are consolidating quality control functions previously handled by manual inspectors. Large processors serving enterprise IT asset disposition contracts are deploying these units to achieve throughput rates exceeding ten tons per hour. The technology is consolidating mid-tier dismantling operations that cannot amortize capital investment across sufficient volume bases.
EPA enforcement of the CRT Glass Test Rule is tightening export documentation requirements for cathode ray tube materials. Processors must now demonstrate legitimate recycling destinations through audited chain-of-custody records. California facilities handling legacy television inventories face the strictest compliance burdens, with state regulators conducting unannounced shipment inspections.
Certification-driven procurement is displacing price-first vendor selection among enterprise IT departments. Fortune 500 technology buyers now require R2 or e-Stewards credentials in master service agreements, filtering informal collectors from qualified bidder pools. The shift is most visible in financial services and healthcare verticals, where data security and environmental liability concerns dominate sourcing criteria.
North America E-Waste Management Market Segmentation
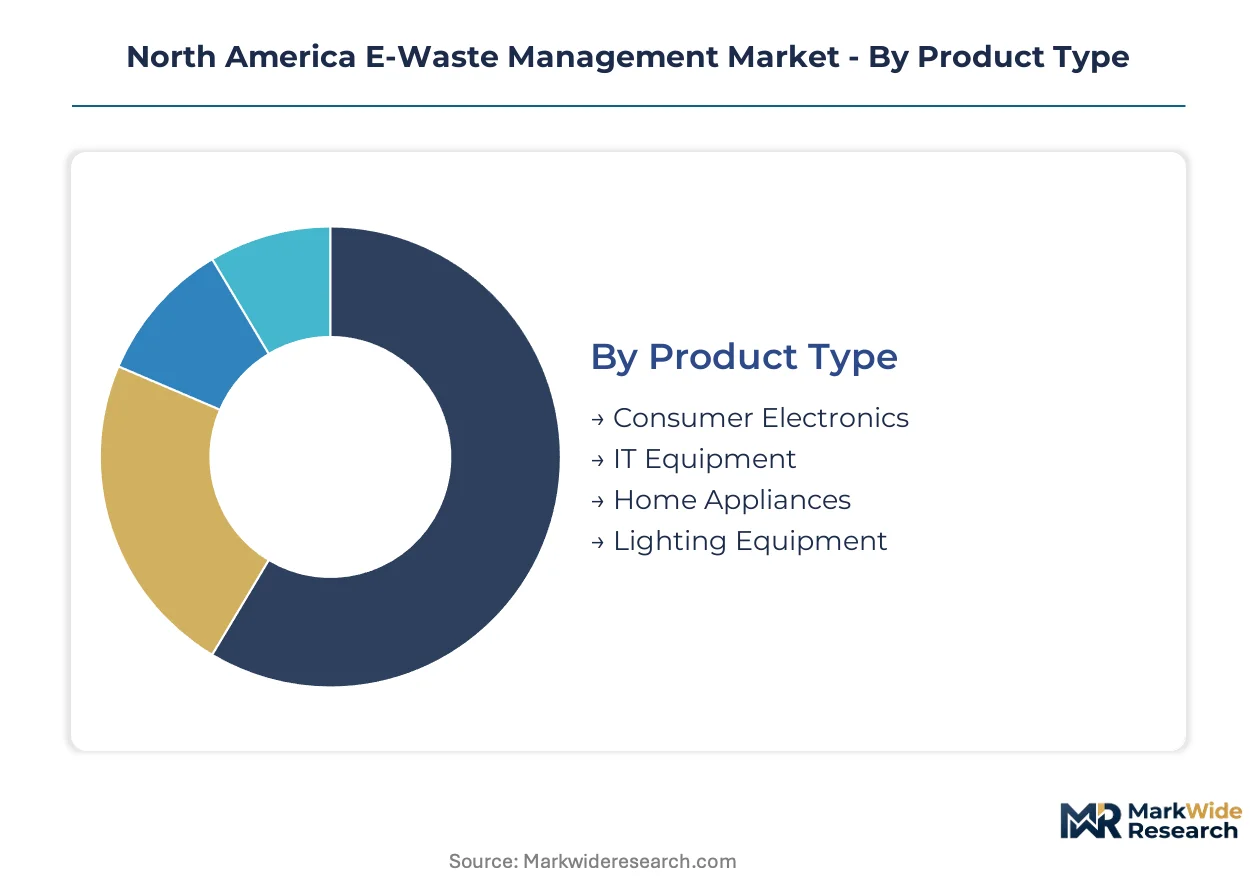
Segmentation in North American e-waste management reveals how recovery economics diverge across material streams and service models. Certified processors optimize facility configurations around the metal density and hazardous content profiles of specific intake categories.
Product Type:
Volume concentration favors consumer-facing categories, while premium recovery economics concentrate in enterprise-grade equipment with higher precious metal loadings.
- Consumer Electronics:Smartphones, tablets, and wearables deliver high unit volumes with moderate copper and gold concentrations per device. California and Texas collection networks handle the densest residential flows, though thin form factors complicate automated disassembly.
- IT Equipment:Servers, storage arrays, and networking hardware contain elevated palladium and gold densities in printed circuit board assemblies. Cloud data center decommissioning in Northern Virginia and Dallas-Fort Worth corridors supplies homogeneous streams that justify capital-intensive pyrometallurgical processing.
- Home Appliances:Refrigerators and washing machines yield bulk ferrous and aluminum fractions with limited precious metal content.
- Lighting Equipment:LED retrofits are displacing legacy fluorescent tube volumes, altering mercury-containing waste profiles.
Mature deployment sits with Consumer Electronics. Newer deployment is concentrated in IT Equipment.
Service Type:
Margin structure separates fee-for-service collection from value-capture recovery operations.
- Recycling:Smelting and hydrometallurgical extraction of copper, gold, and rare earth elements generates revenue from commodity sales rather than service fees. Ontario processors leverage rail-linked logistics to concentrate sufficient volume for standalone smelter economics.
- Collection:Curbside pickup and enterprise IT asset disposition contracts provide guaranteed feedstock access. Republic Services and Waste Management Inc. deploy national container networks to lock in municipal and corporate relationships ahead of downstream sorting investments.
- Repair:Component-level refurbishment extends device lifecycles for resale markets.
- Refurbishment:Functional testing and cosmetic grading target secondary electronics markets with lower certification requirements.
Established infrastructure dominates Collection. Steepest expansion trajectory belongs to Recycling as metal prices justify processing capacity additions.
End User:
Customer type determines compliance stringency and data security requirements that filter processor qualification.
- Commercial:Enterprise IT departments mandate R2 or e-Stewards certification in master service agreements, particularly in financial services and healthcare verticals. Three-year refresh cycles are compressing, delivering concentrated server and storage decommissioning volumes to qualified vendors.
- Residential:Household generators supply fragmented, low-density material flows captured through retailer take-back programs and municipal collection events. California's SB-20 fee structure funds infrastructure that guarantees processor feedstock regardless of commodity price swings.
- Institutional:Universities and government agencies balance procurement compliance with budget constraints.
- Industrial:Manufacturing returns and obsolete control systems require specialized handling for legacy hazardous components.
Contract maturity concentrates in Commercial. Fastest share gains are emerging in Residential as extended producer responsibility legislation expands coverage.
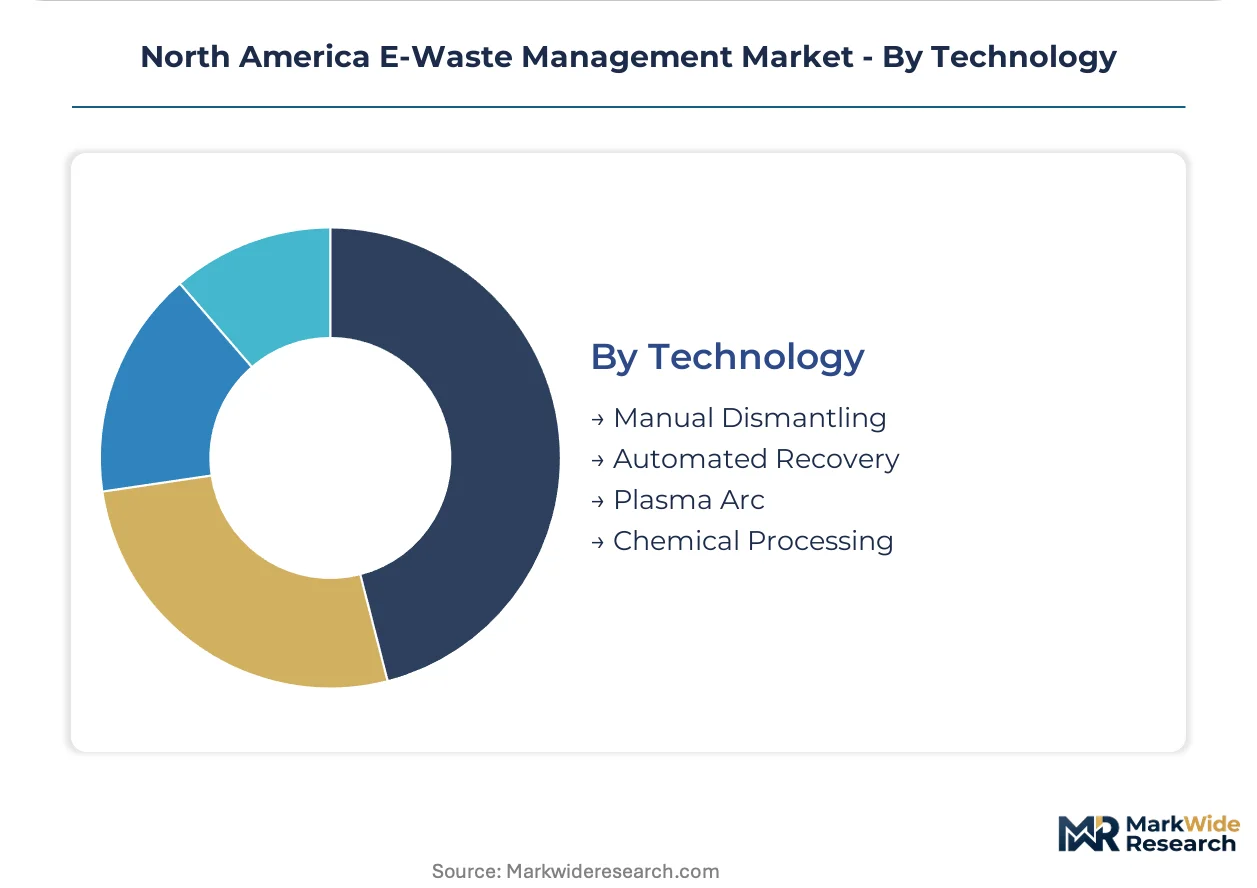
Technology:
Capital intensity and labor cost tradeoffs shape technology selection across facility scale tiers.
- Automated Recovery:X-ray fluorescence and near-infrared sorting systems achieve throughput rates exceeding ten tons per hour for homogeneous IT equipment streams. Large processors serving Fortune 500 asset disposition contracts deploy these units to consolidate quality control functions previously handled by manual inspectors.
- Manual Dismantling:Skilled technicians preserve component integrity for resale markets where intact circuit boards command premiums over shredded fractions. Complex assemblies from legacy industrial electronics resist robotic handling, sustaining labor-intensive operations at mid-scale facilities.
- Plasma Arc:High-temperature processing captures complex printed circuit board assemblies with elevated precious metal loadings.
- Chemical Processing:Hydrometallurgical routes target specific metal fractions with lower energy intensity than thermal alternatives.
Proven deployment clusters in Manual Dismantling. Technology transition is accelerating toward Automated Recovery as labor costs rise and throughput requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT decommissioning concentrates demand in coastal and Great Lakes corridors, while extended producer responsibility legislation drives infrastructure buildout in specific state and provincial jurisdictions.
United States
Cloud data center retirements in Northern Virginia and Dallas-Fort Worth deliver homogeneous server streams with premium metal recovery economics. EPA R2 certification mandates filter vendor pools for Fortune 500 asset disposition contracts. California's SB-20 fee structure funds collection infrastructure that guarantees processor feedstock regardless of commodity price swings.
Canada
Ontario's Waste Electrical and Electronic Equipment Program expansion captures small appliances and power tools through big-box retail partnerships. Provincial coverage mandates divert material from landfill toward certified channels. Toronto-Waterloo corridor processors leverage rail-linked logistics to concentrate sufficient volume for standalone smelter economics.
Mexico
Informal collector networks divert material flows from formal channels, eroding fee-for-service revenue bases for compliant processors. The country's national environmental regulator struggles to enforce e-waste handling standards across fragmented municipal jurisdictions. Mexico City Metro generates dense residential volumes lacking centralized sorting infrastructure.
North America E-Waste Management Market Competitive Landscape
United States producers anchor the integrated tier; Canadian specialists hold provincial collection mandates. The vendor base stratifies between national waste conglomerates with container networks and regional processors with hazardous handling credentials. Three archetypes dominate: scale-driven collectors, certification-heavy IT asset disposition firms, and hazardous materials specialists. Competitive moves concentrate on strategic partnerships with cloud operators and selective facility upgrades for battery preprocessing capabilities.
Within the integrated services tier, Waste Management Inc., Republic Services Inc., and Clean Harbors Inc. exemplify divergent positioning strategies. Waste Management Inc. leverages its national footprint to lock in municipal and corporate collection relationships. Republic Services Inc. occupies a position emphasizing logistics integration across transport and downstream sorting. Clean Harbors Inc. represents the hazardous handling archetype, with specialized capabilities for legacy electronics containing lead, mercury, and cadmium fractions.
| Leading Market Players |
|---|
| Waste Management Inc. |
| Waste Connections |
| Clean Harbors Inc. |
| Republic Services Inc. |
| Electronics Recycling International |
| Veolia Group |
| GEEP |
| Sims Recycling Solutions |
| Avnet |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists dominate mid-scale processing capacity across Texas and Ontario, concentrating ownership in entities that prioritize volume throughput over margin expansion and impose pricing discipline through centralized procurement of collection contracts.
Pricing Analysis
Premium pricing attaches to short lead-time collection windows for enterprise IT asset disposition, while spot inventory trades at discounted rates when processors hold excess cathode ray tube glass or legacy server stockpiles. Three-tier pricing structure across R2-certified premium, standard-certified mid-tier, and uncertified economy channels segments buyer pools. Cost compression in the economy tier is intensifying because informal Mexican collectors undercut compliant service fees. Residential generators exhibit highest price sensitivity; financial services verticals demonstrate lowest sensitivity due to data security mandates.
Supply Chain Analysis
Dual-sourcing requirements from Fortune 500 IT procurement teams mandate multi-processor qualification, preventing single-vendor lock-in across collection, transport, and downstream smelting stages. Feedstock draws from the United States, Canada, and Mexico, with California and Ontario anchoring formal collection infrastructure while Mexican informal channels divert material flows. Critical dependencies include copper concentrate offtake agreements, rare earth magnet separation capacity, and hazardous waste landfill access. Single-source vulnerability concentrates in pyrometallurgical smelting capacity. Distribution runs through rail-linked consolidation yards serving Great Lakes and Gulf Coast corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated recovery technology is displacing manual dismantling as the dominant processing paradigm, compressing the transition window for legacy operators.
For Market Incumbents: To counter margin erosion from robotic disassembly competitors, Waste Management Inc. and Republic Services Inc. should deepen backward integration into smelting capacity near Dallas-Fort Worth. Certification investment in R2 and e-Stewards credentials remains essential to defend enterprise IT contract access against emerging automated specialists. For New Entrants and Emerging Players: Direct-to-enterprise digital platforms offering real-time chain-of-custody documentation represent the most penetrable route into financial services and healthcare verticals. Target cloud data center decommissioning corridors in Northern Virginia for homogeneous server stream access. White-space opportunity concentrates in electric vehicle battery preprocessing capabilities that generalist facilities currently lack. For Investors and Strategic Acquirers: Accelerated EPA enforcement actions against CRT glass exporters are the leading indicator that certified downstream capacity will command scarcity premiums. Mid-scale processors with hazardous handling credentials and rail-linked logistics in Texas or Ontario represent optimal acquisition profiles. Watch for provincial WEEE program expansions into small appliances as the signal for retail collection channel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Disassembly Deployment | X-ray fluorescence sorting achieves ten tons per hour throughput for enterprise IT streams. |
| R2 Certification Investment | EPA enforcement actions filter informal competitors from Fortune 500 vendor pools. |
| Battery Preprocessing Capability | Automotive OEM lithium-ion packs require specialized discharge infrastructure generalists lack. |
| Rail-Linked Consolidation Yards | Toronto-Waterloo and Dallas-Fort Worth corridors enable standalone smelter economics. |
| Cloud Data Center Partnerships | Hyperscale decommissioning schedules deliver homogeneous server volumes with premium metal recovery. |
Research Methodology
Document review covered EPA enforcement records, California SB-20 fee structure documentation, and Ontario WEEE program expansion filings, complemented by interviews with certified e-waste processors, municipal solid waste directors, enterprise IT asset managers, and precious metals traders. Secondary validation drew from EPA R2 certification databases, state-level extended producer responsibility legislation trackers, and customs data on electronic scrap exports. Bottom-up facility capacity modeling and top-down commodity flow analysis enabled triangulation across independent estimation approaches.
Segment-level projections across product type, service type, end user, and technology dimensions were generated through the analysis window. CAGRs were derived from volume trajectory modeling incorporating IT refresh cycle compression rates, cloud data center decommissioning schedules, and provincial program expansion timelines. Forecast inputs included enterprise server shipment data, residential collection event frequency, and rare earth spot price volatility assumptions.
The model holds under stable EPA enforcement intensity and continued state-level producer responsibility adoption; deviation in Mexican informal channel penetration or rare earth price collapse would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
E-Waste Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
PET Bottle Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Recycling Equipment and Machinery Market