
 Global Pharmaceutical Waste Management Market | 2026-2036
Global Pharmaceutical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Waste Management Market Foresight
Advanced tracking and treatment technologies is tilting pharmaceutical waste management toward precision-based compliance systems. Stericycle leverages its North American infrastructure to sustain dominance in regulated medical waste collection networks. Veolia anchors its competitive position through integrated hazardous treatment facilities across multiple European jurisdictions. Clean Harbors competes on specialized incineration capacity for DEA-controlled substance destruction.
Pharmaceutical waste management encompasses the controlled collection, transportation, treatment, and final disposition of expired, contaminated, or unused pharmaceutical products, requiring thermal destruction temperatures exceeding 1,200°C for complete combustion of active pharmaceutical ingredients. The practice prevents environmental contamination and human exposure to potent compounds including cytotoxic agents, hormones, and antibiotics. Incineration technology leads the technology segment due to its proven efficacy in destroying drug potency, while biological treatment is gaining traction for biodegradable pharmaceutical residues where thermal methods prove energy-intensive. The hospitals end-user segment commands the largest service volume given continuous generation of chemotherapy waste, contaminated sharps, and bulk discarded medications from inpatient operations.
The EPA's Resource Conservation and Recovery Act provisions and the DEA's controlled substance disposal regulations shape operational requirements for US-based service providers, while the EU's REACH framework and F-Gas Regulation influence treatment technology selection across European markets. FDA guidance on disposal of unused medicines and WHO's technical guidelines on pharmaceutical waste create overlapping compliance layers that determine market access thresholds. Stakeholders must monitor emerging extended producer responsibility frameworks and traceability mandates that will redefine liability allocation between manufacturers and waste service providers.
Market Dynamics
Specialized incineration infrastructure is concentrating market power among operators capable of sustaining thermal destruction above 1,200°C while navigating overlapping EPA, DEA, and state-level pharmaceutical take-back mandates.
Growth Catalysts
- EMA environmental risk assessment guidelines:Germany's pharmaceutical manufacturers now face mandatory pre-market ecotoxicity screening, forcing investment in advanced disposal partnerships before product launch.
- Hospital chemotherapy waste volumes:Oncology expansion across tertiary care centers generates continuous streams of cytotoxic sharps and bulk discarded antineoplastics requiring specialized collection networks.
- DEA controlled substance destruction mandates:The Secure and Responsible Drug Disposal Act compels healthcare facilities to document witnessed incineration of Schedule II-V pharmaceuticals, institutionalizing third-party service contracts.
Market Restraints
- Natural gas price volatility:Thermal treatment facilities depend on consistent fossil fuel supply for sustained combustion temperatures, exposing margins to European energy market fluctuations.
- Permitting concentration in mature markets:New hazardous waste incinerator approvals cluster in jurisdictions with established EPA or ECHA frameworks, blocking market entry in regulatory lag regions.
- Biological treatment substitution limits:Enzymatic degradation methods fail to neutralize hormone disruptors and persistent pharmaceutical residues, restricting application scope for energy-efficient alternatives.
Strategic Opportunities
- India's CDSCO extended producer responsibility pilot:Draft frameworks for pharmaceutical manufacturer waste liability create first-mover advantage for integrated collection-treatment operators.
- WHO prequalification alignment:Developing country health systems adopting international disposal standards generate demand for compliant service exports from certified operators.
- Reverse logistics digitization:Blockchain-tracked pharmaceutical take-back programs enable real-time chain-of-custody documentation for DEA and EPA audit defense.
Industry Challenges
- Specialized technician scarcity:Qualified hazardous materials handlers capable of managing cytotoxic exposure protocols remain concentrated in established US and EU markets.
- Legacy EHR integration friction:Hospital waste tracking systems require costly middleware development to connect pharmacy inventory platforms with external disposal documentation portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Waste Management Market |
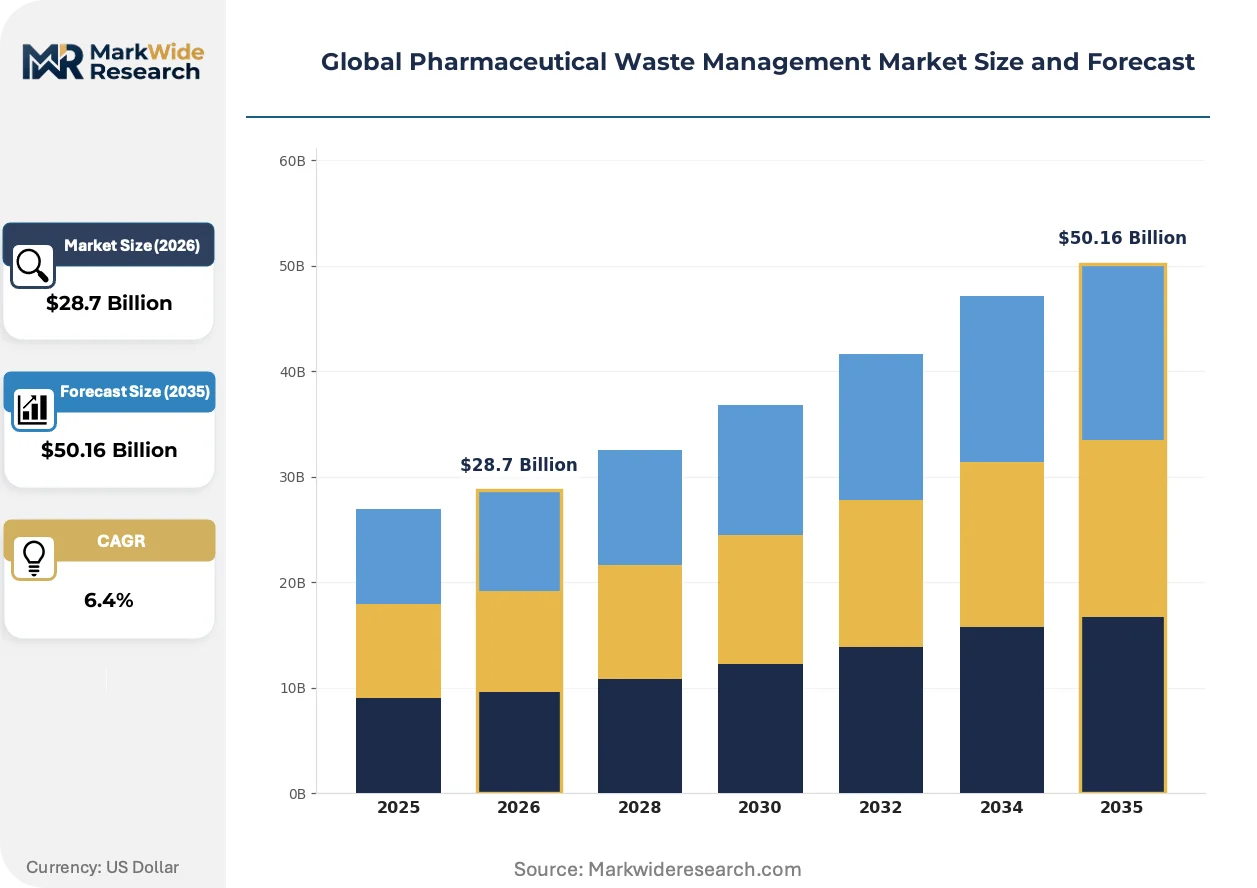
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Disposal, Recycling, Treatment End User: Hospitals, Pharmacies, Clinics, Laboratories Technology: Incineration, Chemical, Biological, Landfill Packaging Type: Containers, Bags, Drums, Boxes |
| Companies Covered | Stericycle, Veolia, Clean Harbors, Waste Management, Republic Services, SUEZ, Covanta, GFL Environmental, MedPro Disposal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Waste Management Market Shifts & Advancements
Plasma arc and superheated steam technologies are compressing treatment timelines while regulatory traceability mandates force digitization across custody chains. These shifts favor capital-intensive operators with integrated compliance infrastructure.
Advanced oxidation processes are migrating from municipal water treatment into pharmaceutical waste streams. European chemical manufacturers now pilot photocatalytic degradation for antibiotic residues previously routed to incineration. This migration from thermal to chemical neutralization is compressing energy costs per ton treated while demanding new chemist staffing models.
The EPA's forthcoming pharmaceutical hazardous waste generator improvements rule will reclassify many healthcare facilities from "very small quantity generators" to stricter regulatory tiers. Industrial consequence includes mandatory biennial reporting and container management standards. Hospital systems in California and New York are responding by consolidating waste contracts under single-source national providers.
Consolidated service agreements are displacing fragmented point solutions across integrated delivery networks. Pharmacy benefit managers now bundle disposal compliance into formulary contracts, forcing standalone waste vendors toward sub-contractor status. This concentration is most visible in US metropolitan hospital clusters where IDN purchasing power dominates procurement decisions.
Global Pharmaceutical Waste Management Market Segmentation
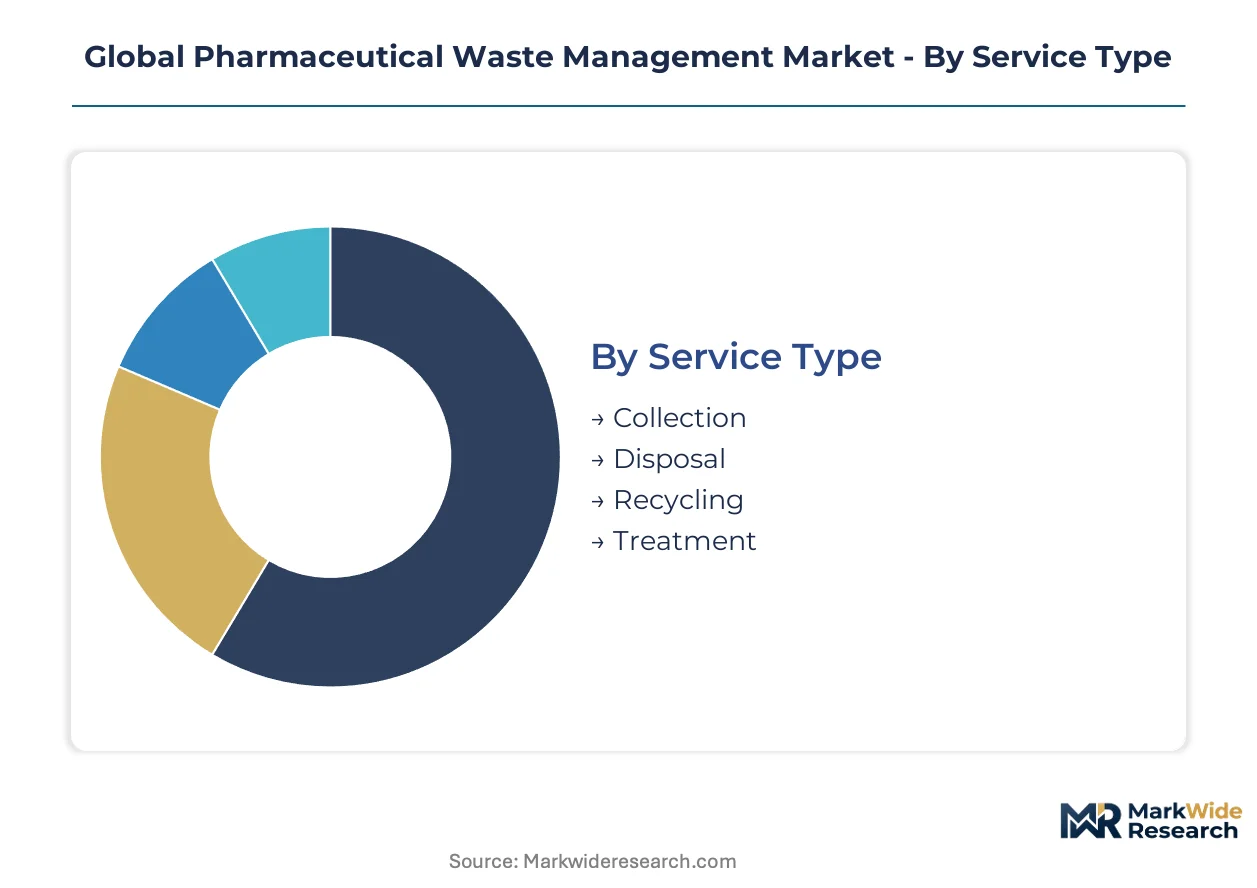
Pharmaceutical waste management segmentation reflects divergent compliance cycles and capital intensity across service delivery models. Collection and treatment modalities operate on fundamentally different equipment replacement timelines and regulatory recertification schedules.
Service Type:
Collection contracts turn over quarterly as hospitals rebid for route density, while treatment infrastructure cycles span decades with permitting bottlenecks.
- Collection:Scheduled pickup services for expired medications and contaminated materials use specialized vehicles with GPS-tracked chain-of-custody documentation. Demand clusters in US metropolitan hospital clusters where DEA witnessed destruction mandates require frequent scheduled service. Germany's EMA-aligned facilities drive premium pricing for temperature-controlled cytotoxic transport.
- Disposal:Final disposition encompasses landfill diversion for non-hazardous residues and secure burial protocols for chemically inert pharmaceutical solids. US EPA Subtitle D municipal landfill restrictions and EU Waste Framework Directive hazardous classifications determine routing decisions.
- Recycling:Active pharmaceutical ingredient recovery from bulk manufacturing waste streams.
- Treatment:Thermal and chemical neutralization processes destroying drug potency.
Collection dominates installed base. Treatment is where expansion concentrates.
End User:
Volume scale separates high-throughput inpatient generators from fragmented outpatient sources with sporadic disposal needs.
- Hospitals:Continuous generation of chemotherapy sharps, bulk discarded antineoplastics, and controlled substance destruction from DEA-registered pharmacies. Oncology expansion across tertiary care centers in the United States and Germany sustains dedicated collection infrastructure investment.
- Pharmacies:Retail and institutional dispensaries managing consumer take-back programs and expired inventory.
- Clinics:Outpatient surgical and infusion centers with intermittent sharps and medication waste.
- Laboratories:Research and quality control facilities generating solvent-contaminated debris and analytical samples.
Hospitals anchor revenue concentration. Pharmacies represent the steepest expansion trajectory as take-back mandates broaden.
Technology:
Capital deployment intensity varies tenfold between thermal destruction and passive containment methods.
- Incineration:Rotary kiln and fixed-hearth systems sustaining temperatures above 1,200°C for complete API combustion. Germany's federal emission standards and US EPA maximum achievable control technology requirements drive continuous scrubber upgrades.
- Chemical:Advanced oxidation and neutralization reactions for liquid pharmaceutical waste streams.
- Biological:Enzymatic degradation and composting for biodegradable residues with limited hormone disruptor efficacy.
- Landfill:Secure engineered containment for chemically inert solid waste meeting EPA Subtitle C or EU hazardous waste acceptance criteria.
Incineration commands the largest capital deployment. Chemical methods are gaining share fastest as energy costs reshape operating economics.
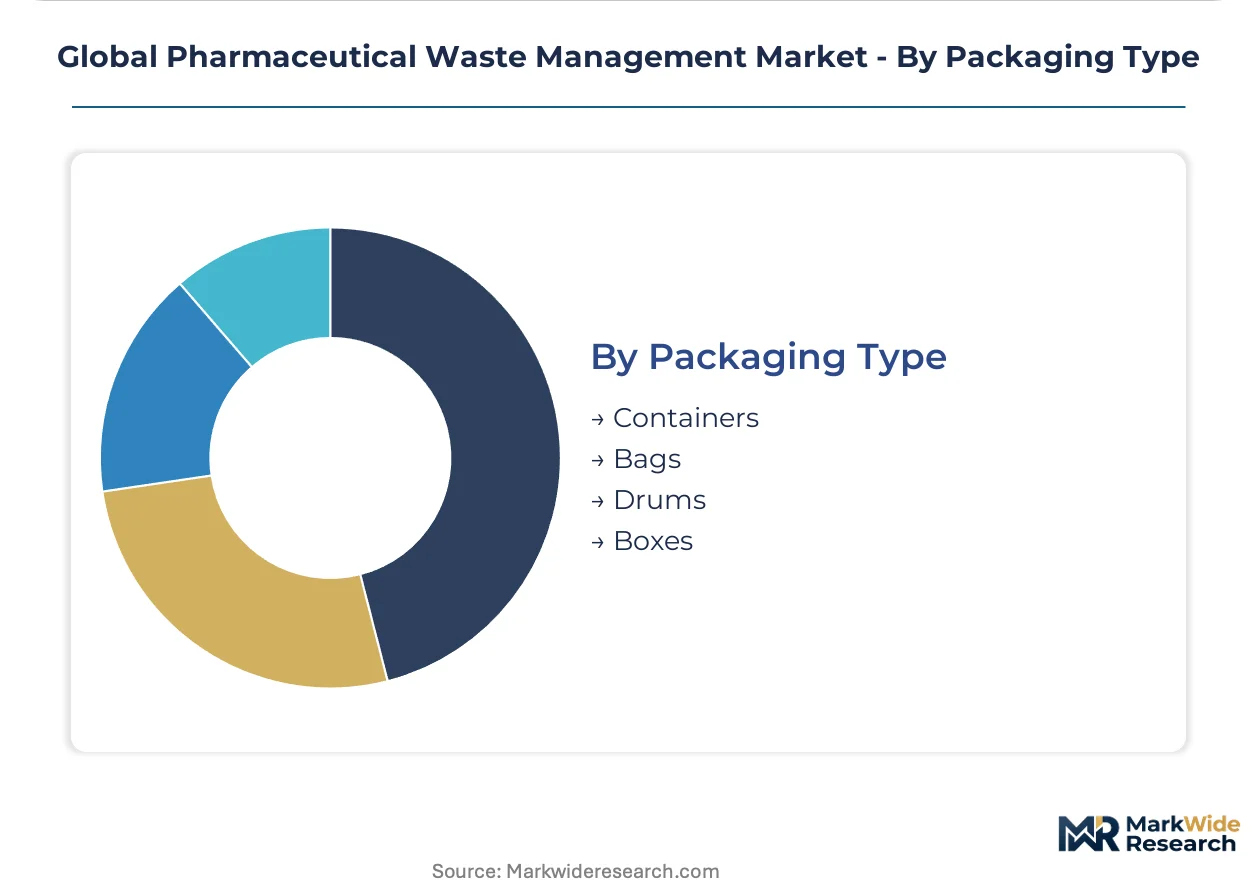
Packaging Type:
Regulatory labeling and containment specifications drive material selection across custody chain handoffs.
- Containers:Rigid puncture-resistant receptacles for sharps and cytotoxic materials with UN-certified transport ratings.
- Bags:Chemotherapy-rated polyethylene assemblies for soft waste with color-coded segregation protocols.
- Drums:Steel and fiber bulk containers for manufacturing-scale pharmaceutical residues.
- Boxes:Corrugated assemblies for non-hazardous expired medications in consumer take-back programs.
Containers absorb the highest unit economics. Bags are expanding most quickly in oncology service lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized incineration technology and compliance consulting services to pharmaceutical manufacturers across Central and Eastern Europe, establishing a trade corridor that shapes regional infrastructure investment patterns.
United States
Oncology expansion at tertiary care centers in Houston and Boston generates continuous cytotoxic waste streams requiring witnessed destruction protocols. The DEA's Secure and Responsible Drug Disposal Act mandates documented incineration for Schedule II-V substances, institutionalizing third-party service contracts. California and New York hospital systems are consolidating waste agreements under single-source national providers ahead of EPA generator reclassification rules.
Germany
EMA environmental risk assessment guidelines force pharmaceutical manufacturers to invest in advanced disposal partnerships before product launch. The federal emission standards and Waste Framework Directive drive continuous scrubber upgrades at rotary kiln facilities. The Rhine-Ruhr industrial corridor hosts the densest concentration of integrated hazardous treatment plants serving both domestic manufacturers and cross-border Austrian and Swiss clients.
India
CDSCO's extended producer responsibility pilot programs for pharmaceutical manufacturer waste liability are creating first-mover opportunities for integrated collection-treatment operators. The Central Pollution Control Board's hazardous waste management rules are tightening enforcement in Maharashtra and Gujarat. Mumbai and Ahmedabad pharmaceutical clusters are contracting specialized vendors for cytotoxic and antibiotic residue handling previously managed through informal channels.
Japan
PMDA guidance on environmental risk assessment for new drug applications is aligning domestic manufacturers with OECD ecotoxicity testing protocols. METI's industrial waste management regulations mandate manifest documentation for pharmaceutical residues from manufacturing and clinical settings. The Kanto region around Tokyo maintains the highest density of licensed medical waste incinerators serving both domestic demand and export-oriented pharmaceutical producers.
United Kingdom
NHS England's sustainable procurement standards are embedding waste minimization requirements into pharmaceutical supply contracts. The Environment Agency's hazardous waste regulations enforce strict tracking for cytotoxic and cytostatic materials from oncology units. The Greater Manchester and London hospital networks are piloting consolidated reverse logistics programs for expired medication take-back from community pharmacies.
Global Pharmaceutical Waste Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates treatment capacity among capital-intensive operators while fragmenting collection services geographically. Three tiers have emerged: integrated hazardous waste conglomerates with multi-jurisdictional incineration networks, regional medical waste specialists with dense route coverage in metropolitan hospital clusters, and technology licensors selling plasma arc and advanced oxidation equipment to third-party operators. Dominant competitive moves include vertical integration of collection assets into treatment facilities and strategic partnerships between waste service providers and pharmacy benefit managers for formulary-linked compliance bundling.
Within the integrated conglomerate tier, Stericycle and Veolia occupy positions that exemplify divergent geographic anchoring strategies. Stericycle represents North American route density concentration, while Veolia sits within the European multi-jurisdictional treatment facility archetype. Clean Harbors anchors the specialized incineration segment for controlled substance destruction requirements.
| Leading Market Players |
|---|
| Stericycle |
| Veolia |
| Clean Harbors |
| Waste Management |
| Republic Services |
| SUEZ |
| Covanta |
| GFL Environmental |
| MedPro Disposal |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial corridor anchors European thermal treatment capacity, concentrating high-temperature incineration infrastructure that commands premium pricing for cytotoxic waste streams requiring witnessed destruction protocols. This geographic clustering creates asymmetric pricing power where operators with DEA and EMA dual-certification capture margin premiums from hospital systems facing generator reclassification deadlines.
Pricing Analysis
Prior-generation rotary kiln incineration, current-generation plasma arc systems, and next-generation superheated steam technologies stratify service pricing across three performance tiers. Contract-based long-term offtake agreements dominate hospital procurement, with price differentiation driven by certification level (EPA maximum achievable control technology vs. standard compliance) and volume scale (tertiary oncology centers vs. outpatient clinics). Cost compression in standard thermal treatment is intensifying because natural gas price volatility erodes margins at fixed-hearth facilities. Retail pharmacy take-back programs exhibit highest price sensitivity due to sporadic waste volumes, while integrated delivery networks demonstrate lowest sensitivity given bundled formulary compliance requirements.
Supply Chain Analysis
Upstream feedstock flows from pharmaceutical manufacturing clusters in Germany, India, and the United States determine collection route economics and treatment facility utilization rates. The supply chain draws from specialized container manufacturers (UN-certified puncture-resistant receptacles), natural gas distributors for combustion temperature maintenance, and licensed hazardous materials transport fleets. Single-source vulnerability concentrates in European natural gas supply for thermal destruction, with German facilities particularly exposed to pipeline disruption. Distribution runs through hub-and-spoke networks where metropolitan hospital clusters feed regional treatment plants, while reverse logistics digitization is compressing chain-of-custody documentation costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma arc and advanced oxidation process commercialization is disrupting incineration-dominated competitive dynamics, while EPA generator reclassification rules compress contracting timelines for hospital procurement consolidation.
For Market Incumbents: Harden DEA-witnessed destruction service contracts through backward integration into pharmacy benefit manager partnerships, insulating against standalone vendor displacement. Expand rotary kiln capacity in Texas and Massachusetts oncology corridors ahead of tertiary care center waste volume surges. Pursue EMA environmental risk assessment pre-certification to capture German pharmaceutical manufacturer pre-launch disposal partnerships. For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical manufacturing clusters offer underpenetrated cytotoxic and antibiotic residue handling demand as CDSCO extended producer responsibility frameworks displace informal channels. Target WHO prequalification alignment for compliant service exports to developing country health systems adopting international disposal standards. Deploy blockchain-tracked take-back programs as differentiated DEA audit defense for mid-sized hospital systems lacking legacy EHR integration resources. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because permitting concentration in mature EPA and ECHA jurisdictions creates durable moats against new entrant supply addition. Acquisition focus should center on regional medical waste specialists with dense metropolitan route coverage and pending DEA registration upgrades. Monitor EPA pharmaceutical hazardous waste generator improvements rule implementation pace as inflection indicator for hospital contract consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Assets | Captures route density economics and DEA chain-of-custody control from fragmented vendors. |
| Plasma Arc Technology Deployment | Compresses treatment timelines below 1,200°C thermal thresholds while satisfying EPA maximum achievable control technology requirements. |
| Pharmacy Benefit Manager Partnership | Locks formulary-linked disposal compliance bundling into integrated delivery network procurement decisions. |
| EMA Pre-Certification Investment | Secures German pharmaceutical manufacturer partnerships before mandatory environmental risk assessment product launches. |
| Blockchain Traceability Implementation | Enables real-time chain-of-custody documentation for DEA and EPA audit defense in consolidated service agreements. |
Research Methodology
A spread of perspectives from hospital procurement managers, hazardous waste facility operators, pharmaceutical regulatory affairs leads, and pharmacy benefit manager formulary directors converged on the working assumptions driving this analysis. Primary intelligence combined structured interviews with secondary validation against EPA hazardous waste generator databases, DEA controlled substance destruction manifests, EMA environmental risk assessment filings, and EU Waste Framework Directive implementation reports. Bottom-up service contract value analysis triangulated against top-down pharmaceutical manufacturing waste coefficient modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type (collection, treatment, disposal), end-user category (hospitals, pharmacies, laboratories), and technology generation (incineration, chemical, biological). CAGRs derived from facility capacity utilization trajectories and regulatory mandate implementation schedules, incorporating oncology expansion rates at tertiary care centers and extended producer responsibility framework adoption curves as pharmaceutical waste management-specific forecast inputs.
Practitioners should monitor EPA generator reclassification rule finalization timing, European natural gas price volatility, and CDSCO extended producer responsibility pilot expansion for early signals requiring forecast revision. Cross-checking against WHO technical guidelines on pharmaceutical waste and OECD ecotoxicity testing protocol adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market