
 Sleep Apnea Implants Market | 2026-2036
Sleep Apnea Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Apnea Implants Market Analysis
Remote patient monitoring and therapy adjustment subscriptions is shifting how implantable sleep apnea devices generate recurring revenue beyond the initial surgical placement. Inspire Medical Systems leverages its proprietary physician training network to sustain high implant volume growth across its installed base. Nyxoah anchors European market development through CE-marked neurostimulation systems designed for outpatient procedures. LivaNova competes on surgical robotics integration, positioning its implant platforms within broader ENT workflow solutions.
Sleep apnea implants are biocompatible electronic devices, typically incorporating platinum-iridium electrodes and titanium housings, that deliver targeted neurostimulation to upper airway musculature to maintain patency during sleep. Their primary commercial purpose is to treat moderate-to-severe obstructive sleep apnea in patients who fail or abandon positive airway pressure therapy. Implantable stimulators command premium pricing and margin pools due to their durable hardware and required surgical implantation expertise. Neurostimulation technology leads clinical adoption, while adaptive servo-ventilation applications address the smaller but complex central sleep apnea segment where implant alternatives to mask-based therapies are gaining investigator interest.
FDA premarket approval requirements and EU MDR technical documentation standards shape device development timelines, clinical evidence thresholds, and market access conditions for manufacturers seeking multi-regional commercialization. The country's national pharmaceutical regulator in Japan and Health Canada also evaluate neurostimulation implants through comparable safety and efficacy frameworks, creating parallel compliance obligations. Stakeholders must monitor reimbursement coding decisions and real-world evidence requirements that determine whether implant volumes scale beyond early-adopter sleep centers into community hospital settings.
Market Dynamics
Reimbursement pathway maturation for hypoglossal nerve stimulation is compressing the gap between clinical validation and community hospital adoption, forcing manufacturers to rebuild commercial infrastructure around outpatient procedural economics rather than academic center volume.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review timelines for novel neurostimulation implants accelerate patient access and de-risk development investments for manufacturers targeting moderate-to-severe OSA populations.
- Platinum-iridium electrode biocompatibility:Advanced materials science extending device longevity beyond ten years reduces replacement surgery burden and strengthens value-based reimbursement arguments.
- Sleep clinic network expansion:Dedicated implant programs across tertiary care centers in the United States build procedural volume and physician training pipelines independent of device manufacturer direct investment.
Market Restraints
- Titanium supply concentration:Device housing fabrication depends on aerospace-qualified titanium suppliers with limited medical-grade capacity, exposing manufacturers to input cost volatility and allocation risk.
- EU MDR technical documentation:Enhanced clinical evidence requirements for active implantable devices extend approval timelines and force portfolio prioritization decisions that delay market entry for secondary indications.
- CPAP therapy persistence:Mask-based positive airway pressure retains first-line guideline status and insurer preference, constraining eligible patient pools to documented PAP failures or intolerances.
Strategic Opportunities
- Central sleep apnea neurostimulation:Adaptive servo-ventilation implant applications represent an underserved pathophysiology with no durable hardware alternatives and limited pharmaceutical competition.
- Remote therapy adjustment platforms:Cloud-based stimulation parameter optimization enables recurring revenue models and reduces in-person sleep lab dependency for post-implant management.
- Health Canada parallel approval:Streamlined recognition of FDA PMA data accelerates North American commercialization without redundant clinical trials, expanding addressable populations beyond United States borders.
Industry Challenges
- ENT-surgical skill scarcity:Hypoglossal nerve dissection and electrode placement demand specialized training that outpaces fellowship program output, creating procedural bottleneck risks as implant volumes scale.
- Real-world evidence collection infrastructure:Payer demands for post-market outcome validation require manufacturers to fund patient registries and data interoperability investments not captured in initial device pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Apnea Implants Market |
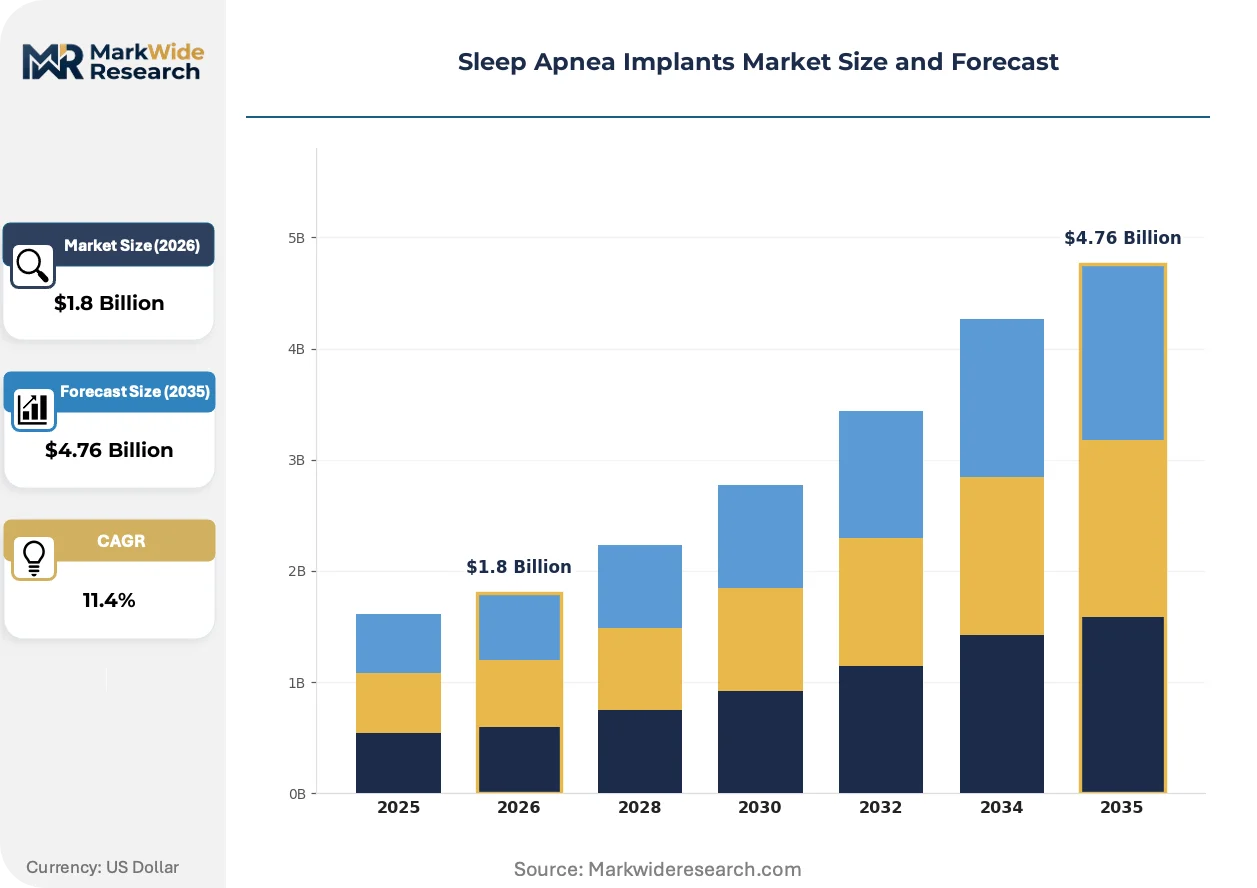
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Stimulators, CPAP, Oral Appliances, Adjustable Devices Technology: Neurostimulation, Adaptive Servo-Ventilation, Bilevel Positive Airway Pressure, Continuous Positive Airway Pressure End User: Home Care Settings, Hospitals, Sleep Clinics, Rehabilitation Centers Application: Obstructive Sleep Apnea, Central Sleep Apnea, Complex Sleep Apnea, Others |
| Companies Covered | Inspire Medical Systems, Nyxoah, LivaNova, Medtronic, ZOLL Medical Corporation, Respicardia, Siesta Medical, Avery Biomedical Devices, Pillar Palatal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Apnea Implants Market Emerging Trajectories
Neurostimulation hardware is converging with digital health infrastructure, reshaping how implantable sleep apnea therapies are prescribed, monitored, and reimbursed across ambulatory and inpatient settings.
Closed-loop respiratory sensing algorithms are converging with implantable pulse generator architectures to enable automatic stimulation adjustment based on real-time airflow detection rather than fixed timing protocols. Sleep medicine practices in the United States are piloting these systems through investigator-initiated trials ahead of regulatory submission. This convergence is compressing the distinction between implantable devices and continuous diagnostic monitors, forcing manufacturers to defend data ownership and cybersecurity liability positions.
EU MDR post-market surveillance requirements are mandating systematic implant registry participation and periodic safety reporting that exceeds FDA PMA conditions for active implantable devices. Manufacturers must rebuild quality management systems around unique device identification traceability and vigilance case processing timelines measured in days rather than months. The neurostimulation segment is responding by consolidating notified body relationships and pre-positioning clinical evidence packages for class III device recertification.
Patient acquisition economics are shifting from specialist referral dependence toward direct-to-consumer education and telehealth screening pathways that compress time-to-diagnosis for PAP-intolerant candidates. Sleep centers are unbundling diagnostic polysomnography from implant candidacy assessments, replacing bundled reimbursement with discrete coding that rewards efficiency. This behavioral pivot is most visible in United States markets where high-deductible health plans have sensitized patients to out-of-pocket costs and accelerated demand for durable alternatives to nightly therapy adherence.
Sleep Apnea Implants Market Segmentation
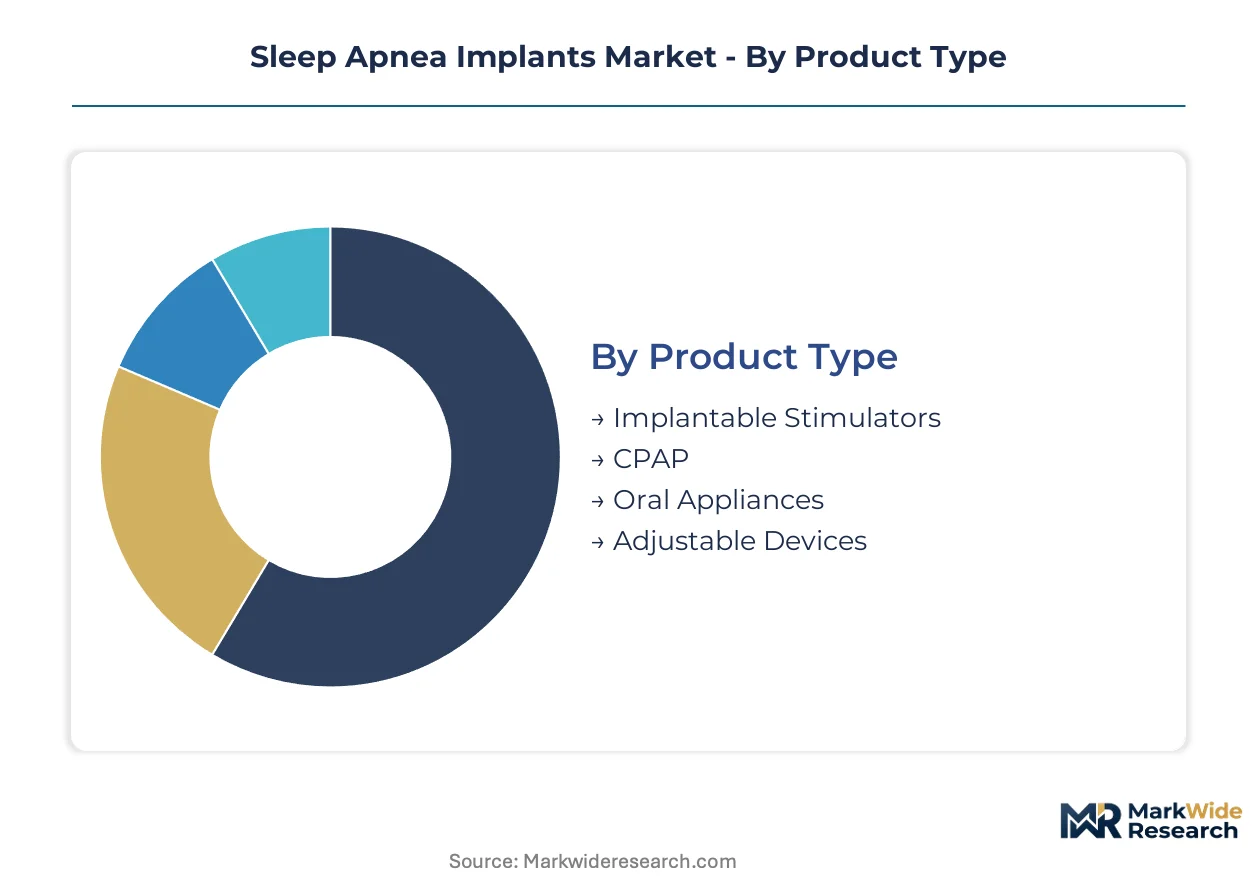
Device segmentation in sleep apnea implants determines reimbursement coding, surgical workflow integration, and patient candidacy pathways. Manufacturers align product portfolios with specific technology tiers and care settings to capture volume across academic medical centers and ambulatory surgery environments.
Product Type:
Replacement cycles and upgrade pathways differ materially across hardware categories, with implantable stimulators commanding decade-long utilization horizons against disposable alternatives.
- Implantable Stimulators:Biocompatible electronic systems incorporating platinum-iridium electrodes and titanium housings deliver targeted hypoglossal neurostimulation. Demand concentrates in United States tertiary care centers where FDA PMA pathways and Category III CPT codes have matured; device longevity beyond ten years strengthens value-based contracting arguments with commercial payers.
- CPAP:Mask-based positive airway pressure systems remain first-line therapy per clinical guidelines, constraining implant-eligible pools to documented failures. Volume dominates in home care settings where insurer preference and lower acquisition costs sustain market presence despite adherence challenges.
- Oral Appliances:Mandibular advancement devices address mild-to-moderate obstructive sleep apnea through dental repositioning.
- Adjustable Devices:Custom-fit hardware with incremental modification capabilities bridges non-invasive and surgical intervention thresholds.
Volume placements concentrate in CPAP systems; the faster expansion belongs to implantable stimulators.
Technology:
Cost tier differentiation separates premium closed-loop architectures from standard fixed-parameter systems, with reimbursement spreads widening between adaptive and conventional modalities.
- Neurostimulation:Closed-loop respiratory sensing algorithms enable automatic stimulation adjustment based on real-time airflow detection. United States sleep medicine practices pilot these systems through investigator-initiated trials ahead of regulatory submission; automatic parameter optimization reduces in-person sleep lab dependency.
- Adaptive Servo-Ventilation:Servo-controlled pressure support addresses central sleep apnea pathophysiology with no durable hardware alternatives. European adoption leads through CE-marked outpatient systems; limited pharmaceutical competition creates pricing leverage for implant manufacturers.
- Bilevel Positive Airway Pressure:Dual-level pressure delivery supports patients with ventilatory insufficiency or elevated CO2 retention.
- Continuous Positive Airway Pressure:Fixed-pressure delivery remains the standard comparator in clinical trials evaluating implant efficacy.
Revenue pools favor neurostimulation platforms; adaptive servo-ventilation claims the steepest expansion trajectory as central apnea indications mature.
End User:
Customer type fragmentation reflects divergent procurement authority, with hospital systems negotiating enterprise contracts against individual physician ownership in sleep clinic settings.
- Sleep Clinics:Dedicated implant programs build procedural volume and physician training pipelines independent of manufacturer direct investment. United States network expansion accelerates as reimbursement pathways compress the gap between academic validation and community adoption.
- Hospitals:Inpatient and ambulatory surgical departments capture implant placement revenue through bundled procedural economics. Operating room scheduling constraints and ENT-surgical skill scarcity create bottleneck risks as volumes scale beyond fellowship program output.
- Home Care Settings:Durable medical equipment suppliers manage CPAP and oral appliance distribution with remote monitoring subscriptions.
- Rehabilitation Centers:Post-acute facilities address sleep-disordered breathing in neurological and stroke recovery populations.
Procedure economics concentrate in sleep clinics; hospitals are gaining share fastest through robotics-integrated surgical platforms.
Application:
Application maturity varies by pathophysiology, with obstructive sleep apnea commanding established clinical evidence and central sleep apnea representing frontier indications.
- Obstructive Sleep Apnea:Upper airway collapse during sleep affects moderate-to-severe populations who fail or abandon positive airway pressure therapy. United States demand concentrates among PAP-intolerant candidates sensitized to out-of-pocket costs under high-deductible health plans.
- Central Sleep Apnea:Ventilatory control instability creates an underserved pathophysiology with no mask-based durable alternatives. Investigator interest in implantable adaptive servo-ventilation is accelerating clinical trial investments ahead of regulatory submission.
- Complex Sleep Apnea:Mixed pathophysiology presentations require multimodal intervention strategies.
- Others:Residual category captures emerging indications including treatment-emergent central apnea and comorbid insomnia-sleep apnea syndromes.
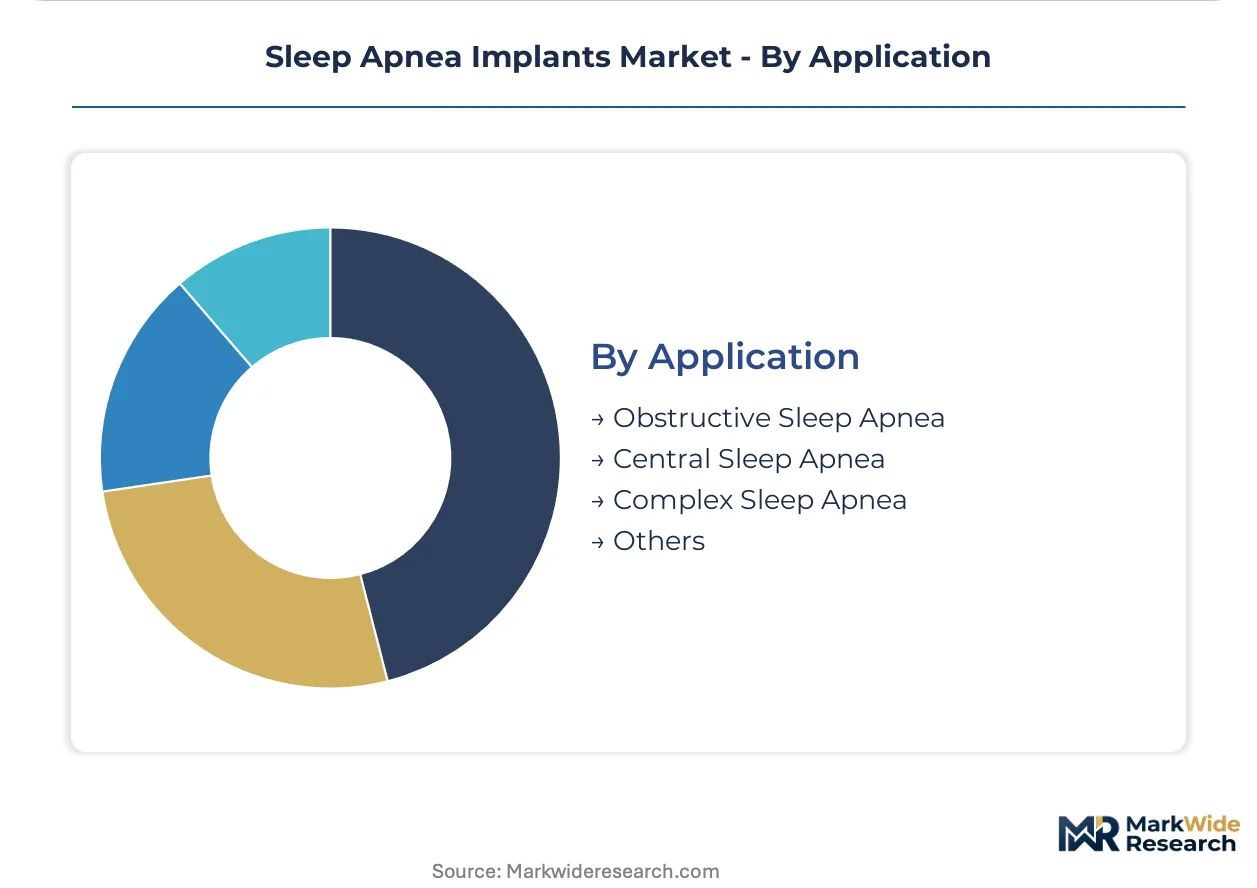
Commercial volume concentrates in obstructive sleep apnea; central sleep apnea is climbing the fastest as neurostimulation indications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors the United States implant ecosystem where Inspire Medical Systems maintains its headquarters and physician training network. Sleep clinics across the Upper Midwest corridor generate procedural volumes that validate reimbursement pathways for community hospital adoption.
United States
FDA premarket approval pathways and Category III CPT coding have matured reimbursement for hypoglossal nerve stimulation beyond academic centers. The Medicare physician fee schedule now covers outpatient implant placement, accelerating volume migration from tertiary hospitals to ambulatory surgery centers in Texas and Florida.
Germany
EU MDR technical documentation requirements and notified body recertification timelines shape market access for active implantable devices. The Rhine-Ruhr metropolitan region hosts specialized sleep medicine centers in Düsseldorf and Cologne that pilot CE-marked neurostimulation systems ahead of broader European rollout.
Japan
PMDA marketing authorization frameworks evaluate neurostimulation implants through comparable safety and efficacy standards to FDA PMA processes. Tokyo and Osaka academic medical centers conduct investigator-initiated trials for closed-loop respiratory sensing algorithms, generating clinical evidence for national reimbursement submissions.
Canada
Health Canada parallel approval mechanisms recognize FDA PMA data, eliminating redundant clinical trials for North American commercialization. Ontario and Quebec sleep clinic networks in Toronto and Montreal build implant program infrastructure that leverages United States training protocols and procedural economics.
Switzerland
Swissmedic medical device regulations align with EU MDR standards while maintaining distinct vigilance reporting requirements for active implants. Zurich and Geneva university hospitals participate in multinational post-market surveillance registries that track long-term neurostimulation outcomes across Alpine region patient populations.
Sleep Apnea Implants Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the sleep apnea implant landscape, with vertically integrated neurostimulation specialists facing asset-light digital health platforms. The market structure concentrates around three to five dominant hardware manufacturers while surgical robotics integrators and remote monitoring software vendors fragment the adjacent service layer. Strategic archetypes include implantable device pure-plays, diversified medtech conglomerates with ENT portfolios, and emerging closed-loop algorithm developers. Competitive moves center on physician training network expansion and cloud-based therapy adjustment platform development.
Within the neurostimulation pure-play tier, Inspire Medical Systems and Nyxoah exemplify divergent geographic strategies, with the former anchoring United States market development through proprietary training infrastructure and the latter occupying a position in European outpatient procedural economics. LivaNova represents the diversified medtech archetype, sitting within broader ENT workflow solutions that integrate implant platforms with surgical robotics systems.
| Leading Market Players |
|---|
| Inspire Medical Systems |
| Nyxoah |
| LivaNova |
| Medtronic |
| ZOLL Medical Corporation |
| Respicardia |
| Siesta Medical |
| Avery Biomedical Devices |
| Pillar Palatal |
| Others |
Supply Flow & Price Mechanics
Device-grade certification bifurcation between FDA PMA-approved neurostimulation implants and CE-marked outpatient systems manifests in divergent pricing architectures and supply chain configurations across North American and European markets. Premium-tier hardware commands titanium-forged housings and platinum-iridium electrode assemblies sourced through aerospace-qualified suppliers, while standard-tier alternatives leverage modular designs with shorter validation cycles and distributed component sourcing.
Pricing Analysis
Margin tightening in implantable stimulator tiers reflects titanium supply allocation constraints and EU MDR compliance cost absorption. The dominant pricing structure rests on value-based contracting tied to decade-long device longevity claims, with differentiation separating FDA PMA-certified systems from CE-marked alternatives and aftermarket service bundles from bare hardware transactions. Pricing pressure accelerates in standard-tier segments as outpatient procedural economics compress acquisition budgets, while academic medical centers exhibit lowest price sensitivity due to bundled reimbursement pathways.
Supply Chain Analysis
Specialized ENT-surgical workforce scarcity in Germany, Switzerland, and Japan constrains implant volume scaling despite manufacturing capacity expansion. Device fabrication draws from titanium suppliers in the United States and Germany, platinum-iridium electrode specialists in Japan, and pulse generator assemblers in South Korea. Single-source vulnerability concentrates in aerospace-qualified titanium forging capacity. Distribution runs through hospital procurement committees and GPO contracts in the United States, with direct manufacturer-to-clinic relationships dominating European outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleep apnea implant sector occupies a technology-transition phase where closed-loop respiratory sensing algorithms displace fixed-parameter neurostimulation protocols, forcing stakeholders to recalibrate around digital health integration and remote therapy management capabilities.
For Market Incumbents: Anticipate regulatory arbitrage opportunities as Health Canada parallel approval mechanisms and EU MDR recertification timelines create temporary market access gaps. Deepen backward integration into platinum-iridium electrode supply through captive relationships with Japanese materials specialists. Fortify position against algorithm-centric entrants by accelerating cloud-based therapy adjustment platform deployment and expanding proprietary physician training networks beyond academic anchor institutions.
For New Entrants and Emerging Players: Sleep clinic network partnerships in Texas and Florida offer the most penetrable entry vector given Medicare outpatient coverage expansion and ambulatory surgery center volume migration. Target central sleep apnea adaptive servo-ventilation applications where no durable hardware alternatives exist and pharmaceutical competition remains limited. Pursue go-to-market angles through telehealth screening platforms that compress time-to-diagnosis for PAP-intolerant candidates.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medtech conglomerates seeking ENT workflow integration. Long-term viability hinges on five-to-ten year reimbursement durability and real-world evidence registry participation. Watch FDA breakthrough device designation velocity as the inflection indicator signaling accelerated patient access and de-risked development investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Category III CPT code maturation accelerates Medicare outpatient coverage expansion beyond academic centers. |
| Hospital System Partnership | Enterprise contracts with Texas and Florida ASC networks capture volume migration from tertiary hospitals. |
| Software Companion Development | Cloud-based stimulation parameter optimization enables recurring revenue and reduces sleep lab dependency. |
| CE Marking Pathway | EU MDR technical documentation compliance opens Rhine-Ruhr metropolitan region pilot programs. |
| Physician Training Network | Proprietary fellowship pipelines address ENT-surgical skill scarcity constraining implant volume scaling. |
Methodological Framework
Multi-period observation of FDA PMA submission timelines, EU MDR recertification cycles, and Medicare reimbursement coding decisions anchored the trend analysis, supplemented by interviews with sleep medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare physician fee schedule updates, ClinicalTrials.gov neurostimulation trial registries, and EU notified body technical documentation databases. Bottom-up implant volume modeling and top-down market sizing triangulated across manufacturer-reported placement data and payer claims analysis.
Segment-weighting approaches applied technology-tier differentiation between closed-loop and fixed-parameter systems, geographic regulatory clustering across FDA, EU MDR, PMDA, and Health Canada frameworks, and end-user procurement authority splits between hospital systems and independent sleep clinics. CAGRs derived from logistic adoption curve modeling calibrated to reimbursement pathway maturation velocity. Forecast inputs incorporated ENT fellowship program output trajectories and titanium supplier capacity allocation patterns.
Caveats apply where FDA breakthrough device designation delays, EU MDR notified body backlogs, or titanium supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions around reimbursement durability and real-world evidence collection infrastructure scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Smart Syringe Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Pen Needles Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Smart Bassinet Market
Medical Devices
Dialysis Catheters Market