
 Global Body Composition Analyzers Market | 2026-2036
Global Body Composition Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Composition Analyzers Market Foresight
Cloud-connected software subscription tiers for longitudinal body composition tracking is realigning how vendors monetize hardware deployments. InBody Co. Ltd. leverages its proprietary algorithm ecosystem to lock in gym chain renewals across Asia and North America. GE Healthcare anchors its hospital-installed base through integrated EMR connectivity and radiology workflow compatibility. Tanita Corporation competes on consumer channel density, with retail scale in Japan and expanding pharmacy distribution in Europe.
Body composition analyzers are devices that measure fat mass, lean tissue, bone mineral content, and total body water using electrical impedance, X-ray attenuation, acoustic reflection, or infrared absorbance, typically reporting segmental distributions with precision thresholds of one to five percent depending on modality. Their primary commercial purpose spans metabolic risk screening in clinical settings, athletic conditioning optimization, and nutritional intervention validation in research protocols. BIA analyzers occupy the highest volume tier due to portability and sub-thousand-dollar price points, while DEXA scanners command the margin pool through reimbursement-linked bone density and visceral adipose quantification. Fitness Assessment applications are expanding fastest among end-user segments as boutique studios and franchise chains standardize member onboarding protocols around quantified baseline metrics.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern clinical claims for body fat percentage and visceral fat grading, compelling manufacturers to fund predicate-device equivalence studies or new clinical validation trials. China's NMPA now requires domestic registration for connected health devices transmitting biometric data to cloud platforms, adding compliance layers for imported systems. Japan's PMDA maintains distinct software-as-medical-device classifications that affect how algorithm updates reach installed units. Stakeholders must monitor whether emerging WHO guidelines on obesity diagnostic thresholds trigger recalibration demands across device firmware and reclassification of existing product registrations.
Market Dynamics
Cloud-native body composition platforms are restructuring vendor revenue models away from one-time hardware sales toward recurring software subscriptions, compressing payback periods while extending customer lifetime value through longitudinal data lock-in.
Growth Catalysts
- Preventive health infrastructure:Germany's statutory health insurance reforms now reimburse biometric screening for metabolic syndrome risk, driving clinical procurement of DEXA and BIA systems in outpatient cardiology networks.
- CE marking under EU MDR:Tightened clinical validation requirements for body fat percentage claims are filtering out uncertified competitors, concentrating demand among predicate-device holders with established equivalence studies.
- Franchise fitness standardization:Boutique studio chains across the United States and China are mandating quantified member onboarding protocols, creating pull-through for connected analyzers with API-ready data exports.
Market Restraints
- Semiconductor input volatility:Precision analog-to-digital converters and bioelectrode sensor arrays face supply concentration from Taiwanese foundries, exposing BIA manufacturers to 12-16 week lead time extensions.
- DEXA reimbursement compression:US Centers for Medicare & Medicaid Services rate-setting for bone density screening has flattened since 2019, constraining hospital capital allocation toward higher-margin imaging modalities.
- Air displacement plethysmography:BOD POD systems offer comparable body fat precision without ionizing radiation, capturing research protocol share from DEXA in North American university settings.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives for electronics hardware are attracting contract assembly partnerships for BIA systems targeting tier-2 city diagnostic chains.
- Home-based metabolic monitoring:Post-pandemic remote patient management protocols are creating demand for consumer-grade analyzers with physician dashboard integration, bypassing traditional clinic workflows.
- AI-driven segmental analysis:Machine learning models trained on MRI reference datasets are enabling smartphone-camera body composition estimation, threatening to democratize access below $50 price points.
Industry Challenges
- Firmware recertification timelines:Algorithm updates that alter body fat calculation methods trigger fresh FDA 510(k) submissions, delaying feature rollouts by 8-14 months.
- EMR integration complexity:HL7 FHIR interoperability requirements vary across Epic, Cerner, and Meditech installations, forcing vendors to maintain multiple API connector configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Composition Analyzers Market |
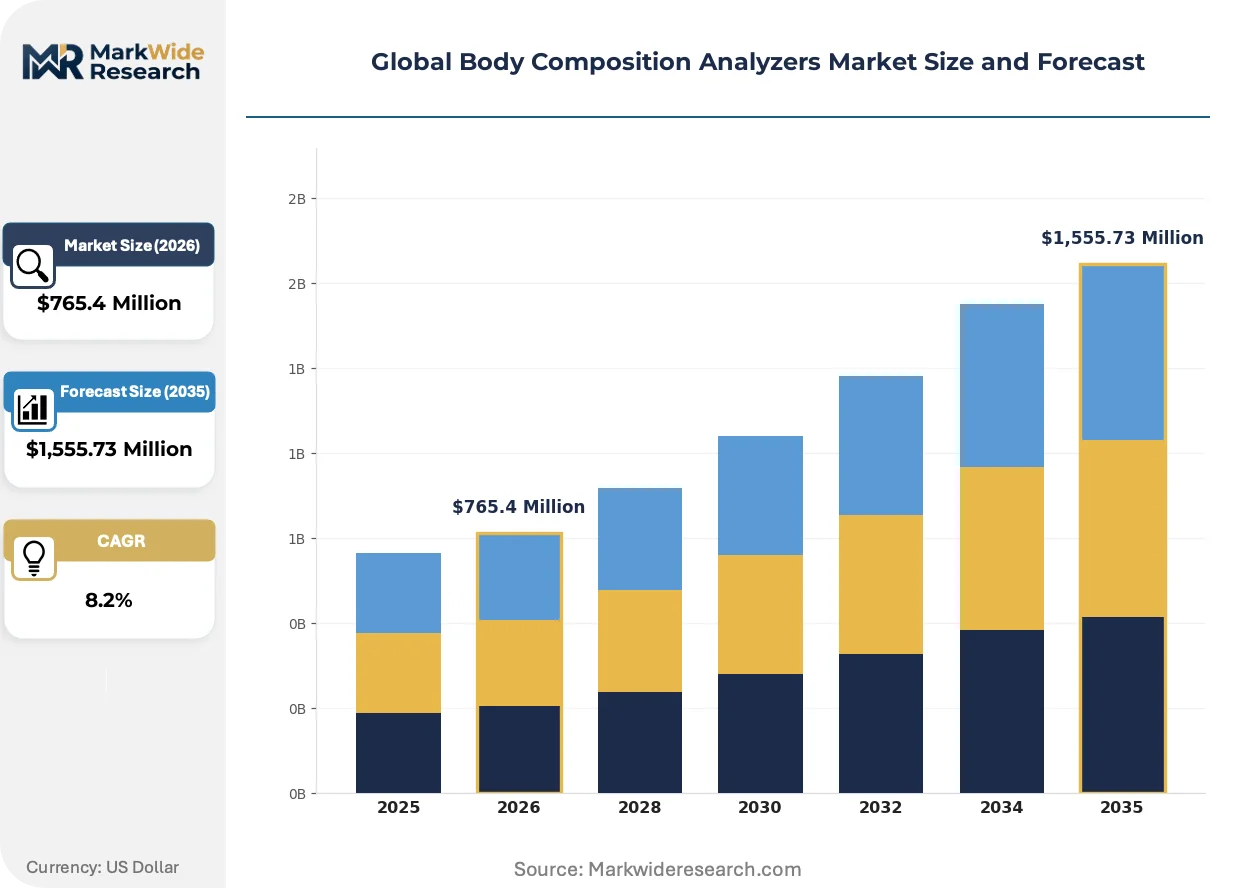
| Market Size in 2026 | $765.4 Million |
| Market Size in 2035 | $1,555.73 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BIA Analyzers, DEXA Scanners, MRI Systems, Ultrasound Devices, Infrared Devices Application: Fitness Assessment, Nutritional Evaluation, Clinical Diagnosis, Sports Performance, Research Studies End User: Hospitals, Fitness Centers, Research Institutes, Physical Therapy Clinics, Wellness Centers Technology: Bioelectrical Impedance, Dual-energy X-ray Absorptiometry, Magnetic Resonance Imaging, Ultrasonography, Near-infrared Spectroscopy |
| Companies Covered | InBody Co. Ltd., GE Healthcare, Hologic Inc., Omron Healthcare, Tanita Corporation, Bodystat Ltd, COSMED Srl, Seca GmbH & Co. KG, Jawon Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Composition Analyzers Market Shifts & Advancements
Multi-frequency bioelectrical impedance analysis is compressing the accuracy gap with DEXA while preserving portability, enabling point-of-care deployment models that bypass centralized radiology workflows entirely.
Multi-frequency BIA is electrifying competitive positioning in the fitness segment. Devices emitting current at 1, 5, 50, 250, 500, and 1000 kHz now resolve extracellular and intracellular water compartments with three-percent precision. Corporate wellness programs at Fortune 500 headquarters are standardizing on these systems for quarterly employee health assessments. The technology is electrifying vendor margin structures by attaching $40-60 monthly SaaS tiers to sub-$800 hardware.
Japan's PMDA software-as-medical-device classification is reshaping how algorithm updates reach installed analyzers. Cloud-connected units transmitting raw impedance data to central servers for calculation now require pre-market approval for each model revision. Manufacturers with domestic regulatory affairs teams in Tokyo are compressing update cycles to 90 days versus 240 days for import-dependent competitors. Hospital-installed bases in Osaka and Fukuoka are consolidating around vendors with captive PMDA submission capabilities.
Boutique fitness studios are unbundling hardware procurement from membership management software, fragmenting vendor relationships that previously bundled both. Independent studios in Brooklyn, Berlin, and Shanghai now source BIA devices from specialized hardware suppliers while subscribing to third-party data visualization platforms. This pattern is most visible in urban markets where studio density exceeds 15 locations per million residents, forcing hardware vendors to expose raw API endpoints or lose placement to interoperable alternatives.
Global Body Composition Analyzers Market Segmentation
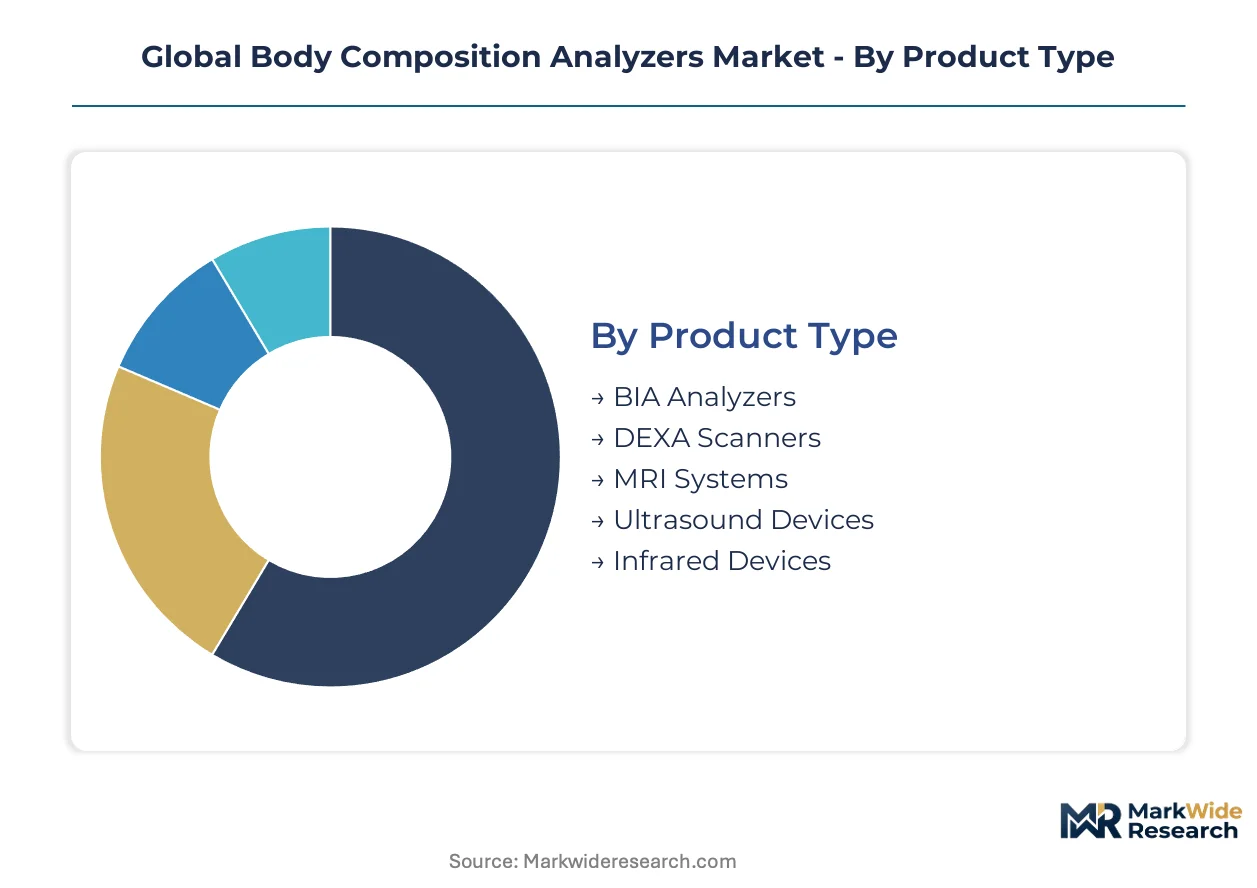
Segmentation in body composition analyzers determines procurement pathways, reimbursement eligibility, and software integration requirements. Buyers select modalities based on accuracy thresholds, regulatory clearance status, and connectivity architecture rather than hardware cost alone.
Product Type:
Buyers prioritize accuracy-to-cost ratios and regulatory clearance status when selecting hardware platforms.
- BIA Analyzers:Multi-frequency bioelectrical impedance devices measure extracellular and intracellular water compartments using currents from 1 kHz to 1000 kHz. Fitness centers in the United States and Germany standardize on these systems for member onboarding protocols that require sub-three-percent precision without ionizing radiation.
- DEXA Scanners:Dual-energy X-ray absorptiometry systems quantify bone mineral density, visceral adipose tissue, and regional fat distribution with sub-one-percent accuracy. Hospital outpatient networks in China and Japan concentrate procurement here for metabolic syndrome screening programs that tie reimbursement to diagnostic-grade measurements.
- MRI Systems:Magnetic resonance-based body composition quantification delivers reference-standard tissue segmentation without radiation exposure. Research institutes in Germany and the United States deploy these for longitudinal intervention studies requiring precise organ-level fat depot tracking.
- Ultrasound Devices:Portable ultrasonography units estimate subcutaneous fat thickness and muscle cross-sectional area at point-of-care. Physical therapy clinics in Japan adopt these for rehabilitation progress monitoring where radiation-free repeatability matters.
- Infrared Devices:Near-infrared spectroscopy analyzers estimate body fat through optical absorbance patterns at specific wavelengths. Wellness centers in China integrate these into consumer-facing health kiosks for population-scale screening campaigns.
Volume sits with BIA Analyzers; growth tilts toward DEXA Scanners.
Application:
End-use environments dictate accuracy requirements and connectivity specifications.
- Fitness Assessment:Baseline quantification and progress tracking for athletic conditioning and weight management programs. Boutique studio chains in the United States mandate standardized onboarding protocols that drive connected analyzer deployment with API-ready data exports.
- Nutritional Evaluation:Validation of dietary intervention outcomes through longitudinal body composition change tracking. Research institutes in Germany deploy these systems for controlled metabolic studies requiring precise lean mass preservation measurement.
- Clinical Diagnosis:Metabolic risk stratification and obesity-related comorbidity assessment in healthcare settings. Hospitals in China integrate these into preventive health infrastructure buildouts under national chronic disease management initiatives.
- Sports Performance:Athlete monitoring for training load optimization and injury risk reduction. Professional sports medicine networks in Japan and Germany concentrate demand here for segmental muscle balance assessment.
- Research Studies:Epidemiological data collection and intervention efficacy measurement in academic protocols. University medical centers in the United States deploy reference-grade systems for multi-site trial standardization.
Clinical Diagnosis commands installed base; Fitness Assessment climbs the fastest.
End User:
Facility type determines capital allocation cycles and software integration depth.
- Hospitals:Acute and outpatient care networks requiring EMR-integrated diagnostic systems with FDA or CE-marked clinical claims. Procurement concentrates in the United States and China for metabolic syndrome screening program expansion.
- Fitness Centers:Commercial gyms and boutique studios standardizing member experience around quantified baselines. Franchise chains in the United States and Germany drive connected platform adoption with subscription-linked hardware.
- Research Institutes:Academic medical centers and contract research organizations requiring reference-standard accuracy for publication-grade data. Demand clusters in Germany, Japan, and the United States for longitudinal intervention protocols.
- Physical Therapy Clinics:Rehabilitation facilities tracking muscle atrophy recovery and functional restoration progress. Japan's aging demographic drives adoption here for sarcopenia management programs.
- Wellness Centers:Corporate and community preventive health facilities offering biometric screening without diagnostic claims. China's tier-2 city expansion builds out this segment for population health management.
Installed base concentrates in Hospitals; Wellness Centers gain share fastest.
Technology:
Underlying measurement physics determines portability, cost structure, and regulatory pathway.
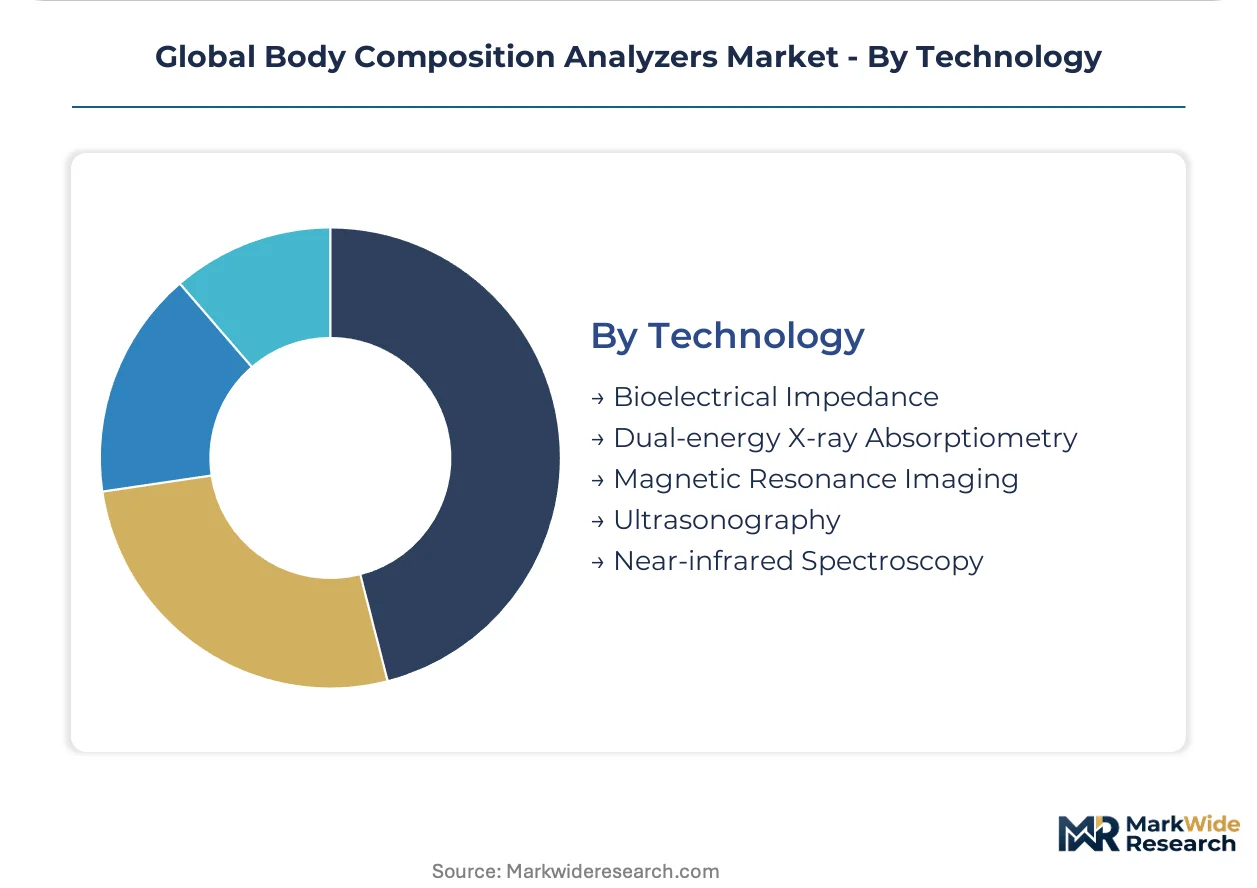
- Bioelectrical Impedance:Electrical current resistance through body tissues enables portable, radiation-free assessment. Multi-frequency architectures from InBody and Tanita dominate fitness and clinical point-of-care deployment.
- Dual-energy X-ray Absorptiometry:Differential X-ray attenuation through tissues delivers reference-standard precision for bone and adipose quantification. GE Healthcare and Hologic anchor hospital-installed bases through integrated radiology workflow compatibility.
- Magnetic Resonance Imaging:Nuclear magnetic resonance signal differentiation enables non-invasive tissue characterization without ionizing radiation. Siemens Healthineers and Philips systems serve research protocols requiring highest accuracy.
- Ultrasonography:Acoustic reflection patterns estimate tissue boundaries and muscle architecture. Portable units from Samsung Medison and Fujifilm serve rehabilitation and field-based sports medicine applications.
- Near-infrared Spectroscopy:Optical absorbance at specific wavelengths correlates with subcutaneous fat thickness. Consumer-grade implementations target pharmacy and wellness kiosk channels in Japan and Europe.
Deployment volume favors Bioelectrical Impedance; Dual-energy X-ray Absorptiometry holds margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Japan, South Korea, and Germany, while consumption pulls strongest from the United States, China, and clinical networks across Western Europe. This divergence creates trade flows in precision sensors and finished devices.
United States
Fitness Assessment applications drive procurement as boutique studio chains mandate standardized member onboarding protocols. FDA 510(k) clearance requirements for clinical-grade body fat claims filter out uncertified competitors. Hospital networks in Texas and Florida expand metabolic syndrome screening programs.
China
National chronic disease management initiatives build preventive health infrastructure in tier-2 cities. NMPA registration requirements for connected devices transmitting biometric data to cloud platforms add compliance layers for imported systems. Diagnostic chains in Chengdu and Wuhan concentrate BIA system deployment.
Germany
Statutory health insurance reforms reimburse biometric screening for metabolic syndrome risk. CE marking under EU MDR tightens clinical validation standards for body fat percentage claims. Outpatient cardiology networks in Bavaria and North Rhine-Westphalia drive DEXA procurement.
Japan
Aging demographics accelerate sarcopenia management programs in physical therapy clinics. PMDA software-as-medical-device classifications affect algorithm update cycles for cloud-connected units. Hospital-installed bases in Osaka and Fukuoka consolidate around vendors with captive regulatory affairs teams.
India
PLI scheme incentives for medical device electronics attract contract assembly partnerships. Domestic manufacturing capacity expands for BIA systems targeting tier-2 city diagnostic chains. Assembly operations concentrate in Gujarat and Karnataka for export-adjacent supply.
Global Body Composition Analyzers Market Competitive Landscape
Top-tier vendors anchor hospital-installed bases through integrated EMR connectivity, while mid-tier specialists compete on fitness channel density and SaaS attach rates. The structure splits between predicate-device holders with established equivalence studies and challengers pursuing boutique studio fragmentation. Strategic archetypes include algorithm-locked platform vendors, radiology workflow integrators, and consumer channel scale players. Dominant competitive moves span M&A for regulatory predicate acquisition and API ecosystem partnerships for data export standardization.
Within the platform-locked tier, InBody Co. Ltd. and Tanita Corporation exemplify divergent geographic anchoring strategies. GE Healthcare occupies a position among radiology-integrated system vendors. Hologic Inc. sits within the predicate-device holder archetype for diagnostic-grade claims.
| Leading Market Players |
|---|
| InBody Co. Ltd. |
| GE Healthcare |
| Hologic Inc. |
| Omron Healthcare |
| Tanita Corporation |
| Bodystat Ltd |
| COSMED Srl |
| Seca GmbH & Co. KG |
| Jawon Medical |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-cleared clinical systems and uncertified fitness devices manifests in both pricing power and supply chain sourcing strategies. Premium predicate-device holders command hardware margins fourfold above commodity BIA manufacturers while sourcing precision bioelectrode arrays from captive Japanese suppliers, whereas budget-tier competitors draw from Taiwanese foundry spot markets and absorb semiconductor volatility directly.
Pricing Analysis
Margin tightening in the fitness-tier BIA segment reflects semiconductor input volatility and SaaS attach-rate compression. Three-tier pricing structure across premium, standard, and economy levels separates DEXA hospital systems with reimbursement-linked contracts from multi-frequency BIA units with subscription bundling, then from single-frequency consumer devices sold through pharmacy retail. Price differentiation hinges on FDA 510(k) clearance status and EMR integration depth. Cost-down pressure on economy-tier hardware accelerates because raw bioelectrode sensor arrays face 12-16 week lead time extensions from Taiwanese foundry concentration. Research institutes exhibit lowest price sensitivity due to grant-funded procurement protocols, while independent boutique fitness studios negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Single-source vulnerability sits with precision analog-to-digital converter fabrication in Taiwan and South Korea. Manufacturing draws from Japan for algorithm-locked system assembly, Germany for DEXA scanner precision mechanics, and China for consumer-grade BIA plastic enclosures and circuit board population. Raw material dependencies include bioelectrode sensor arrays, multi-layer ceramic capacitors, and rare-earth phosphors for DEXA X-ray tubes. Supply chain risk centers on tariff exposure for Japanese-manufactured systems entering Chinese NMPA registration pathways. Distribution runs through hospital GPO contracts in the United States, diagnostic chain procurement offices in China, and fitness franchise headquarters in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR CE marking requirements for body fat percentage claims erect a cost-of-compliance barrier that filters out uncertified competitors and consolidates margin pools among predicate-device holders with established equivalence studies.
For Market Incumbents: Hedge algorithm obsolescence risk by accelerating PMDA software-as-medical-device registration capabilities in Tokyo, compressing firmware update cycles from 240 days to 90 days versus import-dependent rivals. Deepen backward integration into precision bioelectrode sensor production to offset Taiwanese foundry concentration and secure 16-week supply continuity buffers against semiconductor volatility. For New Entrants and Emerging Players: Smartphone-camera body composition estimation using MRI-trained machine learning models offers a technology-first wedge below fifty-dollar price points, threatening to democratize access and bypass hardware procurement entirely. Target India's tier-2 city diagnostic chains under PLI scheme incentives, where domestic manufacturing partnerships attract contract assembly relationships without established incumbent relationships. Pursue white-label API provision to fragmented boutique fitness studios in Brooklyn, Berlin, and Shanghai that unbundle hardware from membership management software. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-locked platform vendors given cloud-native subscription revenue models extending customer lifetime value through longitudinal data lock-in. Long-term viability favors vendors with captive regulatory affairs teams across FDA, CE marking, and PMDA jurisdictions, insulating against firmware recertification timeline delays that stall feature rollouts. Watch for WHO obesity diagnostic threshold guideline revisions as an inflection indicator triggering device firmware recalibration demands and product registration reclassification waves.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR tightened validation requirements filter uncertified competitors from body fat percentage claims. |
| Hospital System Partnership | Epic and Cerner EMR integration secures radiology workflow placement and procurement committee preference. |
| Software Companion Development | Cloud-connected SaaS tiers attach $40-60 monthly subscriptions to sub-$800 hardware deployments. |
| Reimbursement Strategy | Germany's statutory health insurance reforms now reimburse biometric screening for metabolic syndrome risk. |
| Regulatory Predicate Acquisition | M&A for FDA 510(k) cleared devices accelerates market entry without fresh clinical validation trials. |
Research Methodology
Multi-period observation of hardware shipment volumes, SaaS subscription attach rates, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital GPO contracts managers, fitness franchise procurement directors, and diagnostic chain operators. Secondary validation drew from FDA 510(k) clearance databases, NMPA registration filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up segment sizing triangulated against top-down macro health expenditure trends.
Input-output matrices modeled unit economics across product type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from segment-level growth rate assumptions weighted by installed base concentration and replacement cycle dynamics. Forecast inputs included semiconductor lead time trajectories, reimbursement rate-setting announcements, and regulatory guideline revision probabilities.
Several conditions sit outside the modeled scope, including unannounced algorithm breakthroughs obsoleting electrical impedance methods, abrupt WHO obesity threshold revisions, and geopolitical trade restrictions disrupting Japanese-Taiwanese component flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Skincare Devices Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Coil Assisted Flow Diverters Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Colposcopes Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
AI-enabled Medical Devices Market