
 Network Video Recorder (NVR) Market | 2026-2036
Network Video Recorder (NVR) Market Size, Share, and Industry Trends Forecast 2026-2036
Network Video Recorder (NVR) Market Analysis
Multi-source component procurement is realigning supply strategies across NVR manufacturers. Dahua Technology Co., Ltd. leverages in-house semiconductor sourcing to control chipset costs across its recorder lines. Hangzhou Hikvision Digital Technology anchors its position through vertical integration into camera sensor production. Axis Communications AB differentiates via open-platform software architecture that supports third-party analytics integration.
A Network Video Recorder is a specialized computing device that digitizes, compresses, and stores video streams from IP cameras using codecs such as H.265, typically supporting 4K resolution at 30 frames per second with RAID storage redundancy for forensic reliability. Its primary purpose is to provide centralized video retention, real-time playback, and event-triggered retrieval for security operations. Rack-mounted NVR configurations dominate enterprise and data center deployments where density and thermal management matter most. Cloud-based NVR adoption is accelerating among retail chains seeking to eliminate on-site server maintenance while maintaining centralized visibility across distributed locations. Hybrid deployment models are capturing margin pools in critical infrastructure settings where air-gapped local recording must coexist with cloud-based redundancy.
FCC equipment authorization requirements in the United States constrain wireless video transmission modules, while GDPR data retention limits in Europe shape how long facial recognition metadata may reside on NVR storage arrays. China's GB standards and MIIT cybersecurity certifications create a dual compliance burden for manufacturers serving both domestic and export markets. Stakeholders must weigh regulatory fragmentation against the operational benefits of unified platform architectures as they evaluate regional deployment strategies.
Market Dynamics
The transition from H.264 to H.265 codecs alongside AI-enhanced video analytics is compressing storage costs while simultaneously elevating processing requirements across recorder architectures. This codec migration is forcing manufacturers to redesign thermal management and chipset selection for edge deployments.
Growth Catalysts
- Smart City Surveillance Mandates:Municipal governments in China are expanding procurement of IP-based recording systems for urban monitoring networks, with GB standards compliance accelerating domestic deployment timelines.
- GDPR-Compliant Retention Frameworks:European data protection requirements are standardizing metadata management protocols, creating upgrade cycles for legacy analog-to-digital infrastructure in commercial security operations.
- AI Video Analytics Integration:Machine learning inference at the edge is enabling real-time anomaly detection without cloud dependency, reducing bandwidth costs for retail and transportation operators.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabrication capacity constraints create lead time volatility for system-on-chip components essential to 4K encoding pipelines.
- FCC Equipment Authorization Friction:United States wireless transmission module certification adds 4-6 month delays for manufacturers integrating Wi-Fi 6E or private 5G connectivity into mobile NVR units.
- Cloud Storage Substitution:Video-Surveillance-as-a-Service platforms are capturing mid-market accounts seeking to eliminate on-premise hardware maintenance obligations entirely.
Strategic Opportunities
- Hybrid Deployment Architectures:Critical infrastructure operators in Saudi Arabia and UAE require air-gapped local recording with cloud redundancy, creating margin pools for dual-mode system vendors.
- India Smart Cities Mission:The PLI scheme for electronics manufacturing is incentivizing domestic NVR assembly, opening procurement channels previously dominated by Chinese imports.
- EU AI Act Compliance Tools:Facial recognition metadata governance requirements are creating demand for audit-ready storage solutions with automated retention policy enforcement.
Industry Challenges
- Legacy Analog Integration Complexity:Enterprises with existing coaxial infrastructure face costly rip-and-replace cycles when migrating to IP-based centralized retention systems.
- Edge AI Talent Scarcity:Firmware optimization for heterogeneous compute architectures requires embedded systems expertise that concentrates in Shenzhen and Bangalore technology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Video Recorder (NVR) Market |
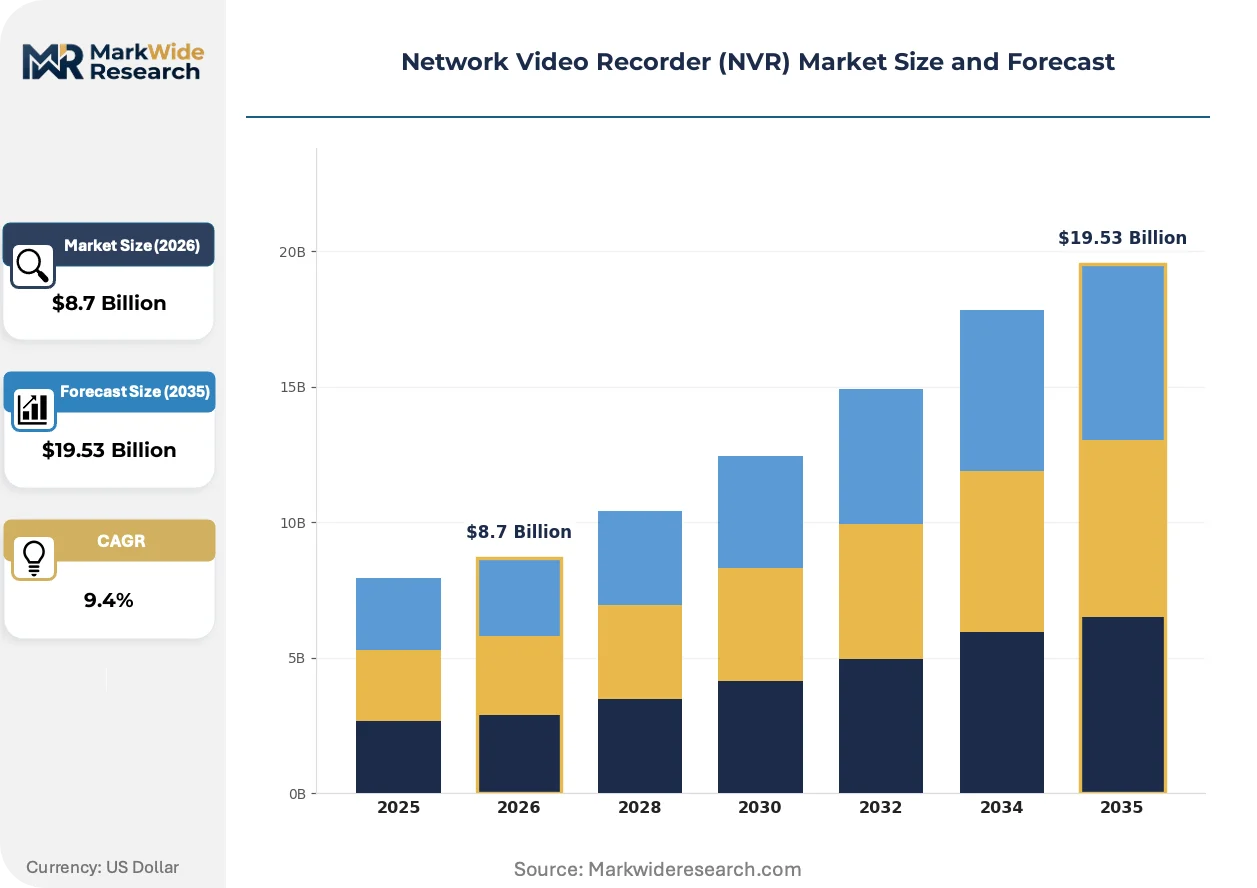
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone NVR, Rack-mounted NVR, Desktop NVR, Cloud-based NVR Technology: IP Video, Analog Video, Hybrid Video, Wireless Video End User: Retail, Government, Transportation, Critical Infrastructure Deployment: On-premise, Cloud-based, Hybrid, Virtualized |
| Companies Covered | Dahua Technology Co., Ltd., Avigilon Corporation, Axis Communications AB, Synology Inc., VIVOTEK Inc., Honeywell International Inc., Panasonic, Teledyne FLIR LLC, Hangzhou Hikvision Digital Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Video Recorder (NVR) Market Emerging Trajectories
Edge computing architectures are redistributing video processing workloads away from centralized data centers, compressing latency for real-time security response while fragmenting traditional NVR hardware specifications.
Software-defined NVR platforms are decentralizing storage and analytics functions across distributed camera-edge-gateway hierarchies. Large-scale logistics operators in Germany and the Netherlands are deploying these architectures to eliminate single points of failure in warehouse monitoring networks. This topology is compressing capital intensity for multi-site deployments while elevating cybersecurity exposure across attack surfaces.
China's MIIT cybersecurity certification requirements for networked security equipment are mandating domestic encryption standards and supply chain provenance documentation. Manufacturers serving both Chinese and export markets must maintain dual firmware branches, elevating engineering overhead. European and North American operators are responding by segmenting product lines to isolate compliance domains.
Subscription-based video management software is displacing perpetual licensing in mid-market commercial accounts. System integrators in Australia and Canada are bundling hardware with multi-year service contracts, capturing recurring revenue streams previously lost to third-party maintenance providers. This model is most visible in retail chains operating 50-200 location footprints where centralized visibility outweighs capital ownership preferences.
Network Video Recorder (NVR) Market Segmentation
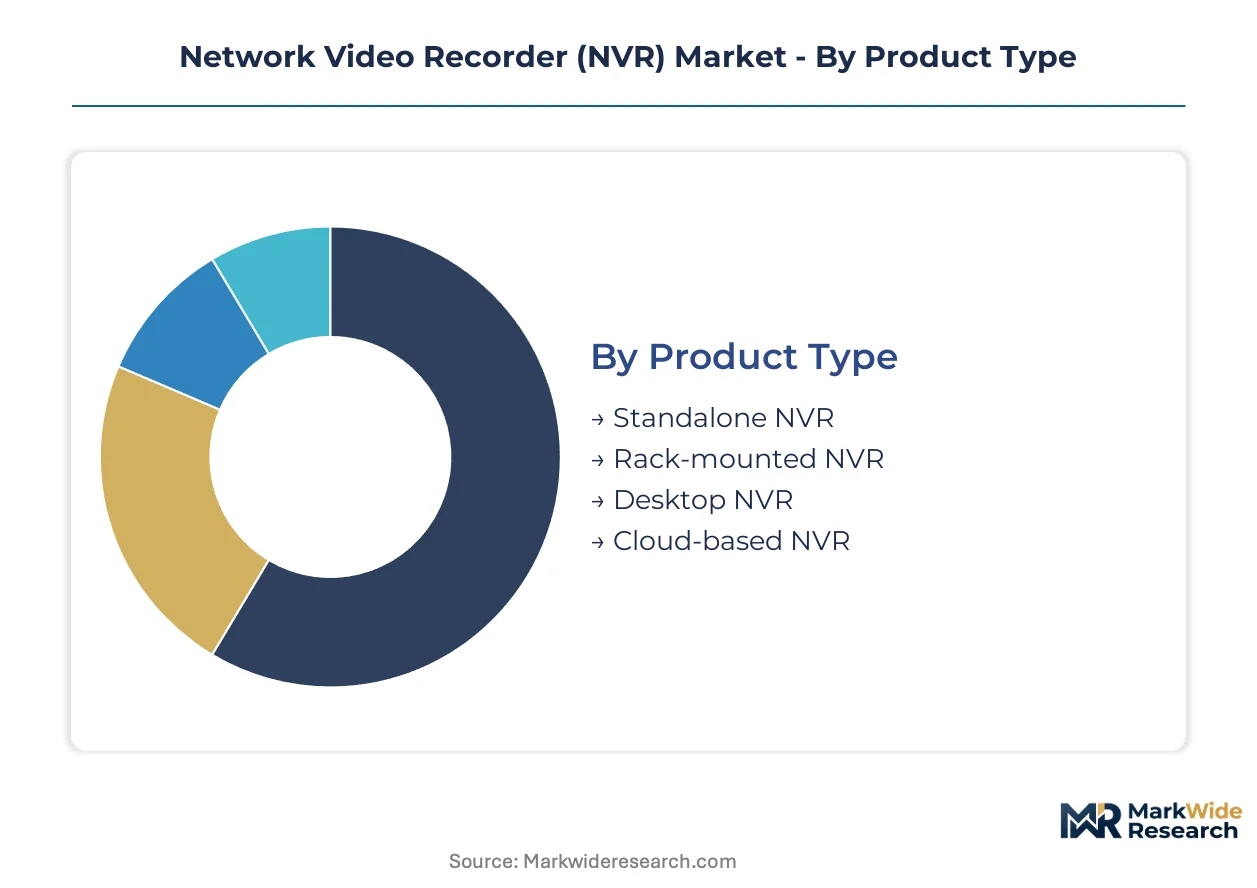
NVR procurement patterns diverge sharply across deployment contexts, with certification requirements and thermal constraints filtering which architectures qualify for specific installations. Understanding these segment boundaries clarifies where vendor R&D investments concentrate and which compliance burdens shape product roadmaps.
Product Type:
FCC equipment authorization governs wireless-enabled standalone units, while rack-mounted configurations face stricter thermal and electromagnetic interference standards in data center deployments.
- Standalone NVR:Compact all-in-one units integrating encoding, storage, and network interfaces in a single chassis. Retail chains in Australia and Canada favor these for 50-200 location rollouts where centralized visibility outweighs capital ownership preferences.
- Rack-mounted NVR:High-density 1U-4U chassis designed for enterprise data centers with redundant power and hot-swappable RAID arrays. Demand concentrates in Saudi Arabia and UAE critical infrastructure where air-gapped local recording must coexist with cloud redundancy.
- Desktop NVR:Small-form-factor units for SOHO and light commercial applications with 4-16 channel capacity.
- Cloud-based NVR:Virtualized recording instances eliminating on-premise hardware maintenance for mid-market accounts seeking Video-Surveillance-as-a-Service models.
Rack-mounted NVR sits at the top of the volume ranking, with cloud-based NVR climbing the fastest.
Technology:
Codec migration from H.264 to H.265 is redistributing market share across technology categories, with processing overhead and bandwidth efficiency driving procurement decisions.
- IP Video:Native digital streams from network cameras using H.265 compression at 4K resolution. Municipal governments in China are expanding procurement for smart city surveillance networks with GB standards compliance accelerating domestic deployment timelines.
- Analog Video:Coaxial-based legacy infrastructure requiring digitization at the recorder. Enterprises face costly rip-and-replace cycles when migrating to centralized retention systems, creating upgrade friction in established commercial installations.
- Hybrid Video:Simultaneous support for IP and analog inputs easing transition paths for mixed estates.
- Wireless Video:Wi-Fi 6E and private 5G transmission modules subject to FCC certification delays of 4-6 months for mobile NVR integration.
IP Video commands the largest installed base, while hybrid Video gains share fastest among enterprises managing legacy infrastructure transitions.
End User:
Retention policy requirements fragment demand across end-user categories, with GDPR metadata limits and critical infrastructure air-gap mandates imposing incompatible specification sets.
- Government:Municipal and national security installations requiring forensic-grade chain-of-custody documentation. China's smart city mandates and MIIT cybersecurity certifications are mandating domestic encryption standards and supply chain provenance documentation.
- Critical Infrastructure:Energy, transportation, and telecommunications facilities where operational technology isolation prevents cloud-only architectures. Operators in Saudi Arabia and UAE require dual-mode systems with local recording and cloud redundancy.
- Retail:Multi-location chains prioritizing centralized visibility and subscription-based software models over capital ownership.
- Transportation:Mobile and fixed installations demanding vibration tolerance and wide-temperature operation for fleet and rail applications.
Government installations lead in average contract value, with critical infrastructure posting the steepest expansion trajectory as air-gap requirements proliferate.
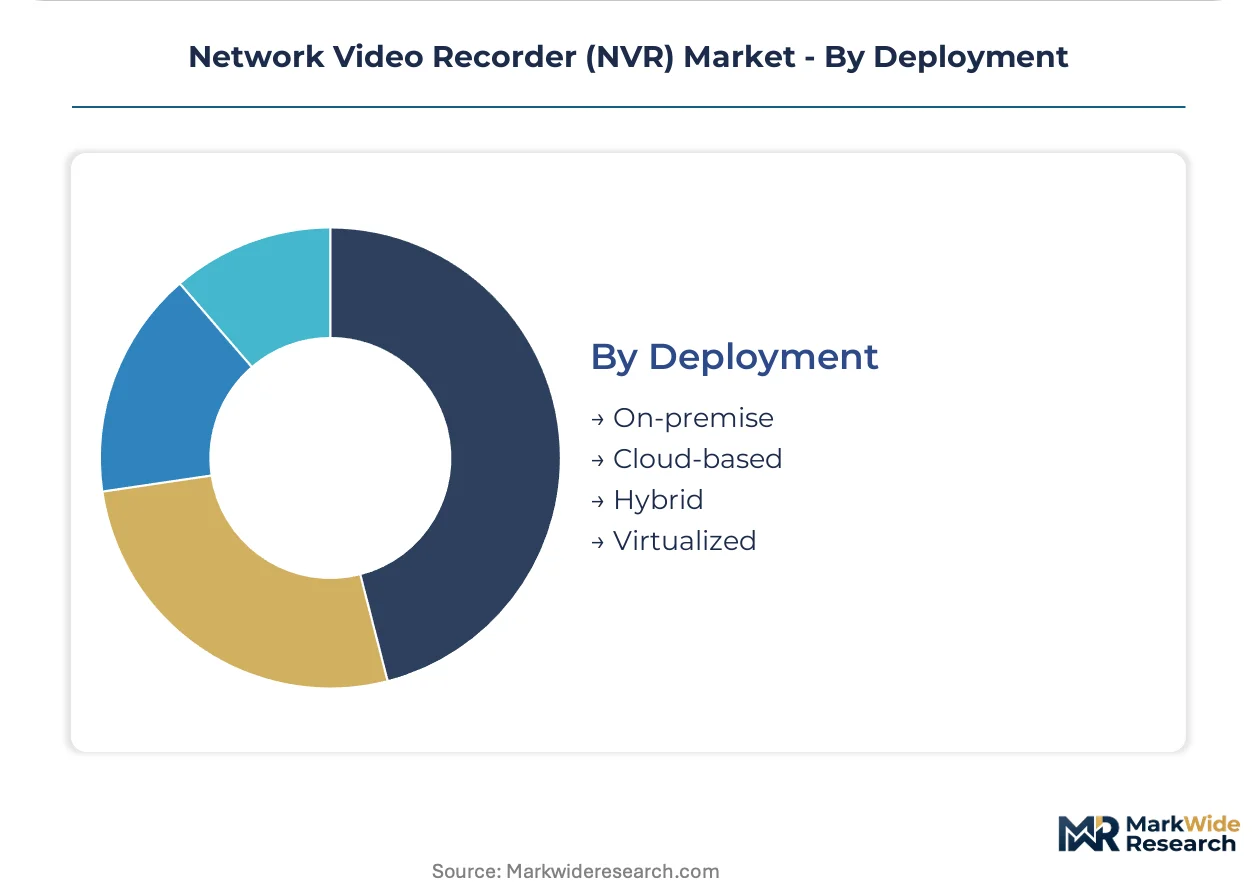
Deployment:
Capital intensity and cybersecurity exposure trade off across deployment models, with subscription economics displacing perpetual licensing in commercial accounts.
- On-premise:Fully localized hardware ownership with direct physical control over storage arrays. Large-scale logistics operators in Germany and the Netherlands are shifting away from this topology to eliminate single points of failure.
- Hybrid:Air-gapped local recording with encrypted cloud replication for disaster recovery. Critical infrastructure operators in Saudi Arabia and UAE are capturing margin pools for vendors offering dual-mode certification.
- Cloud-based:Fully virtualized instances with zero on-site server maintenance, accelerating adoption among retail chains.
- Virtualized:Software-defined NVR platforms decentralizing storage and analytics across distributed camera-edge-gateway hierarchies.
On-premise retains the largest installed base, though hybrid deployment is expanding most quickly as operators reconcile compliance isolation with operational redundancy needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors NVR production capacity, with municipal smart city programs across Asia-Pacific driving procurement volumes. Regulatory fragmentation between MIIT cybersecurity mandates and FCC equipment authorization shapes dual-track product strategies for cross-border vendors.
China
Municipal governments in Beijing and Shanghai are expanding IP-based recording procurement for urban surveillance networks. MIIT cybersecurity certification mandates domestic encryption standards and supply chain provenance documentation for networked security equipment. Shenzhen and Hangzhou technology clusters host integrated manufacturing operations spanning camera sensors to finished recorder systems.
United States
Retail chains operating 50-200 location footprints are accelerating cloud-based NVR adoption to eliminate on-site server maintenance. FCC equipment authorization requirements constrain wireless video transmission modules, adding 4-6 month certification delays for Wi-Fi 6E integration. Greater Boston and Pacific Northwest technology corridors concentrate software-defined platform development for distributed camera-edge-gateway architectures.
Germany
Large-scale logistics operators in the Netherlands-adjacent Rhine-Ruhr region are deploying software-defined NVR platforms to eliminate single points of failure in warehouse monitoring networks. GDPR data retention limits shape how long facial recognition metadata may reside on storage arrays, standardizing metadata management protocols. Bavaria's industrial automation sector drives demand for hybrid deployment models reconciling air-gapped local recording with cloud redundancy.
Saudi Arabia
Critical infrastructure operators in Riyadh and the Eastern Province require air-gapped local recording with encrypted cloud replication for disaster recovery. SFDA-equivalent national security regulations impose forensic-grade chain-of-custody documentation for government installations. NEOM's greenfield development creates procurement channels for dual-mode systems vendors serving smart city surveillance mandates.
India
The PLI scheme for electronics manufacturing is incentivizing domestic NVR assembly, opening procurement channels previously dominated by Chinese imports. Municipal governments in Maharashtra and Karnataka are expanding smart city surveillance programs under the India Smart Cities Mission. Delhi-NCR and Tamil Nadu industrial corridors are capturing contract manufacturing flows as vendors diversify supply chains beyond Shenzhen concentration.
Network Video Recorder (NVR) Market Vendor Landscape
Global majors compete with regional champions across certification compliance and supply chain integration dimensions, producing a tiered structure where scale-driven players coexist with specialized integrators. The vendor base separates into three archetypes: vertically integrated hardware manufacturers controlling captive semiconductor supply, open-platform software architects enabling third-party analytics integration, and subscription-based service providers capturing recurring revenue in mid-market commercial accounts. Dominant competitive moves include backward integration into sensor and chipset production, plus geographic diversification of final assembly to navigate tariff and certification fragmentation.
Within the vertically integrated tier, Dahua Technology Co., Ltd. and Hangzhou Hikvision Digital Technology exemplify Chinese manufacturers leveraging in-house component sourcing to control recorder line economics. Axis Communications AB occupies a position representing open-platform differentiation through software architecture supporting heterogeneous analytics integration. These three anchors illustrate how competitive positioning separates across supply chain control versus architectural flexibility.
| Leading Market Players |
|---|
| Dahua Technology Co., Ltd. |
| Avigilon Corporation |
| Axis Communications AB |
| Synology Inc. |
| VIVOTEK Inc. |
| Honeywell International Inc. |
| Panasonic |
| Teledyne FLIR LLC |
| Hangzhou Hikvision Digital Technology |
| Others |
Supply Flow & Price Mechanics
Codec migration from H.264 to H.265 compression standards simultaneously compresses storage economics and concentrates procurement leverage among semiconductor vendors with advanced encoding IP. This dual effect reshapes cost structures across recorder tiers while elevating chipset sourcing as the primary margin determinant.
Pricing Analysis
Input-cost pass-through from Taiwan and South Korea fabrication capacity constraints elevates system-on-chip pricing across 4K encoding pipelines. Three-tier pricing structure across enterprise, commercial, and SOHO levels reflects certification grade differentiation and volume scale. Pricing pressure stems from Video-Surveillance-as-a-Service substitution capturing mid-market accounts. Retail chains operating distributed footprints exhibit highest price sensitivity, while critical infrastructure operators prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Certification gating through FCC equipment authorization and MIIT cybersecurity mandates fragments supplier qualification pathways for cross-border vendors. Manufacturing concentrates in China, Taiwan, and South Korea, with Shenzhen and Hangzhou technology clusters anchoring integrated production from camera sensors to finished systems. Component sourcing draws from specialized semiconductor foundries and domestic encryption module suppliers. Single-source vulnerability concentrates in advanced codec silicon. Distribution runs through systems integrators and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid deployment architectures where compliance-driven premiums offset cloud substitution pressure. H.265 codec adoption and AI analytics integration compress storage costs while enabling value-based pricing tiers.
For Market Incumbents: Extend software-defined platform development to capture recurring revenue from subscription-based video management contracts. Deepen backward integration into edge AI chipsets to defend against semiconductor supply volatility. Prioritize dual-firmware engineering capabilities to navigate MIIT and FCC certification fragmentation without product line duplication.
For New Entrants and Emerging Players: Cloud-native channel partnerships offer the lowest customer acquisition friction for mid-market retail accounts seeking zero on-premise maintenance. Target India's PLI-incentivized domestic assembly market before procurement channels solidify around established Chinese imports. Lead with GDPR-compliant metadata governance tools to differentiate in European commercial security upgrades.
For Investors and Strategic Acquirers: Valuations sit cheapest among open-platform software architects with third-party analytics integration capabilities rather than hardware-centric vendors. Long-term viability favors vendors controlling both edge inference silicon and centralized management software. Monitor India Smart Cities Mission procurement award velocity as inflection indicator for geographic demand redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Development | Captures margin pools in Saudi and UAE critical infrastructure requiring air-gapped local recording with cloud redundancy. |
| Edge AI Chipset Backward Integration | Reduces dependency on Taiwan and South Korea fabrication capacity for H.265 encoding pipeline components. |
| GDPR-Compliant Metadata Governance Platform | Addresses EU AI Act facial recognition retention requirements with automated policy enforcement tools. |
| India PLI Scheme Manufacturing Localization | Opens procurement channels under Smart Cities Mission previously dominated by Shenzhen supply chains. |
| Software-Defined NVR Platform Launch | Eliminates single points of failure for German and Dutch logistics operators deploying distributed camera-edge-gateway hierarchies. |
Methodological Framework
Direct dialogue with NVR product managers, security systems integrators, municipal procurement officers, and semiconductor sourcing leads grounded qualitative insights in operational reality. Secondary validation drew from FCC equipment authorization databases, MIIT cybersecurity certification registries, EU AI Act implementation guidance, and customs trade flows for networked security equipment. Bottom-up channel checks and top-down macroeconomic triangulation converged on segment-level demand estimates.
Bottom-up modeling aggregated deployment-type, end-user, and technology-category volumes across the projection horizon. Segmentation dimensions included product form factor, codec standard, deployment architecture, and regional regulatory cluster. CAGRs derived from fitted adoption curves for H.265 migration and AI analytics penetration, cross-referenced against municipal smart city budget allocations and enterprise IT capex surveys.
The model assumes a particular technology adoption path; alternative pathways for edge AI inference silicon would alter the outlook if on-device processing economics shift faster than centralized cloud analytics. Forecasts reflect assumptions about codec migration timelines, certification harmonization progress, and cloud substitution elasticity. A model refresh is warranted upon material change in FCC equipment authorization timelines or MIIT cybersecurity mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Extended Detection and Response Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Privileged Access Management (PAM) Market
Security Software
US Hardware Encryption Market
Security Software
GDPR Software and Tools Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Facial Recognition Market
Security Software
Europe Smart Doorbell Market
Security Software
Disk Encryption Software Market
Security Software
Doorbell Camera Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Software Assurance Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Patch and Remediation Software Market
Security Software
Mobile Identity Management Market
Security Software
Identity-As-A-Service (Idaas) Market