
 Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market | 2026-2036
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market Insights
Project finance for shared test infrastructure is rewriting competitive access in automotive cybersecurity validation. Keysight Technologies leverages its signal analyzer portfolio to anchor high-frequency OTA test workflows for premium OEM programs. Rohde & Schwarz sustains R&D intensity across network simulation stacks that replicate multi-cellular V2X attack surfaces. Spirent Communications competes through protocol emulator suites purpose-built for 5G-connected vehicle firmware delivery channels.
Automotive Over-the-Air Cybersecurity Hardening Test Equipment comprises specialized instrumentation that validates cryptographic integrity, RF emission compliance, and intrusion resilience during remote firmware updates to electronic control units. These systems integrate vector signal analysis with real-time traffic emulation to detect man-in-the-middle exploits across cellular, Wi-Fi, and satellite downlink paths. Intrusion Detection technology leads segment margins due to mandatory pre-homologation screening under emerging type-approval frameworks. Protocol Emulators represent the fastest-growing product category as OEMs validate against multi-standard OTA delivery stacks spanning 4G, 5G, and C-V2X interfaces. Firmware Update Verification applications dominate current procurement volumes, though ECU Authentication testing is accelerating with the spread of hardware security module integration.
UN Regulation No. 155, the EU Cybersecurity Act, and ISO/SAE 21434 collectively mandate traceable validation evidence before type approval, forcing OEMs to outsource or scale captive test capacity. FDA-class medical device cybersecurity precedents are influencing automotive regulator expectations for documented penetration test coverage across vehicle lifecycles. Stakeholders must monitor how regional divergence between ECE R155 implementation timelines and China's GB standards for connected vehicles fragments test equipment specification requirements.
Market Dynamics
UN Regulation No. 155 mandates traceable cybersecurity validation evidence before vehicle type approval, forcing OEMs to scale captive test capacity or outsource to accredited laboratories. This regulatory pressure compresses procurement cycles for OTA test benches while elevating cryptographic integrity screening to a non-negotiable program gate.
Growth Catalysts
- EU Cybersecurity Act:Mandatory pre-homologation screening under emerging type-approval frameworks elevates intrusion detection systems to critical-path status in vehicle development pipelines.
- Hardware security module integration:ECU authentication testing accelerates as OEMs deploy HSM-backed firmware verification across electronic control unit architectures.
- Germany:TÜV SÜD and TÜV Rheinland operate accredited laboratories serving OEM certification pipelines, concentrating demand for validated test equipment procurement.
Market Restraints
- RF component cost volatility:Vector signal analyzers and network simulation stacks rely on specialized semiconductor inputs subject to supply concentration risk in East Asian foundries.
- Technical limitation:Real-time traffic emulation across multi-cellular V2X attack surfaces demands computational throughput that exceeds current edge-processing economics for mid-tier suppliers.
- Regulatory friction:Divergence between ECE R155 implementation timelines and China's GB standards fragments test equipment specification requirements, forcing redundant validation workflows.
Strategic Opportunities
- Underpenetrated geography:India's automotive cybersecurity regulatory framework remains nascent, creating first-mover positioning for test equipment vendors ahead of mandatory BIS certification requirements.
- Technology convergence:5G-connected vehicle firmware delivery channels intersect with C-V2X interfaces, opening protocol emulator demand spanning dual-standard validation environments.
- Emerging application:Satellite downlink path verification for over-the-air updates represents uncaptured white space as OEMs expand beyond terrestrial cellular coverage.
Industry Challenges
- Skill gap:Embedded systems security engineering talent scarcity constrains laboratory scaling, particularly for penetration test coverage across vehicle lifecycles.
- Capex intensity:Multi-standard OTA delivery stack validation requires simultaneous 4G, 5G, and C-V2X instrumentation investment that strains supplier balance sheets.
- Certification timeline:ISO/SAE 21434 compliance documentation demands extend program schedules, compressing equipment utilization rates for outsourced test facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market |
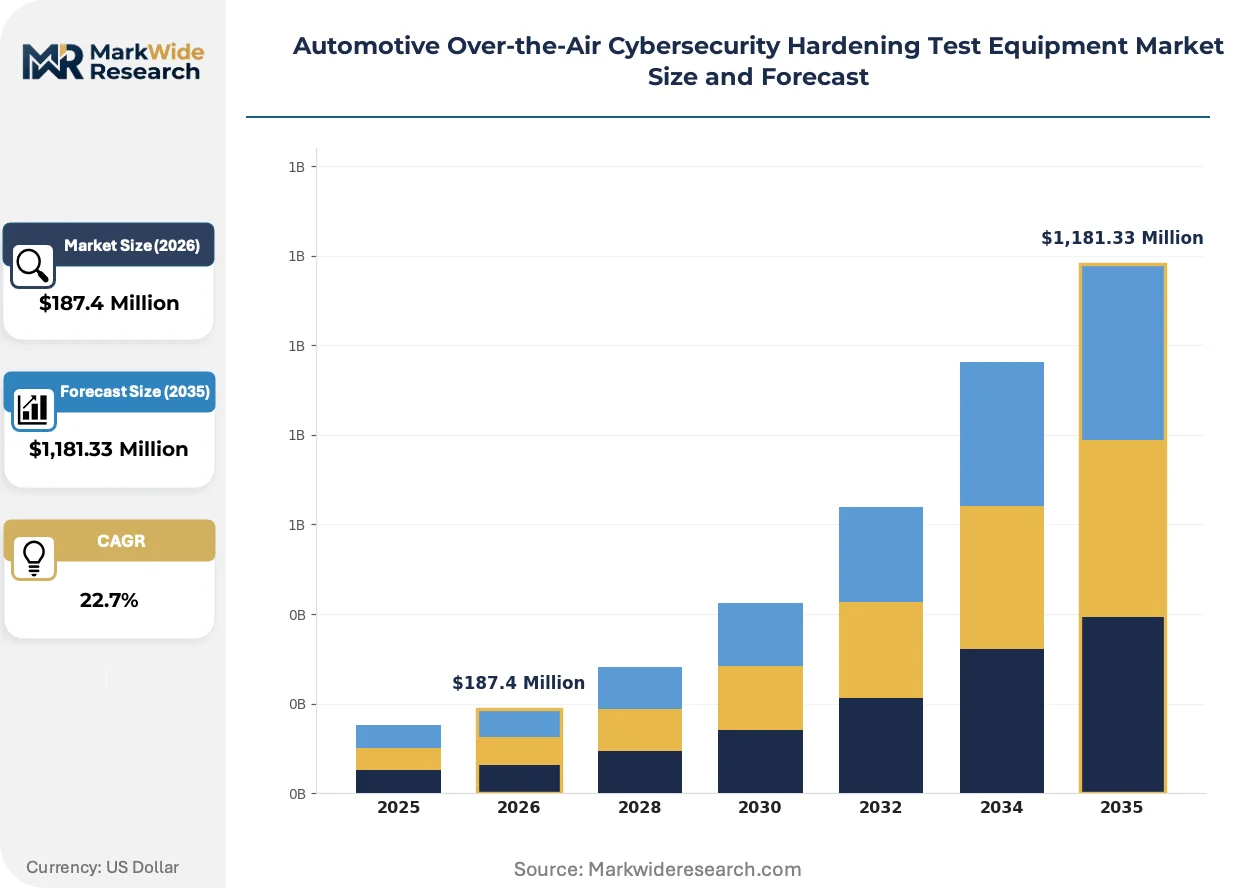
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Analyzers, Network Simulators, Security Scanners, Protocol Emulators, Performance Counters Technology: Intrusion Detection, Anomaly Detection, Encryption Analysis, Penetration Testing, Firmware Validation Application: Firmware Update Verification, ECU Authentication, OTA Communication Security, Threat Intelligence, Vulnerability Assessment End User: Original Equipment Manufacturers, Tier-1 Suppliers, Cybersecurity Firms, Testing Laboratories, Research Institutes |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Spirent Communications, Vector Informatik, ETAS, Intertek Group, TÜV SÜD, TÜV Rheinland, UL Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market Trends and Innovations
Automotive cybersecurity validation is pivoting from reactive penetration testing toward continuous cryptographic integrity monitoring embedded within firmware delivery pipelines. This shift compresses test cycle timelines while elevating real-time traffic emulation to core infrastructure status.
AI-driven anomaly detection engines are rendering obsolete static signature-based intrusion detection systems that dominated early OTA security architectures. Tier-1 suppliers deploy machine learning inference at the protocol layer to identify zero-day exploits during firmware transmission. This capability compression eliminates retrofit demand for legacy rule-based screening equipment.
REACH and RoHS compliance frameworks in Europe now extend to cybersecurity test equipment material declarations, forcing vendors to document hazardous substance thresholds across RF hardware supply chains. German OEMs impose these requirements contractually ahead of regulatory deadlines. Laboratory procurement specifications now embed environmental compliance as a gating criterion alongside technical performance.
Automotive OEMs consolidate vendor relationships around integrated test bench providers capable of spanning firmware update verification through ECU authentication in single-platform deployments. Multi-vendor toolchains lose preference as program managers prioritize traceability across unified validation environments. This concentration is most visible in Germany, where TÜV-accredited laboratories now specify end-to-end platform requirements in RFP documentation.
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market Segmentation
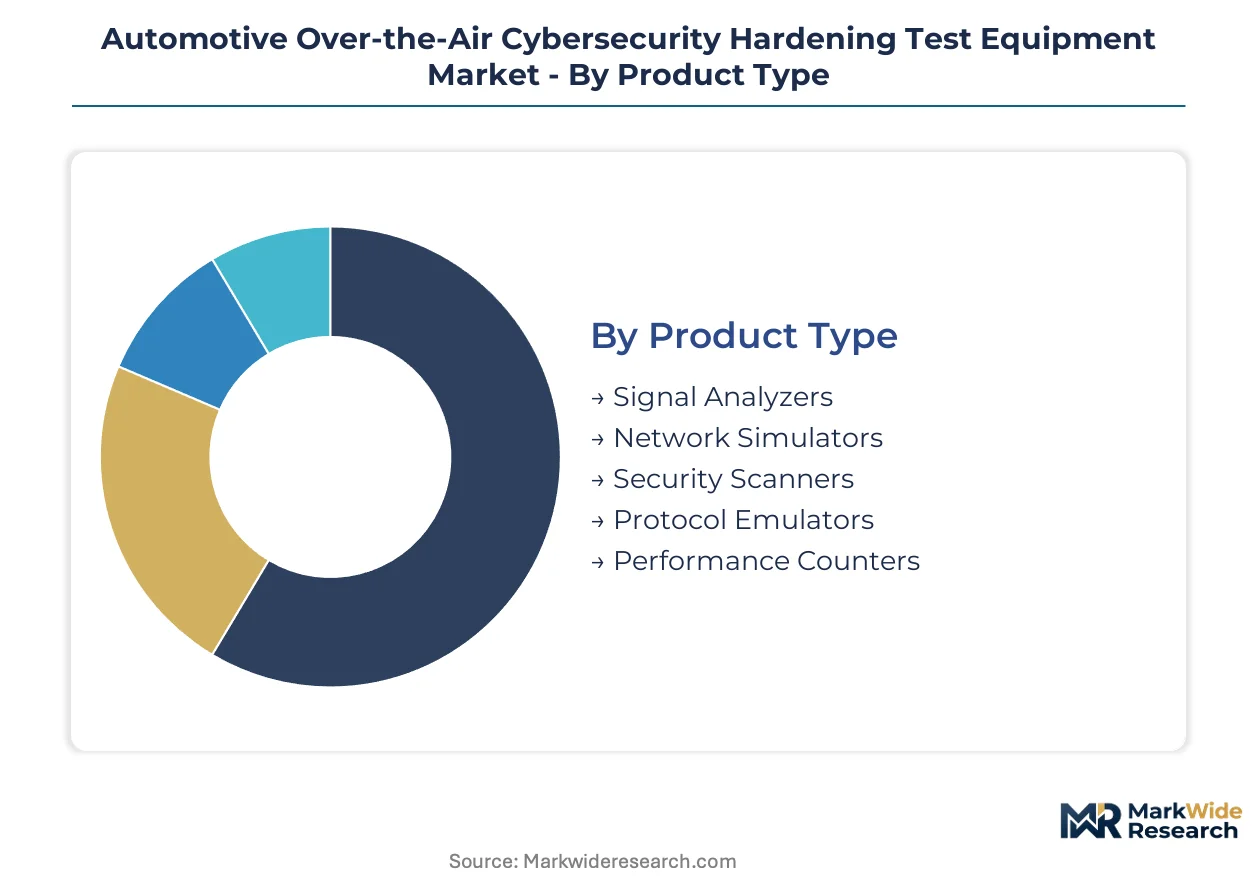
Test equipment procurement patterns diverge sharply across customer archetypes and validation workflows. Segmentation reveals how regulatory pressure concentrates investment in specific technology stacks while geographic implementation timelines fragment specification requirements.
Product Type:
After-sales calibration intensity varies dramatically across instrument categories, with some requiring annual recertification against evolving threat signatures while others demand only firmware refreshes.
- Signal Analyzers:Vector signal analysis platforms measure RF emission compliance and spectral integrity during OTA transmission. German OEM certification pipelines at TÜV SÜD and TÜV Rheinland anchor procurement concentration for these high-frequency validation systems.
- Protocol Emulators:Purpose-built suites replicate multi-cellular V2X attack surfaces across 4G, 5G, and C-V2X interfaces. Tier-1 suppliers expanding OTA test bench procurement drive demand as dual-standard validation environments become mandatory.
- Network Simulators:Real-time traffic emulation stacks replicate cellular, Wi-Fi, and satellite downlink paths for man-in-the-middle exploit detection.
- Security Scanners:Static and dynamic analysis tools audit cryptographic implementations in firmware images pre-deployment.
- Performance Counters:Latency and throughput measurement instrumentation validates OTA delivery channel capacity under load.
By volume, Signal Analyzers lead procurement. By growth pace, Protocol Emulators are expanding most quickly.
Technology:
Cost tier stratification separates premium AI-driven engines from rule-based alternatives, with pricing gaps exceeding 300% between baseline and inference-capable platforms.
- Intrusion Detection:Real-time monitoring systems screen firmware delivery channels for signature-based and behavioral threat indicators. Mandatory pre-homologation screening under UN Regulation No. 155 elevates these systems to critical-path status in vehicle development pipelines.
- Anomaly Detection:Machine learning inference engines identify zero-day exploits at the protocol layer during firmware transmission. Tier-1 suppliers deploy these AI-driven systems to eliminate retrofit demand for legacy screening equipment.
- Encryption Analysis:Cryptographic integrity validation tools audit cipher implementations and key management protocols.
- Penetration Testing:Documented exploit simulation frameworks satisfy ISO/SAE 21434 compliance documentation demands.
- Firmware Validation:Binary verification systems confirm image authenticity and integrity prior to ECU flashing.
Intrusion Detection commands the largest installed base. Anomaly Detection is gaining share fastest as AI deployment accelerates.
Application:
Application maturity correlates directly with regulatory enforcement sequence, with early-mandated validation stages now commoditizing while emerging requirements sustain premium pricing.
- Firmware Update Verification:End-to-end validation of binary delivery, decryption, and installation sequences dominates current procurement volumes. OEM captive test capacity expansion concentrates demand for these workflow-integrated platforms.
- ECU Authentication:Hardware security module integration testing validates cryptographic identity binding between firmware and control units. HSM-backed verification architectures accelerate procurement as OEMs harden electronic control unit security postures.
- OTA Communication Security:Channel integrity validation for cellular, Wi-Fi, and satellite downlink paths.
- Threat Intelligence:Feed integration and indicator-of-compromise management for continuous monitoring.
- Vulnerability Assessment:Systematic exploit identification across vehicle software attack surfaces.
Firmware Update Verification leads by deployment scale. ECU Authentication exhibits the steepest expansion trajectory as hardware security integration spreads.
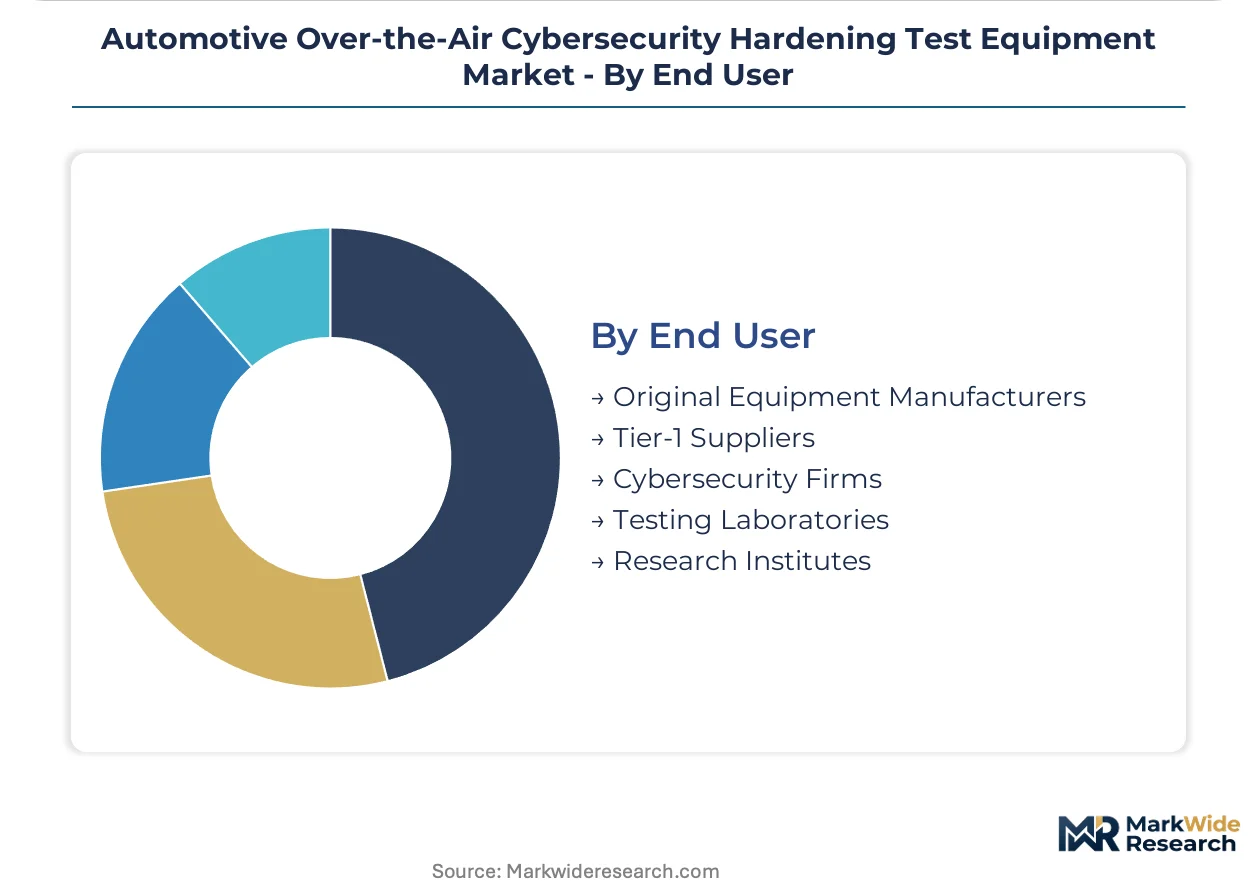
End User:
Customer type determines specification authority, with OEMs dictating platform requirements that cascade through supplier tiers and laboratory accreditation bodies.
- Original Equipment Manufacturers:Captive test facility investment and outsourced laboratory procurement drive the largest absolute demand. UN Regulation No. 155 compliance timelines force simultaneous scaling of internal capacity and third-party validation partnerships.
- Testing Laboratories:Accredited facilities including TÜV SÜD and TÜV Rheinland serve OEM certification pipelines with standardized validation protocols. German laboratory concentration elevates equipment specification requirements for traceable type-approval evidence.
- Tier-1 Suppliers:Subsystem validation capacity expansion follows OEM sourcing mandates.
- Cybersecurity Firms:Specialized penetration testing and consulting services require portable validation tooling.
- Research Institutes:Academic and government research programs advance threat model development and countermeasure validation.
Original Equipment Manufacturers represent the largest customer segment by procurement value. Testing Laboratories are climbing the fastest as regulatory outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN Regulation No. 155 and its ECE R155 implementation timeline are forcing OEMs across multiple jurisdictions to establish traceable cybersecurity validation pipelines before type approval. This regulatory pressure concentrates test equipment procurement in countries with mature automotive certification infrastructure.
Germany
TÜV SÜD and TÜV Rheinland operate accredited laboratories serving OEM certification pipelines with standardized validation protocols. The KBA enforces ECE R155 compliance timelines that compress procurement cycles for OTA test benches. Stuttgart and Munich anchor concentrated demand for vector signal analysis platforms among premium OEM captive test facilities.
United States
NHTSA cybersecurity guidance and state-level data privacy frameworks elevate ECU authentication testing requirements for connected vehicle programs. The IRA's domestic manufacturing incentives indirectly support test infrastructure localization. Michigan and California host the largest concentrations of OEM validation partnerships with third-party cybersecurity laboratories.
China
GB standards for connected vehicles and MIIT cybersecurity mandates are fragmenting test equipment specifications away from ECE R155 frameworks. SAMR type-approval processes require documented penetration test coverage across vehicle lifecycles. Shanghai and Beijing clusters concentrate procurement for multi-standard protocol emulators spanning 4G, 5G, and C-V2X interfaces.
Japan
METI's connected vehicle security guidelines and JIS standards for automotive cybersecurity create parallel validation requirements to European frameworks. PMDA-class medical device cybersecurity precedents influence automotive regulator expectations for documented test coverage. Nagoya and Tokyo metropolitan areas concentrate Tier-1 supplier test bench procurement.
India
BIS certification requirements for automotive electronics remain nascent, creating first-mover positioning for test equipment vendors ahead of mandatory implementation. The PLI scheme for automotive manufacturing indirectly elevates cybersecurity infrastructure investment. Maharashtra and Tamil Nadu clusters show early laboratory capacity expansion for outsourced validation services.
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated test bench providers capable of spanning firmware update verification through ECU authentication in single-platform deployments. Tier-1 automotive suppliers and accredited laboratories now prioritize unified validation environments over multi-vendor toolchains. Two strategic archetypes dominate: RF instrumentation specialists with signal analyzer portfolios, and protocol emulation specialists with network simulation stacks. Competitive moves center on strategic partnerships with OEM certification pipelines and portfolio diversification into AI-driven anomaly detection capabilities.
Within the RF instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify supply-side concentration around high-frequency validation workflows. Among protocol emulation specialists, Spirent Communications occupies a position representing demand for 5G-connected vehicle firmware delivery channel verification. These three companies anchor the competitive structure visible in procurement patterns across German TÜV-accredited laboratories and OEM captive test facilities.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Spirent Communications |
| Vector Informatik |
| ETAS |
| Intertek Group |
| TÜV SÜD |
| TÜV Rheinland |
| UL Solutions |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at German TÜV-accredited laboratories compresses procurement cycles for OTA test benches while elevating pricing power for integrated platform vendors serving OEM certification pipelines. This utilization squeeze forces mid-tier suppliers toward extended lead times or premium slot pricing, reshaping how test equipment vendors structure capacity reservations and service bundling.
Pricing Analysis
Certification level creates the primary spread between ISO/SAE 21434-compliant platforms and baseline instrumentation lacking traceable validation documentation. Pricing stratifies across premium, standard, and economy tiers based on AI-driven anomaly detection capability and after-sales calibration intensity. Cost compression in standard-tier signal analyzers is intensifying because semiconductor input volatility from East Asian foundries feeds through to bill-of-materials pressure. Tier-1 automotive suppliers exhibit highest price sensitivity due to multi-standard 4G/5G/C-V2X instrumentation investment burdens, while accredited laboratories demonstrate lowest sensitivity given non-negotiable compliance timelines.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for RF component sourcing in vector signal analyzers and network simulation stacks. Manufacturing concentrates in Germany, the United States, and Japan for precision instrumentation assembly, while specialized semiconductor inputs draw from Taiwan, South Korea, and China. Single-source vulnerability in high-frequency RF front-end modules threatens production continuity for real-time traffic emulation platforms. Distribution runs through direct OEM procurement teams and TÜV-accredited laboratory consortiums with standardized validation protocol requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-based security testing tools pose a substitution threat to hardware-intensive OTA test benches as virtualized protocol emulation matures, forcing incumbents to defend platform stickiness through integrated certification workflows.
For Market Incumbents: Pre-empt virtualized emulation encroachment by embedding AI-driven anomaly detection as mandatory modules within firmware update verification platforms. Deepen backward integration into RF semiconductor sourcing to insulate margin structures from East Asian foundry volatility. Anchor customer retention through ISO/SAE 21434 documentation automation that accelerates laboratory accreditation timelines. For New Entrants and Emerging Players: Build out satellite downlink path verification capabilities ahead of OEM expansion beyond terrestrial cellular coverage, exploiting uncaptured white space in current competitive positioning. Target India's nascent BIS certification framework for automotive electronics before mandatory implementation locks in incumbent relationships. Lead with portable security scanner offerings for Tier-1 supplier validation partnerships rather than competing head-to-head for TÜV laboratory platform mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled protocol emulator development as machine learning inference engines displace rule-based intrusion detection architectures. Favor acquisition targets with established TÜV SÜD or TÜV Rheinland laboratory partnerships that provide defensive moats through certification pipeline integration. Monitor OEM captive test facility buildout announcements as early signals of outsourced validation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Anomaly Detection Integration | Tier-1 suppliers deploy machine learning inference to eliminate retrofit demand for legacy screening equipment. |
| Multi-Standard Protocol Emulator Development | Dual-standard 4G/5G/C-V2X validation environments become mandatory under UN Regulation No. 155 compliance timelines. |
| TÜV Laboratory Partnership Expansion | Accredited facilities in Germany anchor procurement concentration for traceable type-approval evidence. |
| Satellite Downlink Verification Capability | OEMs expanding beyond terrestrial cellular coverage create uncaptured white space for specialized instrumentation. |
| RF Semiconductor Supply Anchoring | Backward integration into high-frequency component sourcing insulates margins from East Asian foundry volatility. |
Research Methodology
The analysis maps signal analyzer, protocol emulator, and network simulator sub-sectors, each validated through primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, TÜV laboratory technical directors, and cybersecurity validation specialists. Secondary sources include UN ECE regulatory filings, ISO/SAE 21434 documentation standards, KBA type-approval records, and automotive production databases. Bottom-up equipment procurement tracking triangulates against top-down regulatory mandate sizing across ECE R155 implementation timelines.
Assumptions held fixed include UN Regulation No. 155 enforcement continuity and ECE R155 homologation pathway stability, while scenario analysis varied C-V2X adoption pace and hardware security module integration timelines across the projection horizon. Segmentation modeling spans product type, technology stack, application workflow, and end-user archetype dimensions. CAGRs derive from equipment procurement cycle compression analysis and laboratory capacity utilization trajectories, with RF component cost volatility and AI inference hardware pricing as sensitivity inputs.
Practitioners should monitor ECE R155 implementation timeline slippage and China's GB standards divergence for early signals of demand fragmentation or specification balkanization. Forecasts reflect these assumptions without guarantee of regulatory continuity or technological substitution pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Data Privacy Software Market
Security Software
Secure Email Gateway Market
Security Software
Global Digital Signature Software Market
Security Software
Key Management Service Market
Security Software
Europe Encryption Software Market
Security Software
Asia-Pacific Extended Detection and Response Market
Security Software
Messaging Security Market
Security Software
Antivirus Software Package Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Global Network Security Software Market
Security Software
Unified Threat Management (UTM) Market
Security Software
Parental Monitoring Software Market
Security Software
Anomaly Detection Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market