
 Global Security Orchestration Automation and Response (SOAR) Market | 2026-2036
Global Security Orchestration Automation and Response (SOAR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Security Orchestration Automation and Response (SOAR) Market Foresight
Managed Security Service Providers are gaining share as the dominant buyer archetype, while in-house IT security team procurement is unwinding across mid-market enterprises. Palo Alto Networks leverages extensive channel partnerships to anchor cloud-native deployment traction. IBM Corporation sustains mainframe-integrated security workflows across regulated industries. Splunk Inc. competes on data-platform convergence with adjacent observability tools.
Security Orchestration Automation and Response denotes an integrated cybersecurity platform that ingests alerts from disparate tools, applies machine-driven playbooks, and coordinates incident containment across endpoint, network, and cloud layers. Its primary commercial purpose is compressing mean-time-to-response from hours to minutes while preserving audit trails for compliance verification. Cloud-based deployment leads solution type momentum as enterprises retire on-premises Security Operation Center infrastructure. Incident Response and Automation & Orchestration capture expanding margin pools as buyers prioritize playbook-driven remediation over static case management. Threat Detection use cases dominate current spend, though Compliance Management is accelerating fastest under regulatory pressure.
The EU AI Act, GDPR, and NIS2 Directive shape European product requirements by mandating automated breach notification and cross-border incident reporting timelines. The SEC cybersecurity disclosure rules and HIPAA security incident protocols drive comparable automation urgency in the United States healthcare and publicly traded sectors. Stakeholders must evaluate whether hybrid deployment architectures or pure-cloud orchestration better align with evolving jurisdictional data residency constraints.
Market Dynamics
Managed Security Service Providers are consolidating procurement authority as mid-market enterprises dismantle in-house Security Operation Center infrastructure, shifting vendor relationships from direct sales to channel-mediated subscription models.
Growth Catalysts
- EU AI Act breach-notification mandates:Automated incident reporting timelines under the EU AI Act and NIS2 Directive compel enterprises to deploy playbook-driven response systems.
- Healthcare sector HIPAA security protocols:US healthcare providers face compressed disclosure windows for protected health information breaches, accelerating SOAR procurement.
- Cloud-native deployment architectures:Retirement of on-premises Security Operation Center hardware across Germany and Japan creates replacement demand for elastic orchestration platforms.
Market Restraints
- Specialized cybersecurity talent scarcity:Shortage of playbook engineering and threat-hunting expertise inflates implementation costs and extends deployment timelines.
- Data residency fragmentation:Divergent sovereignty requirements across the United States, Germany, and Japan force vendors to maintain region-specific infrastructure instances.
- Legacy SIEM sunk-cost entrenchment:Enterprises with multi-year contracts for on-premises security information and event management platforms delay SOAR migration.
Strategic Opportunities
- Japan's financial sector modernization:METI-guided digital transformation initiatives in banking and insurance create demand for integrated compliance-automation workflows.
- Convergence with observability platforms:Unified telemetry pipelines combining security and performance data open cross-sell opportunities for SOAR vendors.
- SEC cybersecurity disclosure rules:Publicly traded US companies must demonstrate incident response capabilities, expanding addressable market beyond regulated industries.
Industry Challenges
- Multi-tool integration complexity:Enterprises operate heterogeneous endpoint detection, network monitoring, and cloud security stacks that resist standardized API orchestration.
- Playbook maintenance burden:Continuous refinement of automated response workflows requires dedicated analyst hours that strain mid-market security teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Security Orchestration Automation and Response (SOAR) Market |
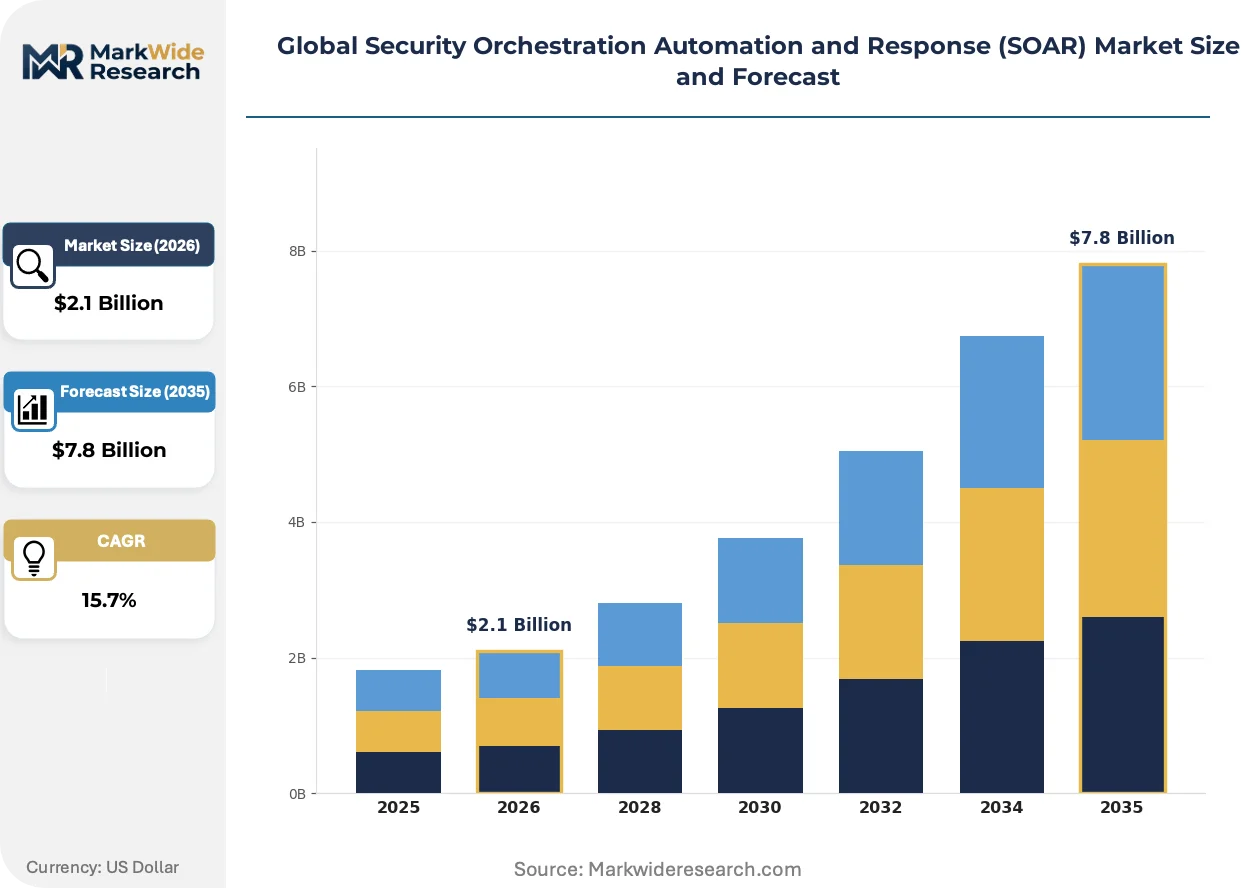
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.8 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Appliance Solution Type: Incident Response, Threat Intelligence, Case Management, Automation & Orchestration Use Case: Threat Detection, Compliance Management, Vulnerability Management, Security Operation Center Automation End User: IT Security Teams, Managed Security Service Providers, Financial Institutions, Government Agencies |
| Companies Covered | IBM Corporation, Splunk Inc., Microsoft Corporation, Palo Alto Networks, Cisco Systems, Fortinet, Rapid7, Swimlane, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Security Orchestration Automation and Response (SOAR) Market Shifts & Advancements
Agentic artificial intelligence architectures are redefining how SOAR platforms execute autonomous decision-making, compressing human-in-the-loop requirements while expanding the scope of machine-driven containment actions.
Large language model integration is decomposing traditional playbook construction workflows. Security engineers at financial services firms and critical infrastructure operators are adopting natural-language interface tools to generate response procedures. This capability is decomposing the specialized skill barrier that previously gated SOAR deployment to enterprises with dedicated automation teams.
The EU AI Act's automated decision-making transparency requirements reshape product development priorities for vendors serving European enterprises. Systems must now generate auditable explanations for machine-initiated containment actions. German automotive manufacturers and French energy utilities are demanding enhanced logging capabilities that satisfy both GDPR data processing records and AI Act algorithmic accountability standards.
Buyer concentration around Managed Security Service Providers is restructuring channel economics. Direct enterprise procurement of perpetual licenses is yielding to consumption-based arrangements mediated by service providers. This pattern is most pronounced in the United States, where mid-market healthcare and retail sectors increasingly delegate Security Operation Center operations to specialized vendors rather than building internal capabilities.
Global Security Orchestration Automation and Response (SOAR) Market Segmentation
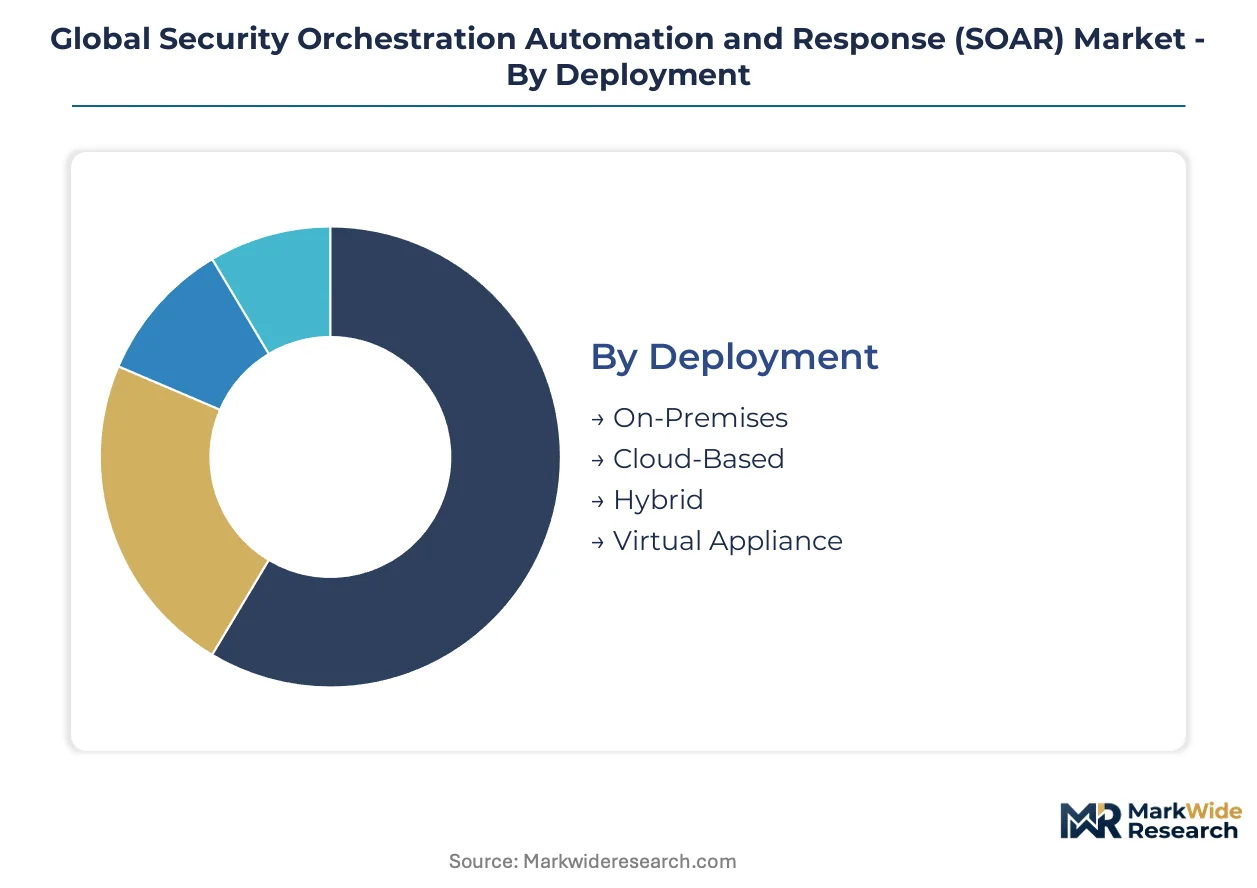
SOAR procurement patterns diverge sharply across deployment models, solution architectures, and buyer types. Regulatory mandates in the United States, Germany, and Japan create asymmetric demand profiles that reshape how vendors configure pricing and channel strategy.
Deployment:
EU AI Act algorithmic accountability requirements and GDPR data residency clauses differentiate cloud and on-premises adoption timelines across European automotive and energy operators.
- Cloud-Based:Elastic orchestration platforms eliminate capital expenditure for hardware refresh cycles. German manufacturers and Japanese financial institutions prioritize cloud-native deployment to satisfy METI digital transformation guidelines and EU cross-border data governance protocols.
- Hybrid:Split architectures partition sensitive telemetry on-premises while pushing automation logic to cloud infrastructure. United States healthcare providers under HIPAA security incident protocols favor hybrid models to preserve protected health information sovereignty.
- On-Premises:Air-gapped installations persist in classified government environments and critical infrastructure operators with stringent network segmentation requirements.
- Virtual Appliance:Containerized deployment packages accelerate time-to-value for mid-market enterprises dismantling legacy Security Operation Center hardware.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Solution Type:
Margin concentration follows automation depth, with playbook-driven remediation commanding premium pricing over static workflow tools.
- Automation & Orchestration:Machine-driven playbook execution coordinates containment across endpoint, network, and cloud layers. United States publicly traded companies under SEC cybersecurity disclosure rules prioritize this capability to demonstrate incident response readiness.
- Incident Response:Case management and forensic documentation compress mean-time-to-response from hours to minutes. Japanese banking operators under METI guidance deploy these systems for integrated compliance-automation workflows.
- Threat Intelligence:Correlation engines ingest indicators of compromise from external feeds and internal telemetry.
- Case Management:Ticketing and audit trail preservation satisfy GDPR data processing records and AI Act transparency mandates.
Margin pools concentrate in Automation & Orchestration; procurement velocity is climbing fastest in Incident Response.
Use Case:
Regulatory pressure reshapes priority rankings, with compliance automation gaining share against traditional threat-centric deployments.
- Compliance Management:Automated breach notification and cross-border incident reporting satisfy EU AI Act, NIS2 Directive, and SEC disclosure timelines. French energy utilities and German automotive manufacturers demand enhanced logging capabilities that satisfy both GDPR and algorithmic accountability standards.
- Threat Detection:Alert ingestion and correlation from disparate security tools dominates current spend volumes across United States healthcare and retail sectors.
- Vulnerability Management:Prioritization and remediation orchestration for patch deployment workflows.
- Security Operation Center Automation:End-to-end workflow integration replaces manual analyst handoffs.
Threat Detection holds current spend leadership; Compliance Management exhibits the steepest expansion trajectory.
End User:
Channel economics restructure as procurement authority migrates from internal teams to external service providers.
- Managed Security Service Providers:Consumption-based subscription models replace perpetual licenses as mid-market enterprises dismantle in-house Security Operation Center infrastructure. United States healthcare and retail sectors increasingly delegate operations to specialized vendors.
- IT Security Teams:Direct enterprise procurement persists in large financial institutions and technology companies with dedicated automation engineering capabilities.
- Financial Institutions:Japan's banking and insurance sectors under METI modernization initiatives drive integrated SOAR adoption.
- Government Agencies:Classified and critical infrastructure deployments mandate sovereign control over security orchestration platforms.
Procurement authority is concentrating in Managed Security Service Providers; direct IT Security Team purchasing unwinds across mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable systems landing at Virginia Beach and Bude-Cornwall underpin North American and European data sovereignty architectures that shape SOAR deployment patterns.
United States
SEC cybersecurity disclosure rules and HIPAA security incident protocols compress response timelines for publicly traded companies and healthcare providers. The Department of Health and Human Services enforces breach notification windows that drive automation procurement. Financial services clusters in New York and Chicago deploy playbook-driven systems to satisfy regulatory readiness examinations.
Germany
Automotive manufacturers and energy utilities demand enhanced logging capabilities under the EU AI Act algorithmic accountability standards. The Federal Office for Information Security coordinates NIS2 Directive implementation across critical infrastructure operators. Industrial cybersecurity hubs in Munich and Stuttgart integrate compliance-automation workflows into manufacturing execution systems.
Japan
METI-guided digital transformation initiatives in banking and insurance create demand for integrated SOAR platforms. The Ministry of Economy, Trade and Industry mandates modernization timelines for financial sector security operations. Tokyo and Osaka financial districts deploy orchestration systems to satisfy cross-border incident reporting requirements.
France
Energy utilities under CNIL oversight implement automated breach notification systems to satisfy GDPR data processing records. The Commission nationale de l'informatique et des libertés enforces transparency requirements for machine-initiated containment actions. Paris and Lyon industrial zones demand audit trail preservation for algorithmic decision-making.
United Kingdom
Financial conduct regulators mandate demonstrable incident response capabilities across London capital markets. The Bank of England and Prudential Regulation Authority supervise operational resilience requirements for systemic institutions. The City of London and Canary Wharf deploy cloud-native orchestration to replace legacy Security Operation Center infrastructure.
Global Security Orchestration Automation and Response (SOAR) Market Competitive Landscape
Listed leaders compete with private specialists across channel economics and deployment architecture differentiation. The vendor base organizes into tiered positions based on platform breadth versus vertical specialization. Three archetypes dominate: diversified cybersecurity platforms with integrated SOAR modules, standalone orchestration specialists, and IT service management vendors extending into security workflows. Competitive moves concentrate on strategic partnerships with Managed Security Service Providers and portfolio convergence with adjacent observability tools.
Within the diversified platform tier, Palo Alto Networks and Cisco Systems exemplify channel-anchored distribution models, while IBM Corporation occupies a position representing mainframe-integrated security workflows across regulated industries. Splunk Inc. sits within the data-platform convergence archetype, competing on unified telemetry pipelines that combine security and performance analytics.
| Leading Market Players |
|---|
| IBM Corporation |
| Splunk Inc. |
| Microsoft Corporation |
| Palo Alto Networks |
| Cisco Systems |
| Fortinet |
| Rapid7 |
| Swimlane |
| ServiceNow |
| Others |
Supply & Pricing Matrix
Ninety-day provisioning cycles for cloud-native orchestration platforms compress procurement windows while amplifying pricing power for vendors with pre-integrated compliance modules. This lead-time compression favors suppliers anchored in United States and German data center corridors, where GDPR and EU AI Act certification investments create tiered access barriers.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and MSSP consumption bands. Subscription SaaS models dominate, with price differentiation hinging on playbook library depth and automated response velocity. Cost compression in mid-market tiers intensifies because channel partners absorb implementation overhead. MSSP buyers exhibit highest price sensitivity; financial institutions with regulatory examination mandates show lowest.
Supply Chain Analysis
Inventory provisioning for hybrid deployment hardware stretches to sixteen-week horizons in constrained semiconductor environments. Software supply concentrates in the United States, Ireland, and Singapore, with cloud infrastructure drawing from hyperscaler compute pools in Frankfurt, Virginia, and Tokyo. Single-source vulnerability sits with proprietary AI model training pipelines. Distribution runs through certified MSSP channel partners rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Switching costs escalate once playbooks embed in compliance audit trails, locking buyers into incumbent platforms.
For Market Incumbents: Compound channel density by acquiring specialized MSSP certification programs in Japan and Germany. Deepen API integration moats against standalone orchestration specialists threatening margin pools. Prioritize EU AI Act algorithmic transparency tooling as a retention lever.
For New Entrants and Emerging Players: Lead with natural-language playbook generation targeting mid-market healthcare providers lacking dedicated automation engineering. France and United Kingdom energy utilities present the most penetrable white-space for compliance-automation workflows. Pursue OEM embedding partnerships with observability platform vendors.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounder play because MSSP channel concentration creates predictable consumption ramps. Target acquisition profiles emphasizing vertical-specific playbook libraries over generic orchestration engines. Watch for inflection when agentic AI architectures achieve autonomous containment without human-in-the-loop requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| MSSP Channel Certification Program | Locks in recurring consumption through embedded audit-trail dependencies under SEC and HIPAA mandates. |
| Agentic AI Architecture Deployment | Compresses mean-time-to-response for German automotive manufacturers facing EU AI Act transparency deadlines. |
| Observability Platform Integration | Opens cross-sell pipelines into Japanese financial institutions under METI modernization guidelines. |
| Vertical Playbook Library Acquisition | Accelerates time-to-value for United States healthcare providers with specialized PHI breach protocols. |
| Regional Data Sovereignty Infrastructure | Satisfies GDPR and NIS2 cross-border constraints for French energy utilities under CNIL oversight. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CISOs, MSSP operations directors, SOC automation engineers, and compliance officers; and secondary validation against SEC cybersecurity disclosure filings, EU NIS2 implementation guidance, METI digital transformation white papers, and healthcare breach notification databases. Bottom-up deployment volume estimates triangulated against top-down vendor revenue attribution.
Across the projection horizon, the analytical framework modeled deployment architecture, solution type automation depth, buyer archetype channel structure, and use case regulatory intensity. CAGRs derived from segment-level adoption curves weighted by compliance mandate enforcement timelines. Forecast inputs incorporated cloud infrastructure capex trajectories and MSSP consolidation velocity.
Forecasts assume regulatory continuity in United States SEC disclosure regimes, EU AI Act implementation, and Japan METI guidance; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Home Webcam Market
Security Software
Anti-Fraud Management System Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Security Software Market
Security Software
Global Email Verification Tools Market
Security Software
Parental Control Software Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Global Cloud IAM Market
Security Software
Global Visitor Management System Market
Security Software
Global Enterprise Key Management Market
Security Software
Global Network Encryption Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Confidential Computing Market