
 Mobile Antivirus Software Market | 2026-2036
Mobile Antivirus Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Antivirus Software Market Insights
The EU AI Act is repositioning how mobile security vendors architect threat detection engines, forcing algorithmic transparency into endpoint protection stacks. Kaspersky leverages its Moscow-based malware research infrastructure to sustain deep telemetry advantages in emerging threat categories. Bitdefender anchors its competitive stance through Bucharest-engineered behavioral analysis layers that differentiate against signature-heavy rivals.
Mobile antivirus software constitutes endpoint protection platforms engineered to detect, quarantine, and remediate malicious code on smartphones and tablets, typically integrating heuristic engines with cloud-backed threat intelligence feeds operating below 200ms response thresholds. The primary commercial purpose centers on preventing data exfiltration, credential theft, and ransomware propagation across personally owned and corporate-liable devices. Enterprise deployment models dominate margin pools as CIOs mandate SaaS-delivered consoles with hybrid on-device and cloud-based scanning architectures, while freemium consumer tiers serve as acquisition funnels with limited monetization depth. Real-time protection modules command premium pricing against scheduled malware scanning due to persistent memory-resident monitoring requirements.
The EU AI Act, GDPR, and India's CERT-In directives collectively shape product roadmaps by mandating explainable detection logic, breach notification timelines, and domestic data residency for government end users. Vendors must navigate fragmented certification pathways where European algorithmic accountability standards diverge from Indian operational security mandates. Stakeholders should monitor regulatory divergence between Brussels and New Delhi as compliance costs threaten to fragment product architectures and delay unified platform rollouts.
Market Dynamics
The EU AI Act is forcing algorithmic transparency into mobile threat detection engines, compelling vendors to redesign heuristic models for explainable output while maintaining sub-200ms response thresholds.
Growth Catalysts
- GDPR breach notification mandates:European enterprises accelerate procurement of endpoint protection suites to meet 72-hour disclosure timelines.
- Financial services mobility adoption:Banks and insurers deploy SaaS-delivered consoles across BYOD fleets to prevent credential theft.
- India CERT-In directives:Domestic data residency requirements for government end users create localized product demand.
Market Restraints
- Algorithmic audit costs:EU AI Act compliance documentation requirements inflate R&D overhead for behavioral analysis layers.
- Signature database fragmentation:Divergent malware telemetry standards between Brussels and New Delhi complicate unified threat intelligence architectures.
- Freemium monetization ceiling:Consumer tiers face conversion rate compression as Android and iOS harden native security controls.
Strategic Opportunities
- Regulated Indian government verticals:CERT-In compliance creates captive demand for domestic data residency configurations.
- Zero-trust architecture convergence:Mobile endpoint protection integrates with identity access management platforms in financial services.
- German automotive connectivity:IVI systems and fleet telematics expand attack surfaces requiring specialized automotive-grade scanning modules.
Industry Challenges
- ML explainability engineering shortage:Vendors struggle to recruit talent capable of translating black-box detection into audit-ready decision trees.
- Legacy SIEM integration friction:CIOs face API complexity when merging mobile telemetry into existing security operations centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Antivirus Software Market |
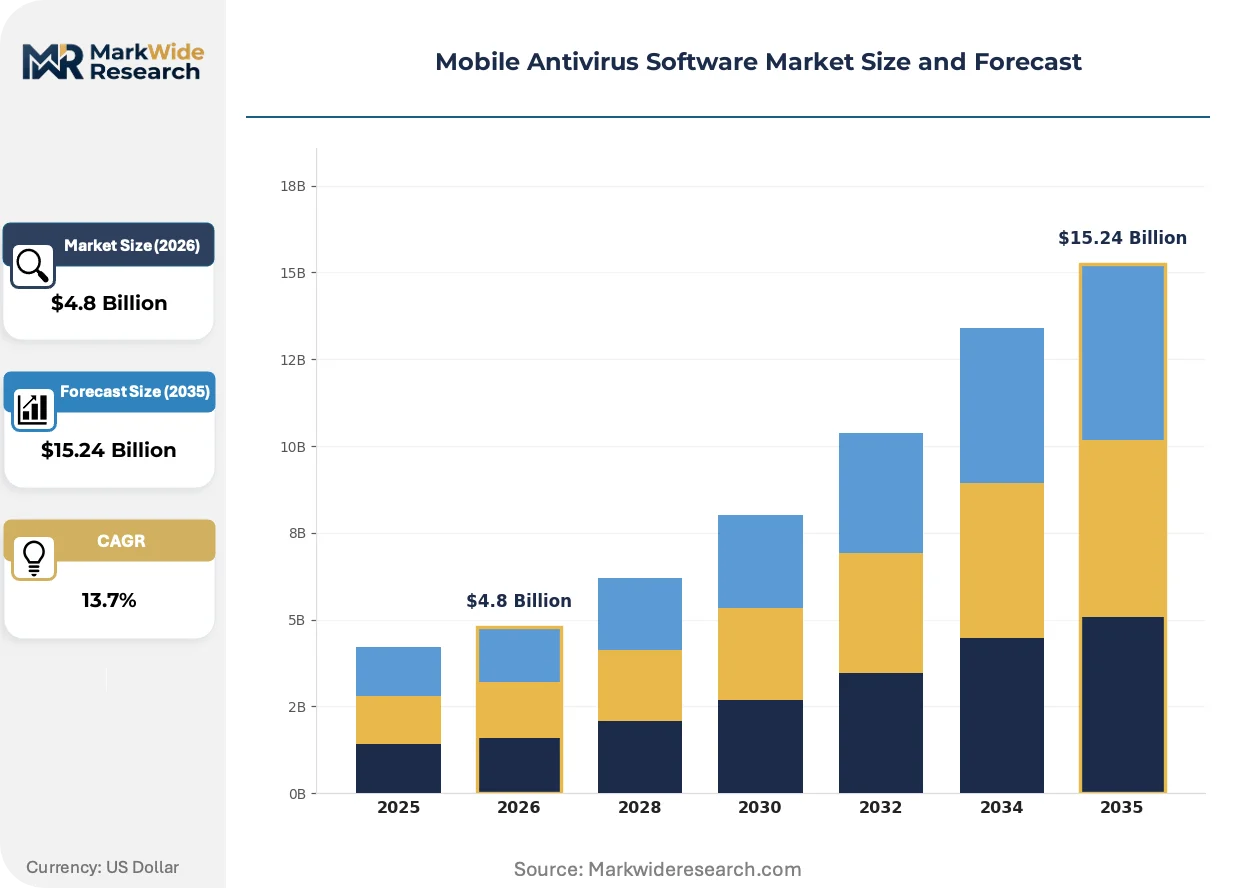
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Free, Paid, Enterprise, Freemium Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Individuals, SMBs, Large Enterprises, Governments Service Type: Real-Time Protection, Malware Scanning, Backup Solutions, VPN Services |
| Companies Covered | Kaspersky, TotalAV, Norton, Microsoft Defender, Sophos, Bitdefender, Avast, Quick Heal Seqrite, Trend Micro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Antivirus Software Market Trends and Innovations
On-device machine learning is compressing cloud dependency for real-time threat detection, while regulatory mandates in Europe and Asia-Pacific reshape how vendors architect data flows and algorithmic accountability.
On-device neural processing units are integrating federated learning models that execute behavioral analysis locally without transmitting raw telemetry to cloud infrastructure. German automotive manufacturers and US financial institutions adopt these architectures to satisfy data minimization principles. This compression of cloud round-trips is integrating edge-first security postures that reduce latency exposure during network handoffs.
The EU AI Act's high-risk system classification extends to autonomous threat detection engines, requiring technical documentation of training data provenance and performance metrics. Vendors serving European enterprise clients must maintain conformity assessment records accessible to national market surveillance authorities. Banking and healthcare verticals face the steepest compliance burden as their mobile endpoints process sensitive personal data triggering algorithmic accountability obligations.
Security procurement in regulated industries now prioritizes bundled endpoint detection and response over standalone antivirus licenses. CIOs consolidate vendor relationships to reduce integration overhead and streamline incident response workflows. This concentration pattern is most visible in United States healthcare systems and German manufacturing conglomerates where procurement teams negotiate enterprise-wide platform contracts replacing point solutions.
Mobile Antivirus Software Market Segmentation
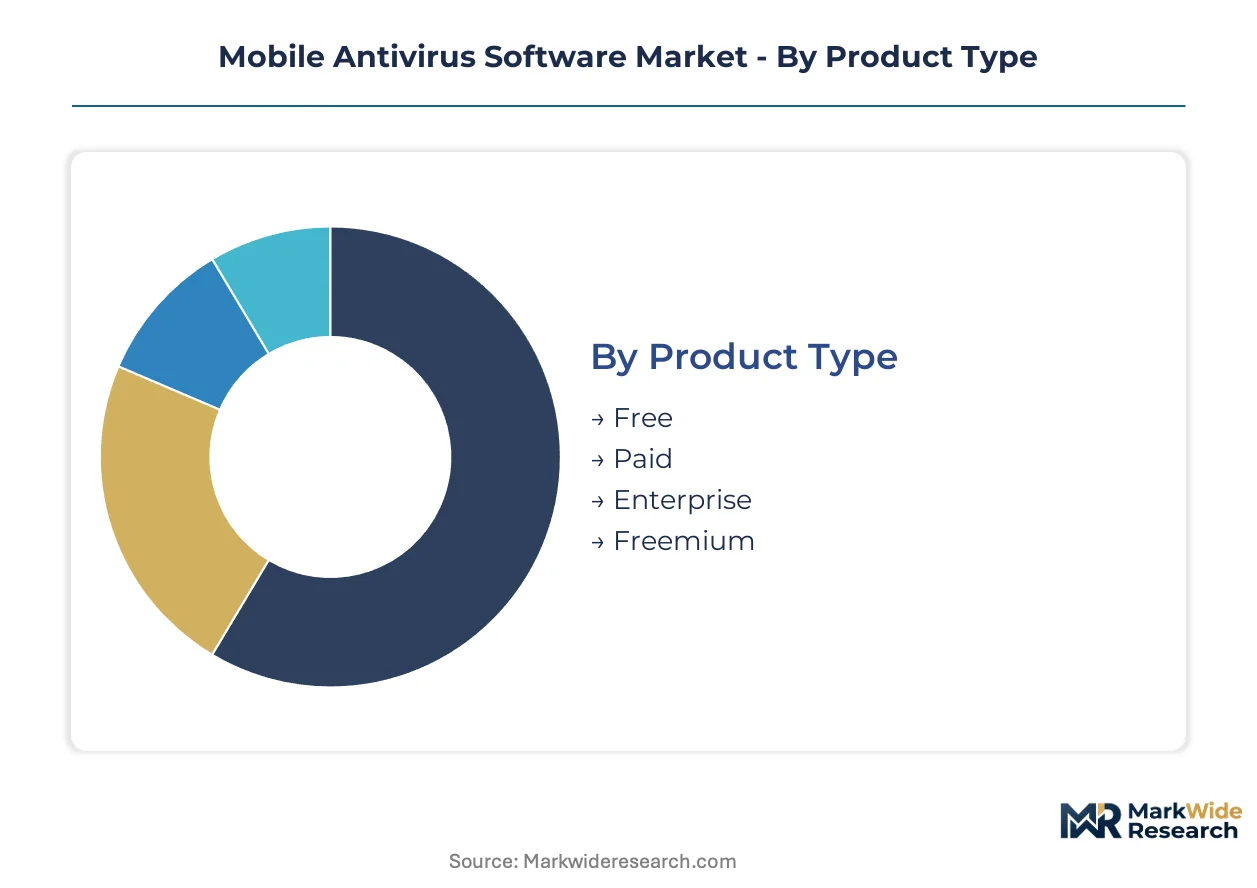
Mobile antivirus architectures fragment across four critical dimensions that determine integration depth with enterprise security stacks. Product type and deployment mode dictate margin structures, while end-user scale and service layering define competitive positioning against native platform security.
Product Type:
Integration depth separates standalone consumer offerings from embedded enterprise suites requiring SIEM connectivity and policy orchestration layers.
- Free:Ad-supported baseline protection with signature-based scanning and limited heuristic coverage. Demand concentrates among price-sensitive consumers in India and Southeast Asia where device replacement cycles compress software investment horizons.
- Paid:Subscription tiers unlocking real-time monitoring, anti-phishing modules, and priority threat intelligence feeds. German and US households drive recurring revenue as privacy consciousness hardens post-GDPR enforcement.
- Enterprise:Unified endpoint protection platforms with centralized policy management, EDR telemetry, and API integrations into identity access management systems. Financial services procurement in London, New York, and Singapore mandates these configurations for BYOD fleet compliance.
- Freemium:Conversion-optimized models using basic virus scanning as acquisition funnel toward premium identity protection and VPN upsells. Conversion rates face compression as Android and iOS native security controls narrow the perceived value gap.
Volume placements concentrate in Free tiers; the faster expansion belongs to Enterprise as regulated industries consolidate vendor relationships.
Deployment:
Cost tier stratification runs from capital-intensive on-premises hardware to variable-cost SaaS consumption models reshaping procurement economics.
- Cloud-Based:Threat intelligence and signature updates delivered from vendor-controlled infrastructure with minimal on-device compute requirements. Indian government verticals under CERT-In directives increasingly reject this architecture for sensitive classifications.
- On-Premises:Dedicated appliance or private cloud deployments maintaining complete data sovereignty and air-gapped update mechanisms. German automotive manufacturers and defense contractors mandate these configurations for IP protection and GDPR Article 32 compliance.
- Hybrid:Split architectures executing behavioral analysis locally while leveraging cloud telemetry for signature correlation and machine learning model refreshes. US healthcare systems adopt this balance to satisfy HIPAA technical safeguards without latency penalties.
- SaaS:Fully managed consoles with per-seat pricing, automatic feature updates, and vendor-operated backend infrastructure. SMB procurement in Brazil and Mexico favors this operational expenditure model over capital-intensive alternatives.
Customer procurement is shifting toward Hybrid; SaaS claims the steepest expansion trajectory among mid-market adopters.
End User:
Application context determines feature depth—from consumer convenience to national security compliance obligations.
- Individuals:Personal device protection prioritizing usability, battery efficiency, and minimal configuration overhead. Privacy-conscious segments in California and Berlin drive demand for transparency dashboards showing exactly what data leaves the device.
- SMBs:Small IT teams requiring simplified management consoles with essential endpoint protection without dedicated security operations centers. Limited integration budgets favor bundled solutions over best-of-breed point products.
- Large Enterprises:Complex environments demanding EDR capabilities, threat hunting tools, and automated incident response workflows. Fortune 500 procurement teams negotiate multi-year platform contracts consolidating mobile, desktop, and server protection under single vendors.
- Governments:Classified and sensitive unclassified systems requiring domestic data residency, supply chain integrity certifications, and algorithmic auditability. India's CERT-In directives and EU AI Act high-risk system classifications impose the steepest architectural constraints.
Revenue concentration sits with Large Enterprises; Governments are gaining share fastest as sovereign cybersecurity mandates proliferate.
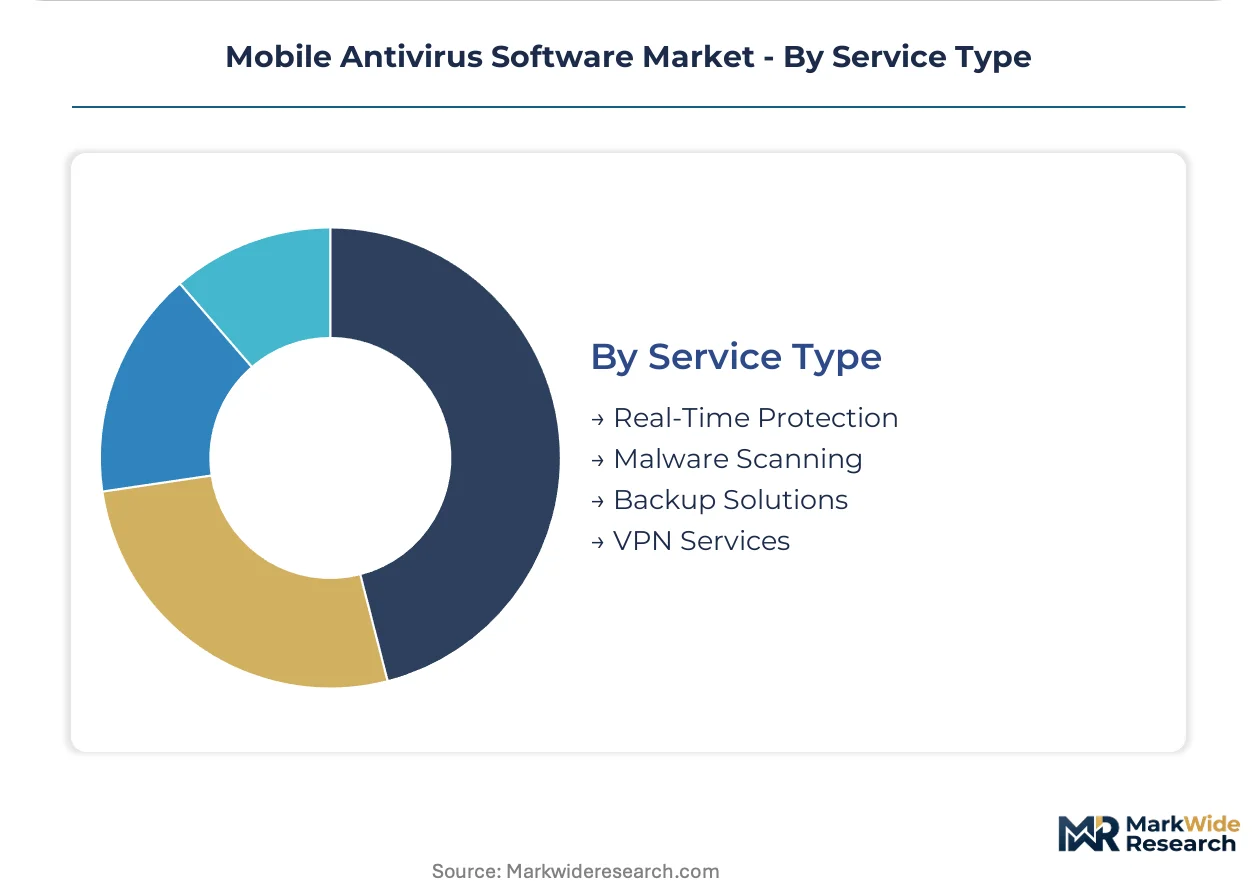
Service Type:
Margin tier differentiation separates commodity scanning from premium persistent protection and adjacent security services.
- Real-Time Protection:Memory-resident monitoring intercepting malicious code execution, network-based attacks, and behavioral anomalies before system compromise. Premium pricing reflects continuous CPU and battery utilization tradeoffs.
- Malware Scanning:Scheduled or on-demand signature matching against known threat databases with minimal background resource consumption. Commoditization pressure intensifies as operating systems integrate baseline scanning capabilities.
- Backup Solutions:Encrypted cloud storage for contacts, photos, and application data with ransomware recovery workflows. Cross-sell integration with identity protection suites drives attachment rates in consumer segments.
- VPN Services:Encrypted tunneling for public Wi-Fi protection and geo-obfuscation, increasingly bundled as standard rather than premium tier differentiator. Regulatory scrutiny of VPN logging practices reshapes vendor selection criteria in privacy-sensitive markets.
Attachment rates concentrate in Real-Time Protection; VPN Services are climbing the fastest as remote work permanence extends mobile threat exposure beyond traditional perimeters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development activity concentrates in the United States and Germany while deployment demand accelerates in India and Southeast Asia. European regulatory complexity creates premium market segments. Asian price sensitivity sustains freemium model dominance.
United States
Financial services and healthcare verticals drive enterprise procurement of SaaS-delivered endpoint protection suites. HIPAA technical safeguards and SEC cybersecurity disclosure rules mandate persistent mobile monitoring across BYOD fleets. New York and San Francisco financial districts host concentrated deployment of zero-trust architecture integrations.
Germany
Automotive manufacturers and industrial conglomerates demand on-premises deployments with GDPR Article 32 compliance certification. The EU AI Act high-risk system classification forces algorithmic auditability into threat detection engines. Munich and Stuttgart engineering clusters specialize in automotive-grade scanning modules for IVI systems.
India
CERT-In directives for domestic data residency create captive demand in government and defense verticals. Price-sensitive consumers sustain the world's largest freemium user base with limited conversion depth. Bengaluru and Hyderabad technology corridors host indigenous security software development for sovereign compliance requirements.
United Kingdom
London financial services procurement consolidates vendor relationships under enterprise-wide platform contracts. The Information Commissioner's Office enforces GDPR breach notification timelines accelerating endpoint protection refresh cycles. The City of London and Canary Wharf banking clusters mandate EDR-capable mobile security stacks.
Japan
Manufacturing and automotive supply chains require specialized mobile protection for industrial IoT convergence. METI cybersecurity guidelines emphasize supply chain integrity certifications for critical infrastructure vendors. Nagoya and Osaka industrial zones deploy behavioral analysis layers for OT-IT boundary protection.
Mobile Antivirus Software Market Competitive Landscape
The competitive structure tilts toward diversified cybersecurity platforms with mobile endpoints as integration modules rather than standalone products. Tier-one vendors leverage existing enterprise relationships to cross-sell mobile protection, while specialist vendors compete on detection latency and behavioral analysis depth. Two strategic archetypes dominate: integrated platform providers bundling mobile into endpoint detection and response suites, and regional specialists capturing sovereign compliance niches. Consolidation through strategic partnerships and technology licensing agreements accelerates as CIOs demand unified consoles.
Within the integrated platform tier, Kaspersky and Bitdefender exemplify divergent geographic positioning strategies. Kaspersky maintains Moscow-based malware research infrastructure sustaining telemetry depth in emerging threat categories. Bitdefender anchors its competitive stance through Bucharest-engineered behavioral analysis layers. Among Asia-Pacific specialists, Quick Heal Seqrite occupies a position calibrated to Indian CERT-In compliance requirements.
| Leading Market Players |
|---|
| Kaspersky |
| TotalAV |
| Norton |
| Microsoft Defender |
| Sophos |
| Bitdefender |
| Avast |
| Quick Heal Seqrite |
| Trend Micro |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement consolidation under GDPR and EU AI Act mandates is compelling vendors to absorb algorithmic audit and certification costs upfront, compressing margin structures and forcing tier repricing across deployment architectures.
Pricing Analysis
Response-time guarantees anchor value-based pricing tiers, with sub-200ms threat detection commanding premium SaaS rates against scheduled scanning alternatives. Subscription models stratify across real-time protection depth, EDR telemetry integration, and managed incident response bundling. Cost compression in freemium tiers intensifies as Android and iOS native security controls narrow perceived differentiation. Government verticals in India and Germany exhibit lowest price sensitivity due to sovereign compliance mandates, while Southeast Asian consumer segments drive volume at minimal conversion depth.
Supply Chain Analysis
Cross-border data transmission costs and residency requirements are fragmenting cloud infrastructure footprints across Germany, India, and the United States. Threat intelligence engine development draws from Bucharest, Moscow, and Bengaluru engineering clusters, with malware signature databases sourced from vendor-controlled telemetry networks. Single-source vulnerability concentrates in cloud-reliant update mechanisms subject to CERT-In and GDPR Article 32 operational restrictions. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and OEM device preloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification erects a compliance moat that favors incumbent vendors with established conformity assessment infrastructure and documented algorithmic provenance.
For Market Incumbents: Acquire specialized ML explainability engineering teams to translate black-box detection into audit-ready decision trees. Consolidate threat intelligence telemetry advantages through deeper integration with Moscow-based and Bucharest-engineered research infrastructure. Defensive positioning requires preemptive certification investment before EU AI Act enforcement timelines compress competitive windows.
For New Entrants and Emerging Players: Managed security service providers represent the most accessible channel partner type for bypassing direct enterprise sales barriers. White-space concentration sits in Indian government verticals demanding CERT-In-compliant domestic data residency configurations. Penetrate through API-first integration plays into zero-trust architecture deployments where incumbent platform fatigue creates substitution openings.
For Investors and Strategic Acquirers: The window for entry favors regional specialists with sovereign compliance certifications and captive government relationships. Long-term viability hinges on algorithmic accountability capabilities becoming non-negotiable procurement criteria. Monitor EU AI Act implementation variance across member states as the signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Certification | EU AI Act compliance documentation creates vendor differentiation in European enterprise procurement. |
| Domestic Data Residency Deployment | CERT-In directive adherence unlocks Indian government and defense vertical captive demand. |
| EDR Platform Integration | Consolidated endpoint detection and response bundling displaces standalone antivirus licenses in regulated industries. |
| Automotive-Grade Module Development | IVI and telematics scanning specialization captures German manufacturer connectivity security spend. |
| Federated Learning Architecture | On-device behavioral analysis satisfies GDPR data minimization without cloud round-trip latency penalties. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CISOs, IT procurement officers, platform engineers, and channel partners across financial services, healthcare, and government verticals. Secondary validation drew from SEC filings, EU AI Act implementation guidance, CERT-In directive documentation, and hyperscaler security partnership disclosures. Bottom-up segment modeling triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed deployment architecture, organization scale, vertical regulatory intensity, and geographic compliance cluster as core segmentation dimensions. CAGRs derived from trend extrapolation and adoption curve analysis across the projection horizon. Forecast inputs incorporated endpoint device shipment trajectories, BYOD policy penetration rates, and sovereign cybersecurity mandate implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement variance, native platform security capability leaps, and geopolitical disruption of threat intelligence sharing agreements. Forecasts reflect assumptions about compliance cost absorption and conversion rate stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Hardware Encryption Market
Security Software
Network Camera and Video Analytics Market
Security Software
Europe Smart Doorbell Market
Security Software
Global Background Check Software Market
Security Software
Privacy Management Software Market
Security Software
North America Video Management System Market
Security Software
AI Security Platforms Market
Security Software
Europe Enterprise Firewall Market
Security Software
Global Password Management Software Market
Security Software
AI in Security Market
Security Software
Europe User Provisioning Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Information Rights Management Market
Security Software
Sound Masking Systems Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Global Cloud IAM Market