
 Studio Lighting Equipment Market | 2026-2036
Studio Lighting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Studio Lighting Equipment Market Analytics
EU Ecodesign Directive is consolidating compliance costs for smaller lighting manufacturers while rewarding scale. ARRI leverages its Munich engineering base to sustain premium positioning across cinema-grade Fresnel systems. Godox anchors volume production through Shenzhen's integrated electronics supply chain, competing aggressively on cost-to-lumen ratios. Profoto differentiates via proprietary wireless triggering ecosystems that lock in professional photographer loyalty.
Studio lighting equipment encompasses electrically powered luminaires engineered for controlled illumination in image-capture environments, typically specifying color rendering index above 90 and correlated color temperature tunability between 2700K and 6500K. These systems serve film production, broadcast studios, and commercial photography by eliminating variable ambient light and enabling repeatable exposure conditions. LED lights now lead product-type value generation due to thermal efficiency and dimming precision, while strobe lighting retains dominance in high-speed photography applications where microsecond flash duration matters. Intelligent lighting represents the fastest-expanding technology segment, integrating DMX512 control and automated color-mixing algorithms that reduce setup labor for event planners and broadcast engineers.
FCC Part 15 emissions standards govern wireless control modules in US-sold equipment, compelling RF shielding investments that raise bill-of-materials costs. CE marking under the EU Low Voltage Directive and RoHS substance restrictions shape European market access, with ECHA REACH compliance adding supply-chain documentation burdens for imported aluminum housings and phosphor coatings. Stakeholders must monitor whether China's GB standards for LED performance diverge further from IEC norms, as such fragmentation would force dual-sku strategies that erode margin pools.
Market Dynamics
The streaming economy is compressing product lifecycles and fragmenting buyer profiles, forcing manufacturers to serve both high-volume content creators and precision-demanding cinema professionals simultaneously.
Growth Catalysts
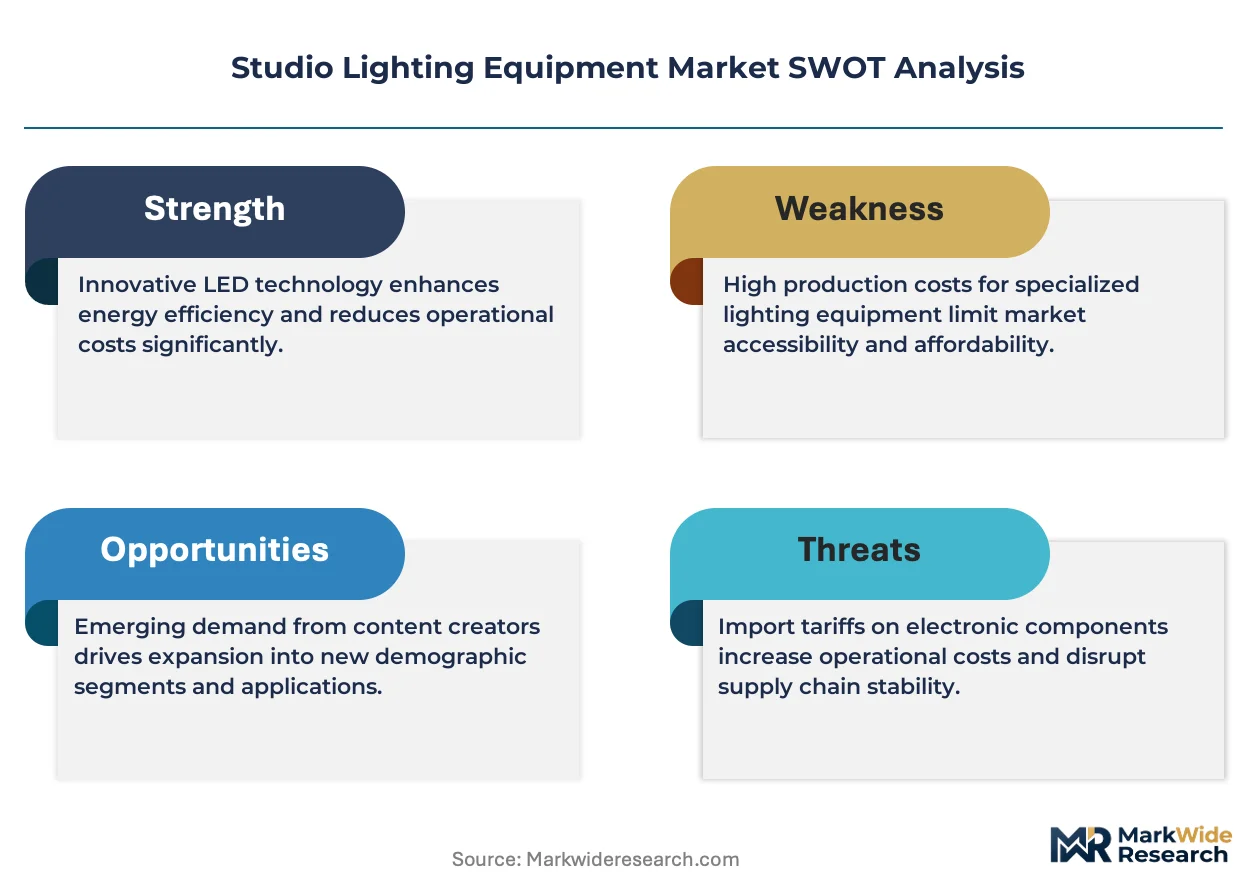
- EU Ecodesign Directive:Tightened energy-efficiency standards are accelerating LED architecture upgrades across European distribution channels, creating replacement demand for legacy tungsten and HMI inventories.
- Shenzhen electronics ecosystem:Vertical integration of LED chip fabrication, driver electronics, and aluminum extrusion within a 50-kilometer radius compresses production costs and shortens prototype-to-shipment cycles.
- DMX512 control protocol:Standardized digital communication is reducing setup complexity for event production crews, expanding addressable market into mid-tier rental houses and corporate AV departments.
Market Restraints
- Phosphor and rare-earth input costs:Yttrium and europium price volatility in Chinese spot markets creates margin compression for LED manufacturers locked into annual distributor contracts.
- Single-source RF module dependency:Wireless triggering systems rely on concentrated Taiwanese semiconductor foundries, exposing brands to allocation risk during consumer electronics demand spikes.
- Microsecond flash duration ceiling:LED technology cannot match strobe lighting's freeze-frame capability in high-speed photography, preserving a shrinking but defensible addressable market for legacy xenon tube architectures.
Strategic Opportunities
- India content creator expansion:YouTube and Instagram penetration in tier-two Indian cities is outpacing professional lighting availability, creating first-mover advantage for compact panel distributors building local service networks.
- LiDAR-to-lighting convergence:Spatial mapping sensors from automotive supply chains are enabling automated beam-steering for virtual production stages, opening cinematography applications previously requiring manual rigging crews.
- EU CSRD reporting mandates:Corporate sustainability disclosures are pushing broadcast studios toward energy-auditable lighting inventories, favoring suppliers with verified lifecycle carbon data.
Industry Challenges
- Gaffer-to-technician skill translation:Traditional lighting crews trained in tungsten color temperature intuition struggle with LED color-mixing interfaces, slowing adoption on union-regulated film sets.
- Multi-protocol integration complexity:Simultaneous support for DMX512, Art-Net, sACN, and proprietary wireless ecosystems strains firmware development resources and extends certification timelines.
- REACH documentation burden:ECHA substance-of-concern declarations for imported aluminum housings and phosphor coatings add 8-12 week delays to European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Studio Lighting Equipment Market |
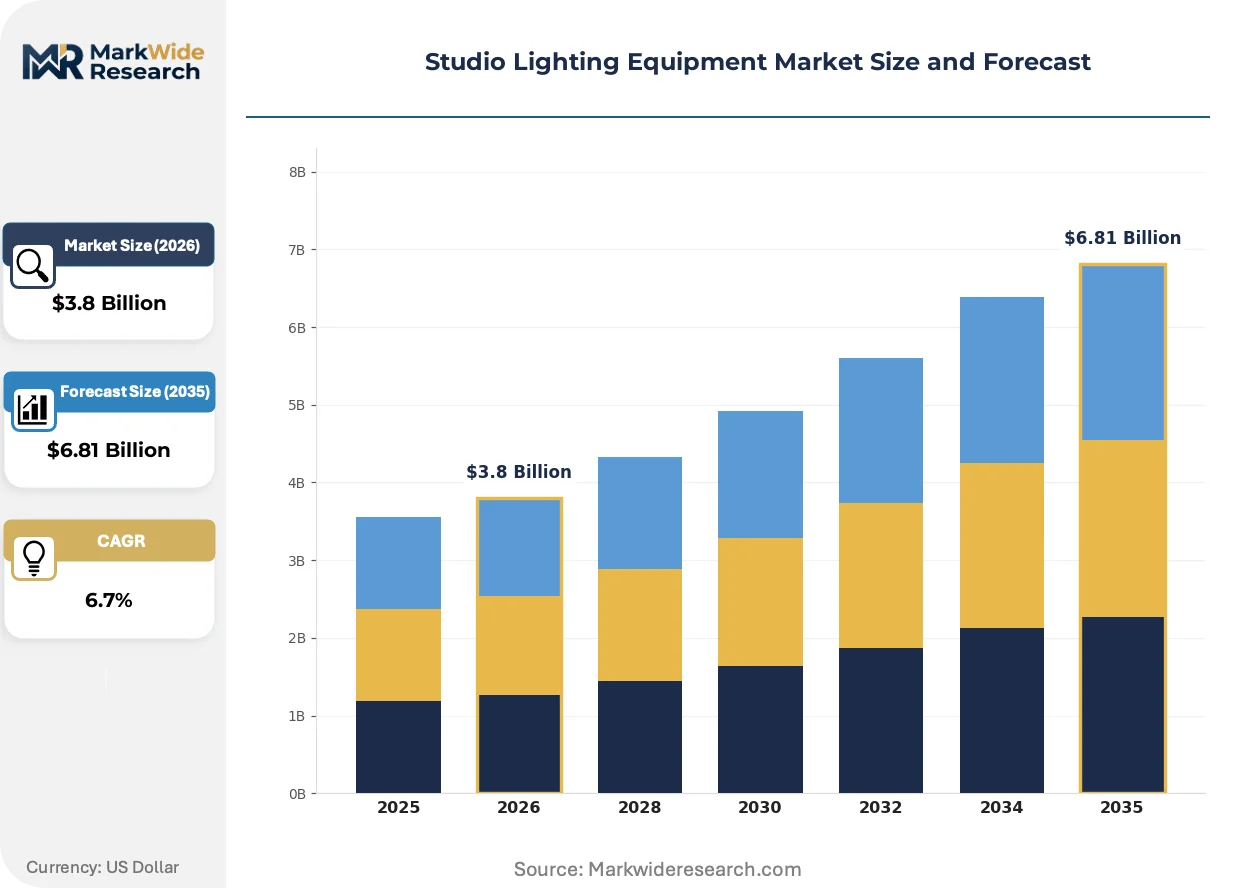
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Softbox, Fresnel Lights, Ring Lights Usage: Photography, Videography, Broadcast, Theater Technology: Continuous Lighting, Strobe Lighting, Hybrid Lighting, Intelligent Lighting End User: Studios, Filmmakers, Photographers, Event Planners |
| Companies Covered | Litepanels, Godox, ARRI, Elinchrom, Profoto, Aputure, Nanlite, Broncolor, Kino Flo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Studio Lighting Equipment Market Evolving Landscape
Computational control and solid-state physics are converging to eliminate traditional trade-offs between color accuracy, thermal management, and form factor that defined studio lighting for decades.
RGBWW LED engines with independent warm-white and cool-white diode channels are decentralizing color correction workflows from post-production suites to on-set lighting consoles. Cinematographers on streaming productions now adjust correlated color temperature in real-time rather than committing to gel filtration. This capability is compressing shooting schedules and reducing rental house equipment turnover.
REACH substance restrictions under ECHA oversight are forcing reformulation of phosphor coatings and solder alloys in European-bound products. Manufacturers with Munich or Rotterdam engineering presence are accelerating compliance documentation, while import-dependent competitors face extended homologation cycles. The professional segment absorbs these costs through premium positioning; entry-tier brands retreat to less regulated export markets.
Subscription-based firmware unlocking is displacing perpetual hardware purchases in high-end cinematography. ARRI and similar brands now tier feature access—color space, wireless mesh density, weather sealing certification—through annual licenses rather than SKU differentiation. North American rental houses favor this model for fleet flexibility; owner-operators in Southern Europe resist recurring obligations.
Studio Lighting Equipment Market Segmentation
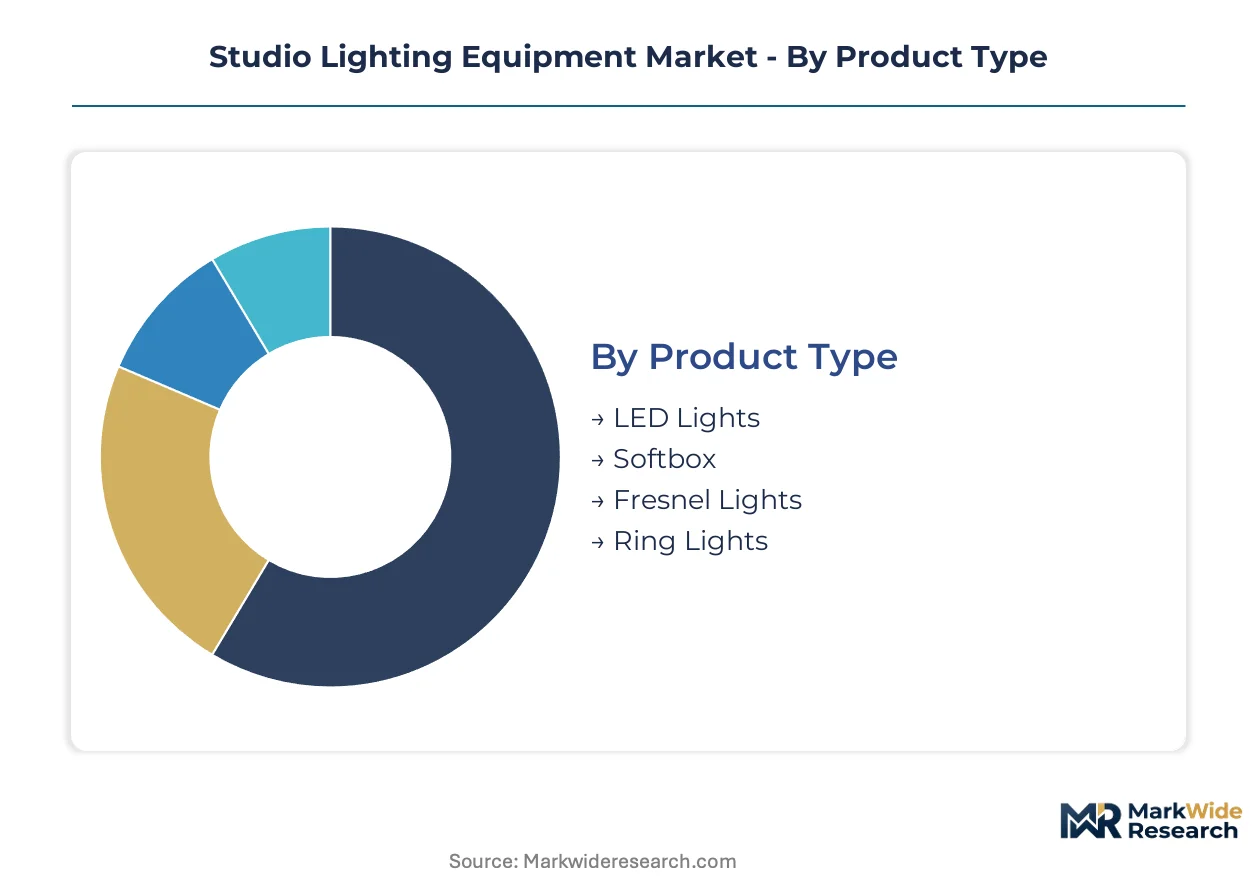
Studio lighting equipment segments diverge sharply on certification intensity and thermal engineering requirements. Product type determines FCC Part 15 exposure for wireless modules, while end-user categories dictate whether CE marking under the Low Voltage Directive suffices or theatrical safety codes apply.
Product Type:
LED Lights and Fresnel systems face distinct electromagnetic compliance pathways under US and European frameworks. FCC Part 15 governs RF emissions in panel arrays with integrated wireless control, while CE marking under the EU Ecodesign Directive imposes minimum luminous efficacy thresholds that legacy tungsten architectures cannot meet.
- LED Lights:Solid-state diode arrays with correlated color temperature tunability between 2700K and 6500K. Streaming content creators in Shenzhen's hardware ecosystem drive volume demand for compact panels with high color rendering index specifications. FCC Part 15 compliance for integrated wireless modules adds bill-of-materials cost pressure.
- Fresnel Lights:Focusable lens systems with adjustable beam angle from spot to flood. Cinema production crews in Munich and Los Angeles specify these for precision spotlighting in narrative filmmaking. Thermal management requirements exceed LED panel standards due to concentrated output density.
- Softbox:Diffusion enclosures modifying raw source quality.
- Ring Lights:Circular arrays for shadowless facial illumination.
LED Lights sits at the top of the volume ranking, with Ring Lights climbing the fastest.
Usage:
Application context determines whether buyers prioritize flicker-free output for high-frame-rate capture or color-mixing flexibility for rapid scene transitions. Broadcast and theater applications impose the most stringent regulatory burdens.
- Photography:Still-image capture requiring precise color temperature control and high-speed sync compatibility. Portrait studios in tier-two Indian cities represent expanding demand for entry-tier strobe systems. Microsecond flash duration requirements preserve xenon tube relevance despite LED efficiency advantages.
- Videography:Motion capture with continuous output and dimming precision. YouTube and Instagram content creators in São Paulo and Jakarta compress product lifecycles through rapid hardware turnover. Flicker-free operation at high frame rates separates professional from consumer tiers.
- Broadcast:Live transmission with DMX512 protocol integration.
- Theater:Stage illumination with automated cueing and safety certification.
Videography commands the largest installed base, while Broadcast shows the steepest expansion trajectory.
Technology:
Technology choice reflects trade-offs between thermal efficiency, flash duration capability, and control protocol complexity. Intelligent systems carry the heaviest firmware certification burden across multiple wireless standards.
- Intelligent Lighting:Automated systems integrating DMX512, Art-Net, and proprietary wireless protocols. Virtual production stages in London and Vancouver deploy these for real-time beam steering without manual rigging. Multi-protocol firmware strains development resources and extends FCC and CE certification timelines.
- Continuous Lighting:Uninterrupted output with precise dimming curves. Documentary filmmakers in Berlin and Sydney favor these for interview setups where flash disruption is unacceptable. LED thermal management determines maximum output duration before automatic throttling.
- Strobe Lighting:Microsecond-duration flash for high-speed freeze-frame.
- Hybrid Lighting:Switchable continuous and strobe modes in single housing.
Continuous Lighting holds the volume lead, with Intelligent Lighting gaining share fastest.
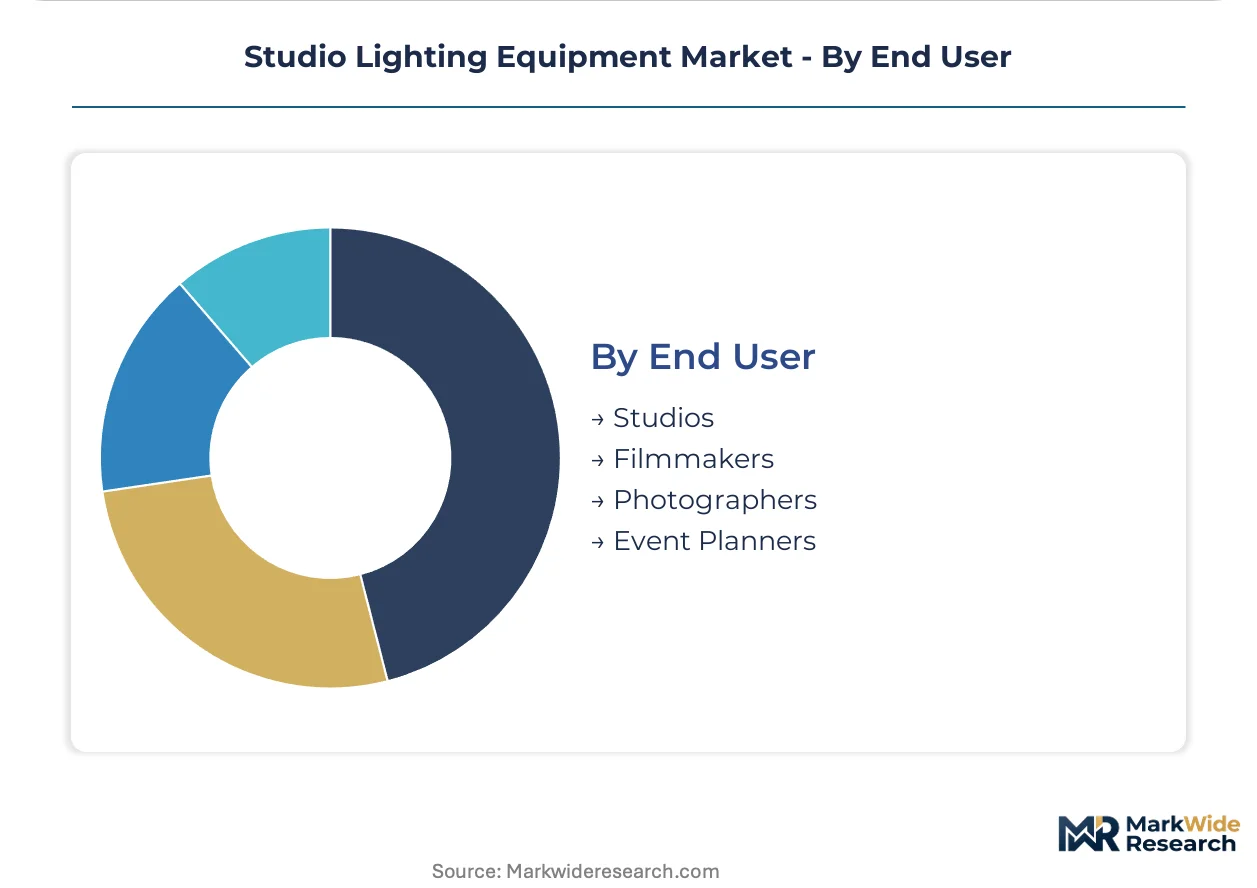
End User:
Customer type segmentation reveals diverging procurement patterns between institutional buyers with sustainability mandates and individual operators prioritizing portability.
- Studios:Permanent installations with energy-auditable inventories under EU CSRD reporting mandates. Broadcast facilities in Rotterdam and Copenhagen specify lifecycle carbon data from suppliers. REACH documentation for aluminum housings and phosphor coatings adds procurement lead time.
- Filmmakers:Owner-operators and rental houses with fleet flexibility requirements. Subscription-based firmware unlocking from Munich-engineered brands displaces perpetual hardware purchases. North American rental houses favor annual licenses; Southern European owner-operators resist recurring obligations.
- Photographers:Individual practitioners with kit portability priorities.
- Event Planners:Corporate AV departments with rapid deployment needs.
Studios dominate absolute spend, with Event Planners expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cinematography talent clusters in Los Angeles, Mumbai, and London drive equipment specification standards that cascade into regional procurement patterns. Gaffer unions and rental house networks in these hubs transmit technical requirements to manufacturers. Regulatory divergence between FCC Part 15 in the United States, EU Ecodesign Directive in Europe, and China's GB standards forces dual-sku strategies that reshape competitive positioning.
United States
Streaming content creators in Los Angeles and Atlanta compress product lifecycles through rapid hardware turnover. FCC Part 15 emissions standards govern wireless control modules, compelling RF shielding investments that raise bill-of-materials costs. The Pacific Northwest hosts post-production facilities that influence lighting specification upstream.
Germany
Munich's engineering base sustains premium positioning across cinema-grade Fresnel systems for narrative filmmakers. CE marking under the EU Low Voltage Directive and RoHS substance restrictions shape market access, with ECHA REACH compliance adding supply-chain documentation burdens. Bavaria's industrial clusters anchor high-end manufacturing.
China
Shenzhen's hardware ecosystem and Godox's manufacturing base anchor global supply for entry-level and mid-tier equipment. GB standards for LED performance are diverging from IEC norms, forcing export-oriented brands into dual-certification strategies. The Pearl River Delta compresses prototype-to-shipment cycles through vertical integration.
India
YouTube and Instagram penetration in tier-two Indian cities is outpacing professional lighting availability, creating first-mover advantage for compact panel distributors. BIS certification requirements for electrical goods add homologation complexity for imported equipment. Maharashtra's media production hubs in Mumbai transmit specification requirements nationwide.
United Kingdom
Virtual production stages in London deploy intelligent lighting for real-time beam steering without manual rigging crews. The UKCA marking transition post-Brexit creates parallel certification obligations alongside retained EU directives. Soho's post-production houses influence upstream equipment specification for broadcast and streaming clients.
Studio Lighting Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance segments. The vendor base organizes around three strategic archetypes: vertically integrated electronics manufacturers leveraging Shenzhen supply chains, Munich-engineered premium brands commanding rental house loyalty, and software-centric challengers monetizing through subscription firmware. Competitive moves concentrate on strategic partnerships with streaming platforms and geographic expansion into underpenetrated creator economies.
Within the premium-engineering tier, ARRI leverages its Munich base to sustain cinema-grade positioning, while Profoto anchors professional photographer loyalty through proprietary wireless ecosystems. Godox occupies a position at the volume-driven end, competing aggressively on cost-to-lumen ratios through Shenzhen's integrated supply chain. These three exemplify how geographic clustering around engineering talent and manufacturing ecosystems translates into divergent competitive strategies.
| Leading Market Players |
|---|
| Litepanels |
| Godox |
| ARRI |
| Elinchrom |
| Profoto |
| Aputure |
| Nanlite |
| Broncolor |
| Kino Flo |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Shenzhen's Pearl River Delta anchor volume-tier production, translating captive LED chip fabrication into pricing discipline that undercuts Munich-engineered premium brands by forty to sixty percent on cost-to-lumen metrics.
Pricing Analysis
Bundled firmware-subscription services now split from unbundled hardware transactions across the professional tier. ARRI and Profoto tier feature access through annual licenses, while Godox and Nanlite compete on transactional per-unit pricing for content creators. CE marking under the EU Ecodesign Directive and FCC Part 15 RF shielding requirements drive price differentiation between certified and uncertified product streams. Pricing pressure stems from rare-earth phosphor cost volatility in Chinese spot markets, compressing margins for manufacturers locked into annual distributor contracts. Individual owner-operators in Southern Europe exhibit highest price sensitivity, resisting recurring subscription obligations; broadcast studios under EU CSRD mandates absorb premium positioning with least friction.
Supply Chain Analysis
Reverse-logistics flows for rental house fleet refurbishment concentrate in Los Angeles and London, where extended product lifecycles recover residual value from Munich-engineered equipment before secondary-market redistribution. Manufacturing gravity centers on China, Taiwan, and Germany, with Shenzhen's fifty-kilometer electronics ecosystem compressing prototype-to-shipment cycles. Yttrium and europium rare-earth dependencies, plus single-source RF module reliance on Taiwanese semiconductor foundries, expose brands to allocation risk during consumer electronics demand spikes. Distribution runs through specialized cinematography rental houses in talent clusters, bypassing mass retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive operates as a regulatory compounder, accelerating replacement demand for legacy tungsten inventories while consolidating compliance costs that reward scale and squeeze import-dependent competitors.
For Market Incumbents: Cement rental house loyalty through proprietary wireless ecosystem lock-in, mirroring Profoto's photographer-retention architecture. Defend against Shenzhen-based cost competitors by deepening Munich-engineered certification documentation for REACH and CE marking, extending homologation delays that disadvantage import-reliant challengers. Prioritize firmware subscription tiering to capture recurring revenue from North American rental houses while maintaining transactional hardware options for price-sensitive Southern European owner-operators.
For New Entrants and Emerging Players: RGBWW color-mixing automation offers a technology-first wedge into virtual production stages in London and Vancouver, where real-time beam steering reduces manual rigging labor. Target tier-two Indian cities where YouTube and Instagram penetration outpaces professional lighting availability, building local service networks before established brands consolidate distribution. Pursue direct-to-creator digital channels rather than rental house intermediaries to bypass incumbent channel control.
For Investors and Strategic Acquirers: Valuations sit cheapest among Shenzhen-anchored mid-tier manufacturers with backward integration into LED chip fabrication but limited brand equity in premium cinematography. Long-term viability hinges on whether content creator volume expansion in India and Southeast Asia sustains cost-to-lumen competition, or whether virtual production automation shifts specification power back toward Munich-engineered intelligent lighting. Monitor LiDAR-to-lighting convergence patents from automotive supply chains as inflection signal for automated beam-steering capability.
| Strategic Initiative | Industry Significance |
|---|---|
| DMX512 Protocol Integration | Reduces setup complexity for event production crews and corporate AV departments. |
| REACH Compliance Documentation | Accelerates European product launches for Munich-engineered brands versus import-dependent competitors. |
| Subscription Firmware Tiering | Captures recurring revenue from North American rental houses seeking fleet flexibility. |
| Local Service Network Buildout | Creates first-mover advantage in tier-two Indian cities outpacing professional lighting availability. |
| LiDAR Sensor Convergence | Enables automated beam-steering for virtual production stages without manual rigging crews. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with lighting gaffers, rental house fleet managers, broadcast engineering directors, and LED manufacturer procurement leads alongside secondary validation. Primary fieldwork drew from SEC filings of publicly traded equipment manufacturers, ECHA REACH substance databases, FCC Part 15 certification records, and customs trade data for LED component flows. Bottom-up demand modeling from content creator penetration metrics triangulated against top-down supply capacity estimates from Shenzhen manufacturing clusters.
Rate-of-change decomposition across the analysis window separated volume growth from mix-shift effects, with CAGRs derived from segmented regression across product type, technology, and end-user dimensions. The forecasting framework modeled LED versus strobe technology substitution curves, DMX512 protocol adoption rates in event production, and streaming platform content budget trajectories as demand drivers. Regional regulatory divergence under FCC Part 15, EU Ecodesign Directive, and China's GB standards informed dual-sku scenario analysis.
The model holds under stable rare-earth pricing and continued Shenzhen ecosystem integration; deviation in phosphor cost volatility or Taiwanese semiconductor allocation shocks would shift margin compression timing. Practitioners should monitor ECHA substance restriction announcements and Chinese GB standard divergence from IEC norms for early signals of compliance cost redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Fluorescent Lighting Market
Lighting
Solar Spotlights Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
GCC Smart Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Art and Museum Lighting Market
Lighting
Display Light Control Film Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
India Lighting Market
Lighting
Circadian Lighting Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
North America Smart Lighting Market
Lighting
Recessed Lighting Market
Lighting
Specialty Lighting Market
Lighting
Ambient Lighting Market
Lighting
Lamps and Lighting Market