
 Architectural Lighting Market | 2026-2036
Architectural Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Lighting Market Intelligence
Market Context
The capability gap between vertically integrated manufacturers and fixture assemblers is collapsing as LED module costs commoditize. Signify anchors its position through captive chip production and proprietary Interact IoT platforms. Cree Lighting leverages silicon carbide substrate expertise to sustain performance leadership in high-lumen output segments. Acuity Brands dominates North American specification channels through its distributed brand architecture and agency-driven specification process.
Technical Definition and Segments
Architectural lighting encompasses engineered luminaires and control systems designed for aesthetic integration, spatial definition, and visual comfort in built environments, typically operating within correlated color temperatures from 2700K to 6500K with color rendering indices exceeding 90 for premium applications. LED luminaires now command the product type landscape as thermal management advances and lumen depreciation curves flatten, while fluorescent fixtures retreat to code-minimum retrofit contexts. Smart lighting and sensor integration represent the fastest-expanding technology clusters as building automation protocols converge on open standards, and hospitality venues generate disproportionate margin pools due to custom specification cycles and designer-driven procurement.
Regulatory Frame
The EU Ecodesign Directive and ENERGY STAR program enforce escalating minimum luminous efficacy requirements that disqualify legacy technologies from new construction and major renovation. The EU AI Act and GDPR impose data governance obligations on connected lighting networks that process occupancy and behavioral data. Stakeholders must monitor harmonization gaps between regional cybersecurity standards for IoT-enabled fixtures and evolving building decarbonization mandates that treat lighting loads as flexible grid assets.
Market Dynamics
LED module commoditization is collapsing the historical capability gap between vertically integrated manufacturers and fixture assemblers, forcing incumbents to differentiate through captive chip production, proprietary IoT platforms, or silicon carbide substrate expertise.
Growth Catalysts
- EU Ecodesign Directive tightening:Escalating minimum luminous efficacy thresholds disqualify legacy technologies from new construction across Germany, the Netherlands, and France, accelerating specification-grade LED retrofits.
- Hospitality venue expansion:Southeast Asian hotel and resort developments are expanding custom specification cycles, generating disproportionate margin pools through designer-driven procurement processes.
- Silicon carbide substrate advances:Thermal management breakthroughs enable high-lumen output segments with flattened depreciation curves, sustaining performance leadership in premium architectural applications.
Market Restraints
- LED chip supply concentration:Captive production capabilities concentrate among East Asian substrate manufacturers, exposing fixture assemblers to input cost volatility and allocation constraints.
- GDPR data governance friction:Connected lighting networks processing occupancy and behavioral data face compliance complexity that extends sales cycles and limits retrofit deployment velocity.
- Fluorescent code-minimum substitution:Budget-constrained municipal and educational retrofits retain legacy fixtures where capital availability blocks LED specification upgrades.
Strategic Opportunities
- Building automation protocol convergence:Open standards integration between lighting controls and HVAC systems creates specification pull from smart building developers seeking unified management platforms.
- Flexible grid asset monetization:EU building decarbonization mandates treat lighting loads as demand-response resources, enabling utility-backed financing models for networked installations.
- Underpenetrated Southeast Asian hospitality:Resort and mixed-use developments in Vietnam and Indonesia lack established specification channels, creating first-mover advantages for agency-network entrants.
Industry Challenges
- IoT cybersecurity skill scarcity:Fixture manufacturers lack embedded security engineering capacity to harmonize regional cybersecurity standards for connected products across multiple export markets.
- Legacy control system integration:BACnet and DALI protocol fragmentation forces custom engineering for each retrofit, compressing project margins and extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Lighting Market |
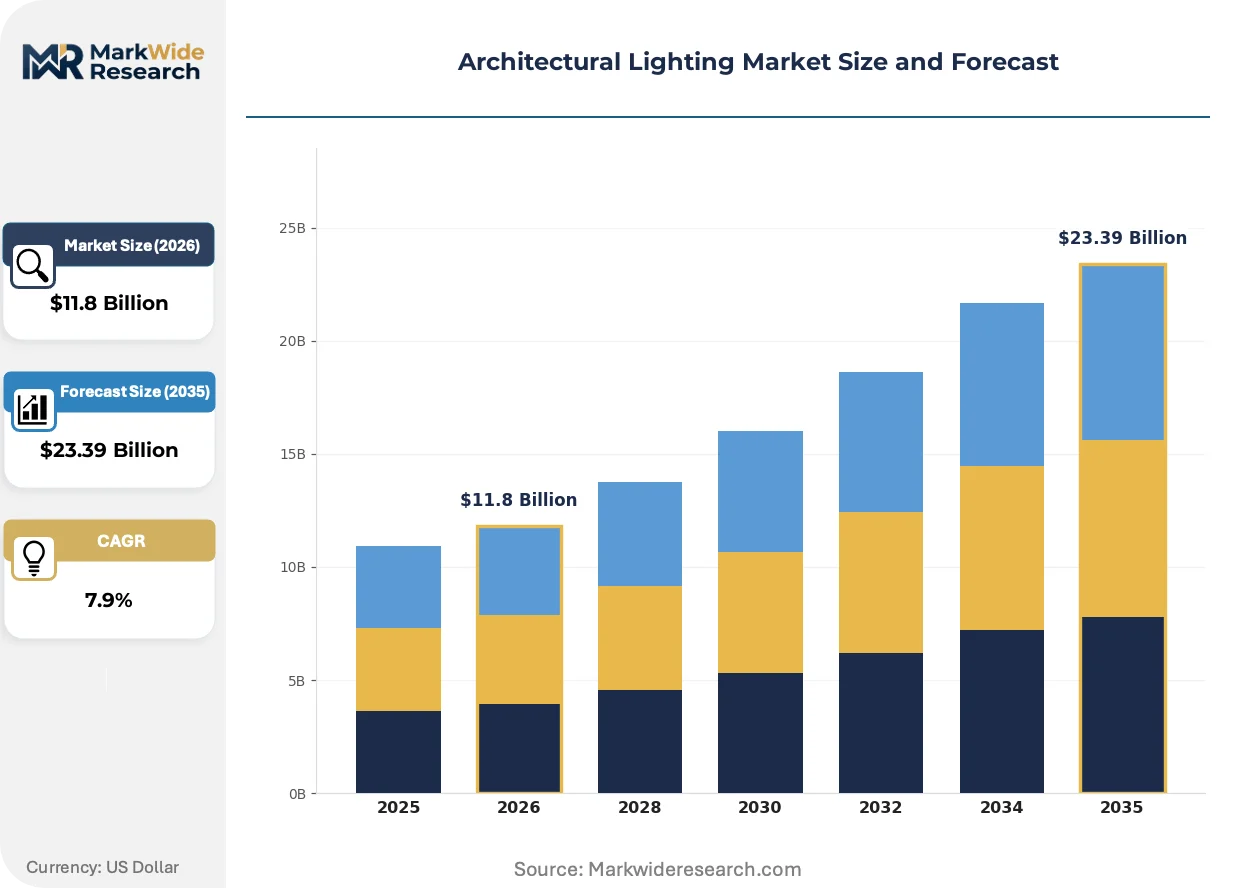
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $23.39 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Luminaires, Fluorescent Fixtures, Incandescent Bulbs, Halogen Lamps, OLED Panels Technology: Smart Lighting, Wireless Control, Dimming Systems, Sensor Integration, RGB Color Management Application: Commercial Complexes, Museums, Hospitality Venues, Religious Buildings, Public Spaces End User: Interior Designers, Facility Managers, Real Estate Developers, Lighting Contractors, Event Planners |
| Companies Covered | Cree Lighting, Hubbell Lighting, Signify (Philips Lighting), Artemide, Louis Poulsen, Acuity Brands, Fagerhult Group, WAC Lighting, Zumtobel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Lighting Market Strategic Shifts & Innovations
Human-centric lighting protocols and circadian rhythm optimization are actively reshaping specification priorities, as building owners recognize measurable productivity and wellness outcomes from tunable white systems.
Li-Fi data transmission through visible light modulation is displacing conventional wireless infrastructure in electromagnetic-sensitive environments. Healthcare facilities and defense installations across Switzerland and Germany are piloting gigabit-capable luminaires for secure, interference-free connectivity. This technology is displacing Wi-Fi dependency in zones where radio frequency restrictions or security protocols block conventional networks.
The EU AI Act imposes algorithmic transparency obligations on lighting networks that automate color temperature and intensity adjustments based on occupancy prediction. Manufacturers must document training data provenance and decision logic for luminaires deploying machine learning models. Premium specification channels in the Netherlands and Denmark are responding by demanding third-party audit trails as standard bid requirements.
Design-build procurement consolidation is compressing traditional agency-specifier influence. Large commercial developers in Germany now bundle lighting design with general contracting, marginalizing independent lighting designers who historically controlled premium fixture selection. This shift concentrates volume with manufacturers possessing direct contractor relationships and configurable product platforms.
Architectural Lighting Market Segmentation
Segmentation in architectural lighting reveals how margin pools concentrate around specification complexity and control system integration. Manufacturers align R&D investment and channel strategy to the procurement behaviors of distinct buyer archetypes across product, technology, application, and end-user dimensions.
Product Type:
Margin pools concentrate in premium LED luminaires where thermal management and optical engineering create defensible specification positions, while legacy technologies retreat to price-sensitive retrofit contexts.
- LED Luminaires:Solid-state emitters mounted on aluminum or ceramic substrates with active thermal management and precision optics command specification channels. Demand concentrates in German and Dutch commercial complexes where EU Ecodesign Directive thresholds disqualify legacy alternatives.
- Fluorescent Fixtures:Linear and compact tube assemblies with magnetic or electronic ballasts persist in budget-constrained municipal and educational retrofits. Southeast Asian hospitality developers specify these only where capital availability blocks LED upgrades.
- Incandescent Bulbs:Tungsten-filament sources with CRI 100 and instant dimming retain niche theatrical and heritage restoration applications.
- Halogen Lamps:Quartz-halogen capsules with precise beam control serve museum accent lighting where color stability matters.
- OLED Panels:Thin-film organic emitters on glass or flexible substrates enable ultra-thin surface-integrated luminaires for high-end residential and corporate interiors.
LED Luminaires holds installed capacity. OLED Panels is rotating up the share rankings.
Technology:
Technology segmentation tracks where control system integration creates recurring revenue streams and locks in specification relationships through proprietary protocols.
- Smart Lighting:Networked luminaires with embedded processors executing scene control, energy management, and predictive maintenance algorithms. Demand concentrates in Netherlands smart building developments where open automation protocol convergence reduces integration friction.
- Wireless Control:Bluetooth Mesh, Zigbee, or proprietary RF networks eliminating control wiring in retrofit contexts. German commercial landlords deploy these to avoid disruption in occupied buildings.
- Dimming Systems:Phase-cut, 0-10V, or DALI-compatible drivers enabling continuous lumen output adjustment.
- Sensor Integration:Occupancy, daylight, and temperature sensors embedded in luminaire housings for autonomous environmental response.
- RGB Color Management:Multi-channel LED engines with calibrated color mixing for dynamic architectural effects and media facades.
Smart Lighting captures the steepest expansion trajectory as building automation investments accelerate.
Application:
Application segmentation maps procurement authority concentration and specification cycle duration across built environment types.
- Hospitality Venues:Hotels, resorts, and restaurants requiring custom fixture development with extended design collaboration and designer-driven procurement. Vietnam and Indonesia resort developments generate disproportionate margin pools through first-mover specification channel establishment.
- Commercial Complexes:Office towers, retail centers, and mixed-use developments with standardized performance specifications and volume procurement. German design-build contractors now bundle lighting with general contracting, compressing traditional agency influence.
- Museums:Conservation-grade illumination with strict UV and IR emission controls for artifact protection.
- Religious Buildings:Historic preservation contexts balancing liturgical requirements with heritage authority constraints.
- Public Spaces:Municipal streets, parks, and transit facilities with lowest-bid procurement and extended maintenance obligations.
Commercial Complexes holds installed capacity. Hospitality Venues is rotating up the share rankings.
End User:
End-user segmentation distinguishes between specification influencers with design authority and procurement executors with budget control.
- Interior Designers:Independent or studio-based design professionals controlling fixture selection in premium residential, hospitality, and corporate projects. Dutch and Danish designers increasingly demand third-party algorithmic audit trails under EU AI Act compliance pressures.
- Real Estate Developers:Asset owners and development firms making portfolio-scale procurement decisions with lifecycle cost emphasis. German developers consolidating design-build contracts concentrate volume with manufacturers possessing direct contractor relationships.
- Facility Managers:Building operations professionals prioritizing maintenance accessibility and energy monitoring integration.
- Lighting Contractors:Electrical installation firms executing specification-driven projects or value-engineering alternatives.
- Event Planners:Temporary installation specialists renting or purchasing theatrical and decorative fixtures for limited-duration deployments.
Facility Managers holds installed capacity. Interior Designers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Dutch commercial buyers absorb specification-grade premiums under regulatory pressure, while Southeast Asian hospitality developers negotiate aggressively on fixture costs despite expanding project pipelines.
Germany
Design-build procurement consolidation concentrates volume with manufacturers possessing direct contractor relationships. The EU Ecodesign Directive enforces escalating minimum luminous efficacy thresholds that disqualify legacy technologies from new construction. Frankfurt and Munich commercial complexes drive specification-grade LED retrofits as landlords bundle lighting with general contracting.
Netherlands
Smart building developers generate disproportionate pull for open automation protocol convergence between lighting and HVAC systems. The EU AI Act imposes algorithmic transparency obligations on connected networks processing occupancy data. Amsterdam and Rotterdam developments increasingly demand third-party audit trails for machine-learning-enabled luminaires.
United States
North American specification channels concentrate around distributed brand architectures and agency-driven procurement processes. ENERGY STAR certification tightens minimum efficacy thresholds for federal and utility-backed retrofit financing. Commercial corridors in Texas and California sustain volume demand despite fragmented regulatory landscapes across state jurisdictions.
Vietnam
Resort and mixed-use developments expand custom specification cycles with limited established agency networks. The country's national construction regulator promotes green building codes that reference international efficacy benchmarks. Da Nang and Phu Quoc hospitality clusters create first-mover advantages for specification channel entrants.
Switzerland
Healthcare and defense installations pilot Li-Fi data transmission through visible light modulation for secure, interference-free connectivity. Swissmedic and federal cybersecurity frameworks impose strict data governance on connected infrastructure. Zurich and Geneva facilities displace Wi-Fi dependency in electromagnetic-sensitive zones.
Architectural Lighting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capability gaps collapsing as LED module costs commoditize. The upper tier defends position through captive chip production, proprietary IoT platforms, or silicon carbide substrate expertise. Mid-scale fixture assemblers compete on configurable product platforms and direct contractor relationships. Dominant competitive moves include backward integration into substrate manufacturing and strategic partnerships for building automation protocol convergence.
Among North American incumbents, Acuity Brands and Cree Lighting exemplify contrasting archetypes—one leveraging distributed channel architecture, the other silicon carbide expertise for thermal performance. Signify anchors the integrated leader tier through captive production and proprietary Interact platforms. European specialists including Zumtobel Group and Fagerhult Group occupy positions emphasizing specification relationships and premium hospitality channels.
| Leading Market Players |
|---|
| Cree Lighting |
| Hubbell Lighting |
| Signify (Philips Lighting) |
| Artemide |
| Louis Poulsen |
| Acuity Brands |
| Fagerhult Group |
| WAC Lighting |
| Zumtobel Group |
| Others |
Cost & Logistics Intelligence
Capacity utilization at East Asian LED substrate foundries shapes both supply concentration and price floors across specification tiers. German commercial buyers absorb premium markups under EU Ecodesign Directive pressure, while Southeast Asian hospitality developers negotiate aggressively despite expanding project pipelines.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value in specification-grade installations. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified luminaires from code-minimum retrofits and commodity replacements. Cost compression in the economy tier intensifies as Chinese module exports displace regional assembly margins. Municipal procurement teams exhibit highest price sensitivity, while Dutch interior designers prioritize algorithmic audit compliance over unit cost.
Supply Chain Analysis
China and Taiwan anchor LED chip and substrate fabrication, while Malaysia and Mexico concentrate fixture assembly and thermal management component production. Silicon carbide wafers, aluminum heat sinks, and precision optics draw from concentrated East Asian suppliers. Single-source vulnerability in silicon carbide substrate supply exposes high-lumen manufacturers to allocation constraints during capacity crunches. Distribution runs through specification agencies in developed markets and direct contractor relationships in design-build procurement contexts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around service-layer gaps as design-build procurement marginalizes traditional agency-specifier influence. Building automation protocol convergence creates niches for integration specialists capable of bridging lighting and HVAC control systems.
For Market Incumbents: Consolidate specification channel control through captive chip production and proprietary IoT platform deployment. Silicon carbide substrate expertise sustains performance leadership against emerging fixture assemblers exploiting commoditized LED modules. Direct contractor relationships in German design-build procurement defend volume positions against agency-network erosion.
For New Entrants and Emerging Players: Cybersecurity engineering services for connected luminaires represent an under-served layer where incumbents lack embedded security capacity. Vietnam and Indonesia hospitality developments offer first-mover specification channel establishment before agency networks mature. Target open automation protocol integration as the go-to-market angle, positioning as HVAC-lighting convergence specialists.
For Investors and Strategic Acquirers: Specialist firms with silicon carbide thermal management IP and established hospitality specification relationships offer durable margin positions. Long-term viability hinges on regulatory compliance capabilities as EU AI Act algorithmic transparency obligations expand. Watch for harmonization gaps between regional cybersecurity standards as the inflection indicator for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captive silicon carbide wafer supply insulates Signify and Cree Lighting from allocation volatility. |
| Proprietary IoT Platform Deployment | Signify's Interact ecosystem locks in recurring revenue through building automation protocol convergence. |
| Direct Contractor Relationship Building | Acuity Brands' agency-driven specification process concentrates North American commercial complex volume. |
| Third-Party Algorithmic Audit Capability | Dutch and Danish designers now demand documented training data provenance under EU AI Act compliance. |
| Li-Fi Data Transmission Pilot Expansion | Swiss healthcare and defense installations pilot gigabit-capable luminaires for electromagnetic-sensitive zones. |
Research Approach
Cross-validation between specification agency interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed lighting design principals, electrical contractor procurement leads, facility management directors, and smart building developers across Germany, the Netherlands, Vietnam, and Switzerland. Secondary validation drew from EU Ecodesign Directive implementation reports, ENERGY STAR certification databases, SEC 10-K disclosures from listed lighting manufacturers, and building automation protocol standardization documents. Bottom-up demand modeling triangulated against top-down construction spend allocation to ensure segmentation integrity.
Sensitivity analysis around LED module cost trajectories and regulatory phase-out timelines informs the projection framework. The analytical framework segments across product type, technology integration level, application vertical, and end-user procurement authority throughout the forecast period. CAGRs derive from installed base replacement cycles, new construction permit flows, and efficacy standard enforcement schedules. Human-centric lighting protocol adoption rates and circadian optimization specification penetration serve as industry-specific demand modifiers.
Material uncertainties — tariff exposure on Chinese substrate imports, GDPR enforcement variance across member states, and hospitality construction financing availability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization pace and open standard adoption velocity without claiming predictive certainty. Recalibration cycles align with material shifts in EU Ecodesign Directive thresholds and building decarbonization mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Tritium Light Source Market
Lighting
UAE Smart Lighting Market
Lighting
Lighting Market
Lighting
Global Lighting Control System Market
Lighting
Portable Lamps Market
Lighting
Directional Luminaire Market
Lighting
Hazardous Lighting Market
Lighting
UV Lamps Market
Lighting
Photography Light Box Market
Lighting
Global Stadium Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Industrial Lighting Market
Lighting
Dimmers Market
Lighting
Illuminating Signs Market
Lighting
High Bay Lighting Market
Lighting
North America Street Lighting Market