
 GCC Smart Lighting Market | 2026-2036
GCC Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Smart Lighting Market Intelligence
The split between premium intelligent systems and basic retrofit commodity units is realigning procurement patterns across GCC utilities. Signify N.V. leverages its Interact platform to anchor large-scale municipal deployments in Saudi Arabia. Schneider Electric competes through integrated building management architectures that merge lighting with HVAC and security stacks. Acuity Brands Inc. differentiates via advanced spectral tuning and circadian lighting portfolios targeting healthcare and hospitality verticals.
Smart lighting denotes networked luminaire systems incorporating sensors, wireless communication modules, and programmable drivers to enable remote control, energy optimization, and data collection. LED technology dominates installed base economics through lumen-per-watt efficiencies exceeding 150 lm/W and operational lifespans surpassing 50,000 hours. Commercial Lighting leads value capture due to payback-driven retrofit cycles in existing building stock, while Smart Street Lights represent the fastest expansion vector as Gulf municipalities bundle illumination with environmental sensing and traffic monitoring capabilities. IoT-Enabled platforms concentrate margin pools in software licensing and recurring platform fees rather than hardware shipment volumes.
Saudi Standards, Metrology and Quality Organization (SASO) efficiency mandates and UAE's Estidama Pearl rating system shape product certification requirements and specification thresholds for building-integrated systems. MOHAP and local civil defense authorities in the UAE enforce emergency lighting and fire safety interoperability standards that constrain vendor selection. Facility managers and municipal procurement officers must monitor evolving interoperability protocols and local content requirements as Gulf states deepen domestic manufacturing incentives.
Market Dynamics
Municipal procurement officers across Gulf Cooperation Council states are bundling illumination infrastructure with environmental sensing capabilities, compressing vendor selection criteria toward integrated platform providers rather than standalone luminaire manufacturers.
Growth Catalysts
- SASO efficiency mandates:Saudi Arabia's technical regulations for lighting products mandate minimum luminous efficacy thresholds that accelerate LED retrofit cycles in existing commercial building stock.
- Mesh networking protocols:Wireless communication standards enabling street-level device-to-device connectivity reduce backbone infrastructure costs for municipality-wide deployments.
- Healthcare vertical demand:Circadian lighting installations in hospital recovery wards and senior care facilities create specification pull for tunable spectral output systems.
Market Restraints
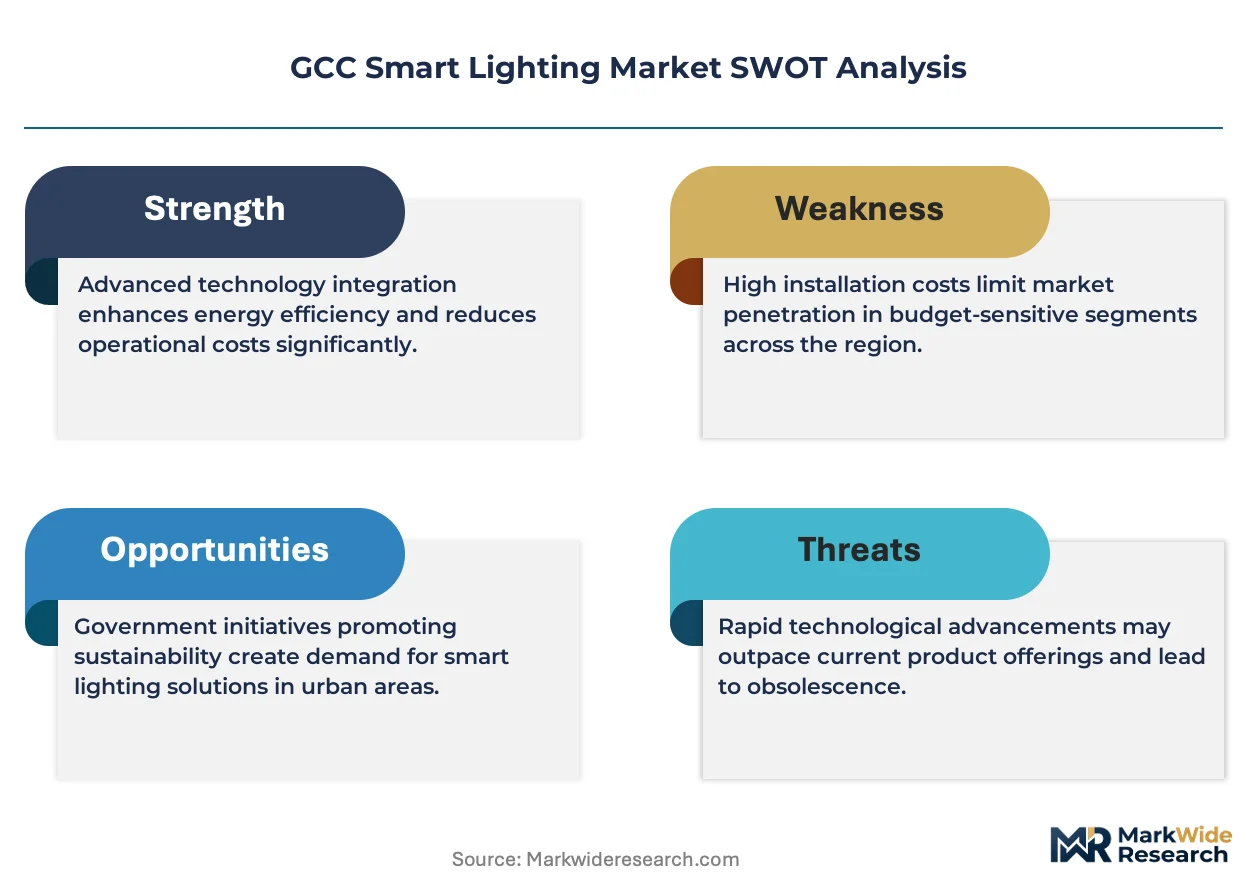
- Semiconductor input volatility:Programmable LED drivers depend on microcontroller unit supply chains concentrated in East Asian foundry capacity, exposing procurement timelines to allocation constraints.
- Technical interoperability gaps:Proprietary IoT platforms from competing vendors lack standardized application programming interfaces, forcing buyers into single-source dependencies.
- Skilled installation labor scarcity:Network commissioning and sensor calibration require technicians trained in both electrical systems and IT infrastructure, a combination scarce across Gulf labor markets.
Strategic Opportunities
- Qatar's stadium-to-city conversion:Post-event infrastructure from international sporting venues creates concentrated demand for smart district lighting with integrated crowd-flow analytics.
- Kuwait's Five-Year Development Plan:Government capital allocation toward new urban centers mandates connected utility infrastructure including intelligent street illumination networks.
- Li-Fi convergence:Visible light communication technology embedding data transmission within illumination beams opens adjacent revenue streams in bandwidth-constrained indoor environments.
Industry Challenges
- Legacy electrical infrastructure incompatibility:Existing streetlight feeder systems designed for high-pressure sodium ballasts require complete circuit redesign to support networked LED drivers and sensor power draw.
- Cybersecurity certification timelines:MOHAP and civil defense authorities in the UAE enforce data protection protocols for connected public infrastructure, extending product approval cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Smart Lighting Market |
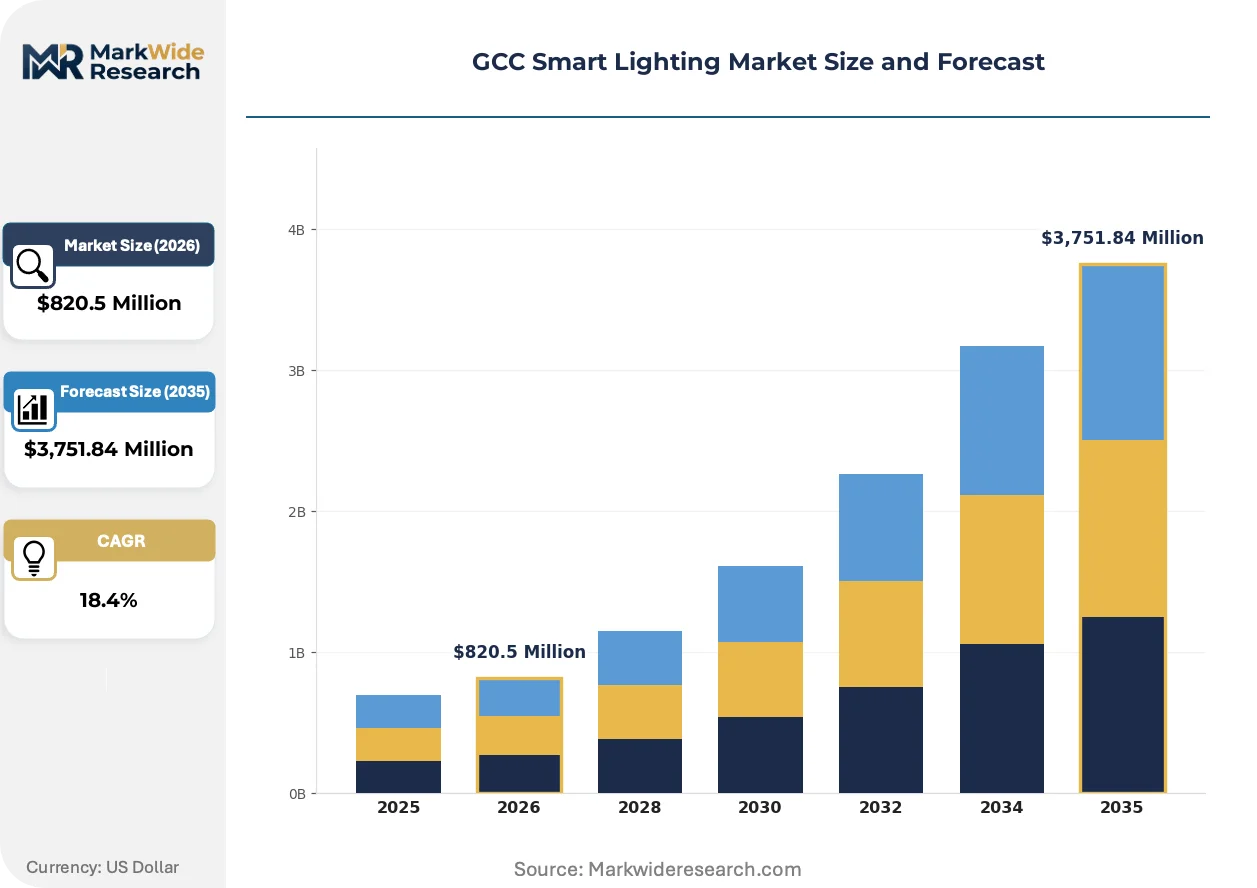
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,751.84 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Lighting, Commercial Lighting, Outdoor Lighting, Smart Street Lights Technology: LED, OLED, IoT-Enabled, Dimming Systems Application: Energy Management, Security, Environmental Monitoring, Home Automation End User: Municipalities, Retailers, Homeowners, Facility Managers |
| Companies Covered | Schneider Electric, Lutron Electronics Co. Inc., Signify N.V., Samsung Electronics, Eaton Corp., Acuity Brands Inc., Honeywell International Inc., Osram, Philips Lighting, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Smart Lighting Market Strategic Shifts & Innovations
Connected illumination systems are absorbing adjacent building automation functions, compressing the traditional separation between lighting controls and broader facility management platforms into unified software environments.
Edge computing architectures are modularizing luminaire design by embedding data processing capacity directly within street-level housing units. Saudi municipal operators now specify onboard analytics for traffic pattern recognition rather than cloud-dependent architectures. This distributed intelligence is modularizing vendor value propositions away from hardware shipment volumes toward software-defined feature licensing.
UAE's Estidama Pearl rating system now mandates daylight-responsive dimming and occupancy-based switching for new construction seeking higher sustainability tiers. The regulation forces specification of networked control systems in commercial building permits across Abu Dhabi and Dubai. Developers respond by pre-wiring tenant spaces for centralized lighting management during core-and-shell construction phases.
Facility management outsourcing contracts now unbundle lighting maintenance from comprehensive service agreements, creating direct procurement relationships between end-users and platform providers. Large retail operators in Bahrain and Oman negotiate separate agreements for illumination system uptime guarantees distinct from general building maintenance. This channel disintermediation concentrates in hospitality portfolios where brand standards require consistent color temperature across property networks.
GCC Smart Lighting Market Segmentation
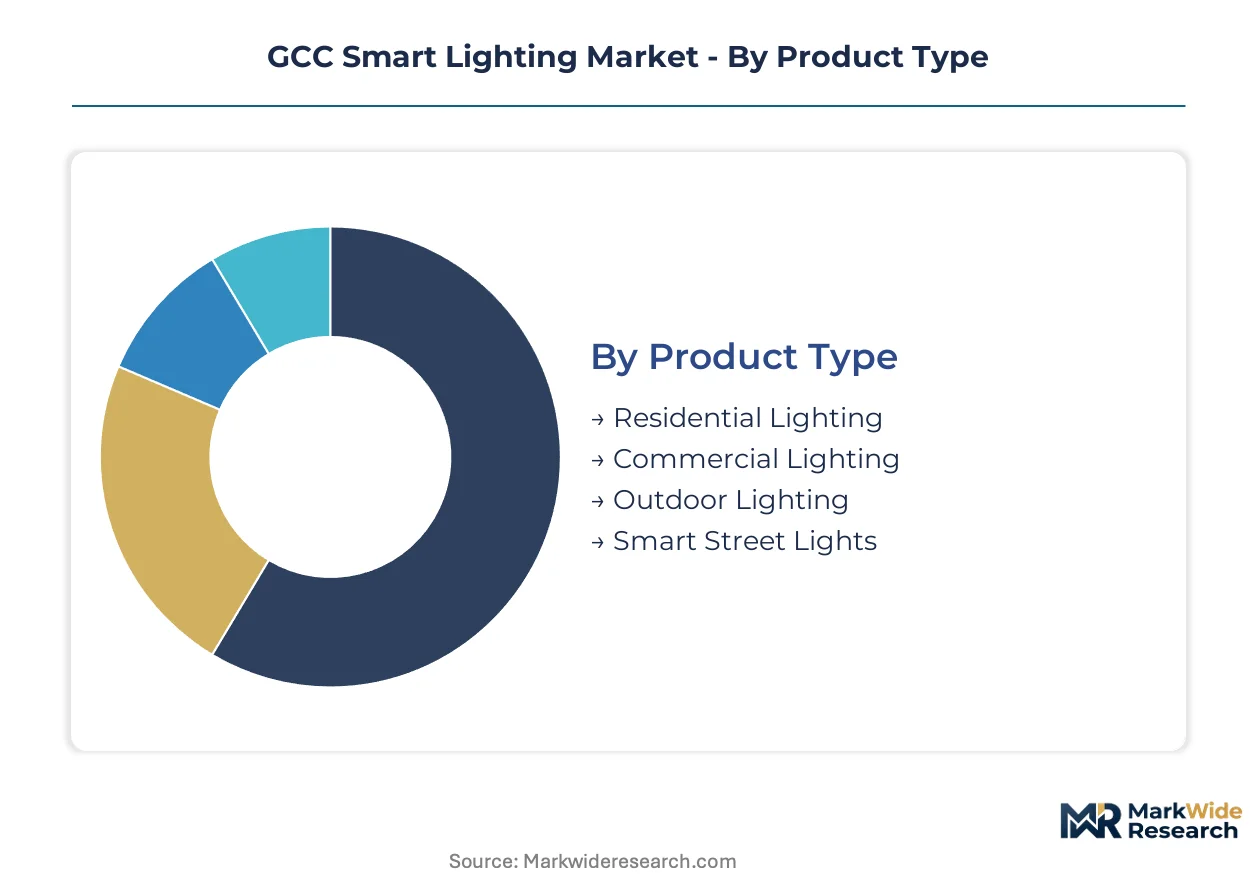
Procurement officers across Gulf utilities evaluate smart lighting investments through multiple overlapping lenses. Product specifications, connectivity protocols, and end-use requirements fragment vendor selection criteria into distinct purchasing workflows that reshape competitive positioning.
Product Type:
Cost tier determines specification thresholds and payback calculations for retrofit versus new-build decisions.
- Commercial Lighting:Networked luminaire systems for offices, hotels, and retail environments incorporate occupancy sensors and daylight harvesting controls. Demand concentrates in Dubai and Abu Dhabi where Estidama Pearl ratings mandate automated dimming for new construction permits.
- Smart Street Lights:Connected pole infrastructure bundles illumination with environmental sensors, traffic cameras, and public Wi-Fi access points. Saudi municipalities accelerate deployment as SASO efficiency regulations phase out high-pressure sodium inventory.
- Residential Lighting:Consumer-grade connected fixtures and bulb replacements with smartphone control interfaces.
- Outdoor Lighting:Weather-hardened luminaires for parking structures, campuses, and industrial perimeters without full municipal networking.
Commercial Lighting leads on scale; Smart Street Lights lead on momentum.
Technology:
Application requirements determine whether buyers prioritize lumen efficiency, spectral tunability, or data architecture integration.
- LED:Solid-state illumination exceeding 150 lm/W efficacy dominates installed base economics through operational lifespans surpassing 50,000 hours. Procurement across GCC commercial retrofits favors LED for payback periods under three years.
- IoT-Enabled:Wireless communication modules and programmable drivers enable remote commissioning, energy analytics, and predictive maintenance. UAE facility managers specify mesh networking protocols to reduce backbone infrastructure costs.
- OLED:Organic emissive panels for decorative and display applications with limited penetration in functional illumination.
- Dimming Systems:Analog and digital control gear for legacy fluorescent and HID retrofits without full connectivity.
LED commands volume share; IoT-Enabled platforms capture margin concentration.
Application:
Customer type dictates whether procurement emphasizes operational savings, regulatory compliance, or revenue generation.
- Energy Management:Automated load scheduling and demand response integration reduce electricity consumption and peak demand charges. Saudi commercial building operators deploy these systems to meet SASO efficiency mandates.
- Security:Motion-activated illumination and video analytics integration for perimeter protection and crowd monitoring. Qatar's stadium-to-city conversion drives specification for integrated security lighting.
- Environmental Monitoring:Air quality sensors, noise meters, and weather stations mounted on connected poles.
- Home Automation:Voice control and scene programming for residential convenience applications.
Energy Management leads on scale; Security leads on momentum.
End User:
Procurement authority and budget cycle timing fragment sales channels and contract structures.
- Municipalities:City and regional governments issue multi-year tenders for street and public space illumination with integrated sensing infrastructure. Kuwait's Five-Year Development Plan channels capital toward connected utility networks.
- Facility Managers:Building operations teams negotiate separate uptime guarantees for lighting systems distinct from general maintenance contracts. Large retail operators in Bahrain and Oman drive direct procurement relationships with platform providers.
- Retailers:Franchise and chain operators standardizing color temperature across property portfolios.
- Homeowners:Individual consumers purchasing through electrical distributors and home improvement channels.
Municipalities lead on scale; Facility Managers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lighting engineers and IoT integration specialists concentrate in Gulf commercial hubs, with Dubai and Riyadh anchoring the regional talent pool for connected infrastructure deployment.
United Arab Emirates
Dubai's smart city mandates and Abu Dhabi's Estidama Pearl rating system drive specification of networked control systems in commercial permits. MOHAP enforces data protection protocols for connected public infrastructure. The Dubai Silicon Oasis cluster hosts regional headquarters for platform providers targeting municipal retrofit contracts.
Saudi Arabia
SASO efficiency mandates accelerate LED retrofit cycles across existing commercial building stock while Riyadh and Jeddah municipalities bundle illumination with environmental sensing. The Saudi Standards, Metrology and Quality Organization phases out high-pressure sodium inventory through technical regulations. NEOM's northwest development zone pilots edge-computing street infrastructure with onboard traffic analytics.
Qatar
Post-World Cup stadium-to-city conversion creates concentrated demand for smart district lighting with integrated crowd-flow analytics. The country's civil defense authority enforces emergency lighting interoperability standards that constrain vendor selection. Lusail City operates as a testbed for connected pole infrastructure bundling illumination with air quality monitoring.
Kuwait
Government capital allocation under the Five-Year Development Plan mandates connected utility infrastructure including intelligent street illumination networks. The country's national standards body shapes certification requirements for building-integrated systems. The Al-Sabah Medical District drives specification for circadian lighting installations in hospital recovery wards.
Oman
Large retail operators negotiate direct procurement relationships with platform providers for uptime guarantees distinct from general building maintenance. The Ministry of Housing and Urban Planning issues efficiency guidelines for new commercial construction. Muscat's Knowledge Oasis cluster attracts facility management outsourcing contracts unbundling lighting maintenance from comprehensive service agreements.
GCC Smart Lighting Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the GCC smart lighting value chain, with integrated platform providers commanding municipal tenders while component specialists serve retrofit segments. The vendor base organizes into three tiers: multinational conglomerates with building automation portfolios, pure-play lighting technology firms, and regional system integrators. Consolidation pressure intensifies as procurement officers favor single-source dependencies for networked infrastructure. Dominant competitive moves include strategic partnerships between luminaire manufacturers and software platform developers, plus backward integration into semiconductor driver production.
Within the integrated platform tier, Signify N.V. and Schneider Electric exemplify archetypes competing for large-scale municipal deployments. Signify's Interact platform anchors connected street infrastructure specifications in Saudi Arabia, while Schneider Electric merges lighting controls with broader building management architectures. Acuity Brands Inc. occupies a position among spectral tuning specialists targeting healthcare and hospitality verticals with circadian lighting portfolios. These three firms represent divergent strategic postures: software-centric platform licensing, integrated building automation stacks, and vertical-specific spectral engineering.
| Leading Market Players |
|---|
| Schneider Electric |
| Lutron Electronics Co. Inc. |
| Signify N.V. |
| Samsung Electronics |
| Eaton Corp. |
| Acuity Brands Inc. |
| Honeywell International Inc. |
| Osram |
| Philips Lighting |
| Others |
Cost & Logistics Intelligence
Estidama Pearl rating mandates in Abu Dhabi gate qualified supply access and premium-tier pricing power for networked control systems, compressing vendor margins on non-compliant hardware while elevating software licensing fees for certified platform providers.
Pricing Analysis
The bundled-versus-unbundled service split defines procurement economics across GCC utilities. Facility management outsourcing contracts now separate lighting uptime guarantees from general maintenance agreements, concentrating direct platform relationships with end-users. Pricing stratifies across premium certified tiers, standard interoperable systems, and economy retrofit units based on SASO efficiency compliance and mesh networking protocol support. Municipal buyers in Saudi Arabia exhibit lowest price sensitivity due to multi-year tender structures, while small retail operators in Bahrain and Oman drive cost compression through competitive bidding for standalone luminaire replacements.
Supply Chain Analysis
Workforce availability constraints in East Asian semiconductor foundries and Chinese LED packaging facilities tighten programmable driver supply. Microcontroller units and wireless communication modules feed from concentrated Taiwan and South Korea manufacturing bases, while phosphor substrates and aluminum heat sinks source from Chinese industrial clusters. Single-source vulnerability in microcontroller allocation exposes procurement timelines to foundry capacity constraints. Distribution runs through regional system integrators in Dubai and Riyadh who manage commissioning and sensor calibration for municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC smart lighting market operates as a geographic-arbitrage play where Saudi Arabia's SASO efficiency mandates create accelerated retrofit demand against the UAE's more mature but saturated installed base, amplifying margin capture for vendors with cross-border certification capabilities.
For Market Incumbents: Anchor municipal platform positions through backward integration into semiconductor driver production, reducing exposure to East Asian foundry allocation constraints. Deepen software licensing concentration by embedding edge-computing analytics within luminaire housings, displacing cloud-dependent architectures that emerging platform competitors promote. Prioritize certification investment for MOHAP data protection protocols to extend approval cycle advantages over unqualified rivals. For New Entrants and Emerging Players: Capture white-space in Oman's facility management outsourcing segment where lighting maintenance unbundling creates direct procurement relationships absent entrenched platform providers. Target Kuwait's Five-Year Development Plan capital allocation for intelligent street illumination networks, leveraging the country's lagging deployment timeline relative to Saudi and UAE municipalities. Pursue go-to-market partnerships with regional system integrators in Muscat and Manama who control commissioning labor scarcity. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators because skilled installation labor scarcity across Gulf markets creates captive value in commissioning and sensor calibration capabilities. Platform providers with software-defined feature licensing models demonstrate superior long-term viability against hardware-shipment-dependent competitors. Watch for inflection in Li-Fi technology readiness levels as bandwidth-constrained indoor environments create adjacent revenue stream potential.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merges lighting controls with HVAC and security stacks per Schneider Electric's building automation architecture. |
| Edge Computing Deployment | Embeds traffic analytics within Saudi street-level luminaires, reducing cloud dependency for NEOM pilots. |
| Certification Investment | Accelerates MOHAP data protection approval timelines for UAE municipal tender participation. |
| Backward Integration | Captures programmable LED driver production to offset East Asian semiconductor allocation risks. |
| Vertical Market Specialization | Targets healthcare circadian lighting specifications in Kuwait's Al-Sabah Medical District recovery wards. |
Research Approach
Multiple input streams — municipal procurement officer interviews, facility manager surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged smart city program directors, electrical contractor executives, and platform provider sales leads across Dubai, Riyadh, and Doha. Secondary validation incorporated SASO technical regulations, UAE Estidama Pearl certification databases, and Kuwait Five-Year Development Plan capital allocation disclosures. Bottom-up luminaire shipment estimates and top-down infrastructure spending analysis were triangulated to cross-check volume figures.
Historical deployment trajectories in Saudi Arabia and the UAE were cross-referenced against panel input from municipal planning departments to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, connectivity protocol, application function, and end-user procurement authority dimensions. CAGRs were derived from fitted trend analysis rather than endpoint extrapolation, with specific weighting for IoT-enabled platform adoption curves and LED retrofit cycle timing.
Semiconductor supply allocation disruptions, regulatory interoperability standard delays, and municipal budget reallocation are the dominant revision risks to forecast outputs. Material deviation in any of these named triggers warrants strategic pause and segment-level re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Illuminating Signs Market
Lighting
Architectural Lighting Market
Lighting
Human Centric Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Intelligent Lighting Controls Market
Lighting
Gesture Control Light Market
Lighting
Cleanroom Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Art and Museum Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
North America Street Lighting Market
Lighting
Connected Lighting Platform Market
Lighting
Street Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Vintage Bulb Market
Lighting
LED Eye Protection Lamp Market