
 Solar Column Headlight Market | 2026-2036
Solar Column Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Column Headlight Market Insights
IP65-rated weatherproofing and lithium iron phosphate battery compatibility is collapsing the gap between premium solar column headlights and conventional grid-tied alternatives. Signify N.V. leverages its Lumec division's municipal relationships to sustain large-scale deployment contracts across European public infrastructure. Solar Electric Power Company (SEPCO) anchors its competitive stance through captive manufacturing of photovoltaic modules and LED arrays in Florida. Greenshine New Energy differentiates via all-in-one fixture designs that reduce installation labor for California transit authorities.
A solar column headlight integrates a photovoltaic panel, charge controller, rechargeable battery cell, and LED luminaire into a self-contained pole-mounted unit, typically delivering 3,000 to 12,000 lumens with autonomous operation across 3-5 sunless days. Street light configurations dominate municipal procurement volumes, while decorative light variants command higher margin pools in hospitality and retail campus applications. Battery storage technology segments are gaining structural importance as nickel-metal hydride and lithium-ion chemistries displace lead-acid systems in cold-climate installations.
FCC Part 15 emissions compliance governs integrated wireless control modules in US-sold units, while CE marking under the EU's Ecodesign Directive mandates minimum luminous efficacy thresholds for public roadway equipment. India's BIS certification requirements for solar photovoltaic products create market access barriers for unqualified import suppliers. Stakeholders must monitor evolving battery recycling regulations under REACH and emerging state-level extended producer responsibility frameworks before committing to multi-year manufacturing footprints.
Market Dynamics
Municipal infrastructure procurement is pivoting from grid-tied systems toward autonomous photovoltaic-powered street lighting, driven by energy-efficiency mandates and distributed energy resilience planning.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Public lighting efficiency targets are accelerating municipal adoption of off-grid solar solutions across European urban centers.
- India's smart city initiatives:State-level urban development authorities are prioritizing solar column installations for roadway and park illumination in tier-1 and tier-2 cities.
- Lithium iron phosphate battery chemistry:Superior cold-weather performance and cycle life are collapsing reliability gaps versus conventional grid-tied alternatives.
Market Restraints
- Photovoltaic module supply concentration:Dependence on concentrated Asian manufacturing creates input cost volatility and logistics vulnerability for system integrators.
- Lead-acid battery displacement friction:Legacy installed base and established recycling infrastructure slow conversion to advanced lithium chemistries in price-sensitive procurement segments.
- BIS certification barriers:India's mandatory solar photovoltaic product standards create market access hurdles for unqualified import suppliers.
Strategic Opportunities
- Underpenetrated hospitality and retail campus segments:Decorative light variants command premium margin pools compared to standardized municipal street configurations.
- Integrated wireless control modules:FCC Part 15-compliant smart lighting management is opening remote monitoring and adaptive dimming revenue streams.
- Extended producer responsibility frameworks:Emerging state-level battery recycling mandates are creating first-mover advantages for manufacturers with closed-loop supply chain capabilities.
Industry Challenges
- Embedded systems firmware integration:Municipal IT departments lack specialized expertise to configure charge controllers with legacy urban management platforms.
- IP65 weatherproofing certification timelines:Third-party testing bottlenecks delay product launches for seasonal procurement windows.
- Multiyear manufacturing footprint commitments:REACH battery recycling regulation evolution creates compliance uncertainty for capital-intensive production investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Column Headlight Market |
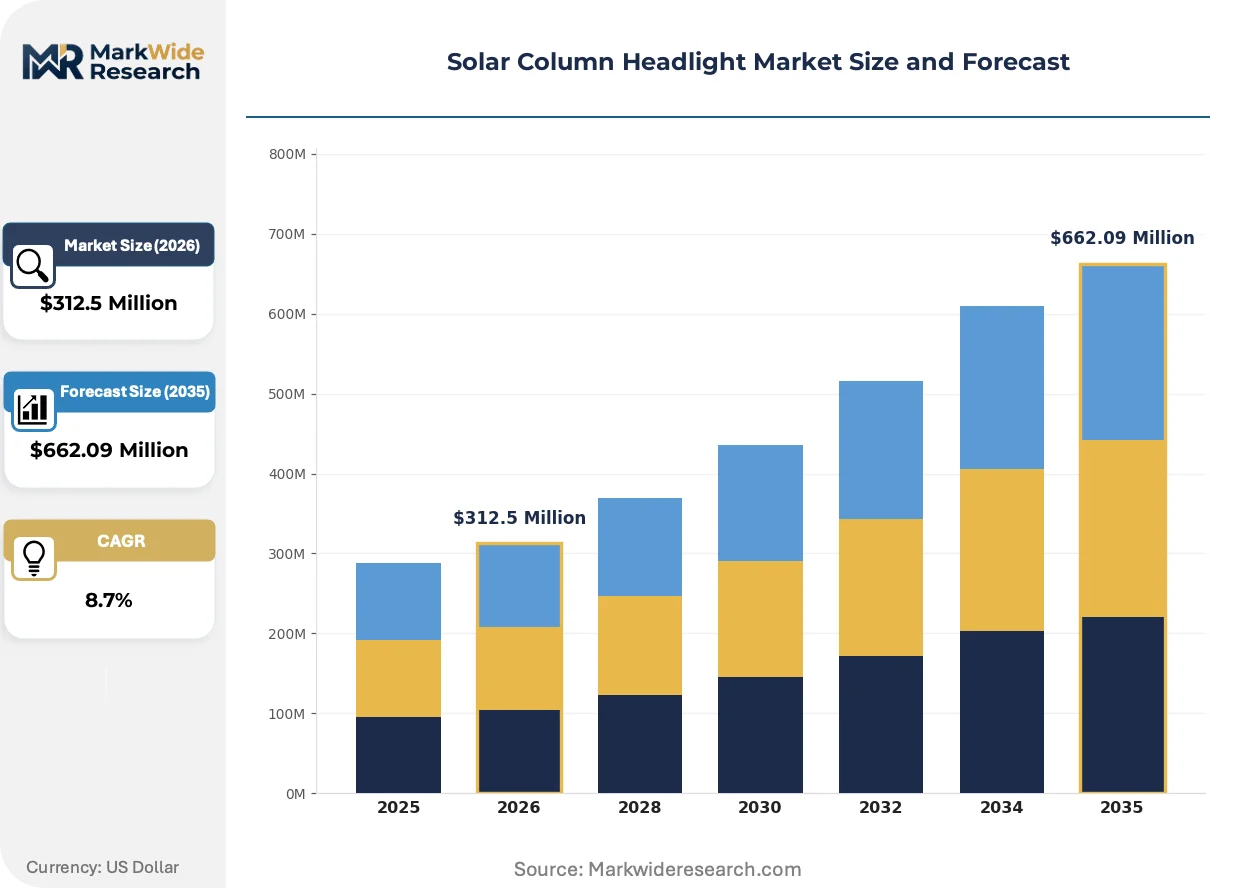
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Garden Lights, Decorative Lights, Flood Lights Technology: LED, Photovoltaic, Solar Panel, Battery Storage End User: Municipalities, Commercial Properties, Residential Areas, Parks Installation: Permanent, Temporary, Ground Mount, Pole Mount |
| Companies Covered | Signify N.V., Solar Electric Power Company (SEPCO), Greenshine New Energy, Solar Street Lights USA, Fonroche Lighting, Sunna Design, Sol Inc., Hubbell Incorporated, Bridgelux, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Column Headlight Market Trends and Innovations
Photovoltaic street lighting is undergoing rapid technological consolidation as battery chemistry advances and smart control architectures reshape product specifications and buyer expectations.
Monocrystalline silicon photovoltaic panels with integrated micro-inverters are supplanting polycrystalline alternatives in premium municipal tenders. German and Dutch city authorities specify these configurations for 25-year operational lifecycles. The technology is compressing total cost-of-ownership gaps versus grid-tied sodium vapor systems.
REACH regulations governing battery substance restrictions and recycling obligations are tightening supply chain compliance requirements for European market access. Manufacturers must document full material provenance and end-of-life recovery pathways. Cold-climate installations face the steepest adaptation costs due to thermal management chemistry constraints.
Municipal procurement departments are consolidating vendor relationships around turnkey installation and maintenance contracts. California transit authorities now bundle fixture supply with 10-year performance guarantees. This bundling is displacing component-only purchasing through electrical distributors.
Solar Column Headlight Market Segmentation
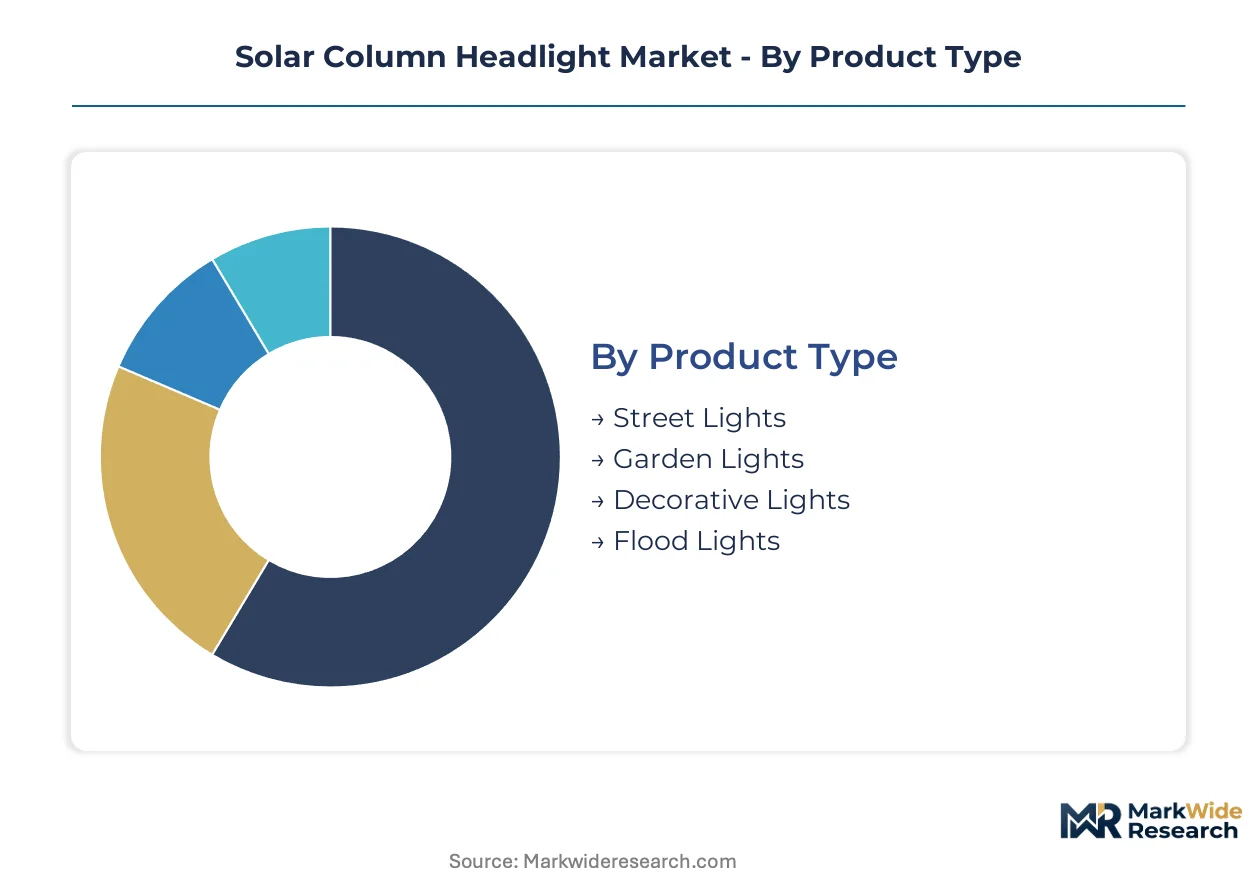
Solar column headlight procurement patterns diverge sharply across application contexts, with municipal infrastructure demanding ruggedized 25-year lifecycles while hospitality and retail campuses prioritize aesthetic integration. Technology choices cascade through battery chemistry, photovoltaic cell architecture, and control system specifications that lock buyers into multi-year vendor relationships.
Product Type:
Street lights dominate export flows to infrastructure-heavy markets, while decorative variants concentrate in domestic hospitality and retail campus procurement.
- Street Lights:Engineered for 3,000-12,000 lumen output with autonomous 3-5 day operation, these systems incorporate monocrystalline silicon panels and lithium iron phosphate battery banks. Municipal procurement in German and Dutch urban centers specifies these configurations for roadway and arterial illumination under EU Green Deal efficiency mandates.
- Decorative Lights:Lower lumen packages with ornamental housing designs command premium pricing in hotel, resort, and retail campus applications. California and Florida hospitality developments specify these variants for pathway and plaza illumination where visual integration supersedes raw output metrics.
- Garden Lights:Compact pole-mounted units with 1,000-3,000 lumen output serve residential subdivision and park pathway applications.
- Flood Lights:High-output directional fixtures for parking facility and perimeter security lighting with motion-sensing activation capability.
Street lights command the established base. The steepest expansion runs through decorative lights.
Technology:
Cost tier stratification separates premium integrated systems from component-level procurement, with battery chemistry representing the primary margin determinant.
- LED:Solid-state luminaires delivering 130-150 lumens per watt with 50,000-hour rated lifespans now constitute the universal baseline across all product categories. Municipal specifications in India require minimum luminous efficacy thresholds under BIS certification protocols.
- Battery Storage:Lithium iron phosphate chemistry displaces legacy lead-acid systems in cold-climate installations from Minnesota to Scandinavia, with superior cycle life and thermal stability justifying 40-60% cost premiums in procurement evaluations.
- Photovoltaic:Monocrystalline silicon panels with integrated micro-inverters compress total cost-of-ownership gaps versus polycrystalline alternatives in premium tenders.
- Solar Panel:Discrete photovoltaic modules for retrofit integration with existing pole infrastructure in budget-constrained municipal programs.
LED penetration is now universal across tiers. Battery storage chemistry represents the fastest-moving specification battleground.
End User:
Customer type determines financing structure, with municipalities leveraging municipal bonds and commercial properties deploying accelerated depreciation schedules.
- Municipalities:City and county infrastructure departments procure through formal tender processes with 10-25 year performance guarantees, bundling installation with maintenance contracts. California transit authorities now require turnkey vendor relationships displacing component-only distribution channels.
- Commercial Properties:Corporate campuses, logistics facilities, and retail developments specify solar column systems for parking and perimeter illumination to meet corporate sustainability targets and hedge against grid reliability risks.
- Parks:State and regional park authorities prioritize off-grid solutions for remote trail and campground illumination where grid extension proves economically unviable.
- Residential Areas:Homeowner associations and subdivision developers deploy garden light variants for streetscape and common area lighting with minimal ongoing maintenance requirements.
Municipalities anchor procurement volume. Commercial properties are gaining share fastest as ESG disclosure requirements harden.
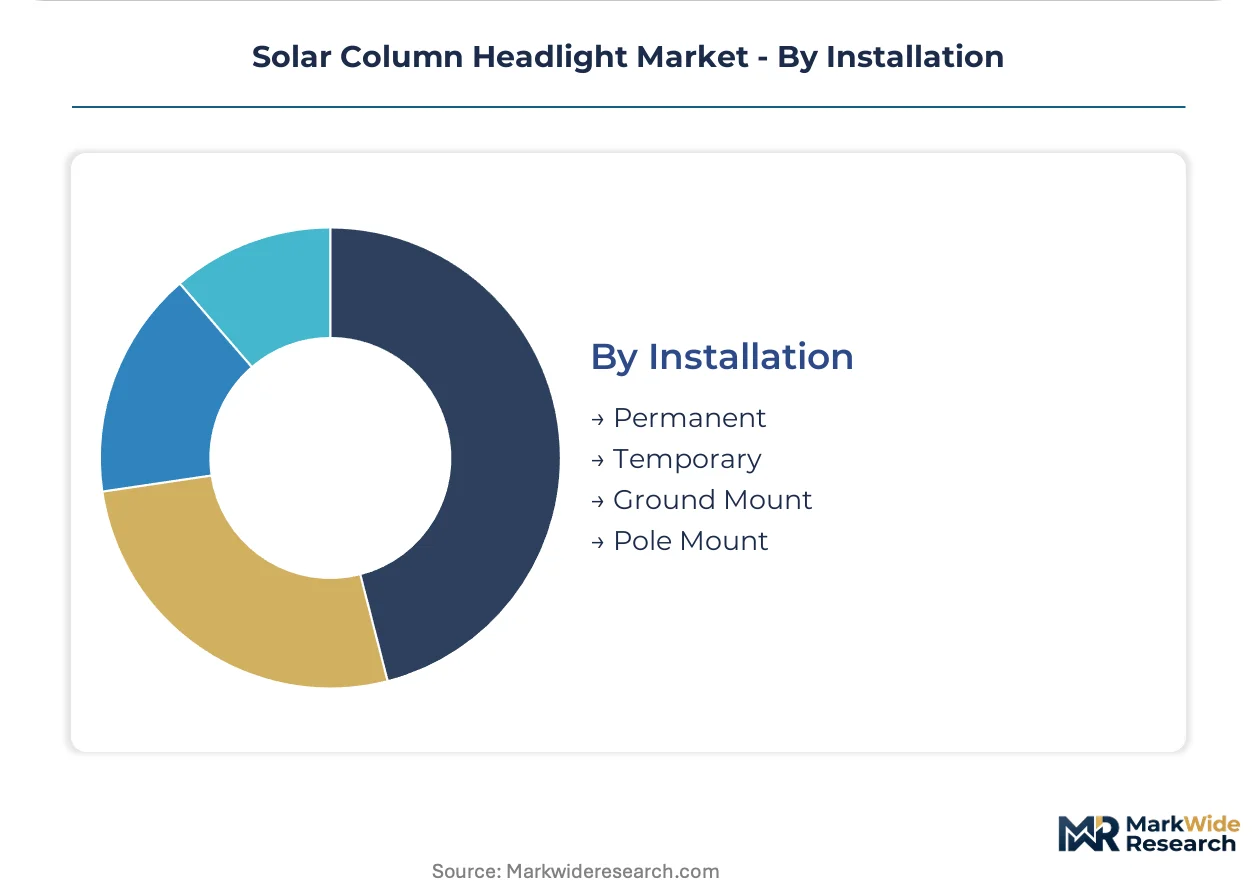
Installation:
Mounting configuration directly correlates with labor cost structure and seasonal deployment windows, with pole mount dominating in established urban corridors.
- Pole Mount:Standardized tenon or slip-fit mounting interfaces compatible with existing street lighting infrastructure, minimizing civil works and accelerating deployment timelines for municipal retrofit programs.
- Permanent:Concrete foundation installations with embedded conduit and anchor bolts for 25-year design life in highway and arterial roadway applications.
- Ground Mount:Low-profile fixtures for pathway, plaza, and landscape illumination with below-grade junction boxes and surface-mounted luminaire housings.
- Temporary:Portable skid or trailer-mounted systems for construction sites, event venues, and emergency response scenarios with rapid deployment and retrieval capability.
Pole mount configurations dominate retrofit demand. Permanent foundations anchor new infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts, with municipal infrastructure buyers in emerging economies demanding lowest-first-cost solutions while European public authorities prioritize lifecycle economics and regulatory compliance.
United States
California transit authorities and Florida municipal agencies drive procurement volume through bundled installation-maintenance contracts with decade-long performance guarantees. FCC Part 15 emissions compliance governs integrated wireless control modules for smart city deployments. The Southeast corridor from Miami to Atlanta concentrates hospitality campus installations where decorative variants command premium positioning.
Germany
Dutch and German city authorities specify monocrystalline silicon configurations with 25-year operational lifecycles under EU Green Deal efficiency mandates. REACH battery substance restrictions tighten supply chain documentation requirements for European market access. The Ruhr industrial cluster and Bavarian urban centers anchor large-scale arterial roadway retrofit programs displacing sodium vapor infrastructure.
India
State-level urban development authorities in Maharashtra and Karnataka prioritize solar column installations for smart city roadway and park illumination. BIS certification requirements for solar photovoltaic products create market access barriers for unqualified import suppliers. Tier-1 and tier-2 municipal corporations in Gujarat and Telangana consolidate procurement through formal tender processes with localized manufacturing preferences.
Netherlands
Dutch municipal engineering departments specify premium integrated systems with lithium iron phosphate battery banks for cold-climate reliability. CE marking under the EU's Ecodesign Directive mandates minimum luminous efficacy thresholds for public roadway equipment. The Randstad conurbation anchors procurement concentration for cycling pathway and canal bridge illumination where off-grid resilience proves critical.
France
French regional park authorities and hospitality developers in Provence-Alpes-Côte d'Azur deploy decorative variants for pathway and plaza illumination. ANSM and CNIL regulatory frameworks intersect with CE marking for public infrastructure cybersecurity in connected lighting deployments. The Île-de-France region concentrates municipal retrofit demand as Paris metropolitan authorities phase out legacy grid-tied street lighting.
Solar Column Headlight Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated system specialists commanding premium positioning against component assemblers competing on procurement price. The vendor base stratifies across three tiers: multinational lighting conglomerates with municipal relationship networks, captive manufacturers controlling photovoltaic and LED module supply, and regional installers bundling procurement with maintenance services. Dominant competitive moves center on turnkey contract bundling and backward integration into battery cell supply chains.
Among Netherlands-based conglomerates, Signify N.V. occupies a position exemplifying the municipal-relationship archetype through its Lumec division's European public infrastructure presence. Solar Electric Power Company represents the captive-manufacturing model with Florida-based photovoltaic module and LED array production. Greenshine New Energy anchors the design-integration specialist tier with all-in-one fixture configurations reducing installation labor for California transit authorities.
| Leading Market Players |
|---|
| Signify N.V. |
| Solar Electric Power Company (SEPCO) |
| Greenshine New Energy |
| Solar Street Lights USA |
| Fonroche Lighting |
| Sunna Design |
| Sol Inc. |
| Hubbell Incorporated |
| Bridgelux, Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal efficiency mandates and REACH battery substance restrictions simultaneously gate supplier qualification and stratify price tiers across the solar column headlight market. Municipal buyers in Germany and the Netherlands pay premiums for documented compliance, while price-sensitive procurement in India and Southeast Asia prioritizes lowest-first-cost configurations that sacrifice lifecycle guarantees.
Pricing Analysis
Turnkey installation and maintenance contracts extending across 10-25 year performance guarantees capture the dominant share of lifetime value in municipal procurement. Three-tier pricing structure across premium, standard, and economy levels separates monocrystalline lithium iron phosphate systems from polycrystalline lead-acid alternatives. Cost compression in economy tiers is intensifying because photovoltaic module oversupply from concentrated Asian manufacturing feeds price competition. Municipal infrastructure departments in emerging economies exhibit the highest price sensitivity, while Dutch and German city authorities prioritize total cost-of-ownership metrics over upfront capital expenditure.
Supply Chain Analysis
Port congestion on transpacific trade lanes and container availability constraints on Asia-Europe routes elevate inbound logistics costs for European and North American system integrators. Photovoltaic cell manufacturing concentrates in China, Vietnam, and Malaysia, while lithium iron phosphate battery cell production clusters in China and South Korea. Polysilicon wafers, LED driver electronics, and aluminum extrusion housings constitute critical component dependencies. Single-source vulnerability in photovoltaic module supply creates structural risk for procurement timelines. Distribution runs through electrical distributors for component-only sales and direct vendor relationships for bundled turnkey contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar column headlight market represents a high-growth infrastructure disruption as lithium iron phosphate battery chemistry collapses reliability gaps versus grid-tied alternatives. EU Green Deal mandates and India's smart city initiatives create synchronized regulatory tailwinds across multiple procurement jurisdictions.
For Market Incumbents: Fortify captive manufacturing positions in photovoltaic modules and LED arrays to defend against price erosion from component assemblers. Signify N.V.'s Lumec division demonstrates the defensive value of entrenched municipal relationships in European public infrastructure. Capacity addition in India and Southeast Asia addresses the threat of BIS certification barriers and localized manufacturing preferences in high-growth procurement markets. For New Entrants and Emerging Players: Firmware integration services for municipal IT departments represent a critical service-layer gap where incumbents under-serve buyers lacking specialized charge controller configuration expertise. Hospitality and retail campus decorative lighting in California and Florida offers the most penetrable white-space segment with premium margin pools. A go-to-market angle bundling aesthetic customization with accelerated installation timelines displaces standardized municipal street configurations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery storage sub-segments as lithium iron phosphate chemistry achieves manufacturing scale. The 5-10 year viability window favors acquisition targets with closed-loop battery recycling capabilities and REACH compliance documentation. Battery recycling regulation evolution under emerging state-level extended producer responsibility frameworks serves as the critical inflection indicator for manufacturing footprint investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium iron phosphate production secures margin control against raw material volatility from Chinese suppliers. |
| Turnkey Installation-Maintenance Bundling | California transit authorities now mandate decade-long performance guarantees displacing component-only distribution channels. |
| Smart Control Module Certification | FCC Part 15 compliance unlocks remote monitoring revenue streams in US municipal smart city deployments. |
| Decorative Variant Design Specialization | Premium positioning in Florida and California hospitality campuses commands margin multiples above standardized street configurations. |
| Closed-Loop Battery Recycling Infrastructure | REACH documentation and emerging state-level extended producer responsibility mandates create first-mover qualification advantages. |
Research Methodology
Initial hypotheses were tested against primary input from municipal procurement officers, solar system integrators, battery technology specialists, and electrical distribution channel managers and refined through secondary validation. Municipal tender databases, customs trade records for photovoltaic module flows, BIS certification registries, and EU Ecodesign Directive compliance filings constituted core secondary sources. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts anchored the market estimation framework.
Variance decomposition across product type, battery chemistry, installation configuration, and end-user financing structure informed the analytical framework over the projection horizon. CAGRs were derived from modeled unit shipments and average selling price trajectories. Photovoltaic panel efficiency curves, battery cycle life degradation rates, and municipal procurement cycle timing served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation, BIS certification protocols, and REACH substance restrictions; material policy shifts would require re-modeling. Battery recycling mandate acceleration, photovoltaic trade policy disruption, or lithium supply constraint emergence constitute specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Cleanroom Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Lighting Market
Lighting
Lighting Product Market
Lighting
US Indoor LED Lighting Market
Lighting
High-End Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Intelligent Lighting Controls Market
Lighting
Lighting Control Components Market
Lighting
LED Eye Protection Lamp Market
Lighting
Dimmer and Color Tunable Market
Lighting
Lamps and Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Bulb Market
Lighting
Directional Luminaire Market
Lighting
South America Outdoor LED Lighting Market