
 Miniature Bulbs Market | 2026-2036
Miniature Bulbs Market Size, Share, and Industry Trends Forecast 2026-2036
Miniature Bulbs Market Analytics
Buyer concentration in automotive interior lighting is rebalancing as tier-1 suppliers consolidate vendor lists and demand standardized LED modules across vehicle platforms. Osram GmbH leverages its vertical integration in chip-on-board LED architectures to secure long-term supply agreements with European automakers. Panasonic Corporation anchors its position through captive manufacturing of ceramic substrate bases for high-temperature miniature applications. Norman Lamps competes on rapid custom filament geometries for aftermarket instrument clusters.
Miniature bulbs are compact light sources typically measuring under 20 millimeters in diameter, engineered from tungsten filaments, xenon gas envelopes, or solid-state semiconductor junctions to deliver directional illumination in space-constrained environments. Their primary purpose spans vehicle dashboard indicators, medical endoscopy equipment, and aircraft cockpit displays where thermal management and shock resistance are critical. LED miniature formats now dominate value creation as automotive electrification mandates low-draw interior lighting, while halogen festoon variants retain margin pools in medical instrumentation requiring precise color rendering. Incandescent T10 and T5 form factors face structural decline in OEM channels but sustain aftermarket replacement demand across aging vehicle fleets and industrial control panels.
EPA energy conservation standards and NHTSA vehicle safety lighting regulations in the United States shape product qualification pathways, while REACH substance restrictions and CE marking requirements in Europe filter market access for non-compliant suppliers. The EU Green Deal's embedded carbon reporting through CSRD extends compliance burdens upstream to component manufacturers. Stakeholders must monitor divergence between EPA efficiency tiers and EU Ecodesign requirements when configuring dual-market product portfolios.
Market Dynamics
Automotive electrification is compressing the traditional miniature bulb supply chain as OEMs mandate chip-on-board LED modules for dashboard and interior lighting, forcing filament-based suppliers to pivot or exit.
Growth Catalysts
- EU Green Deal CSRD mandates:Embedded carbon reporting requirements are accelerating mercury-free LED adoption across European automotive clusters, creating compliance-driven replacement cycles for instrument panel illumination.
- Medical endoscopy equipment:Precision color rendering requirements in surgical visualization systems are sustaining premium demand for xenon gas envelope formats despite solid-state encroachment in adjacent segments.
- Germany's automotive lighting cluster:Concentrated R&D investment around Munich and Stuttgart is generating technology spillover effects that standardize LED module specifications across tier-1 supplier networks.
Market Restraints
- Tungsten filament input volatility:Raw material price swings and concentrated mining operations in Central Asia create margin compression for incandescent format manufacturers serving aftermarket replacement demand.
- REACH substance restrictions:European chemical compliance costs disproportionately burden small-format halogen producers, filtering market access for non-vertically integrated suppliers lacking in-house regulatory affairs capabilities.
- Solid-state substitution threat:Semiconductor junction architectures are displacing thermal filament technologies in vehicle interior applications where low-draw power budgets are non-negotiable design constraints.
Strategic Opportunities
- Aircraft cockpit display retrofits:Shock-resistant miniature formats for avionics backlighting represent an underpenetrated niche where thermal management specifications exceed consumer-grade LED capabilities.
- India PLI scheme for automotive components:Production-linked incentives for domestic manufacturing are attracting module assembly investment to serve emerging electric vehicle platforms in the subcontinent.
- Dual carbon goals in China:National energy efficiency mandates are creating regulatory tailwinds for low-power illumination in industrial control panels across manufacturing hub provinces.
Industry Challenges
- Chip-on-board packaging expertise gap:Shortage of thermal engineers capable of integrating semiconductor junctions with ceramic substrate bases is constraining capacity expansion at mid-tier suppliers.
- NHTSA vehicle safety certification timelines:Extended qualification pathways for dashboard indicator lighting are delaying product launches and tying up working capital in pre-revenue development phases.
- Legacy industrial control panel integration:Retrofitting solid-state modules into aging T10 and T5 socket configurations requires custom form factor engineering that fragments production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniature Bulbs Market |
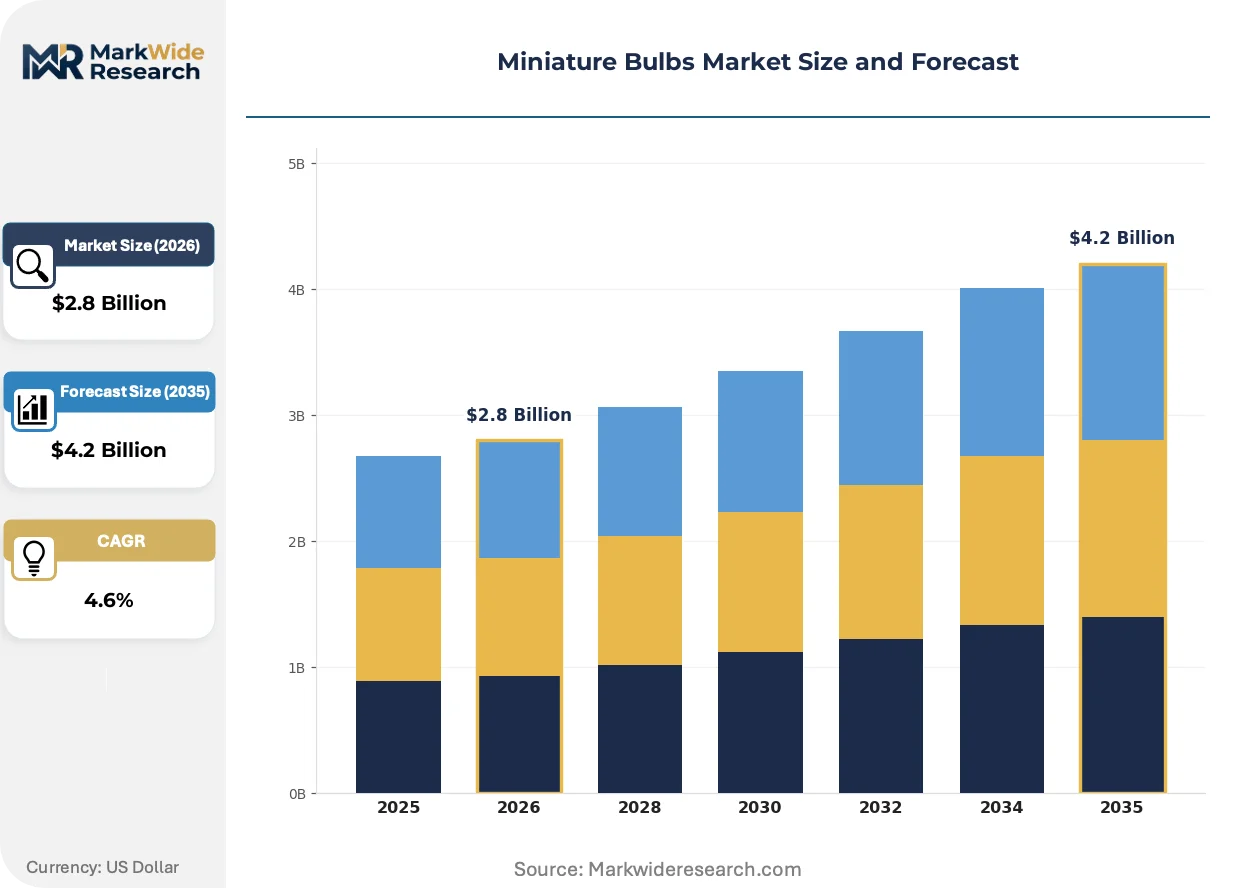
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incandescent, LED, Halogen, Xenon Application: Automotive Lighting, Decorative Lighting, Flashlights, Instrumentation Form Factor: T5, T10, Festoon, MR16 Power Rating: 1W, 5W, 10W, 20W |
| Companies Covered | Norman Lamps, Grainger, Sunray Lighting, GE Lighting, Philips Lighting (Signify), Osram GmbH, Panasonic Corporation, Lutron Electronics, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniature Bulbs Market Evolving Landscape
Technology convergence between semiconductor packaging and thermal substrate engineering is redefining competitive advantage in space-constrained illumination, while regulatory carbon accounting extends compliance burdens upstream.
Chip-on-board LED architectures are unifying thermal management and optical performance in a single package format. Tier-1 automotive suppliers are adopting these modules at accelerated pace for next-generation vehicle platforms. This unification is compressing the supplier base by eliminating discrete component sourcing for heat sink and emitter functions.
REACH and RoHS substance restrictions in Europe are forcing reformulation of gas envelope chemistries and filament alloys. Manufacturers serving EU automotive OEMs must certify mercury-free alternatives and document supply chain provenance. Medical instrumentation producers face the steepest compliance costs due to stringent color stability requirements under the EU MDR framework.
Automotive OEMs are consolidating vendor lists and demanding standardized LED modules across vehicle platforms. Long-term supply agreements are replacing spot procurement for interior lighting components. This concentration is most visible in Germany, where Munich and Stuttgart-based manufacturers are reducing qualified supplier counts by half to simplify quality assurance overhead.
Miniature Bulbs Market Segmentation
Miniature bulb configurations diverge sharply across certification requirements, with automotive interior applications demanding NHTSA safety validation and medical instrumentation requiring FDA device clearance. These regulatory fault lines create distinct margin pools and supplier qualification barriers that reshape competitive positioning within each segment category.
Product Type:
LED formats carry the heaviest REACH and RoHS compliance burdens for mercury-free certification, while incandescent and halogen variants face divergent EPA energy conservation standards depending on end-use classification.
- LED:Solid-state semiconductor junctions deliver directional illumination with thermal management integrated through chip-on-board architectures. Automotive OEMs in Germany's Munich-Stuttgart corridor are consolidating vendor lists around standardized LED modules for dashboard applications, driven by EU Green Deal CSRD mandates for embedded carbon reporting.
- Incandescent:Tungsten filament constructions maintain aftermarket demand for aging vehicle fleet instrument clusters and industrial control panels. REACH substance restrictions disproportionately burden small-format producers lacking in-house regulatory affairs capabilities, filtering market access for non-vertically integrated suppliers.
- Halogen:Gas envelope formats retain premium positioning in medical instrumentation requiring precise color rendering under FDA and EU MDR frameworks.
- Xenon:High-intensity discharge variants serve surgical visualization systems where color stability specifications exceed solid-state alternatives.
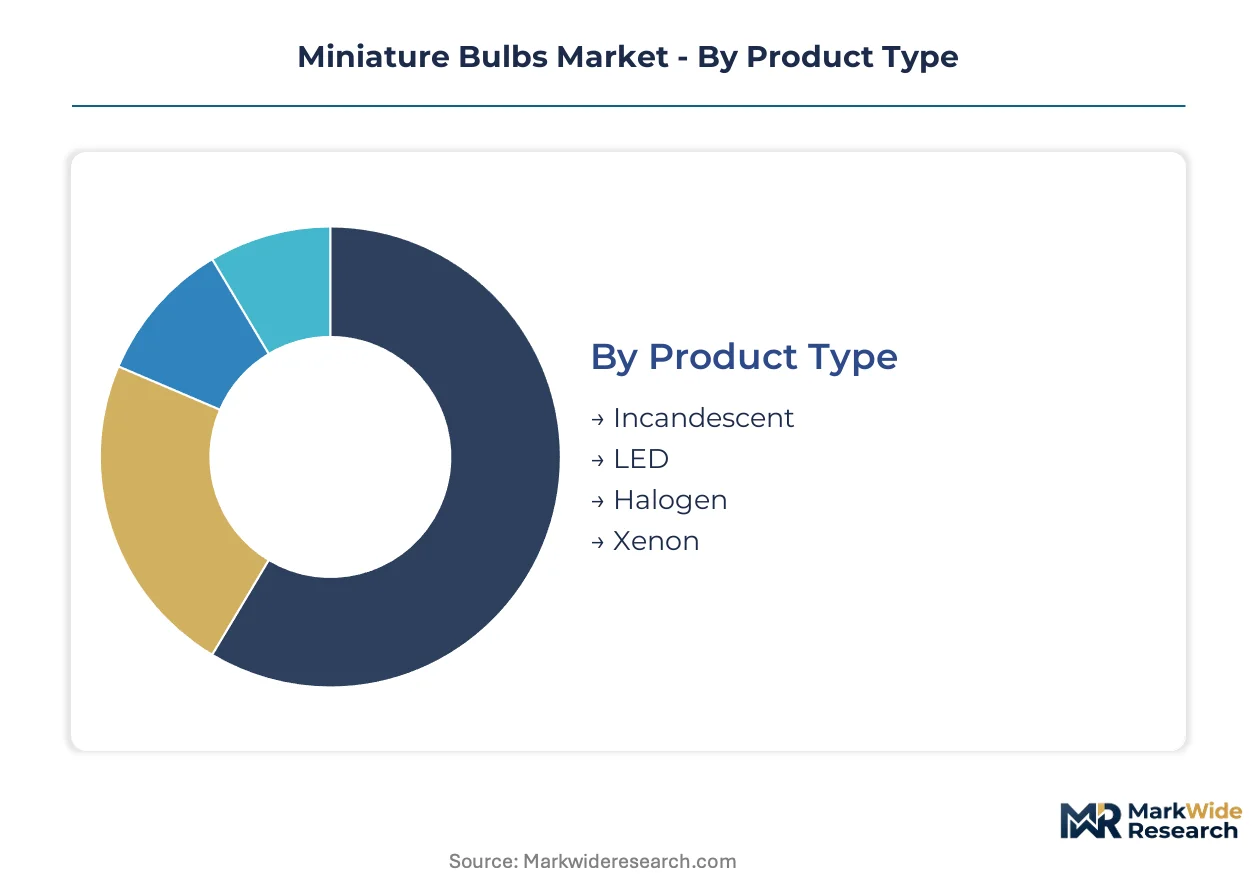
LED sits at the top of the volume ranking, with Xenon climbing the fastest on medical endoscopy equipment demand.
Application:
Cost stratification separates military-grade avionics retrofits from mass-market automotive interior modules, with certification tier determining supplier margin capture.
- Automotive Lighting:Chip-on-board LED modules dominate OEM interior and dashboard illumination as electrification mandates low-draw power budgets. Tier-1 suppliers are reducing qualified vendor counts by half to simplify quality assurance overhead across vehicle platforms.
- Instrumentation:Precision color rendering requirements sustain demand for xenon and halogen formats in medical endoscopy and aircraft cockpit displays. FAA and EASA certification timelines for avionics backlighting extend qualification pathways and tie up working capital in pre-revenue phases.
- Flashlights:Portable illumination applications favor LED formats for thermal efficiency in space-constrained enclosures.
- Decorative Lighting:Aesthetic applications tolerate wider spectral variance, reducing regulatory compliance intensity relative to safety-critical segments.
Automotive Lighting commands the largest revenue pool, while Instrumentation delivers the steepest expansion trajectory on medical equipment demand.
Form Factor:
Socket standardization across Germany's automotive cluster is compressing format diversity, with T10 and T5 configurations facing structural decline in OEM channels.
- T10:Wedge-base incandescent formats sustain aftermarket replacement demand across aging vehicle fleets and legacy industrial control panels. Retrofitting solid-state modules into existing T10 socket configurations requires custom engineering that fragments production runs.
- Festoon:Cylindrical envelope designs serve automotive interior dome lighting and vanity mirror applications. Ceramic substrate bases from Panasonic's captive manufacturing anchor thermal management for high-temperature miniature applications.
- T5:Compact wedge variants face accelerated substitution in dashboard indicator roles where LED modules meet NHTSA vehicle safety regulations.
- MR16:Reflector-equipped formats retain niche positioning in directional accent lighting with precise beam control requirements.
Festoon maintains volume leadership, with MR16 gaining share fastest on premium architectural lighting demand.
Power Rating:
India's PLI scheme for automotive components is attracting module assembly investment toward 5W and 10W ratings for emerging electric vehicle platforms.
- 5W:Mid-range LED modules balance thermal dissipation requirements with automotive interior illumination specifications. Production-linked incentives in India are concentrating assembly capacity for domestic electric vehicle supply chains.
- 10W:Higher-draw formats serve medical instrumentation and aircraft cockpit displays where shock resistance and thermal management specifications exceed consumer-grade capabilities.
- 1W:Ultra-low power variants address indicator and signaling applications in battery-constrained devices.
- 20W:High-output configurations retain positioning in surgical visualization systems requiring intense directional illumination.
5W dominates shipment volumes, with 10W expanding most quickly on medical and avionics certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive interior lighting R&D while the United States sustains medical instrumentation demand, creating divergent growth trajectories across mature markets. Regulatory carbon accounting in Europe contrasts with efficiency mandates in Asia-Pacific manufacturing hubs. Industrial clusters in specific cities now determine competitive access rather than national borders alone.
Germany
Automotive OEMs around Munich and Stuttgart are consolidating vendor lists for standardized LED modules across vehicle platforms. REACH and RoHS compliance through ECHA enforcement filters market access for mercury-free alternatives in instrument panel illumination. The Munich-Stuttgart corridor generates technology spillover effects that reshape tier-1 supplier specifications continent-wide.
United States
FDA-cleared medical endoscopy equipment sustains premium demand for xenon formats requiring precise color rendering in surgical visualization. EPA energy conservation standards and NHTSA vehicle safety regulations shape dual qualification pathways for dashboard indicator lighting. Greater Detroit's automotive supply base pivots toward chip-on-board architectures as electrification mandates accelerate.
China
National dual carbon goals and MIIT energy efficiency mandates create regulatory tailwinds for low-power LED modules in industrial control panels. GB standards enforcement tightens embedded carbon reporting requirements for component manufacturers serving export markets. Yangtze River Delta manufacturing hubs concentrate module assembly capacity for domestic and international automotive programs.
India
The PLI scheme for automotive components attracts module assembly investment toward 5W and 10W ratings for emerging electric vehicle platforms. BIS certification requirements and DGFT import regulations shape local content thresholds for lighting component sourcing. Tamil Nadu and Gujarat production corridors concentrate foreign and domestic OEM supplier manufacturing.
Japan
METI efficiency standards and JIS certification requirements maintain premium positioning for high-reliability miniature formats in avionics and medical instrumentation. PMDA device clearance timelines extend qualification pathways for surgical visualization equipment backlighting. Kansai region producers anchor ceramic substrate engineering for high-temperature miniature applications.
Miniature Bulbs Market Competitive Landscape
German producers anchor one tier through captive chip-on-board LED architectures; Japanese specialists hold another via ceramic substrate engineering for thermal management. The vendor base compresses as automotive OEMs halve qualified supplier counts to simplify quality assurance overhead. Three archetypes now dominate: vertically integrated semiconductor packagers, captive substrate manufacturers, and rapid-response custom geometry specialists. Consolidation through long-term supply agreements replaces spot procurement, while backward integration into ceramic base production emerges as a defensive margin move.
Within the integrated manufacturing tier, Osram GmbH and Panasonic Corporation exemplify divergent approaches to thermal substrate control, with the former anchoring European automotive programs and the latter supplying high-temperature miniature bases through captive production. Norman Lamps occupies a position in the custom filament segment serving aftermarket instrument cluster demand. These three entities represent the structural split between semiconductor-led consolidation and legacy format persistence.
| Leading Market Players |
|---|
| Norman Lamps |
| Grainger |
| Sunray Lighting |
| GE Lighting |
| Philips Lighting (Signify) |
| Osram GmbH |
| Panasonic Corporation |
| Lutron Electronics |
| Hubbell Incorporated |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA-cleared medical formats and commodity automotive aftermarket bulbs manifests in divergent margin structures and sourcing configurations. Premium xenon and halogen envelopes for surgical visualization command captive ceramic substrate supply from Kansai-region producers, while mass-market LED modules face price compression from standardized chip-on-board architectures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing hubs are reshaping price floors for standardized LED modules serving automotive interior applications. Three-tier pricing structure across premium medical-grade, standard OEM-specification, and economy aftermarket levels reflects FDA clearance costs versus bulk contract volumes. Pricing pressure stems from solid-state substitution in vehicle electrification programs. Aftermarket replacement demand for T10 and T5 incandescent formats shows highest price sensitivity, while medical instrumentation buyers prioritize color stability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Germany's Munich-Stuttgart automotive cluster, while distributor networks serve fragmented aftermarket replacement. Manufacturing concentrates in China, Germany, and Japan for distinct format specializations. Raw material dependencies include tungsten filament wire from Central Asian mining operations, ceramic substrate bases from Japanese captive production, and semiconductor junctions from East Asian foundries. Single-source vulnerability in ceramic substrate supply creates structural risk for high-temperature miniature applications. Distribution runs through tier-1 automotive supplier networks and medical device OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive electrification and EU Green Deal CSRD mandates shift procurement toward premium mercury-free LED specifications with embedded carbon documentation.
For Market Incumbents: Deepen backward integration into ceramic substrate production to defend margin position against Panasonic's captive manufacturing advantage. Secure long-term supply agreements with Munich-Stuttgart automotive OEMs before vendor list consolidation halves qualified supplier counts. Prioritize REACH and RoHS certification investment as ECHA enforcement intensifies.
For New Entrants and Emerging Players: Launch via direct partnerships with India's Tamil Nadu and Gujarat production corridors to capture PLI scheme benefits for 5W and 10W module assembly. Target aircraft cockpit display retrofits as the most penetrable niche where shock-resistant formats exceed consumer-grade LED capabilities. Pursue FAA and EASA certification as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where chip-on-board packaging expertise gaps constrain mid-tier supplier capacity expansion. The 5-10 year viability window favors acquisition of vertically integrated semiconductor packagers with thermal engineering capabilities. Watch NHTSA vehicle safety certification timeline extensions as the signal indicating working capital stress and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Captive supply of high-temperature bases anchors thermal management specifications for medical and avionics applications. |
| REACH and RoHS Compliance Certification | ECHA mercury-free validation opens access to EU automotive OEM procurement channels undergoing vendor consolidation. |
| Long-term Supply Agreement with Tier-1 Automotive Suppliers | Platform standardization across vehicle programs locks in volume commitments and reduces spot procurement exposure. |
| Capacity Expansion in India PLI Corridors | Tamil Nadu and Gujarat assembly investment captures domestic content requirements for emerging electric vehicle platforms. |
| FAA and EASA Avionics Certification Pathway | Shock-resistant miniature formats for cockpit displays command premium positioning where consumer-grade LEDs fail thermal specifications. |
Research Methodology
Direct dialogue with tier-1 automotive supplier procurement officers, medical device OEM regulatory affairs leads, ceramic substrate manufacturing engineers, and aftermarket distribution channel managers grounded qualitative insights. Secondary validation drew from EPA energy conservation standard filings, ECHA REACH substance restriction databases, NHTSA vehicle safety lighting regulations, and EU Green Deal CSRD implementation guidance. Bottom-up shipment data triangulated against top-down OEM platform content estimates across the analysis window.
Segmentation-level outputs across product type, application, form factor, and power rating dimensions were modeled through the projection horizon. CAGRs were derived from regression analysis of historical shipment trajectories against automotive electrification penetration curves and medical equipment capital expenditure cycles. Forecast inputs included chip-on-board LED adoption rates, REACH compliance cost pass-through assumptions, and India PLI scheme capacity buildout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tungsten filament input volatility and NHTSA certification timeline extensions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Recessed Lighting Market
Lighting
Global Commercial Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Tritium Light Source Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Photography Light Box Market
Lighting
Illuminating Signs Market
Lighting
Architectural Lighting Market
Lighting
Smart Lights Market
Lighting
Solar Rope Light Market
Lighting
OLED Lightening Panels Market
Lighting
Xenon Headlights Market
Lighting
Dimmer and Color Tunable Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Lighting Market
Lighting
Xenon Flashlamps Market