
 Germany Indoor LED Lighting Market | 2026-2036
Germany Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Indoor LED Lighting Market Insights
Lighting-as-a-service and third-party leasing of LED retrofit assets is rewriting competitive entry requirements for mid-sized electrical contractors and facility managers. TRILUX GmbH & Co. KG leverages captive manufacturing in Arnsberg to sustain cost discipline across commercial specification projects. Zumtobel Group anchors premium positioning through architectural-grade downlight and track systems for museum and gallery segments. ams-OSRAM AG competes at the component tier, supplying LED packages and drivers that power downstream luminaire brands.
Germany Indoor LED Lighting comprises solid-state luminaires employing semiconductor diodes with typical efficacies exceeding 100 lumens per watt, color rendering indices above 80, and rated lifespans of 50,000 hours or more, designed to replace fluorescent and halogen sources in enclosed building environments. Panel lights dominate volume in open-plan commercial refurbishment due to standardized ceiling grid compatibility and uniform glare control. Smart control technology represents the fastest-expanding dimension, with wireless DALI-2 and Zigbee protocols displacing conventional wired dimming in new construction. Downlights retain margin concentration in high-end residential and hospitality applications where beam precision and trim aesthetics command specification premiums.
KBA energy efficiency labeling, the EU Ecodesign Directive, and Germany's Building Energy Act collectively mandate minimum luminous efficacy thresholds and phase out non-directional halogen sources, compelling stock turnover in existing building stock. The Federal Office for Economic Affairs and Export Control administers subsidies through the Federal Funding for Efficient Buildings program that offset upfront LED retrofit costs for commercial property owners. Stakeholders must weigh interoperability commitments across proprietary smart lighting ecosystems against the risk of stranded control infrastructure as open standards mature.
Market Dynamics
The Germany Indoor LED Lighting Market is being fundamentally restructured by the collision of the EU Ecodesign Directive's phase-out deadlines with the accelerating shift toward wireless DALI-2 and Zigbee control architectures. This regulatory-technology squeeze is compressing replacement cycles and forcing specification decisions around interoperability before open standards fully mature.
Growth Catalysts
- Building Energy Act retrofit mandates:Germany's federal efficiency standards for commercial buildings are compelling property owners in Bavaria and North Rhine-Westphalia to accelerate fluorescent-to-LED conversions.
- Federal Funding for Efficient Buildings subsidies:The BAFA-administered program offsets upfront capital costs for LED installations, reducing payback periods for mid-sized facility managers.
- Smart control protocol maturation:Wireless DALI-2 and Zigbee ecosystems are enabling granular zone control in open-plan offices, driving specification premiums for connected luminaire packages.
Market Restraints
- LED driver supply concentration:Captive manufacturing of critical power electronics remains concentrated among a handful of European and Asian component suppliers, creating input bottlenecks.
- Interoperability risk premium:Proprietary smart lighting ecosystems from dominant platform vendors threaten stranded infrastructure investments as open standards evolve.
- Skilled electrical contractor scarcity:Certified installation capacity for networked lighting controls is insufficient across German metropolitan construction markets.
Strategic Opportunities
- Lighting-as-a-service model expansion:Third-party leasing of LED retrofit assets lowers capital barriers for mid-tier commercial property owners in secondary German cities.
- Museum and gallery specification vertical:Architectural-grade track and downlight systems for cultural institutions command margin premiums through specialized beam control and CRI performance.
- KBA energy efficiency labeling alignment:Early certification to tightened German automotive-sector lighting standards creates transferable credibility for industrial facility applications.
Industry Challenges
- Legacy fluorescent disposal compliance:Mercury-containing lamp decommissioning under German hazardous waste regulations adds operational complexity and cost to retrofit projects.
- Control system integration fragmentation:Building management system interoperability requires bespoke commissioning for each proprietary platform, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Indoor LED Lighting Market |
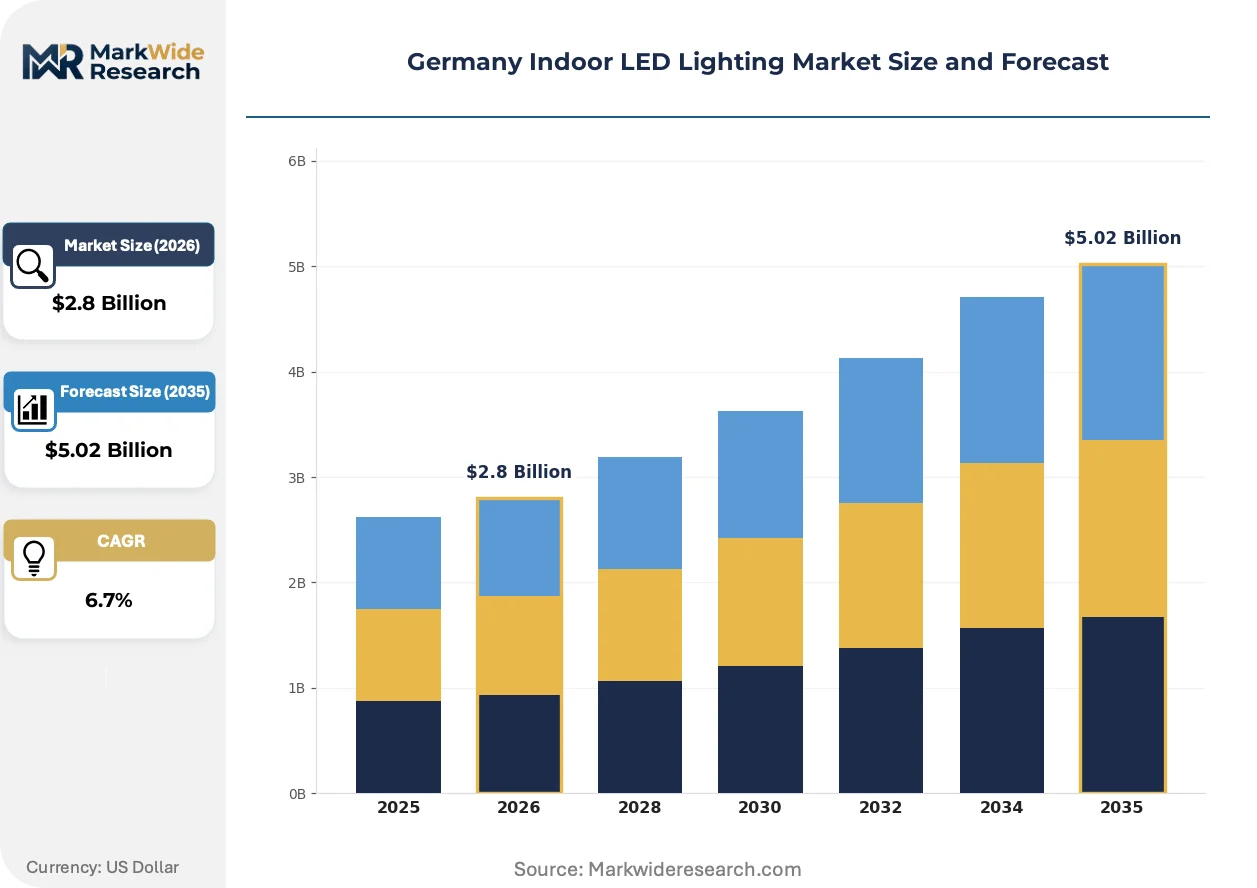
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Bulbs, Tube Lights Installation Type: Recessed, Surface-mounted, Pendant, Wall-mounted End User: Residential, Commercial, Retail, Industrial Control Technology: Dimming, Smart Control, Wired, Wireless |
| Companies Covered | TRILUX GmbH & Co. KG, Zumtobel Group, ams-OSRAM AG, Thorn Lighting Ltd., ERCO, Signify (Philips), EGLO Leuchten GmbH, Thorlux Lighting, LEDVANCE GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Indoor LED Lighting Market Trends and Innovations
Human-centric lighting and circadian rhythm optimization are migrating from healthcare and education verticals into mainstream commercial specification. This shift is reshaping product development priorities around tunable white and dynamic color temperature capabilities rather than static efficacy metrics alone.
Human-centric LED systems with tunable white and melanopic flux control are hybridizing conventional architectural lighting with wellness infrastructure. Corporate headquarters and co-working operators in Frankfurt and Munich are specifying these systems for employee retention and productivity claims. The technology is hybridizing lighting procurement with workplace strategy budgets, compressing traditional silos between facilities and human resources capital planning.
Germany's transposition of the EU Ecodesign Directive into national law is eliminating non-directional halogen sources from the market ahead of broader EU timelines. The Federal Office for Economic Affairs and Export Control is enforcing minimum luminous efficacy thresholds that disqualify legacy fluorescent troffers from new commercial installations. Premium downlight and panel manufacturers are responding with accelerated R&D on integrated sensor packages that justify price positioning through compliance and control functionality.
Facility managers are consolidating vendor relationships around full-service lighting partners capable of delivering design, installation, financing, and ongoing maintenance through single contracts. This consolidation is displacing the traditional fragmented procurement of luminaires, controls, and electrical labor through separate channels. The pattern is most visible in large-scale retail fit-outs across North Rhine-Westphalia, where total-cost-of-ownership calculations now dominate upfront capital expenditure decisions.
Germany Indoor LED Lighting Market Segmentation
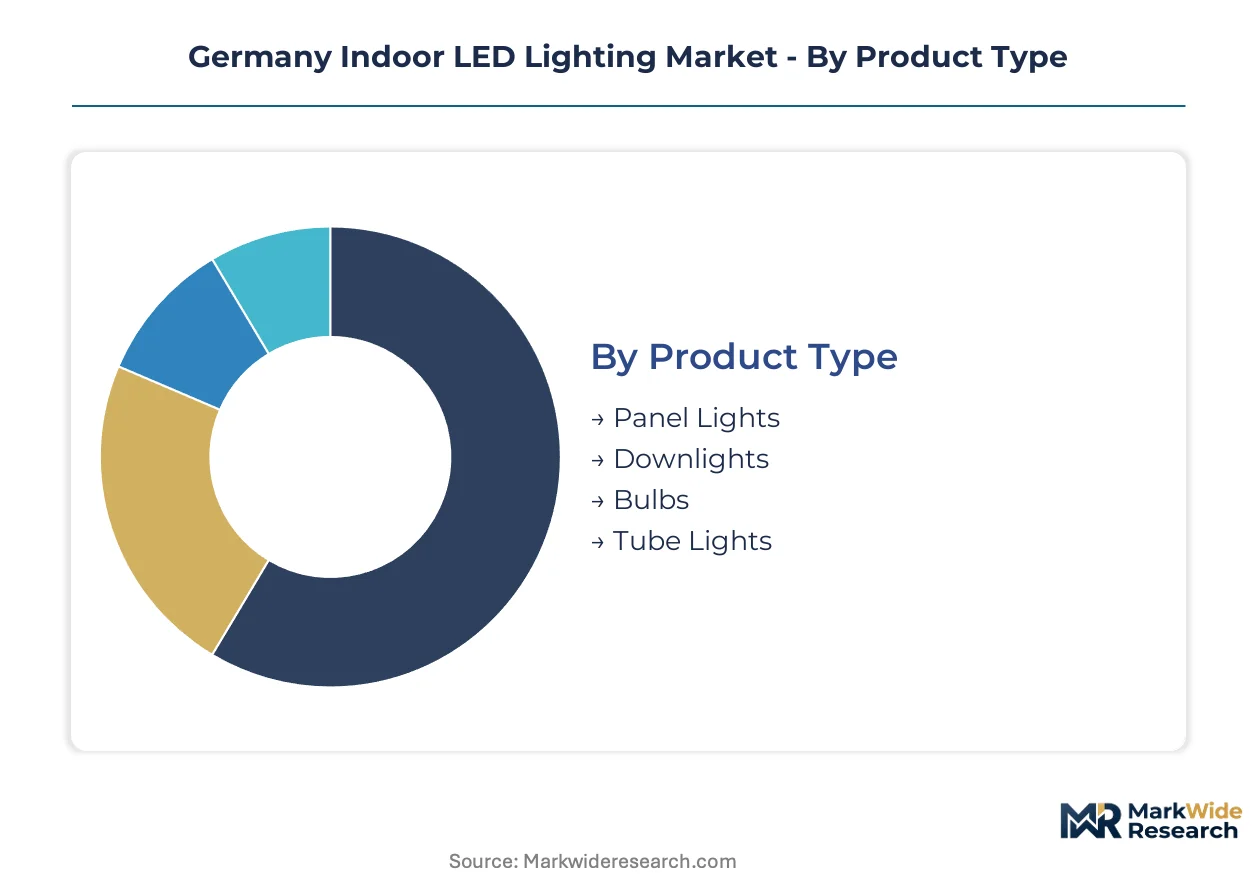
Product architecture, mounting configuration, and control sophistication segment German indoor LED demand into distinct specification tiers. Each dimension carries divergent margin profiles, regulatory exposure, and retrofit versus new-build applicability.
Product Type:
Cost tier stratification separates commodity replacement lamps from integrated luminaire systems with embedded controls and thermal management.
- Panel Lights:Flat-profile edge-lit or back-lit fixtures designed for suspended ceiling grid integration, typically 600x600mm or 1200x600mm formats. Bavarian and North Rhine-Westphalian commercial office retrofits concentrate demand here, driven by standardized compatibility with existing infrastructure and uniform glare suppression for open-plan workstations.
- Downlights:Recessed ceiling luminaires with precision reflector optics or lens arrays for controlled beam distribution. Frankfurt and Munich hospitality and high-end residential specifications prioritize these for trim aesthetics and CRI performance above 90, commanding margin premiums through architectural-grade specification.
- Bulbs:Retrofit A-shape, globe, and candle form factors with Edison or bayonet bases for direct lamp replacement. Mass-market residential channels in secondary German cities absorb volume as halogen phase-out compliance purchases.
- Tube Lights:Linear LED substitutes for T8 and T5 fluorescent tubes, available as integrated fixtures or retrofit lamps with internal drivers. Industrial facility maintenance departments specify these for high-bay and warehouse applications where lumen maintenance and vibration resistance matter.
Panel lights command the established base. The steepest expansion runs through downlights with integrated smart control packages.
Installation Type:
Mounting geometry determines project complexity, electrical contractor skill requirements, and compatibility with legacy building stock.
- Recessed:Luminaires installed into ceiling voids with visible trim profiles flush to the surface. Commercial fit-outs across German metropolitan construction markets concentrate specification here, though skilled installer scarcity extends commissioning timelines for networked control integration.
- Surface-mounted:Direct ceiling or wall attachment without plenum penetration. Secondary city retail refurbishments favor these for speed of installation and minimal structural intervention where suspended ceilings are absent.
- Pendant:Suspended cable or rod mounting for decorative or task-oriented illumination. Co-working and hospitality interiors in Berlin and Hamburg specify these for spatial definition and biophilic design integration.
- Wall-mounted:Vertical surface attachment for accent, cove, or circulation lighting. Museum and gallery verticals in Munich and Cologne prioritize these for grazing and wall-wash applications with precise cutoff control.
Recessed installations retain the volume concentration. Pendant mounting gains share fastest in wellness-oriented workplace redesigns.
End User:
Customer type segmentation maps to divergent procurement behaviors, from fragmented residential replacement to consolidated commercial lighting-as-a-service contracts.
- Residential:Individual homeowners and multi-family property managers purchasing through electrical wholesale and retail channels. Energy efficiency labeling under KBA standards influences selection, though price sensitivity dominates volume tiers.
- Commercial:Office landlords and corporate occupiers in Frankfurt, Munich, and Düsseldorf specifying integrated systems. Federal Funding for Efficient Buildings subsidies compress payback calculations, accelerating fluorescent-to-LED conversion decisions.
- Retail:Chain operators and independent merchants prioritizing color consistency and flexible scene setting. North Rhine-Westphalia large-format fit-outs consolidate vendor relationships around full-service partners delivering design-through-maintenance contracts.
- Industrial:Manufacturing and logistics facility managers emphasizing lumen maintenance, ingress protection, and emergency lighting integration. Automotive-sector KBA certification creates transferable credibility for suppliers serving this segment.
Commercial end users anchor revenue concentration. Retail applications expand most quickly through lighting-as-a-service model adoption.
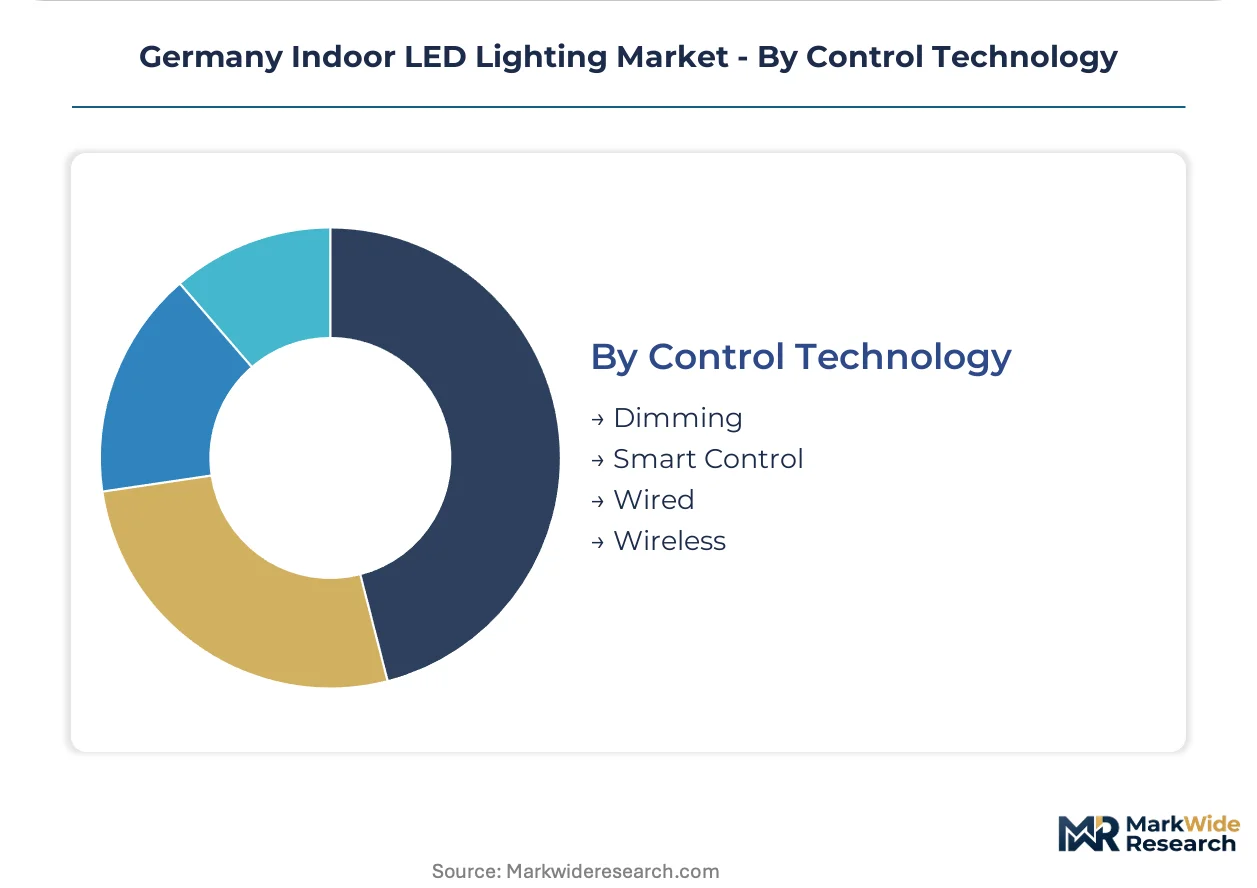
Control Technology:
Maturity gradients separate basic dimming from protocol-dependent smart architectures with interoperability risk exposure.
- Dimming:Phase-cut or 0-10V analog reduction of luminous flux for basic ambient adjustment. Legacy fluorescent retrofit projects specify these for minimal control infrastructure investment, though functionality caps at static scenes.
- Smart Control:Sensor-integrated, network-connected systems enabling occupancy detection, daylight harvesting, and circadian programming. Corporate headquarters in Frankfurt and Munich specify tunable white and melanopic flux variants for productivity and retention claims.
- Wired:DALI-2, KNX, or proprietary bus architectures requiring dedicated control cabling. New construction with integrated building management systems favors these for reliability, though commissioning complexity extends project timelines.
- Wireless:Zigbee, Bluetooth Mesh, or proprietary RF protocols eliminating control wiring. Open-plan office refurbishments adopt these for speed of installation, though proprietary ecosystem commitments risk stranded infrastructure as standards mature.
Wired controls hold the installed base. Wireless architectures climb the fastest as interoperability standards stabilize and installer capacity constraints bite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal subsidies under the Building Energy Act are compressing payback periods for LED retrofits across German metropolitan construction markets. Bavaria and North Rhine-Westphalia anchor commercial specification volume through concentrated office refurbishment programs. Regional differentiation stems from varying enforcement intensity of KBA energy efficiency labeling and municipal procurement preferences for smart-enabled installations.
Bavaria
Munich's corporate headquarters and co-working operators are specifying human-centric lighting systems for employee retention claims. The Federal Funding for Efficient Buildings program subsidizes fluorescent-to-LED conversions in commercial properties throughout the state. Automotive-sector KBA certification requirements create transferable credibility for suppliers serving Bavarian industrial facilities.
North Rhine-Westphalia
Düsseldorf and Cologne retail fit-outs are consolidating vendor relationships around full-service lighting partners delivering design-through-maintenance contracts. The EU Ecodesign Directive's phase-out deadlines for non-directional halogen sources are accelerating replacement cycles in existing building stock. Large-format commercial refurbishments in the Ruhr region concentrate demand for standardized panel light installations.
Baden-Württemberg
Stuttgart's automotive and industrial machinery sectors are driving specification for high-bay tube lights with lumen maintenance guarantees. Germany's Building Energy Act mandates minimum efficacy thresholds that disqualify legacy fluorescent troffers from new installations in commercial properties. Museum and gallery verticals in the region prioritize architectural-grade downlights with CRI performance above 90.
Hesse
Frankfurt's financial services occupiers are adopting wireless DALI-2 control architectures for granular zone management in open-plan offices. BAFA-administered subsidies offset upfront capital costs for LED installations, reducing payback periods for mid-sized facility managers. The city's premium hospitality sector commands margin premiums for recessed downlights with precision beam control.
Berlin-Brandenburg
Co-working and creative industry operators in Berlin are specifying pendant-mounted luminaires for spatial definition and biophilic design integration. Skilled electrical contractor scarcity for networked lighting controls extends commissioning timelines across the metropolitan construction market. Secondary city retail refurbishments in Brandenburg favor surface-mounted fixtures for speed of installation where suspended ceilings are absent.
Germany Indoor LED Lighting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification tiers defined by project scale and control sophistication. The market structure concentrates around captive manufacturing capabilities and full-service contracting capacity. Three archetypes dominate: vertically integrated luminaire manufacturers with in-house LED packaging, component-tier suppliers of drivers and emitters, and lighting-as-a-service operators bundling financing with maintenance. Competitive moves center on strategic partnerships for smart control interoperability and portfolio diversification into human-centric lighting systems.
Among Germany-based integrated manufacturers, TRILUX GmbH & Co. KG and Zumtobel Group occupy positions on opposite ends of the specification spectrum. TRILUX exemplifies the scale-driven archetype through captive manufacturing in Arnsberg serving commercial retrofit volume. Zumtobel represents the premium-tier specialist focused on architectural-grade specification for cultural institutions. At the component tier, ams-OSRAM AG anchors supply relationships with downstream luminaire brands across European markets.
| Leading Market Players |
|---|
| TRILUX GmbH & Co. KG |
| Zumtobel Group |
| ams-OSRAM AG |
| Thorn Lighting Ltd. |
| ERCO |
| Signify (Philips) |
| EGLO Leuchten GmbH |
| Thorlux Lighting |
| LEDVANCE GmbH |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Asian LED driver manufacturing is compressing margins for German luminaire assemblers while simultaneously elevating pricing power among captive component producers. The BAFA subsidy program partially offsets this pressure for commercial retrofit buyers, though residential channels absorb full cost pass-through.
Pricing Analysis
Certification level under KBA and EU Ecodesign standards creates the primary spread between premium architectural specification and commodity replacement tiers. Project-based pricing dominates commercial fit-outs, with volume scale and control sophistication as secondary differentiation factors. Cost compression in standard panel lights is intensifying as Chinese imports flood electrical wholesale channels. Residential buyers exhibit highest price sensitivity, while museum and gallery curators prioritize CRI performance above unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for German LED importers. LED packages and drivers concentrate in China, Taiwan, and South Korea, with phosphor materials and aluminum heat sinks drawing from German and Dutch suppliers. Single-source vulnerability in DALI-2 controller chipsets threatens stranded inventory during protocol transitions. Distribution runs through electrical wholesale networks serving contractor specification, with direct OEM relationships gaining share in large-scale retail fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Indoor LED Lighting Market is approaching a platform-economics inflection as proprietary Zigbee ecosystems collide with maturing open standards. Interoperability commitments made today will determine competitive positioning through the next retrofit cycle.
For Market Incumbents: Harden captive manufacturing positions in LED packaging and driver electronics against Asian component volatility. Consolidate specification relationships with facility managers through lighting-as-a-service contracts that embed long-term maintenance revenue. The EU Ecodesign Directive's phase-out deadlines threaten margin erosion for pure-play luminaire assemblers lacking upstream control. For New Entrants and Emerging Players: Secondary city retail refurbishment in Saxony and Thuringia offers underpenetrated white-space with reduced incumbent saturation. Museum and gallery verticals in Cologne and Stuttgart command specification premiums through specialized beam control expertise. A go-to-market angle centered on human-centric lighting wellness claims differentiates against commodity panel competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless control sub-segments as chipset commoditization accelerates. Long-term viability favors full-service operators bundling financing, installation, and maintenance over pure manufacturing plays. Acquisition targets should demonstrate proven DALI-2 integration capabilities and established BAFA subsidy navigation. The signal to watch is consolidation velocity among mid-sized electrical contractors facing skilled installer scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Platform Integration | DALI-2 and Zigbee interoperability investments reduce stranded infrastructure risk for commercial specifiers. |
| Lighting-as-a-Service Model Expansion | Third-party leasing structures lower capital barriers and capture recurring maintenance revenue streams. |
| Human-Centric Lighting Development | Tunable white and melanopic flux capabilities command specification premiums in corporate headquarters. |
| Backward Integration into LED Packaging | In-house emitter production insulates margin pressure from Asian driver supply concentration. |
| BAFA Certification Alignment | Early compliance with tightened German efficiency standards creates transferable credibility across segments. |
Research Methodology
A spread of perspectives from electrical contractors, facility managers, lighting designers, and BAFA program administrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with specification professionals and procurement leads at commercial property operators. Secondary validation drew from EU Ecodesign Directive filings, KBA energy efficiency labeling databases, German customs trade records, and BAFA subsidy disbursement reports. Bottom-up luminaire shipment data triangulated against top-down building stock retrofit projections.
Demand-supply balance modeling anchored the forecast framework across the analysis window. Segmentation dimensions included product architecture, mounting configuration, end-user category, and control technology sophistication. CAGRs derived from fitted growth curves calibrated to historical replacement cycle data and regulatory phase-out timelines. Key inputs incorporated BAFA funding authorization trajectories and EU Ecodesign enforcement intensity assumptions.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles or German federal subsidy appropriations would shift the trajectory. Forecasts reflect documented assumptions about interoperability standard maturation and skilled installer capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Ultraviolet Lamps Market
Lighting
Gesture Control Light Market
Lighting
Display Light Control Film Market
Lighting
Tritium Light Source Market
Lighting
Art and Museum Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Street Lighting Market
Lighting
Recessed Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Smart Lights Market
Lighting
Smart Lighting Market
Lighting
Industrial Lighting Market
Lighting
Asia-Pacific Lighting Control Market