
 Wearable Motion Sensors Market | 2026-2036
Wearable Motion Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Motion Sensors Market Analytics
Buyer concentration in enterprise healthcare procurement is realigning how sensor vendors allocate R&D resources. STMicroelectronics leverages its MEMS fabrication scale to serve hospital system tenders across Europe. Bosch Sensortec anchors consumer wearable supply through direct partnerships with fitness device OEMs.
Wearable motion sensors are microelectromechanical systems (MEMS) that detect acceleration, angular velocity, or magnetic field orientation, typically packaged in surface-mount housings below 3 mm thickness for integration into body-worn electronics. Their primary purpose is converting physical movement into digital signals for real-time biomechanical analysis or navigation assistance. Accelerometer technology dominates unit shipments due to its inclusion in every fitness tracker and smartwatch baseline configuration. Healthcare end users command premium pricing for magnetometer-enhanced gait analysis systems used in neurological rehabilitation.
FDA clearance pathways for clinical-grade wearables and the EU Medical Device Regulation create dual compliance burdens for vendors seeking transatlantic distribution. ISO 13485 quality management certification has become a de facto entry requirement for hospital procurement committees. Stakeholders must monitor how software-as-medical-device classifications in the United States and European Union reshape liability and validation obligations for integrated sensor-fusion algorithms.
Market Dynamics
Hospital procurement committees now require ISO 13485 certification as a baseline filter, compressing vendor qualification timelines and forcing MEMS fabricators to restructure quality management systems before tender participation.
Growth Catalysts
- EU Medical Device Regulation:Tightened accuracy requirements for clinical-grade wearables create premium pricing tiers for magnetometer-enhanced gait analysis systems in neurological rehabilitation.
- Remote patient monitoring:Healthcare providers expanding RPM programs drive sensor volume for continuous ambulatory assessment in post-surgical recovery protocols.
- Germany's industrial cluster:Concentrated demand around Munich and Stuttgart anchors specialized supply chains for ergonomic workplace wearables in automotive manufacturing.
Market Restraints
- MEMS fabrication concentration:Foundry capacity constraints in East Asia create supply bottlenecks for 3 mm surface-mount accelerometer packages during demand surges.
- Dual compliance burden:FDA clearance pathways and EU MDR create parallel validation costs for vendors seeking transatlantic distribution without harmonized testing protocols.
- Software-as-medical-device classification:Uncertain liability frameworks for sensor-fusion algorithms in the United States and European Union delay product launches.
Strategic Opportunities
- Neurological rehabilitation:Magnetometer-enhanced gait analysis systems command premium pricing from healthcare end users seeking objective mobility metrics.
- Fitness device OEM partnerships:Direct supply relationships with consumer wearable manufacturers offer volume anchors for accelerometer baseline configurations.
- ISO 13485 certification services:Quality management consulting for MEMS fabricators represents adjacent revenue as hospital procurement standards tighten.
Industry Challenges
- Sensor-fusion algorithm validation:Integrated accelerometer-magnetometer-gyroscope systems require extensive clinical testing to meet EU MDR accuracy thresholds.
- Biomechanical analysis talent:Shortage of engineers combining MEMS physics with clinical movement science slows product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Motion Sensors Market |
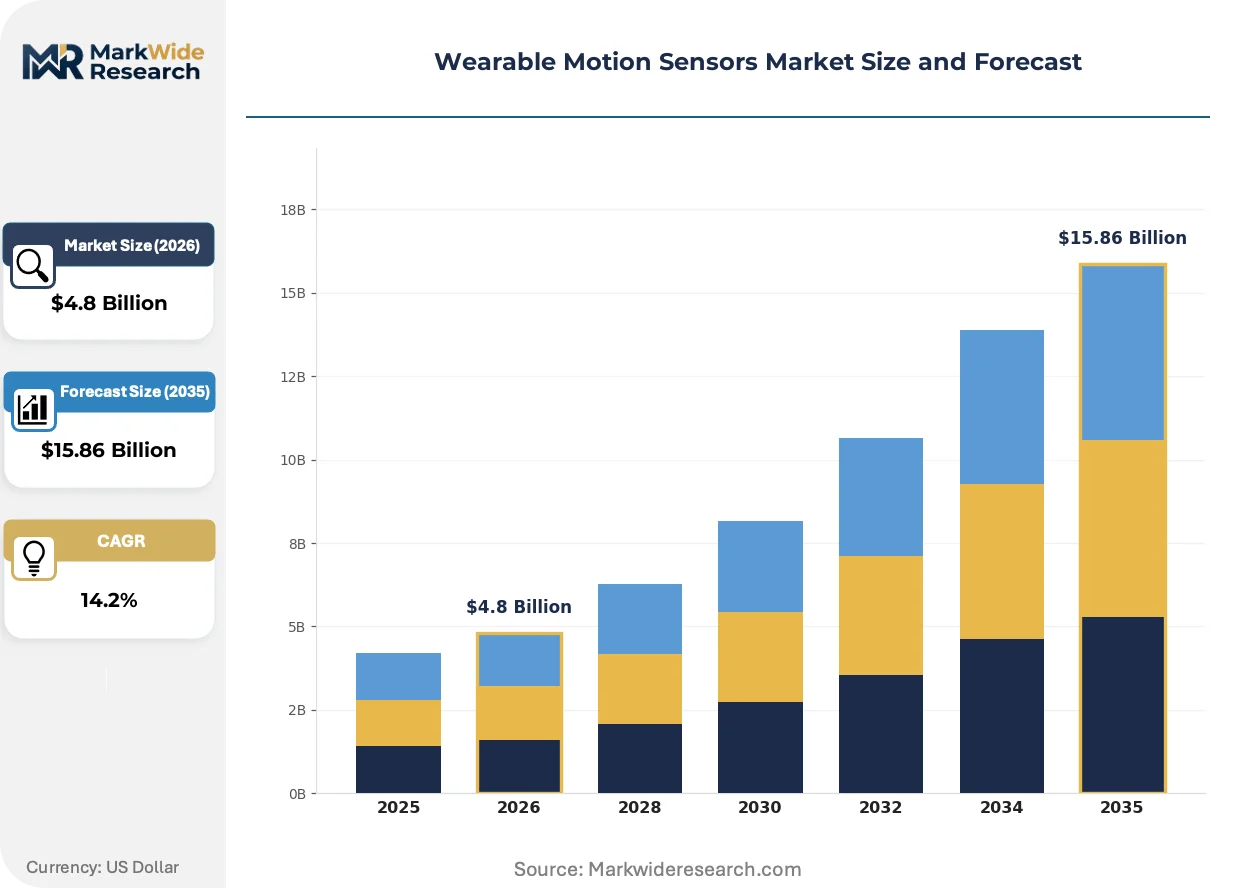
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Fitness Tracker, Smartwatch, Heart Rate Monitor, Smart Glasses Technology: Accelerometer, Gyroscope, Magnetometer, RFID End User: Healthcare, Sports, Automotive, Gaming Application: Health Monitoring, Fitness Coaching, Performance Analysis, Gesture Recognition |
| Companies Covered | STMicroelectronics, Analog Devices, Texas Instruments, Infineon Technologies, Bosch Sensortec, NXP Semiconductors, Panasonic Corporation, TE Connectivity, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Motion Sensors Market Evolving Landscape
Sensor miniaturization and algorithm sophistication are compressing the boundary between consumer fitness tracking and clinical-grade monitoring, forcing vendors to reposition product architectures.
Magnetometer arrays are expanding into neurological gait assessment systems, detecting subtle magnetic field orientation changes during ambulation. Rehabilitation clinics in Germany and the Netherlands are adopting these configurations for Parkinson's disease progression monitoring. The technology is expanding into premium pricing tiers previously reserved for laboratory-grade motion capture systems.
EU Medical Device Regulation implementation is fragmentating vendor qualification pathways, requiring separate technical documentation for clinical-grade versus wellness-designated wearables. Sensor manufacturers must maintain dual quality management systems to serve both hospital procurement committees and consumer electronics distributors. Rehabilitation device categories face the steepest compliance cost escalation.
Enterprise healthcare procurement is consolidating sensor vendor relationships around ISO 13485-certified fabricators capable of supporting tender documentation. Hospital systems are replacing fragmented supplier bases with preferred provider agreements spanning multiple wearable categories. This concentration is most visible in German hospital networks managing industrial workplace rehabilitation contracts.
Wearable Motion Sensors Market Segmentation
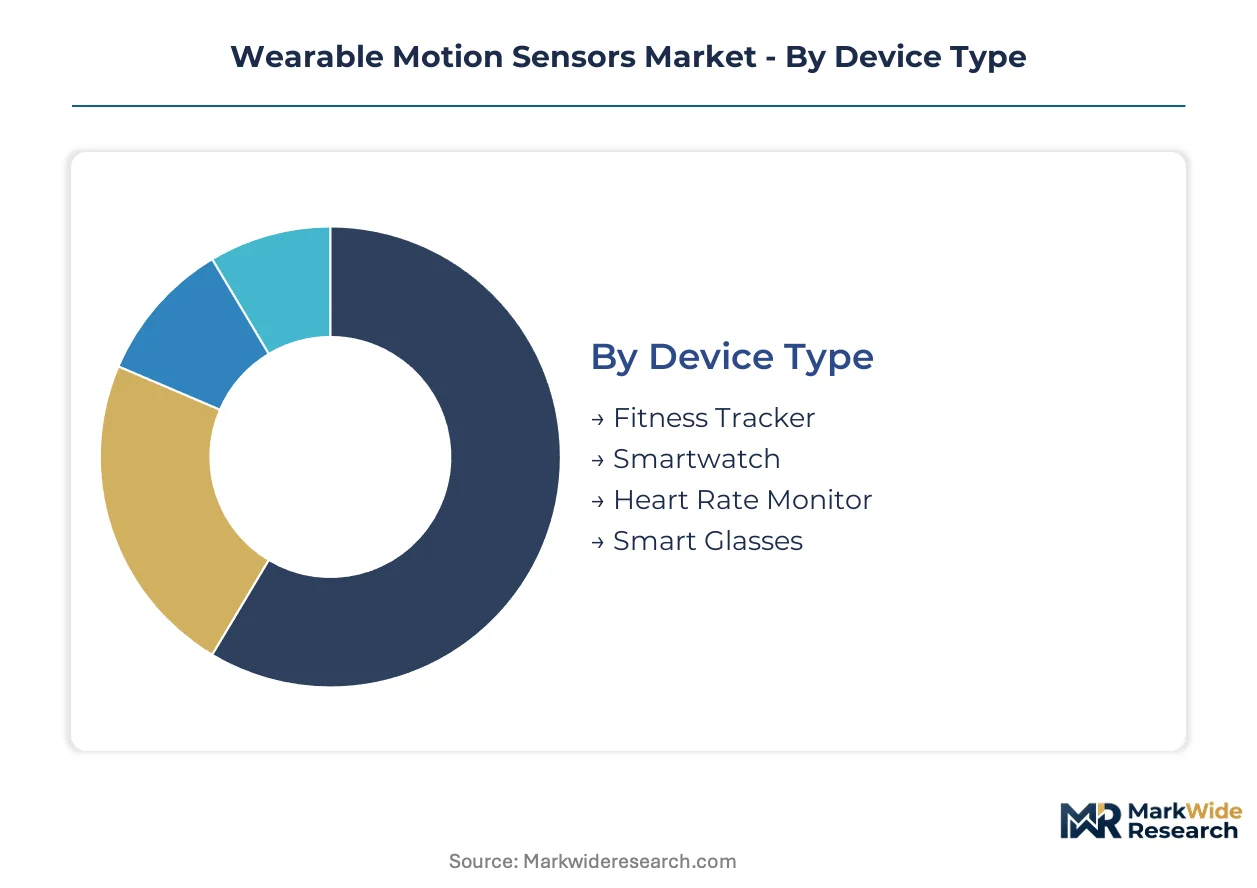
Wearable motion sensor procurement diverges sharply across use cases, with clinical validation requirements and consumer price sensitivity creating distinct commercial pathways. Understanding these segment boundaries enables vendors to align fabrication investments with margin structures and compliance burdens.
Device Type:
Hospital procurement committees filter tenders by ISO 13485 certification status, while consumer electronics distributors prioritize unit cost and supply continuity.
- Fitness Tracker:Baseline accelerometer configurations dominate unit shipments. Demand concentrates in direct OEM partnerships with consumer wearable manufacturers seeking sub-$5 BOM targets for entry-level devices.
- Smartwatch:Multi-sensor fusion platforms integrate accelerometer, gyroscope, and magnetometer arrays. Premium pricing tiers emerge in neurological rehabilitation applications across German and Dutch hospital networks.
- Heart Rate Monitor:PPG-integrated motion sensing for activity-correlated cardiac assessment. Clinical-grade variants require FDA clearance and EU MDR technical documentation.
- Smart Glasses:Head-mounted IMU configurations for industrial workplace ergonomics. Munich-Stuttgart automotive cluster demand anchors specialized supply chains.
Volume sits with fitness trackers; growth tilts toward smartwatches with clinical-grade sensor fusion.
Technology:
Component selection traces directly to end-use accuracy requirements and the regulatory classification of the finished device.
- Accelerometer:MEMS devices detecting linear acceleration across three axes, packaged below 3 mm thickness. Foundry capacity constraints in East Asia create supply bottlenecks during demand surges for surface-mount packages.
- Gyroscope:Angular velocity measurement enabling orientation tracking. Integration with accelerometers drives sensor fusion algorithm complexity and validation costs under EU MDR.
- Magnetometer:Magnetic field orientation detection for gait analysis. German rehabilitation clinics adopt these for Parkinson's disease progression monitoring at premium pricing tiers.
- RFID:Passive motion-triggered identification for industrial asset tracking. Workplace ergonomic wearables in automotive manufacturing drive concentrated demand.
Accelerometers capture baseline volume; magnetometer-enhanced systems gain share fastest in clinical rehabilitation.
End User:
Compliance architecture separates segments, with healthcare procurement requiring quality management certification absent in consumer channels.
- Healthcare:Remote patient monitoring programs drive continuous ambulatory assessment sensor volume. Post-surgical recovery protocols require magnetometer-enhanced gait analysis for objective mobility metrics.
- Sports:Performance optimization wearables prioritize real-time biomechanical feedback. Fitness coaching applications accept lower accuracy thresholds than clinical deployments.
- Automotive:Industrial workplace wearables for ergonomic monitoring concentrate around Germany's Munich-Stuttgart manufacturing cluster. OEM integration demands automotive-grade reliability standards.
- Gaming:Gesture recognition controllers emphasize latency reduction over precision. Consumer price sensitivity limits sensor fusion complexity.
Healthcare commands premium pricing; sports and gaming segments expand unit volume through consumer channels.
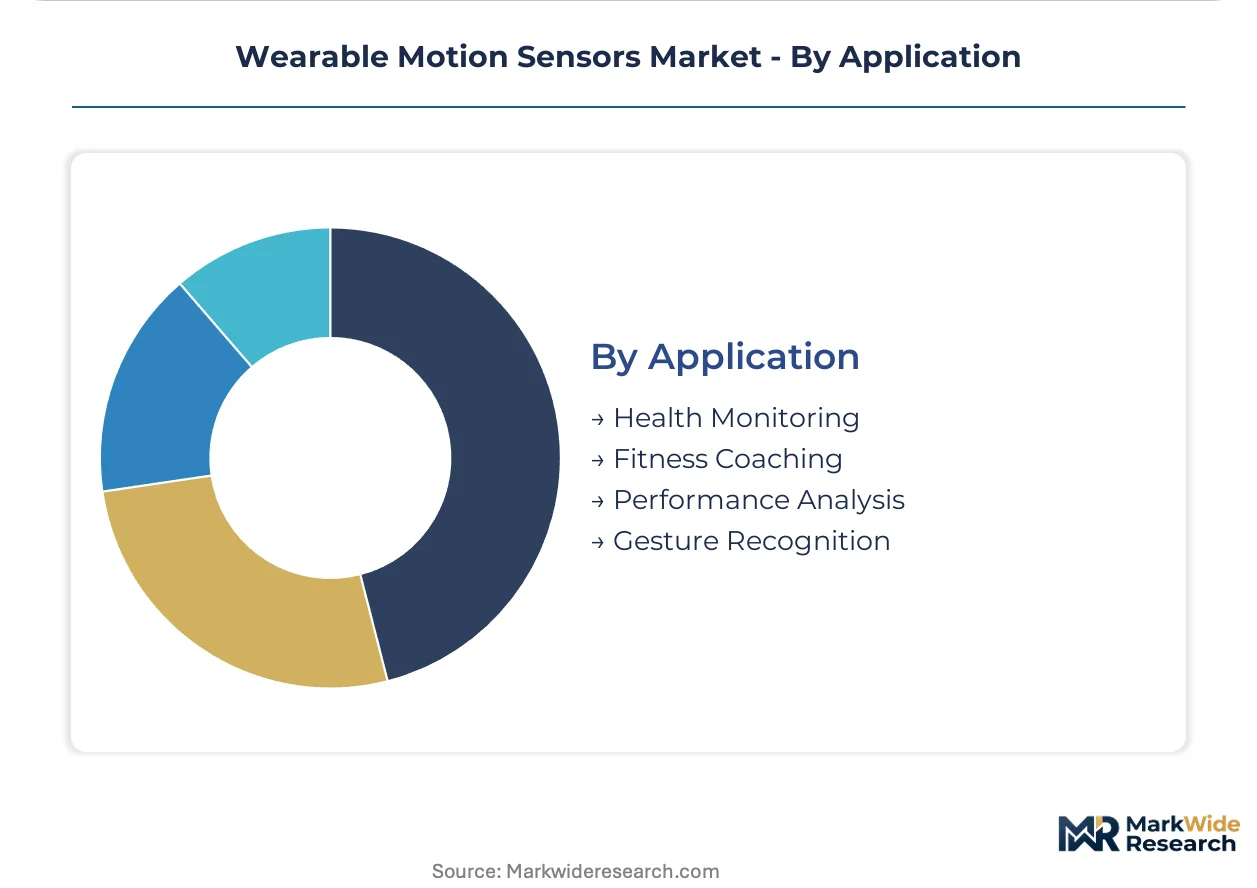
Application:
Software-as-medical-device classifications reshape liability frameworks and validation obligations for integrated algorithms.
- Health Monitoring:Continuous vital sign and activity tracking for chronic disease management. FDA clearance pathways and EU MDR create dual compliance burdens for transatlantic distribution.
- Fitness Coaching:Real-time biomechanical feedback for exercise optimization. Wellness-designated wearables avoid clinical-grade documentation requirements.
- Performance Analysis:Laboratory-grade motion capture alternatives using wearable sensor arrays. Neurological rehabilitation clinics in the Netherlands adopt these for objective assessment protocols.
- Gesture Recognition:Movement pattern classification for human-machine interface control. Gaming and industrial applications drive divergent accuracy requirements.
Health monitoring anchors clinical revenue; fitness coaching scales consumer volume without regulatory overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement committees in Germany concentrate demand for clinical-grade wearable motion sensors, while industrial workplace applications anchor specialized supply chains across multiple geographies.
United States
FDA clearance pathways for clinical-grade wearables drive hospital system procurement of magnetometer-enhanced gait analysis devices. The agency's software-as-medical-device classifications reshape liability frameworks for integrated sensor-fusion algorithms. Post-surgical recovery protocols in Texas and California medical centers expand remote patient monitoring sensor volume.
Germany
EU Medical Device Regulation tightens accuracy requirements for clinical-grade wearables entering hospital procurement channels. ISO 13485 certification serves as a baseline filter for tender participation across German hospital networks. Munich and Stuttgart anchor concentrated demand for ergonomic workplace wearables serving automotive manufacturing rehabilitation contracts.
China
MEMS foundry capacity constraints in East Asia create supply bottlenecks for surface-mount accelerometer packages during demand surges. NMPA medical device regulations establish parallel validation requirements for clinical-grade wearable distribution. Yangtze River Delta fabrication clusters supply consumer electronics OEMs with baseline fitness tracker configurations.
Japan
PMDA neurological rehabilitation device approvals enable premium pricing tiers for magnetometer arrays in Parkinson's disease progression monitoring. METI industrial technology programs support workplace ergonomic wearable development for aging workforce applications. Kanto region rehabilitation clinics adopt laboratory-grade motion capture alternatives using wearable sensor arrays.
Netherlands
EMA-coordinated EU Medical Device Regulation implementation fragments vendor qualification pathways for transatlantic distribution. Rehabilitation clinics adopt objective assessment protocols using magnetometer-enhanced gait analysis systems. Eindhoven region health technology clusters concentrate sensor-fusion algorithm development for clinical movement science applications.
Wearable Motion Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized clinical certification pathways to differentiate positioning. The vendor base stratifies between MEMS fabrication scale leaders and quality-management-certified specialists serving hospital procurement. Three archetypes dominate: foundry-scale fabricators with ISO 13485 compliance, consumer electronics-anchored volume suppliers, and clinical-grade algorithm developers. Competitive moves concentrate on strategic partnerships with fitness device OEMs and geographic expansion into German industrial rehabilitation clusters.
Among European MEMS specialists, STMicroelectronics, Bosch Sensortec, and Infineon Technologies occupy positions spanning consumer volume and clinical certification tiers. STMicroelectronics represents the foundry-scale archetype capable of serving hospital system tenders. Bosch Sensortec exemplifies direct OEM partnership models anchoring consumer wearable supply chains. Infineon Technologies sits within the industrial-automotive crossover segment supplying Munich-Stuttgart workplace ergonomic applications.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Texas Instruments |
| Infineon Technologies |
| Bosch Sensortec |
| NXP Semiconductors |
| Panasonic Corporation |
| TE Connectivity |
| Murata Manufacturing |
| Others |
Value Network & Pricing Analysis
EU MDR compliance mandates gate both qualified supply and premium-tier pricing access, bifurcating vendor participation between ISO 13485-certified fabricators serving hospital procurement and uncertified suppliers locked into consumer electronics channels. Magnetometer-enhanced gait analysis systems command substantial premiums in neurological rehabilitation, while baseline accelerometer configurations face relentless cost compression in fitness tracker OEM tenders.
Pricing Analysis
Volume concentrates in sub-dollar accelerometer units for fitness trackers, while margins accumulate in magnetometer-array systems for clinical gait analysis. Three-tier pricing structure separates FDA-cleared clinical devices from wellness-designated wearables and economy fitness components, with ISO 13485 certification as the primary price differentiation driver. Cost compression in consumer tiers intensifies because foundry capacity constraints in East Asia force allocation decisions toward higher-margin hospital contracts. Sports and gaming segments exhibit highest price sensitivity; post-surgical rehabilitation programs show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for fitness tracker accelerometers, while authorized distributor networks serve fragmented rehabilitation device manufacturers. MEMS fabrication concentrates in Taiwan, South Korea, and China's Yangtze River Delta, drawing from silicon wafer substrates, specialized packaging materials, and precision etching equipment. Single-source vulnerability in 3 mm surface-mount package supply creates bottlenecks during demand surges. Distribution runs through tier-one electronics distributors for consumer volumes and direct hospital system contracts for clinical-grade tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-fusion algorithms are displacing single-axis accelerometer architectures, compressing development timelines for vendors caught with legacy product portfolios.
For Market Incumbents: Deploy ISO 13485 certification as a competitive moat against emerging MEMS fabricators lacking hospital procurement access. Accelerate backward integration into specialized packaging capabilities to reduce dependency on East Asian foundry allocation decisions. Magnetometer array complexity from emerging clinical entrants threatens premium positioning; counter by deepening algorithm validation partnerships with German rehabilitation networks. For New Entrants and Emerging Players: Hospital GPO contracts represent the most penetrable channel for clinical-grade sensor vendors without established OEM relationships. Target Dutch neurological rehabilitation clinics adopting objective gait assessment protocols as beachhead accounts. Pursue white-label manufacturing arrangements with industrial ergonomic wearable developers in the Munich-Stuttgart automotive cluster to bypass direct certification burdens. For Investors and Strategic Acquirers: FDA software-as-medical-device clearance announcements are the leading indicator that algorithm-centric vendors will capture disproportionate clinical revenue share. Five-to-ten year viability favors acquirers of ISO 13485-certified fabricators with dormant magnetometer IP portfolios. Watch for PMDA neurological device approvals in Japan as signal that premium-tier pricing will sustain across Asian rehabilitation markets.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks German hospital network tenders and GPO contract eligibility. |
| Magnetometer Array Development | Captures Parkinson's disease monitoring revenue in Dutch rehabilitation clinics. |
| FDA Software-as-Medical-Device Submission | Reshapes liability frameworks for integrated sensor-fusion algorithm vendors. |
| Direct OEM Partnership Expansion | Anchors volume commitments for accelerometer baseline configurations. |
| East Asian Foundry Diversification | Mitigates single-source risk in 3 mm surface-mount package supply. |
Research Methodology
Document review covered SEC filings from MEMS fabricators, EU MDR technical documentation databases, and FDA 510(k) clearance records, complemented by interviews with biomedical engineers, hospital procurement committee members, GPO contracts managers, and rehabilitation clinic directors. Secondary validation drew from customs trade data for sensor component flows, ISO certification registries, and hospital tender announcement databases. Bottom-up sensor shipment estimates triangulated against top-down wearable device production forecasts.
Cross-referencing historical pricing trajectories of accelerometer and magnetometer components against panel input from procurement executives anchored volume and value outputs across the modeling period. Segmentation dimensions modeled include device type, sensor technology, end-user industry, application purpose, and regional regulatory cluster. CAGRs were synthesized from foundry capacity expansion announcements, hospital RPM program adoption curves, and automotive ergonomic wearable deployment timelines in German manufacturing.
Caveats apply where FDA software-as-medical-device reclassifications, EU MDR implementation delays, or East Asian foundry supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding sustained hospital procurement committee certification requirements and continued automotive cluster demand concentration. Periodic stress-testing of base assumptions against foundry utilization rates and regulatory guidance document releases is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Smart Sports Bracelet Market