
 Global GPS Watch Tracker Market | 2026-2036
Global GPS Watch Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Global GPS Watch Tracker Market Analysis
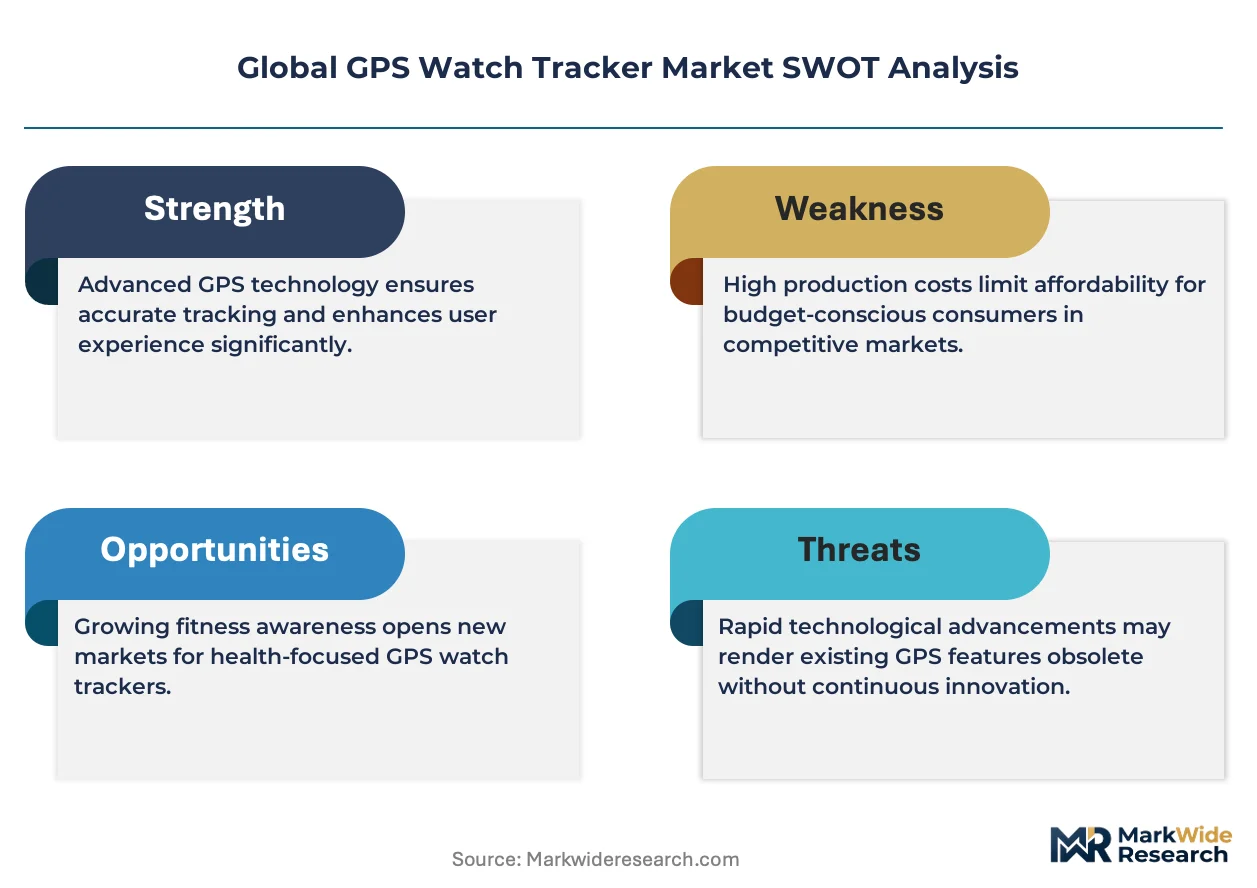
The EU AI Act is restructuring the cost-of-entry calculus for GPS-enabled wearables by imposing algorithmic transparency requirements on health data processing. Garmin leverages its in-house chipset design to sustain margin control across premium and mid-tier lines. Apple dominates consumer mindshare through vertical ownership of hardware, software, and health services. Samsung competes by anchoring its Galaxy Watch ecosystem within the broader Android device universe.
A GPS watch tracker integrates multi-constellation satellite receivers, inertial measurement units, and biometric sensors into a wrist-worn form factor, transmitting location and physiological data via Bluetooth, Wi-Fi, or cellular modems for navigation, activity logging, and emergency alerting. Smartwatches lead the product type landscape by absorbing functions from dedicated fitness trackers and sports watches into unified platforms. Fitness trackers retain volume strength in entry-level pricing bands across Asia-Pacific markets. Cellular connectivity represents the fastest-growing technology segment as consumers seek untethered emergency and live-tracking capabilities independent of paired smartphones.
FCC certification governs radio frequency emissions for devices sold in the United States, while CE marking and the EU Green Deal shape material sourcing and recyclability mandates across European markets. Japan's METI enforces battery safety standards that constrain cell chemistry choices and supplier qualification timelines. Stakeholders must monitor evolving interoperability requirements between proprietary health platforms and national electronic health record systems as regulators push for data portability.
Market Dynamics
Cellular-enabled GPS watches are compressing the traditional smartphone tether, forcing chipset vendors to requalify modems for wrist-worn thermal constraints and battery envelopes that diverge sharply from handset specifications.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Health data processing requirements are accelerating investment in on-device inference engines that reduce cloud dependency for biometric analytics.
- Enterprise wellness program expansion:Self-insured employers in the United States are subsidizing GPS watch deployments for workforce cardiovascular monitoring and location-based safety protocols.
- Multi-constellation receiver integration:Simultaneous GPS, GLONASS, Galileo, and BeiDou tracking is improving fix accuracy in urban canyon environments where single-system wearables fail.
Market Restraints
- Lithium-polymer cell chemistry constraints:Japan's METI battery safety standards extend supplier qualification timelines by 8-14 months for high-density cells required by cellular models.
- GNSS chipset supply concentration:Three vendors control 80% of low-power receiver silicon, creating allocation risk during smartphone demand surges.
- Smartphone substitution pressure:Handset-based location logging and health apps satisfy casual users without dedicated hardware expenditure.
Strategic Opportunities
- India PLI scheme for wearables:Manufacturing incentives are attracting assembly investment for export-oriented production serving Middle East and African markets.
- Ambient health monitoring convergence:Integration of continuous glucose monitoring patches with GPS watches creates diabetes management platforms for aging populations in Germany and Japan.
- Direct-to-consumer telehealth bundling:Subscription models pairing hardware with remote physician access are bypassing traditional retail markup structures.
Industry Challenges
- RF engineering talent scarcity:Compact antenna design for cellular modems in metal-cased watches requires expertise concentrated among semiconductor vendors and aerospace contractors.
- Interoperability certification backlog:FCC Part 15 and Part 27 testing queues for new cellular SKUs extend time-to-revenue by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GPS Watch Tracker Market |
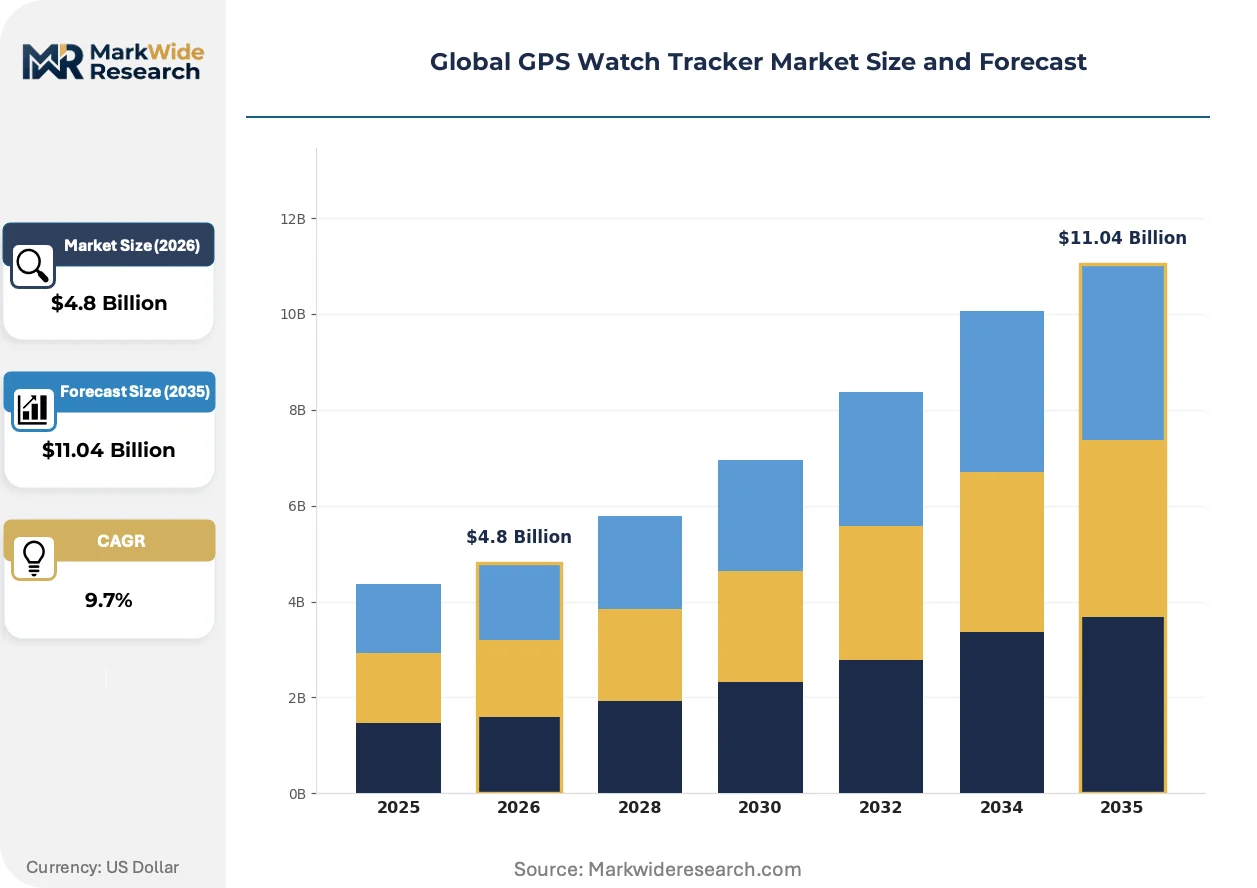
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Sports Watches, Hybrid Watches Technology: Bluetooth, GPS, Wi-Fi, Cellular Customer Type: Fitness Enthusiasts, Athletes, Casual Users, Seniors End User: Individuals, Corporate Users, Health Institutions, Educational Institutions |
| Companies Covered | Starmax, COROS, Garmin, Amazfit, Samsung, Apple, Polar, Concox (Jimi IoT), Suunto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GPS Watch Tracker Market Emerging Trajectories
Dual-frequency GNSS reception and on-device machine learning inference are converging to enable meter-level positioning without network assistance, compressing the performance gap between consumer wearables and professional survey equipment.
Dual-band L1/L5 GNSS reception is rewriting accuracy expectations for wrist-worn navigation. Marathon training communities and alpine rescue coordinators are adopting these receivers faster than general fitness demographics. The technology is compressing addressable market boundaries between consumer GPS watches and dedicated outdoor navigation units.
REACH substance restrictions and the EU Green Deal circular economy mandates are forcing redesigns of watch housings and circuit boards. Manufacturers must document recycled content percentages and eliminate specific flame retardants by specified phase-out windows. Premium product lines targeting German and French consumers are responding with modular designs enabling battery and display replacement.
Employer-sponsored wellness procurement is consolidating buying decisions away from individual consumers. Benefits administrators in the United States are negotiating fleet pricing and data portability terms directly with platform operators, displacing retail channel volume for corporate segments. This concentration is most visible among Fortune 500 self-insured plans with active safety-critical workforce populations.
Global GPS Watch Tracker Market Segmentation
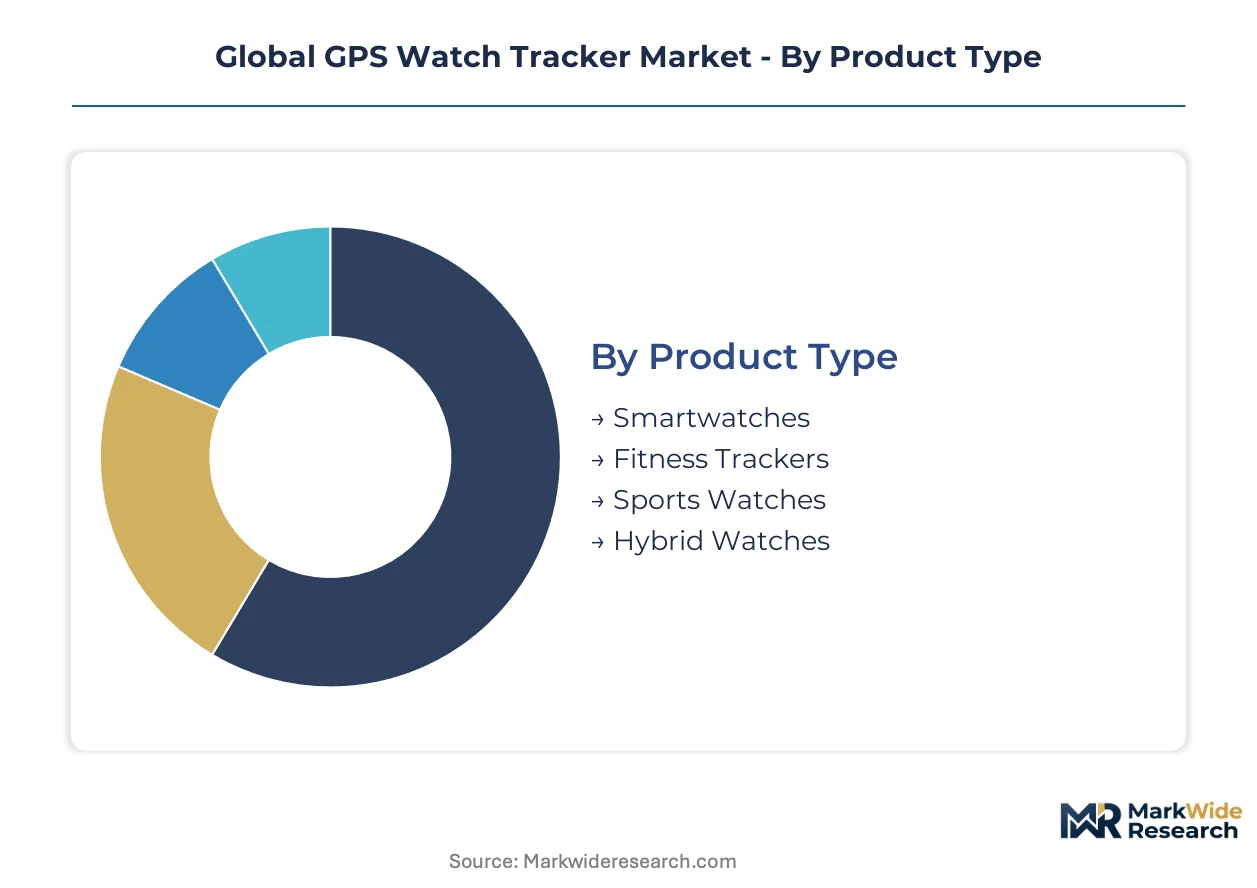
Segmentation in GPS watch trackers reveals how hardware specifications, connectivity architectures, and user profiles reshape procurement economics. Manufacturers must align chipset investments against distinct thermal, battery, and certification requirements that vary sharply across these divides.
Product Type:
Form factor and functional integration define how satellite receivers, biometric sensors, and display modules combine into wrist-worn devices.
- Smartwatches:Unified platforms absorb functions from dedicated fitness trackers and sports watches, combining multi-constellation GNSS with cellular modems and app ecosystems. Demand concentrates among corporate wellness programs in the United States where employers subsidize fleet deployments for workforce cardiovascular monitoring and location-based safety protocols.
- Fitness Trackers:Stripped-down devices prioritize step counting, sleep staging, and basic GPS logging within constrained battery envelopes. Volume strength persists in entry-level pricing bands across India and Southeast Asia where first-time wearable adoption outpaces replacement cycles.
- Sports Watches:Purpose-built units emphasize barometric altimeters, breadcrumb navigation, and extended battery life for ultramarathon and alpine environments. German and Austrian outdoor retailers report strongest sell-through among mountain rescue volunteers and trail running clubs.
- Hybrid Watches:Analog-digital hybrids embed GPS receivers beneath traditional watch faces, targeting fashion-conscious professionals in France and Italy who resist full-screen smartwatch aesthetics.
Smartwatches lead on scale; sports watches lead on momentum among specialized athletic communities.
Technology:
Connectivity architecture determines whether devices operate tethered to smartphones or as independent communication nodes.
- Bluetooth:Low-energy protocols enable smartphone-tethered data sync with minimal power draw. Remains dominant in Japan's senior monitoring applications where paired caregiver apps reduce cellular subscription burdens on fixed-income users.
- GPS:Single- or dual-frequency satellite receivers provide location fixes without network assistance. Multi-constellation integration combining GPS, GLONASS, Galileo, and BeiDou is climbing the fastest in urban canyon environments across China and South Korea.
- Wi-Fi:Auxiliary connectivity enables firmware updates and cloud sync when within range of known networks. Health institutions in Germany deploy Wi-Fi-preferred modes to reduce electromagnetic exposure in clinical settings.
- Cellular:Embedded modems permit emergency alerting and live tracking without smartphone pairing. FCC Part 27 certification queues and METI battery safety standards constrain supplier qualification timelines for this expanding category.
Bluetooth dominates installed base; cellular gains share fastest as untethered use cases proliferate.
Customer Type:
User sophistication and physiological monitoring intensity segment demand across pricing tiers and feature prioritization.
- Fitness Enthusiasts:Amateur athletes demand VO2 max estimation, training load balance, and recovery metrics. These users drive replacement cycles in Australia and New Zealand where Strava-integrated social features influence purchase decisions.
- Athletes:Professional and competitive amateurs require lactate threshold detection, running power measurement, and course navigation. This segment commands premium pricing in Norway and Switzerland where national ski federations distribute subsidized units to developmental athletes.
- Casual Users:Step counters and notification mirroring satisfy basic needs without specialized sensor arrays. Price sensitivity concentrates volume in Brazil and Mexico through retail installment plans.
- Seniors:Fall detection, geofenced wandering alerts, and simplified interfaces address aging demographics. Japan's municipal governments procure these units for dementia care programs under METI-directed technology adoption subsidies.
Casual users anchor volume; athletes generate steepest expansion trajectory through performance-tier hardware upgrades.
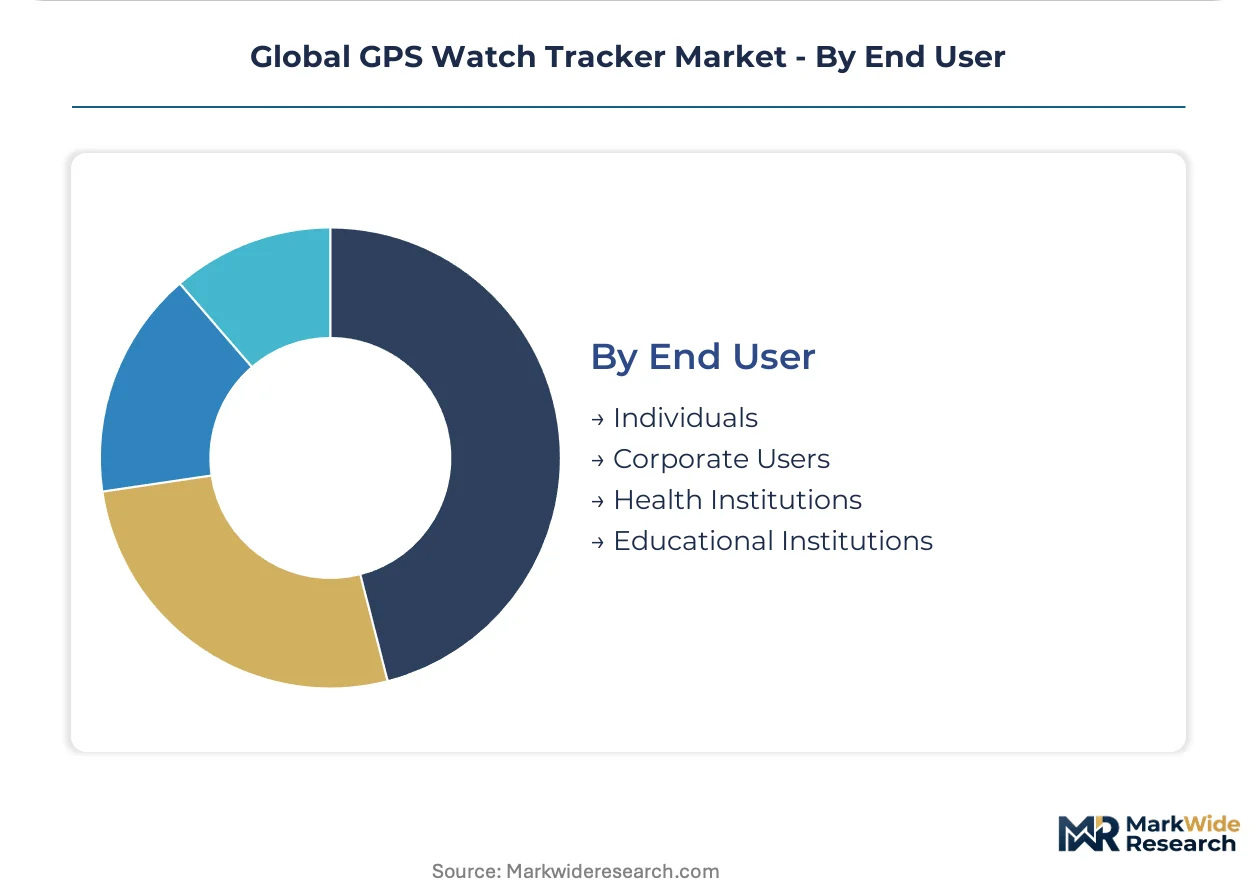
End User:
Purchasing authority and data governance requirements differentiate consumer, enterprise, and institutional deployment patterns.
- Individuals:Direct consumers select devices based on brand ecosystem lock-in and health platform interoperability. Retail channel concentration in the United States and Germany favors established app store integrations.
- Corporate Users:Self-insured employers negotiate fleet pricing and data portability terms directly with platform operators. Fortune 500 safety-critical workforces in oilfield services and logistics drive this segment's procurement consolidation.
- Health Institutions:Hospitals and clinics require HIPAA-compliant data handling and EHR interoperability. Pilot programs in Denmark and the Netherlands test continuous glucose monitoring patch integration for diabetes management platforms.
- Educational Institutions:University athletic departments and K-12 systems deploy location-aware devices for student-athlete welfare and campus safety. Procurement runs through state-level cooperative purchasing agreements in Texas and California.
Individuals dominate unit shipments; corporate users reshape pricing through consolidated benefits administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Shenzhen, Seoul, and Dallas anchor the GPS watch tracker's hardware development geography. These concentrations shape where multi-constellation receiver silicon gets qualified for wrist-worn thermal constraints.
United States
Enterprise wellness program subsidies from self-insured employers drive fleet procurement for workforce cardiovascular monitoring. FCC Part 15 and Part 27 certification queues extend time-to-revenue for new cellular SKUs by 4-6 months. Dallas-Fort Worth hosts RF engineering contractors specializing in compact antenna design for metal-cased watches.
Germany
Mountain rescue volunteers and trail running clubs generate premium demand for barometric altimeter-equipped sports watches. REACH substance restrictions and EU Green Deal circular economy mandates force housing redesigns with documented recycled content. Bavarian outdoor retailers report strongest sell-through among alpine sports federations distributing subsidized units.
China
Urban canyon environments across Beijing and Shanghai accelerate multi-constellation receiver adoption combining GPS, GLONASS, Galileo, and BeiDou. MIIT enforces GB standards for radio transmission that diverge from FCC and CE specifications. Shenzhen's electronics corridor concentrates assembly investment for export-oriented production serving Middle East and African markets.
Japan
Municipal dementia care programs under METI-directed technology adoption subsidies procure senior-focused devices with fall detection and geofenced wandering alerts. METI battery safety standards extend supplier qualification timelines by 8-14 months for high-density lithium-polymer cells. Tokyo's precision component vendors constrain cell chemistry choices through extended qualification protocols.
Australia
Strava-integrated social features influence replacement cycles among amateur athletes demanding VO2 max estimation and training load metrics. TGA oversight applies to devices claiming clinical-grade biometric accuracy. Melbourne and Sydney host the Asia-Pacific headquarters for platform operators negotiating data portability terms with benefits administrators.
Global GPS Watch Tracker Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans three strategic archetypes: vertically integrated platform operators controlling hardware-software-service stacks, component specialists supplying multi-constellation receiver silicon, and regional assemblers leveraging India PLI manufacturing incentives. M&A activity concentrates on RF engineering talent acquisition, while portfolio diversification targets ambient health monitoring convergence.
Within the platform operator tier, Garmin and Apple exemplify divergent margin architectures. Garmin's in-house chipset design sustains margin control across premium and mid-tier lines. Apple's vertical ownership of hardware, software, and health services dominates consumer mindshare. Samsung anchors the Android-aligned ecosystem tier through Galaxy Watch integration with broader device universes.
| Leading Market Players |
|---|
| Starmax |
| COROS |
| Garmin |
| Amazfit |
| Samsung |
| Apple |
| Polar |
| Concox (Jimi IoT) |
| Suunto |
| Others |
Supply Flow & Price Mechanics
Captive chipset design anchors both supply security and pricing power for vertically integrated platform operators. Garmin's in-house receiver silicon insulates premium sports watch lines from GNSS module allocation shocks, while outsourced modem sourcing exposes mid-tier competitors to FCC Part 27 certification queues that compress margins through extended time-to-revenue cycles.
Pricing Analysis
Bundled hardware-subscription splits are reshaping procurement economics across corporate wellness and direct-to-consumer telehealth channels. Three-tier pricing structure across premium, standard, and economy levels separates cellular-enabled flagship units from Bluetooth-tethered mid-range devices and entry-level fitness trackers. Cost compression in the cellular tier is intensifying because METI battery safety standards extend supplier qualification timelines. Casual users in Brazil and Mexico exhibit highest price sensitivity, while enterprise benefits administrators negotiate fleet pricing with reduced per-unit elasticity.
Supply Chain Analysis
Low-power GNSS receiver silicon rests on design houses concentrated in Taiwan, South Korea, and the United States. Lithium-polymer cell chemistry, compact antenna substrates, and multi-constellation baseband processors feed assembly operations in Shenzhen and Dongguan. Single-source vulnerability concentrates in cellular modem qualification, where three vendors control dominant share of wrist-worn thermal-optimized SKUs. Distribution runs through enterprise benefits administrators, outdoor specialty retailers, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act functions as a regulatory compounder, mandating algorithmic transparency for health data processing that accelerates investment in on-device inference engines and reshapes procurement priorities among enterprise wellness programs.
For Market Incumbents: Lock in RF engineering talent clusters through targeted acquisition of Dallas-Fort Worth antenna design contractors and Shenzhen multi-constellation receiver teams. Deepen backward integration into lithium-polymer cell qualification protocols to bypass METI timeline constraints. Defensive positioning requires pre-emptive certification investment for dual-frequency L1/L5 GNSS reception ahead of alpine rescue and marathon training community adoption curves.
For New Entrants and Emerging Players: Enterprise benefits administrators represent the most penetrable channel partner type for bypassing retail markup structures. White-space targets concentrate in India PLI scheme assembly for Middle East and African export markets, and ambient health monitoring convergence pairing continuous glucose monitoring patches with GPS-enabled platforms. Direct-to-consumer telehealth bundling offers the cleanest go-to-market angle for subscription-based revenue models.
For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering talent scarcity intersects with FCC certification backlogs that extend time-to-revenue. Long-term viability favors platform operators with captive chipset design and health services integration over pure-play hardware assemblers. Acquisition target archetypes include modular design specialists enabling EU Green Deal-compliant battery replacement programs. Watch dual-frequency GNSS adoption rates among mountain rescue federations as inflection indicator for premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Device Inference Engine Development | EU AI Act compliance reduces cloud dependency for biometric analytics processing. |
| Dual-Frequency GNSS Receiver Integration | L1/L5 reception compresses accuracy gap with professional survey equipment. |
| Cellular Modem Thermal Optimization | Wrist-worn form factors diverge sharply from handset battery envelopes. |
| Modular Design for Circular Economy | REACH mandates force documented recycled content and battery replacement capability. |
| Enterprise Wellness Fleet Procurement | Fortune 500 benefits administrators negotiate direct platform operator contracts. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combining executive interviews with RF engineering contractors, benefits administrators at self-insured employers, and outdoor specialty retail buyers. Secondary validation draws from FCC equipment authorization databases, METI battery safety standard filings, EU AI Act implementation guidance, and GNSS receiver vendor technical documentation. Bottom-up unit shipment estimates triangulate against top-down consumer electronics expenditure data.
Granularity-level modeling disaggregates volume and value across product type, connectivity architecture, customer sophistication tier, and purchasing authority segment throughout the forecast period. CAGRs derive from segment-specific adoption curves weighted by regulatory milestone timing and enterprise procurement cycle phasing. Industry-specific inputs include cellular modem certification queue durations, lithium-polymer cell qualification timelines, and multi-constellation receiver silicon allocation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement calibration, METI battery chemistry rule evolution, and GNSS chipset vendor concentration dynamics. Forecasts reflect assumptions around enterprise wellness program subsidy continuity and ambient health monitoring patch integration timelines. A small set of named triggers warrants ongoing watch: dual-frequency GNSS price parity thresholds, India PLI scheme capacity ramp schedules, and FCC Part 27 testing queue clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Stress Tracking Devices Market