
 Global Blood Flow Restriction Band Market | 2026-2036
Global Blood Flow Restriction Band Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Flow Restriction Band Market Foresight
The blood flow restriction band market is rebalancing between pneumatic systems with digital pressure monitoring and basic elastic straps sold through sporting goods channels. KAATSU Global Inc. leverages proprietary cycle training protocols to anchor premium positioning in athletic facilities. Delfi Medical Innovations Inc. sustains clinical credibility through FDA-registered pneumatic devices used in post-surgical rehabilitation settings. B Strong competes on portability with a handheld pump design that targets home users and traveling athletes.
Blood flow restriction bands are inflatable or elastic cuffs applied to proximal limbs that reduce venous return while maintaining arterial inflow, typically operating at pressures between 50 and 200 mmHg depending on limb circumference and systolic blood pressure; their primary purpose is to induce muscular hypertrophy and strength adaptations at submaximal loads. Pneumatic bands capture the dominant margin pool due to precise pressure control required in physiotherapy clinics, while elastic bands represent the highest volume growth channel through online retailers serving home-based strength conditioning programs. Velcro straps retain relevance in orthopedic clinics where quick application protocols matter more than pressure granularity.
FDA Class I device regulations govern pneumatic band claims in the United States, while the EU Medical Device Regulation requires CE marking for clinical-grade occlusion systems sold through healthcare providers in Germany and France. Japan's Ministry of Health, Labour and Welfare evaluates blood flow restriction devices under existing physical therapy equipment frameworks, creating divergent approval timelines across major demand centers. Stakeholders must monitor reimbursement code expansions and pressure calibration standards as clinical evidence accumulates for specific patient populations.
Market Dynamics
Pneumatic occlusion systems with integrated digital pressure monitoring are compressing margins for basic elastic strap manufacturers while simultaneously expanding the addressable market into post-surgical rehabilitation settings.
Growth Catalysts
- Collegiate Athletic Programs:NCAA Division I strength departments are mandating certified pneumatic systems for athlete safety protocols, creating institutional procurement pipelines.
- CE Marking Pathway:The EU Medical Device Regulation's streamlined Class I accessory classification is reducing time-to-market for clinical-grade occlusion devices in Germany and France.
- Rehabilitation Reimbursement:Physical therapy billing codes in Japan are expanding coverage for blood flow restriction therapy under existing Ministry of Health, Labour and Welfare frameworks.
Market Restraints
- Silicone Bladder Supply Concentration:Medical-grade pneumatic bladder manufacturing concentrates among three East Asian component suppliers, creating input vulnerability.
- Pressure Calibration Liability:FDA documentation requirements for Class I device pressure claims are extending product development timelines and legal exposure.
- Home Fitness Substitution:Basic resistance band systems and bodyweight training apps capture price-sensitive consumers seeking low-cost hypertrophy alternatives.
Strategic Opportunities
- Home-Based Clinical Monitoring:Telehealth-integrated pneumatic bands with remote pressure logging address the post-operative patient segment outside facility walls.
- Geriatric Sarcopenia Protocols:Japan's aging population and established physical therapy infrastructure position the market for prescription-based home deployment.
- Convergence with Wearable Biometrics:Integration of occlusion pressure data with continuous glucose monitors and HRV sensors creates differentiated premium positioning.
Industry Challenges
- Certified Pressure Technician Shortage:Clinical facilities lack personnel trained in limb occlusion pressure calculation protocols, limiting safe expansion.
- Legacy EMR Integration:Pneumatic device data streams require custom API development to interface with established electronic medical record systems.
- Patent Thicket Navigation:Proprietary cycle training and rapid inflation algorithms create licensing complexity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Flow Restriction Band Market |
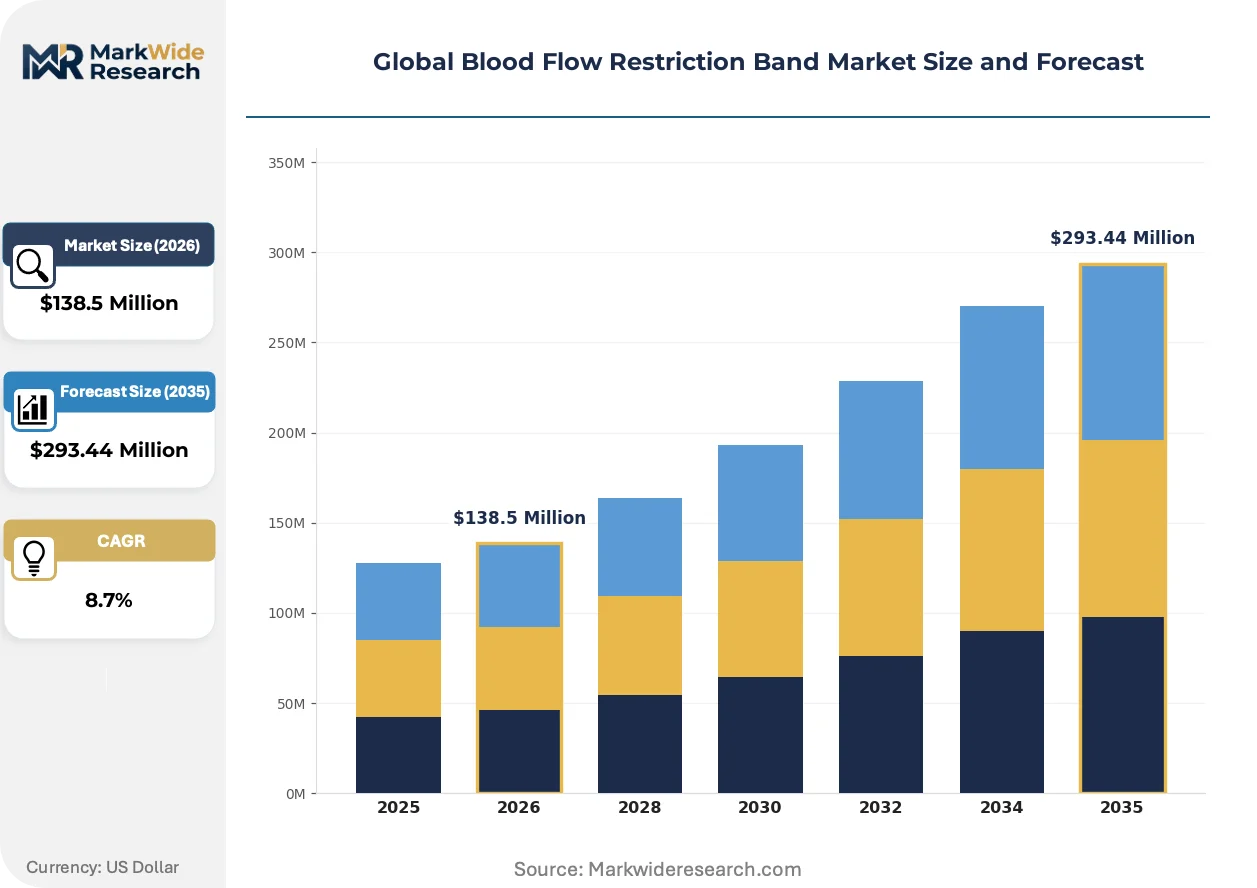
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $293.44 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bands, Pneumatic Bands, Velcro Straps, Adjustable Cuffs, Neoprene Bands Application: Physical Therapy, Sports Training, Post-Surgical Rehabilitation, Strength Conditioning, Injury Recovery End User: Physiotherapy Clinics, Athletic Facilities, Wellness Centers, Orthopedic Clinics, Home Users Distribution Channel: Online Retailers, Specialty Medical Stores, Sporting Goods Stores, Healthcare Providers, Direct Sales |
| Companies Covered | KAATSU Global Inc., Delfi Medical Innovations Inc., B Strong, Saga Fitness, Fit Cuffs, EDGE Mobility System, Smart Tools Plus, Occlusion Cuff, Iron Bull Strength, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Flow Restriction Band Market Shifts & Advancements
Real-time pressure telemetry and automated limb occlusion pressure algorithms are transforming pneumatic bands from passive tools into connected therapeutic devices, compressing the gap between clinical precision and consumer accessibility.
Microelectromechanical pressure sensors embedded within pneumatic bladder walls is electrifying the competitive landscape by enabling continuous digital feedback loops previously available only in hospital-grade Doppler systems. Collegiate athletic trainers and outpatient physical therapy chains are adopting these sensor-integrated bands at replacement-cycle speeds of eighteen to twenty-four months. The technology is electrifying demand for subscription-based calibration services and cloud-based treatment logging platforms that lock users into recurring revenue relationships.
The FDA's tightening documentation requirements for Class I medical device pressure calibration claims are extending development cycles and legal review costs for manufacturers seeking clinical credibility. This regulatory friction is compressing the supplier base toward established pneumatic device specialists with existing quality management systems. Post-surgical rehabilitation settings in the United States are responding by consolidating procurement around FDA-registered suppliers and demanding indemnification clauses for pressure-related adverse events.
Direct-to-consumer subscription models bundling pneumatic hardware with remote coaching protocols are displacing traditional sporting goods retail channels for home-based strength conditioning. Athletic performance facilities and traveling professional athletes are driving demand for portable systems with handheld pumps and travel cases. Germany and Japan exhibit the strongest channel migration, where reimbursement-adjacent home therapy markets reward ongoing digital engagement over one-time equipment sales.
Global Blood Flow Restriction Band Market Segmentation
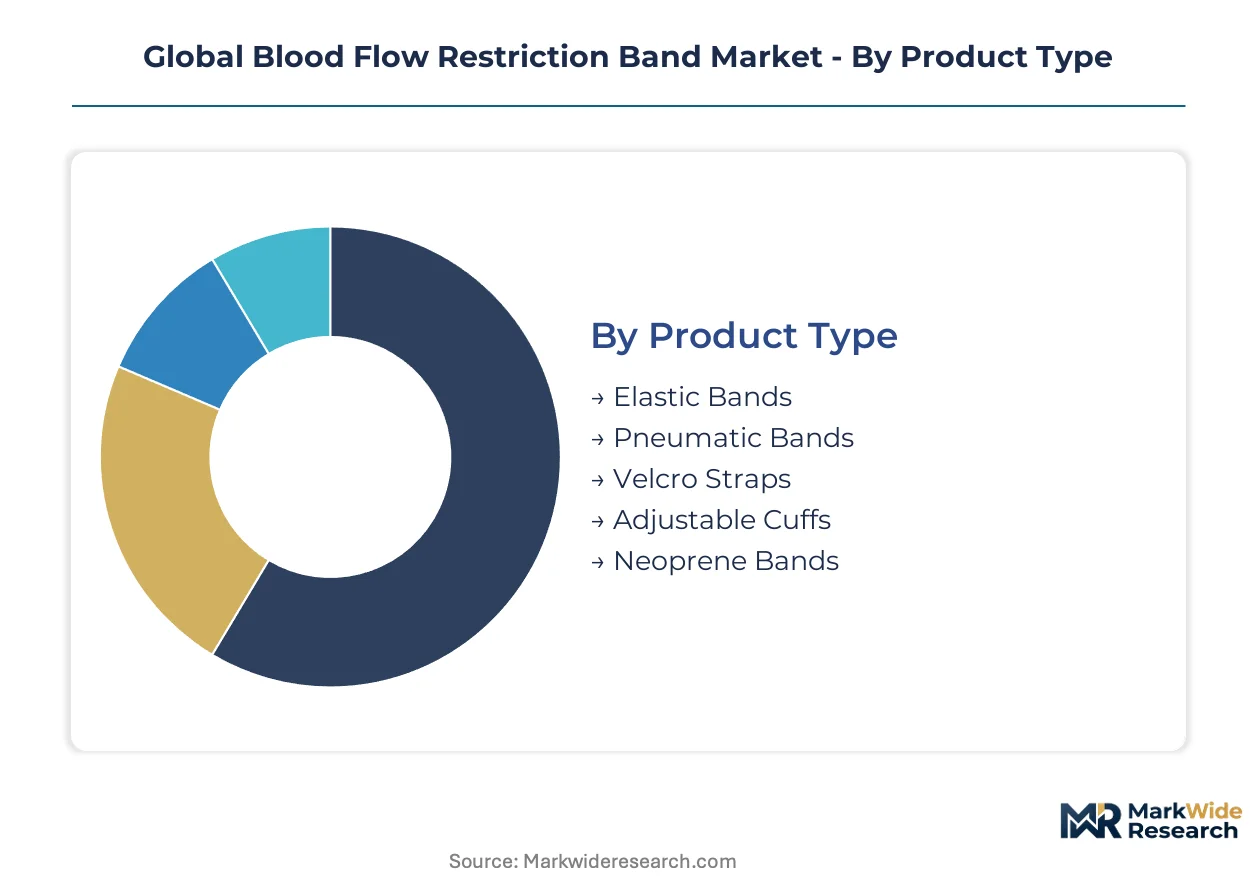
Blood flow restriction bands fragment across pressure technology, clinical setting, and buyer sophistication. Segmentation reveals where pneumatic precision commands premium pricing versus where elastic simplicity drives volume scale.
Product Type:
Elastic bands dominate unit volume through sporting goods channels while pneumatic systems capture margin in clinical procurement.
- Elastic Bands:Fabricated from natural rubber latex or synthetic polymer blends with calibrated resistance ratings. Demand concentrates in United States home fitness segments where price-sensitive consumers prioritize portability over pressure precision. Resistance band substitution and bodyweight app proliferation constrain pricing power in this tier.
- Pneumatic Bands:Constructed with medical-grade silicone bladders and microelectromechanical pressure sensors enabling real-time limb occlusion pressure monitoring. Demand concentrates in German and Japanese physiotherapy clinics where CE marking and reimbursement codes validate clinical-grade claims. FDA documentation requirements for Class I device pressure calibration extend development timelines and compress the supplier base toward established specialists.
- Velcro Straps:Hook-and-loop fastening systems with graduated compression markings for rapid limb application.
- Adjustable Cuffs:Ratchet or cam-lock mechanisms accommodating variable limb circumferences without bladder inflation.
- Neoprene Bands:Closed-cell synthetic rubber construction providing thermal insulation alongside occlusion function.
Today's leader: Pneumatic Bands. Tomorrow's challenger: Elastic Bands.
Application:
Post-surgical protocols generate the steepest reimbursement tailwinds while sports training absorbs the highest absolute unit volume.
- Physical Therapy:Clinician-supervised protocols for musculoskeletal rehabilitation requiring documented pressure parameters for insurance billing. Japanese Ministry of Health, Labour and Welfare frameworks are expanding coverage eligibility, anchoring demand in aging population centers.
- Sports Training:Collegiate and professional athletic programs mandating certified pneumatic systems for safety compliance. NCAA Division I strength departments institutionalize procurement pipelines with eighteen-to-twenty-four-month replacement cycles.
- Post-Surgical Rehabilitation:Orthopedic recovery protocols following joint replacement or ligament reconstruction procedures.
- Strength Conditioning:Hypertrophy-focused programming at submaximal loads for muscle preservation.
- Injury Recovery:Acute phase management of soft tissue trauma with modified loading parameters.
Clinical applications command pricing premiums; consumer fitness applications scale through volume.
End User:
Procurement authority separates institutional buyers with compliance mandates from discretionary individual purchasers.
- Physiotherapy Clinics:Reimbursement-dependent facilities requiring FDA-registered or CE-marked devices with indemnification clauses for pressure-related adverse events. United States consolidation around registered suppliers intensifies vendor qualification requirements.
- Athletic Facilities:Performance centers and collegiate training rooms with certified athletic trainer oversight.
- Wellness Centers:Commercial fitness operations integrating blood flow restriction into group training formats.
- Orthopedic Clinics:Surgeon-directed post-operative protocols with direct-to-patient equipment dispensing.
- Home Users:Individual consumers purchasing through Amazon, brand-direct websites, or sporting goods retailers.
Institutional buyers dominate pneumatic procurement; home users drive elastic band velocity.
Distribution Channel:
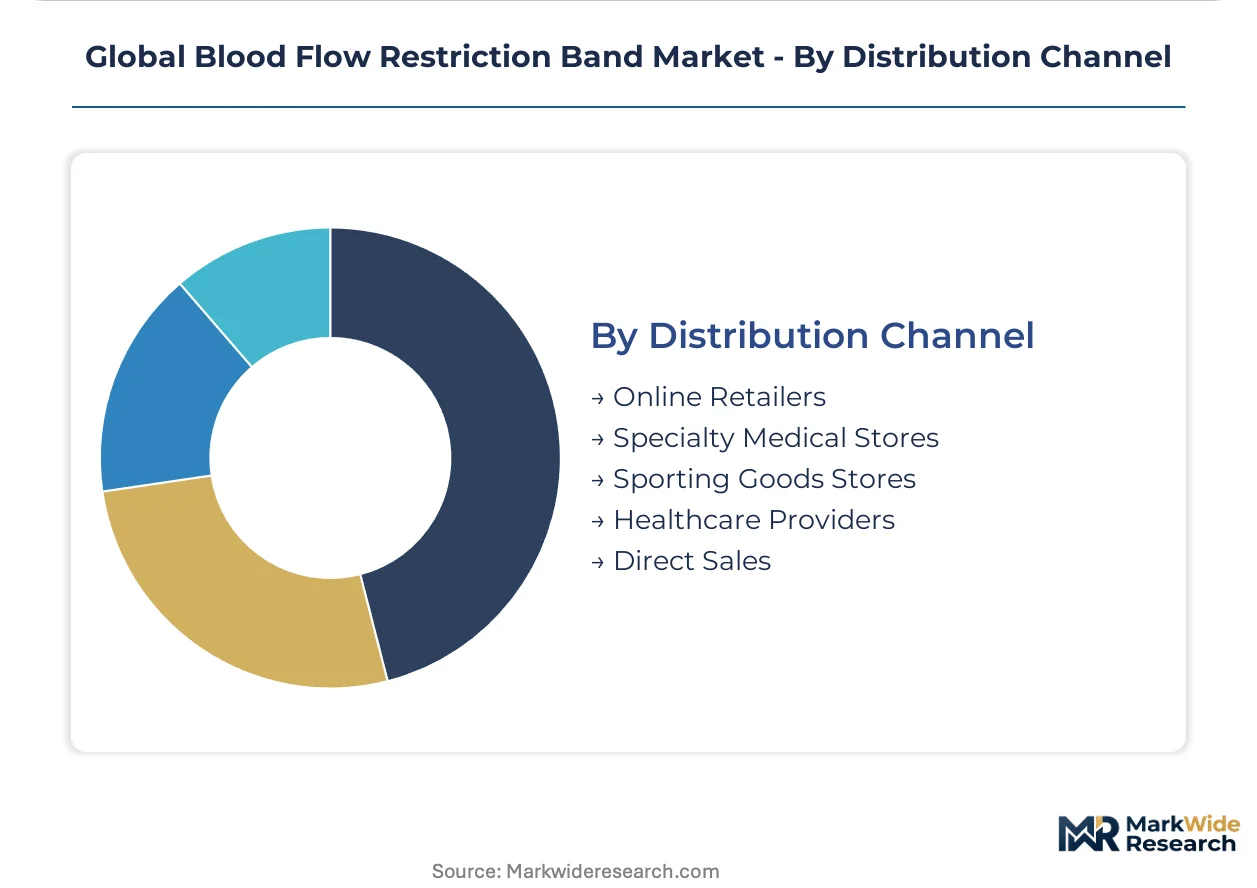
Channel selection reflects buyer sophistication and reimbursement adjacency.
- Online Retailers:Amazon and direct-to-consumer brand sites capturing home user volume with subscription bundling of hardware and remote coaching protocols. Germany and Japan exhibit strongest channel migration where reimbursement-adjacent home therapy markets reward ongoing digital engagement.
- Specialty Medical Stores:Durable medical equipment suppliers serving outpatient clinic procurement with insurance billing support.
- Sporting Goods Stores:Dick's Sporting Goods and specialty fitness retailers stocking elastic bands for recreational strength training.
- Healthcare Providers:Hospital system purchasing cooperatives negotiating enterprise contracts for rehabilitation departments.
- Direct Sales:Manufacturer field representatives targeting collegiate athletic programs and physical therapy chains.
Digital channels scale fastest; healthcare provider relationships defend margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified athletic trainers and physical therapy specialists concentrate in the United States, Germany, and Japan, anchoring procurement demand for pneumatic occlusion systems with documented pressure protocols.
United States
NCAA Division I strength departments mandate certified pneumatic systems for athlete safety compliance, creating institutional procurement pipelines with eighteen-to-twenty-four-month replacement cycles. FDA Class I device regulations govern pressure calibration claims, extending development timelines for manufacturers seeking clinical credibility. Post-surgical rehabilitation settings in Texas and Florida consolidate procurement around FDA-registered suppliers demanding indemnification clauses.
Germany
Physiotherapy clinics in Bavaria and North Rhine-Westphalia drive demand for CE-marked clinical-grade occlusion systems with precise pressure monitoring capabilities. The EU Medical Device Regulation's streamlined Class I accessory classification reduces time-to-market for manufacturers targeting healthcare providers. Medical device clusters around Munich and Düsseldorf host specialized distributors serving outpatient rehabilitation chains with insurance billing support.
Japan
Aging population centers in Tokyo and Osaka generate prescription-based demand for home-deployable pneumatic systems targeting geriatric sarcopenia protocols. The Ministry of Health, Labour and Welfare evaluates devices under existing physical therapy equipment frameworks, expanding reimbursement eligibility for blood flow restriction therapy. Kanto region rehabilitation networks integrate telehealth-integrated bands with remote pressure logging for post-operative patients.
United Kingdom
Private physiotherapy chains in London and Manchester adopt pneumatic systems with digital pressure telemetry for musculoskeletal rehabilitation billing. MHRA regulations align with EU MDR transition timelines for clinical-grade device registration. Southeast England sports medicine facilities serve professional football and rugby programs with certified occlusion protocols.
Australia
Elite sports institutes in Sydney and Melbourne anchor demand for portable pneumatic systems with handheld pump designs targeting traveling athletes. TGA medical device frameworks require pressure calibration documentation for clinical-grade claims. Victorian and New South Wales physiotherapy networks expand adoption through subscription-based remote coaching bundling.
Global Blood Flow Restriction Band Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the blood flow restriction band market, with pneumatic system specialists maintaining dedicated quality management systems while elastic band distributors operate through sporting goods channels. The supplier base compresses toward established pneumatic device manufacturers as FDA documentation requirements extend development cycles. Three archetypes dominate: clinical-grade pneumatic specialists with FDA registration, portable consumer-focused brands with direct-to-consumer subscription models, and elastic band commodity producers serving price-sensitive home fitness segments. Strategic moves center on M&A consolidation of component suppliers and geographic expansion into reimbursement-adjacent home therapy markets.
Among pneumatic system specialists, KAATSU Global Inc. and Delfi Medical Innovations Inc. exemplify the clinical-credibility archetype through established regulatory registrations, while B Strong occupies a position within the portable consumer tier targeting home users and traveling athletes. These three entities represent divergent positioning strategies: the first two anchor institutional procurement through compliance-heavy documentation, while the third exemplifies asset-light distribution through digital subscription bundling. Saga Fitness and Fit Cuffs sit within the mid-market segment, bridging clinical precision and consumer accessibility without the capital intensity of full regulatory registration.
| Leading Market Players |
|---|
| KAATSU Global Inc. |
| Delfi Medical Innovations Inc. |
| B Strong |
| Saga Fitness |
| Fit Cuffs |
| EDGE Mobility System |
| Smart Tools Plus |
| Occlusion Cuff |
| Iron Bull Strength |
| Others |
Supply & Pricing Matrix
Microelectromechanical pressure sensor integration into pneumatic bladder walls is simultaneously elevating production costs and compressing the supplier base toward East Asian component specialists with captive sensor fabrication capabilities. This technology transition rewards manufacturers with backward integration into medical-grade silicone processing while penalizing pure-play assemblers dependent on spot-market bladder procurement.
Pricing Analysis
Bundled hardware-subscription services versus unbundled equipment-only sales defines the pricing architecture across pneumatic and elastic tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered clinical systems from CE-marked professional devices and unregulated consumer straps. Price differentiation hinges on pressure calibration certification and indemnification clause inclusion. Cost compression in the elastic tier intensifies because resistance band substitution erodes perceived value. Home fitness consumers exhibit highest price sensitivity; post-surgical rehabilitation clinics demonstrate lowest sensitivity due to reimbursement pass-through mechanics.
Supply Chain Analysis
Dual-sourcing requirements from United States and German physiotherapy chains mandate multi-supplier qualification for medical-grade silicone bladders, forcing manufacturers to qualify secondary East Asian component vendors beyond primary Taiwanese and South Korean sources. Raw material dependencies center on liquid silicone rubber, microelectromechanical pressure sensors, and medical-grade Velcro fastening systems. Single-source vulnerability concentrates in Taiwanese MEMS sensor foundries serving pneumatic band specialists. Distribution runs through durable medical equipment suppliers in reimbursement-adjacent markets and direct-to-consumer digital channels in fitness-focused segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood flow restriction band market functions as a stable compounder anchored by institutional procurement mandates from NCAA Division I athletic programs and post-surgical rehabilitation networks with eighteen-to-twenty-four-month replacement cycles.
For Market Incumbents: Deepen backward integration into medical-grade silicone bladder manufacturing to offset East Asian component supplier concentration risk. Secure indemnification clause templates with United States hospital system purchasing cooperatives to defend against pressure calibration liability exposure. Prioritize FDA quality management system recertification investments ahead of tightening Class I device documentation requirements. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling of pneumatic hardware with remote coaching protocols offers the most penetrable entry vector. Target Germany and Japan's reimbursement-adjacent home therapy markets where digital engagement rewards ongoing service relationships over one-time equipment sales. Deploy telehealth-integrated pressure logging as the primary go-to-market differentiator against established sporting goods retail channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market pneumatic specialists bridging clinical precision and consumer accessibility without full regulatory registration overhead. Long-term viability frames around consolidation of component suppliers and geographic expansion into aging population centers with established physical therapy infrastructure. Watch Japanese Ministry of Health, Labour and Welfare reimbursement code expansions as the critical inflection signal for prescription-based home deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Registration Pathway | Class I device pressure calibration documentation extends development timelines and compresses supplier base toward established specialists. |
| CE Marking Acceleration | EU MDR streamlined accessory classification reduces time-to-market for clinical-grade occlusion systems in German and French physiotherapy networks. |
| Component Supplier Consolidation | Captive silicone bladder manufacturing secures input supply against East Asian supplier concentration vulnerability. |
| Telehealth Platform Integration | Remote pressure logging with cloud-based treatment protocols locks users into recurring revenue relationships outside facility walls. |
| Reimbursement Strategy Development | Japanese Ministry of Health, Labour and Welfare code expansions unlock prescription-based home deployment for geriatric sarcopenia protocols. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Australia, with primary inputs from each market's regulatory and procurement stakeholders. The analysis combines structured interviews with NCAA athletic trainers, physiotherapy clinic directors, hospital purchasing committee members, and pneumatic device biomedical engineers with secondary validation from FDA 510(k) filings, EU MDR registration databases, and Japanese Ministry of Health, Labour and Welfare physical therapy equipment frameworks. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from trade customs data and durable medical equipment distribution records.
Granularity-level modeling disaggregates volume and value outputs across product type, application, end user, and distribution channel dimensions, with additional segmentation by pressure technology tier and reimbursement adjacency. CAGRs derive from logistic growth curve fitting calibrated to institutional procurement cycle data and replacement rate assumptions. Industry-specific forecast inputs include NCAA equipment mandate adoption curves, Japanese aging population sarcopenia prevalence projections, and pneumatic sensor cost experience curves.
Regulatory approval delays, reimbursement code reversals, and silicone bladder supply disruptions are the dominant revision risks to the outlook. Deviation in Japanese reimbursement expansion timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Smart Fitness Trackers Market