
 Smart Sports Wearables Market | 2026-2036
Smart Sports Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sports Wearables Market Analytics
Silicon-based microelectromechanical systems are pivoting toward gallium nitride and advanced polymer substrates to reduce sensor power draw and extend device longevity between charges. Garmin Ltd. leverages its proprietary GPS chipset architecture to dominate outdoor and endurance sport segments. Apple Inc. sustains premium positioning through tight integration with its health software ecosystem and clinical-grade heart rate algorithms. Whoop Inc. specializes in subscription-based recovery analytics, differentiating through strain and sleep coaching rather than hardware sales alone.
Smart sports wearables encompass sensor-embedded garments, wrist-worn biometric monitors, and ocular or footwear-integrated devices that capture physiological and kinematic data during athletic activity. These systems typically integrate accelerometers, photoplethysmography optical sensors, and thermistors to track heart rate variability, oxygen saturation, core temperature, and movement mechanics with sampling frequencies exceeding 100 Hz for motion capture. Fitness trackers anchor current volume shipments due to accessible price points and broad consumer familiarity, while smart clothing captures expanding margin pools as textile-integrated electrode arrays replace strap-based heart rate monitors in professional settings. GPS-enabled devices lead technology attachment rates in outdoor cycling and running, whereas heart rate monitoring remains the default specification across all product tiers.
FDA software-as-medical-device oversight and EU AI Act algorithmic transparency requirements are elevating compliance costs for vendors processing health-adjacent biometric data. The EU Green Deal's extended producer responsibility frameworks are pressuring manufacturers to redesign battery architectures and enable component recyclability. Stakeholders must monitor evolving CE marking thresholds under the EU Medical Device Regulation as fitness devices with diagnostic claims face reclassification pressures. The decisive inflection point hinges on whether clinical validation investments convert wearable data into reimbursable healthcare workflows.
Market Dynamics
Clinical validation investments are converting wearable biometric data into reimbursable healthcare workflows, forcing vendors to choose between consumer fitness positioning and regulated medical device pathways. This bifurcation is reshaping R&D allocation, compliance staffing, and partnership strategies across the value chain.
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:The FDA's SaMD framework accelerates clearance for algorithms detecting atrial fibrillation and sleep apnea, opening reimbursement channels through Medicare Advantage plans.
- NCAA Athletic Departments:Collegiate sports programs in the United States are mandating biometric monitoring for concussion protocols and load management, creating institutional procurement pipelines.
- Gallium Nitride Sensors:GaN-based photoplethysmography chips cut power consumption by half versus silicon MEMS, extending battery life in continuous-monitoring form factors.
Market Restraints
- EU AI Act Compliance Costs:Algorithmic transparency requirements for health-adjacent wearables force vendors to maintain explainability documentation and human-in-the-loop review systems.
- Lithium-Ion Supply Concentration:Battery cell production clusters in East Asia expose manufacturers to shipping cost volatility and geopolitical supply disruptions.
- Optical Sensor Limitations:Melanin absorption interference reduces photoplethysmography accuracy on darker skin tones, constraining addressable population segments.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for wearable manufacturing attract assembly investment to offset China supply chain exposure.
- Textile-Integrated Electrode Arrays:Smart garments with woven conductive threads replace chest straps in professional cycling and rowing, capturing premium margin pools.
- Subscription Recovery Analytics:Strain-sleep-recovery coaching models decouple revenue from hardware refresh cycles, improving lifetime value metrics.
Industry Challenges
- Biomedical Algorithm Talent Scarcity:Vendors compete for machine learning engineers with clinical signal-processing expertise to validate arrhythmia detection claims.
- CE Marking Timeline Compression:EU Medical Device Regulation reclassification of fitness devices with diagnostic claims extends certification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sports Wearables Market |
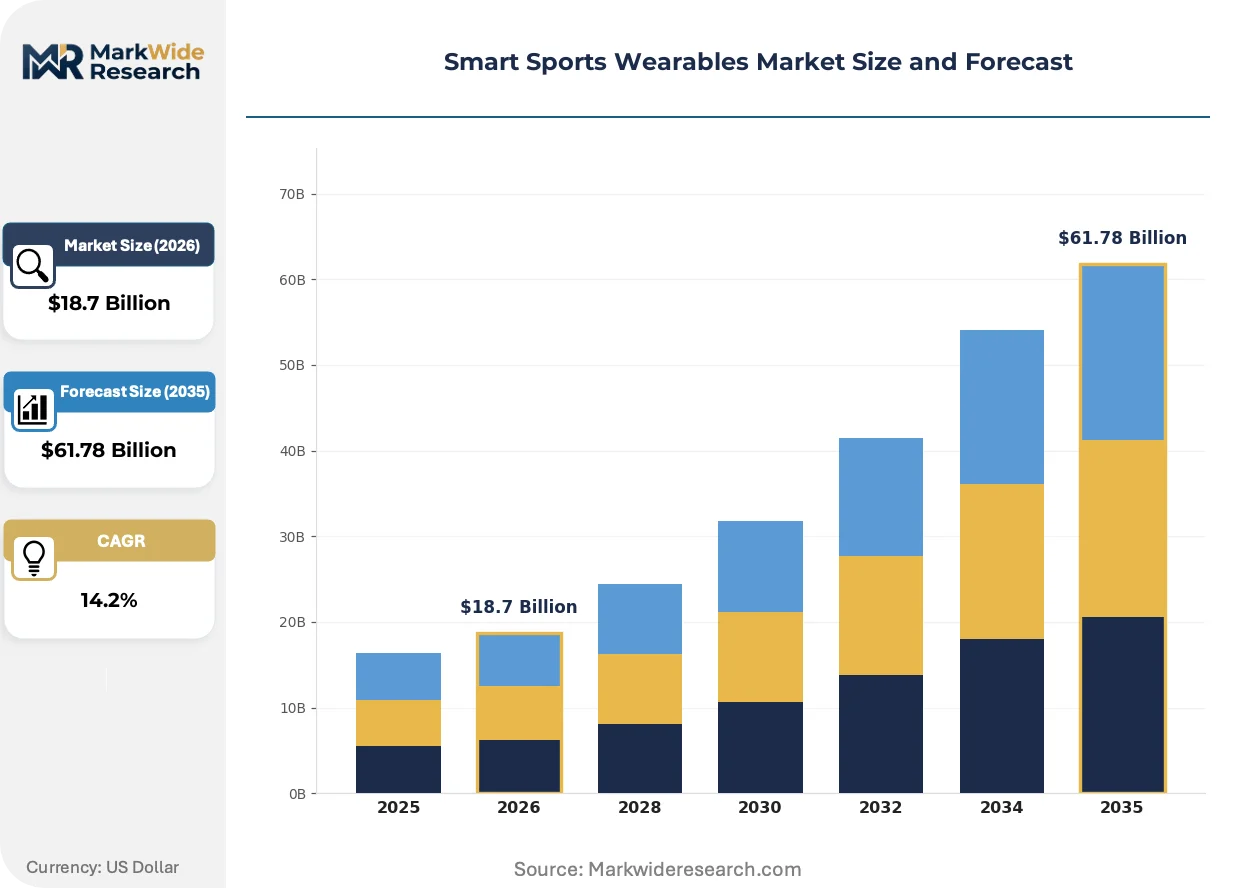
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smart Glasses, Smart Clothing, Smart Shoes Technology: Bluetooth, NFC, GPS, Heart Rate Monitoring End User: Athletes, Fitness Enthusiasts, Coaches, Health-Conscious Individuals Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Fitness Centers |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Fitbit Inc., Huawei Technologies, Xiaomi Corporation, Under Armour Inc., Catapult Group International Ltd., Whoop Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sports Wearables Market Evolving Landscape
Convergence between clinical-grade sensing and consumer accessibility is compressing the boundary between wellness accessories and regulated medical devices. This shift demands simultaneous investment in FDA-grade validation and mass-market manufacturing scale.
Photoplethysmography is unifying heart rate, blood oxygen, and respiration sensing into single optical modules. Olympic training programs and NCAA performance labs are adopting these multi-parameter arrays for real-time load monitoring. The technology is unifying previously separate device categories into consolidated wrist-worn platforms, reducing athlete equipment burden while expanding data capture density.
The EU AI Act's risk-based classification system imposes documentation burdens on wearables processing biometric data for health inferences. Vendors must maintain technical files demonstrating algorithmic robustness across demographic subgroups. Professional sports teams in Germany and France are delaying deployments until compliance frameworks clarify liability allocation between device makers and institutional users.
Institutional procurement is consolidating around platform ecosystems that integrate wearable data with electronic health records and team management software. NCAA athletic departments and NFL franchise performance labs are replacing point-solution vendors with integrated-stack providers. This preference shift is most visible in the United States, where bundled analytics contracts now outnumber standalone hardware purchases in professional settings.
Smart Sports Wearables Market Segmentation
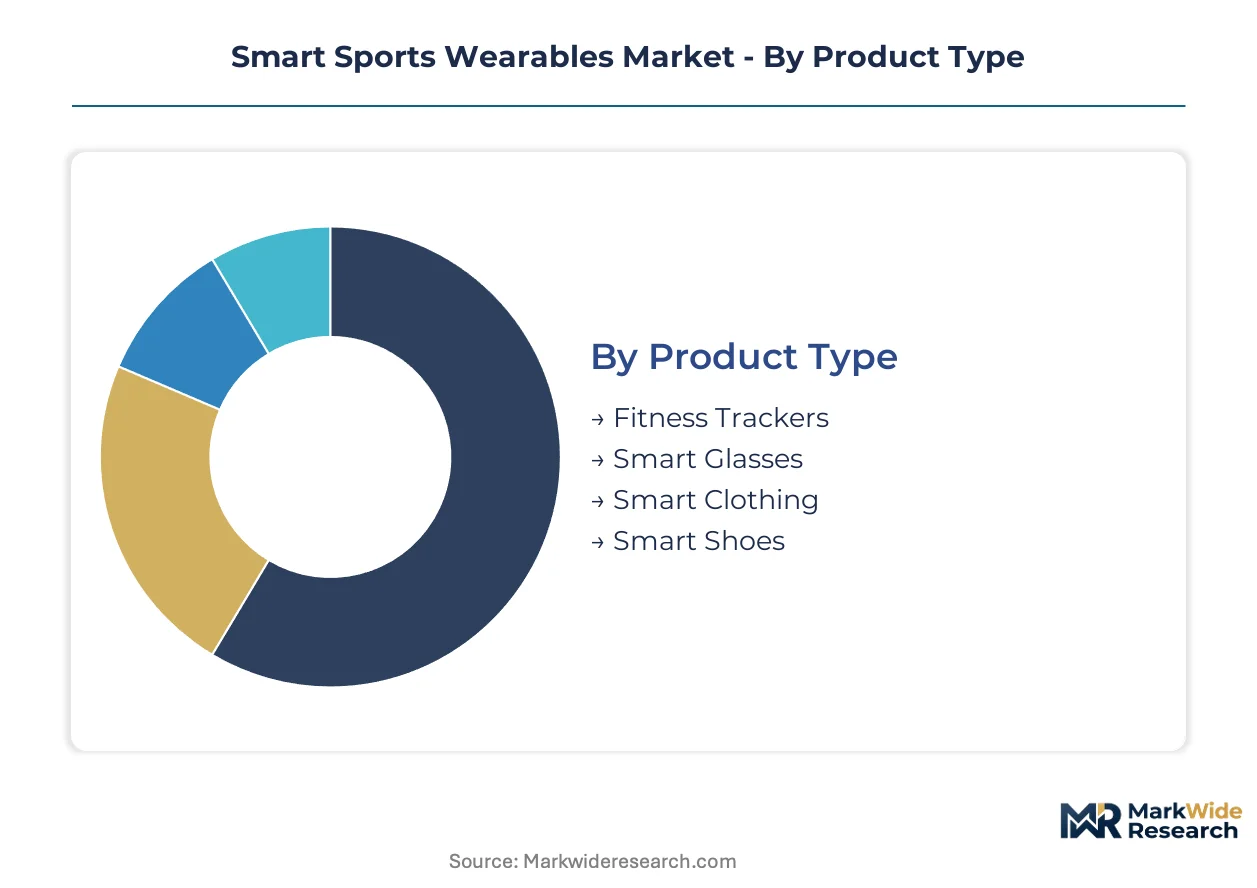
Segmentation in smart sports wearables determines which regulatory pathways manufacturers must navigate. Product positioning across fitness, clinical, or hybrid categories dictates FDA SaMD eligibility, EU MDR classification thresholds, and reimbursement potential through Medicare Advantage or private insurers.
Product Type:
Fitness Trackers carry minimal certification burdens as wellness devices, while Smart Clothing with diagnostic electrode arrays triggers EU MDR Class IIa scrutiny and FDA 510(k) requirements for arrhythmia detection claims.
- Fitness Trackers:Wrist-worn devices combining accelerometers with basic photoplethysmography sensors for step counting and heart rate zone tracking. NCAA athletic departments mandate these for concussion protocol baselines, with institutional procurement favoring platforms integrating with electronic health record systems.
- Smart Clothing:Textile-embedded conductive thread arrays replacing chest strap monitors for continuous ECG-quality heart rate capture. Professional cycling teams and Olympic rowing programs drive demand as woven electrodes eliminate skin contact variability during high-sweat exertion.
- Smart Glasses:Ocular-mounted displays with integrated gaze tracking and performance metrics overlay. Limited penetration outside specialized training environments due to battery constraints and visual distraction liability concerns.
- Smart Shoes:Footwear-embedded pressure sensors and inertial measurement units capturing ground contact time, cadence, and pronation mechanics. Adoption concentrates in professional running programs and physical therapy rehabilitation protocols.
Fitness Trackers sit at the top of the volume ranking, with Smart Clothing climbing the fastest.
Technology:
Technology selection determines power architecture, data transmission security requirements, and the precision of biometric inference algorithms subject to EU AI Act transparency mandates.
- Bluetooth:Dominant short-range wireless protocol for device-to-smartphone synchronization. Low Energy 5.3 specifications enable multi-day battery life in continuous-monitoring form factors.
- NFC:Near-field communication for tap-to-pair setup and contactless payment integration in premium wrist-worn devices.
- GPS:Satellite positioning systems enabling pace, distance, and elevation tracking in outdoor cycling and running segments. Multi-band GNSS chipsets from Garmin and Apple reduce urban canyon positioning errors.
- Heart Rate Monitoring:Photoplethysmography optical sensors unifying pulse detection with blood oxygen and respiration rate estimation. Melanin absorption interference on darker skin tones remains an unresolved accuracy constraint limiting addressable populations.
Bluetooth anchors current shipment volumes, with GPS-enabled devices gaining share fastest in outdoor endurance segments.
End User:
End user categories diverge sharply in price sensitivity, data integration requirements, and willingness to accept subscription-based analytics over hardware ownership.
- Athletes:Professional and collegiate competitors requiring load management, recovery optimization, and injury risk quantification. NCAA concussion protocols and NFL franchise performance labs institutionalize procurement through bundled analytics contracts.
- Coaches:Team staff aggregating biometric data across athlete rosters for training periodization and tactical substitution decisions. Platform ecosystem integration with team management software determines vendor selection.
- Fitness Enthusiasts:Recreational consumers prioritizing goal tracking and social sharing features over clinical-grade accuracy. Price elasticity drives volume concentration in sub-premium hardware tiers.
- Health-Conscious Individuals:Aging demographics seeking FDA-cleared arrhythmia detection and sleep apnea screening for Medicare Advantage reimbursement eligibility.
Fitness Enthusiasts represent the largest addressable population, with Coaches showing the steepest expansion trajectory as institutional procurement consolidates around integrated-stack providers.
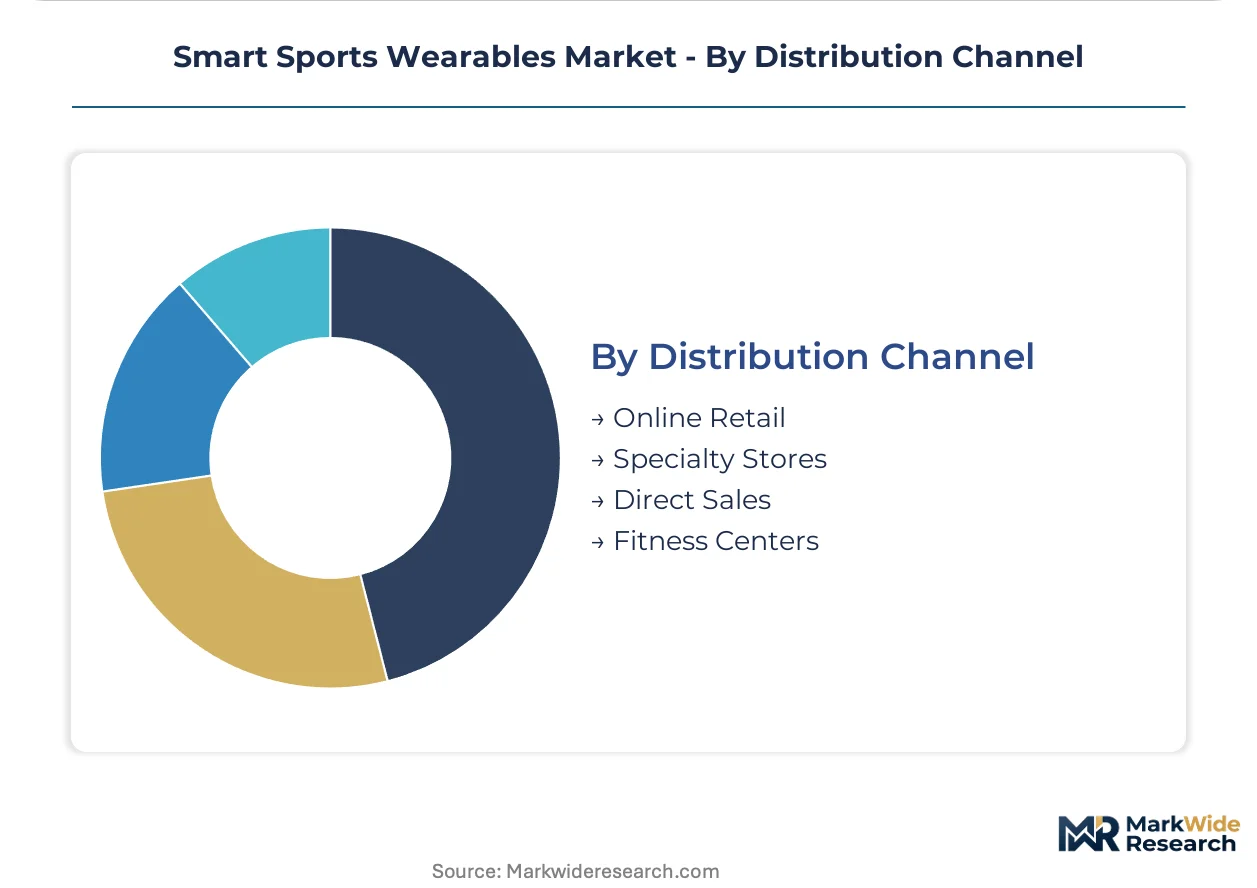
Distribution Channel:
Channel strategy shapes margin capture, customer acquisition costs, and the feasibility of subscription attach for recurring revenue models.
- Online Retail:E-commerce platforms enabling direct-to-consumer subscription bundling and firmware update distribution. Whoop and similar vendors bypass retail margin extraction through proprietary storefronts.
- Specialty Stores:Running and cycling shops providing fitting services and local community engagement. Premium positioning depends on trained staff explaining optical sensor limitations and recovery algorithm interpretations.
- Direct Sales:Enterprise contracts with NCAA athletic departments, Olympic training centers, and professional franchise performance labs. Procurement committees evaluate data security, HIPAA compliance, and electronic health record integration capabilities.
- Fitness Centers:Gym partnerships distributing devices as membership perks or premium upsells. High churn in gym subscriptions creates customer lifetime value uncertainty for hardware vendors.
Online Retail commands the dominant volume position, with Direct Sales expanding most quickly as institutional procurement pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santa Clara County anchors wearable semiconductor design, with Apple and Garmin engineering teams driving photoplethysmography innovation from Silicon Valley campuses.
United States
NCAA athletic departments mandate biometric monitoring for concussion protocols, creating institutional procurement pipelines across collegiate sports. FDA software-as-medical-device pathways accelerate clearance for arrhythmia detection algorithms. Austin and Boston clusters concentrate startup activity in recovery analytics and textile-integrated sensors.
Germany
Professional cycling teams and Olympic training programs drive demand for ECG-quality smart garments with woven electrode arrays. EU AI Act algorithmic transparency requirements force vendors to maintain explainability documentation for health-adjacent wearables. Munich and Stuttgart engineering centers specialize in precision sensor manufacturing for automotive-derived MEMS applications.
China
Domestic brands capture volume shipments in fitness trackers through accessible price points and broad distribution networks. NMPA medical device regulations tighten scrutiny on diagnostic claims for consumer wearables. Shenzhen manufacturing clusters dominate assembly capacity for Bluetooth modules and lithium-ion battery cells.
India
Production-linked incentive schemes for electronics manufacturing attract assembly investment to offset China supply chain exposure. BIS certification requirements create compliance barriers for imported devices. Bangalore and Hyderabad emerging as design hubs for algorithm development and firmware engineering.
Japan
Aging demographics drive demand for FDA-cleared sleep apnea screening and Medicare Advantage reimbursement eligibility. METI standards for wearable device interoperability shape procurement specifications for enterprise health programs. Tokyo and Osaka metropolitan areas concentrate corporate wellness program deployments.
Smart Sports Wearables Market Competitive Landscape
Global majors compete with regional champions across ecosystem integration versus localized price positioning. The vendor base stratifies into three tiers: vertically integrated platform owners, subscription-native analytics specialists, and component-focused OEM suppliers. Consolidation pressure intensifies as institutional procurement favors integrated-stack providers over point-solution vendors. Dominant competitive moves include strategic partnerships with electronic health record platforms and geographic expansion through local manufacturing incentives.
Within the integrated-platform tier, Apple Inc. and Samsung Electronics exemplify ecosystem-driven positioning through proprietary health software architectures. Garmin Ltd. occupies a specialist position in outdoor and endurance segments through captive GPS chipset design. Whoop Inc. represents the subscription-native archetype, decoupling revenue from hardware refresh cycles through strain-sleep-recovery coaching models.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit Inc. |
| Huawei Technologies |
| Xiaomi Corporation |
| Under Armour Inc. |
| Catapult Group International Ltd. |
| Whoop Inc. |
| Others |
Value Network & Pricing Analysis
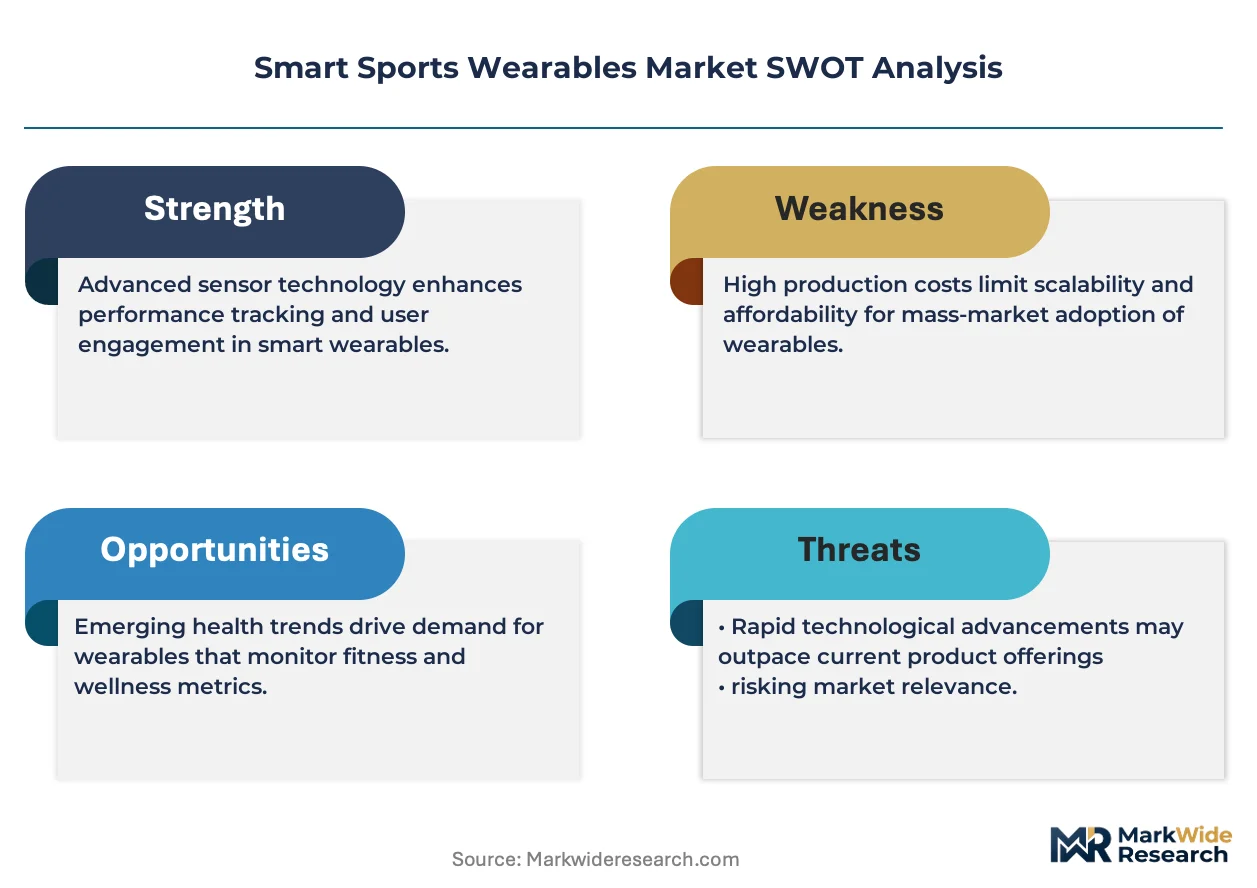
Gallium nitride sensor fabrication is displacing silicon MEMS production lines, simultaneously compressing power-consumption premiums and concentrating foundry relationships among Japanese and Taiwanese compound semiconductor specialists. This transition tightens margin capture for vendors locked into legacy silicon supply agreements while rewarding early movers with unit-cost advantages in continuous-monitoring form factors.
Pricing Analysis
Input-cost pass-through from lithium-ion cells and optical sensor modules governs landed hardware costs, with battery chemistry volatility transmitting directly to manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared arrhythmia detection devices from wellness-tracker SKUs, with certification grade commanding the widest price differentiation. Pricing pressure stems from Chinese domestic brands compressing entry-tier margins through vertically integrated Shenzhen assembly. Fitness enthusiasts exhibit highest price elasticity, while NCAA athletic departments and NFL franchise performance labs demonstrate minimal sensitivity due to bundled analytics procurement.
Supply Chain Analysis
Photoplethysmography chip supply rests on Taiwanese foundries and Japanese specialty chemical producers for GaN epitaxy substrates. Raw material dependencies include lithium carbonate from Chilean and Australian mining operations, rare-earth elements for magnetometers concentrated in Chinese processing facilities, and advanced polymers for textile-integrated electrodes sourced from German chemical conglomerates. Single-source vulnerability in Bluetooth Low Energy controller silicon exposes manufacturers to allocation constraints during consumer electronics demand spikes. Distribution runs through direct-to-consumer online retail for subscription-native vendors and enterprise sales teams for institutional procurement pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart sports wearables market reads as a late-cycle quality story, with demand consolidating around clinical-grade specifications as NCAA concussion protocols and Medicare Advantage reimbursement eligibility elevate performance thresholds.
For Market Incumbents: Lock in institutional procurement relationships through electronic health record integration and HIPAA-compliant data architectures. Deepen backward integration into gallium nitride sensor design to secure power-efficiency advantages against emerging entrants. Prioritize CE marking completion ahead of EU MDR reclassification deadlines to defend channel access.
For New Entrants and Emerging Players: Collegiate athletic departments outside Power Five conferences represent an underserved buyer archetype with unconsolidated vendor relationships and limited platform integration requirements. India's PLI scheme for electronics manufacturing offers white-space assembly capacity with tariff-advantaged export positioning to Middle Eastern and African markets. Pursue direct sales contracts emphasizing strain-recovery algorithm differentiation over hardware specifications.
For Investors and Strategic Acquirers: Roll-up economics work for subscription-native recovery analytics specialists because institutional procurement is consolidating around integrated-stack providers and point-solution vendors face exclusion from NCAA and NFL performance lab contracts. Target acquisition archetypes include textile-integrated sensor startups with woven electrode IP and clinical validation pipelines for sleep apnea detection algorithms. Watch FDA SaMD clearance timelines for atrial fibrillation algorithms as the decisive signal for reimbursement-enabled revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates Medicare Advantage reimbursement eligibility for arrhythmia detection claims. |
| Textile-Integrated Electrode Array Development | Captures premium margin pools in professional cycling and Olympic rowing programs. |
| CE Marking Pathway Completion | Defends EU market access against MDR reclassification of diagnostic fitness devices. |
| Electronic Health Record Platform Integration | Determines vendor selection in NCAA athletic department procurement committees. |
| India PLI Scheme Manufacturing Footprint | Offsets China supply chain exposure through tariff-advantaged assembly capacity. |
Research Methodology
Direct dialogue with wearable engineering executives, NCAA athletic department procurement officers, FDA regulatory consultants, and sports medicine clinicians grounded qualitative assessments in operational reality. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, SEC filings of publicly traded vendors, and Medicare Advantage plan reimbursement schedules. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology attachment, and end-user segmentation dimensions.
Segmented outputs across fitness trackers, smart clothing, and GPS-enabled devices reconciled with technology penetration rates and regional adoption patterns throughout the forecast period. CAGRs were derived from logistic growth curve fitting calibrated to historical smartphone and fitness tracker diffusion trajectories. Industry-specific forecast inputs included NCAA concussion protocol mandate expansion timelines and EU AI Act compliance cost assumptions for algorithmic transparency documentation.
Inputs from institutional procurement databases and FDA clearance registries were available through the study window; gaps in private company subscription revenue disclosures introduce uncertainty bands around lifetime value metrics. Forecasts reflect documented assumptions regarding gallium nitride sensor yield improvements and lithium-ion cell price trajectories. A small set of triggers—including EU MDR reclassification enforcement timing and NMPA diagnostic claim scrutiny in China—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Wearable Sensors Market