
 5G Internet of Things Market | 2026-2036
5G Internet of Things Market Size, Share, and Industry Trends Forecast 2026-2036
5G Internet of Things Market Outlook
Telecom operator channel partnerships are reshaping how 5G-IoT solutions reach enterprise buyers. Nokia Corporation leverages its radio access network portfolio to anchor private 5G deployments for manufacturing clients. Qualcomm Technologies specializes in chipset-level integration that sustains its position across wearables and connected vehicle modules. Ericsson competes through end-to-end network slicing capabilities that differentiate its industrial automation offerings.
5G Internet of Things denotes a cellular connectivity architecture where ultra-reliable low-latency communication links massive device densities at sub-10 millisecond response times for mission-critical sensing and actuation. Its primary commercial purpose is enabling real-time data exchange between distributed machines, infrastructure, and consumers without wired tethering. Industrial Equipment within the Device Type dimension dominates current revenue as factory retrofit cycles accelerate, while Edge Computing within the Technology dimension captures expanding margin pools as processing migrates from centralized clouds to local nodes. Smart Cities within the Application dimension represents the fastest-growing deployment category as municipal budgets prioritize connected traffic, energy, and safety systems.
The FCC governs spectrum allocation and device certification requirements that directly determine which radio frequencies 5G-IoT hardware can legally operate across the United States. ETSI and 3GPP framework convergence in Europe is forcing modular hardware designs that comply with both CE marking and open RAN interoperability standards. China's MIIT enforces domestic GB standards and dual carbon goals that shape local vendor product roadmaps and energy efficiency benchmarks. Stakeholders must monitor evolving national spectrum auctions and open RAN mandates to calibrate hardware investment cycles and partnership strategies.
Market Dynamics
Private 5G network deployment is concentrating capital flows toward edge-native architectures, compressing traditional cloud-centric procurement cycles and rewiring vendor-buyer power structures across industrial verticals.
Growth Catalysts
- CBRS Spectrum Liberalization:The FCC's 3.5 GHz band reallocation in the United States unlocks licensed-shared access for factory operators, bypassing carrier dependency for mission-critical automation.
- Factory Retrofit Cycles:China's manufacturing corridor is replacing wired PLC systems with wireless actuation nodes, creating immediate hardware refresh demand across automotive and electronics assembly lines.
- ETSI-3GPP Framework Convergence:Modular radio designs compliant with both CE marking and open RAN standards reduce certification duplication costs for European equipment vendors.
Market Restraints
- Gallium Nitride Supply Concentration:RF power amplifier substrate production clusters in East Asian foundries, exposing module manufacturers to single-source fragility.
- Millimeter-Wave Propagation Limits:Sub-6 GHz spectrum saturation forces indoor deployments toward 28 GHz bands with severe wall-penetration degradation.
- Dual Carbon Compliance Burden:China's MIIT energy efficiency mandates add thermal design constraints that extend product development timelines by 20-30%.
Strategic Opportunities
- India's PLI Scheme for Telecom:Production-linked incentives for 5G equipment manufacturing attract module assembly relocation from higher-cost East Asian bases.
- Smart City Sensor Convergence:Municipal traffic-energy-safety system integration in Barcelona and Seoul creates bundled procurement vehicles for multi-application vendors.
- Network Slicing Monetization:End-to-end SLA guarantees for autonomous logistics fleets enable premium pricing tiers distinct from best-effort consumer connectivity.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortages of engineers proficient in real-time operating systems and radio firmware delay private network commissioning timelines.
- Multi-Vendor Interoperability Testing:Open RAN disaggregation fragments integration accountability across radio unit, distributed unit, and centralized unit suppliers.
- Legacy SCADA Bridge Complexity:Protocol translation between Modbus/Profibus industrial networks and 5G-TSN gateways requires custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Internet of Things Market |
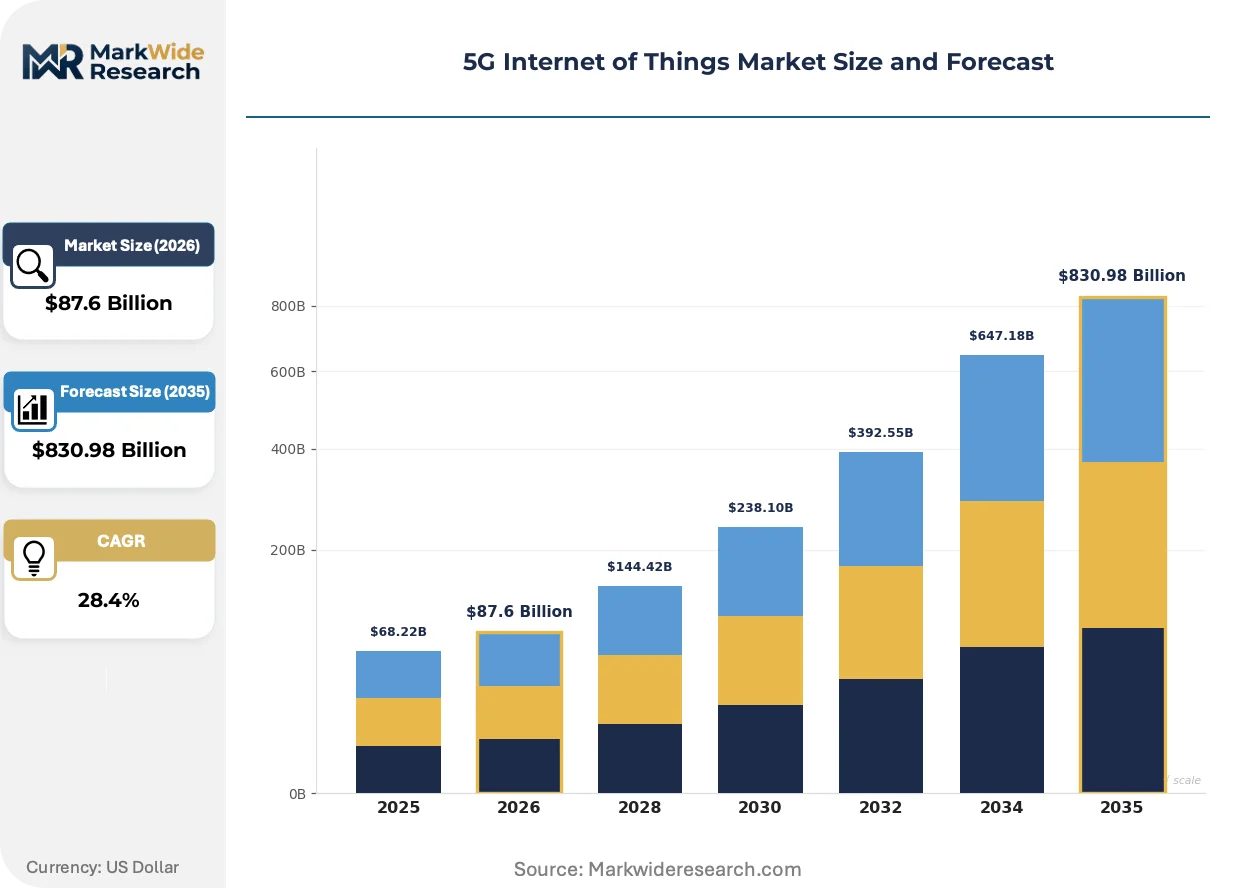
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $830.98 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearables, Smart Home Devices, Connected Vehicles, Industrial Equipment Technology: NB-IoT, LTE-M, Massive MIMO, Edge Computing Application: Smart Cities, Healthcare Monitoring, Asset Tracking, Industrial Automation End User: Telecom, Manufacturing, Healthcare, Retail |
| Companies Covered | Huawei Technologies, Nokia Corporation, Telefonaktiebolaget LM Ericsson, Qualcomm Technologies, AT&T, Verizon Communications, China Mobile Limited, Cisco Systems, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Internet of Things Market Strategic Shifts
Computational migration from centralized clouds toward distributed edge nodes is compressing latency budgets and rewiring where value capture occurs across the connectivity stack.
Containerized network functions running on commodity servers at cell tower bases are rendering obsolete proprietary hardware-centric baseband processing. Mining operators in Australia's Pilbara region are deploying these virtualized radio access networks to support autonomous haul truck coordination. The shift decouples software upgrade cycles from hardware replacement, extending infrastructure depreciation schedules.
The EU AI Act's risk classification framework for autonomous industrial systems is mandating explainability documentation for sensor-driven safety decisions. German automotive plants must now maintain algorithmic audit trails for connected robotic cells. This is accelerating investment in edge AI inference chips with built-in logging capabilities.
Enterprise buyers are consolidating vendor relationships around systems integrators capable of delivering unified connectivity-compute-storage stacks. Japanese manufacturing conglomerates now specify single-contract accountability for private 5G deployment rather than procuring radio, core, and edge compute separately. The pattern concentrates margin with full-stack providers and marginalizes component specialists.
5G Internet of Things Market Segmentation
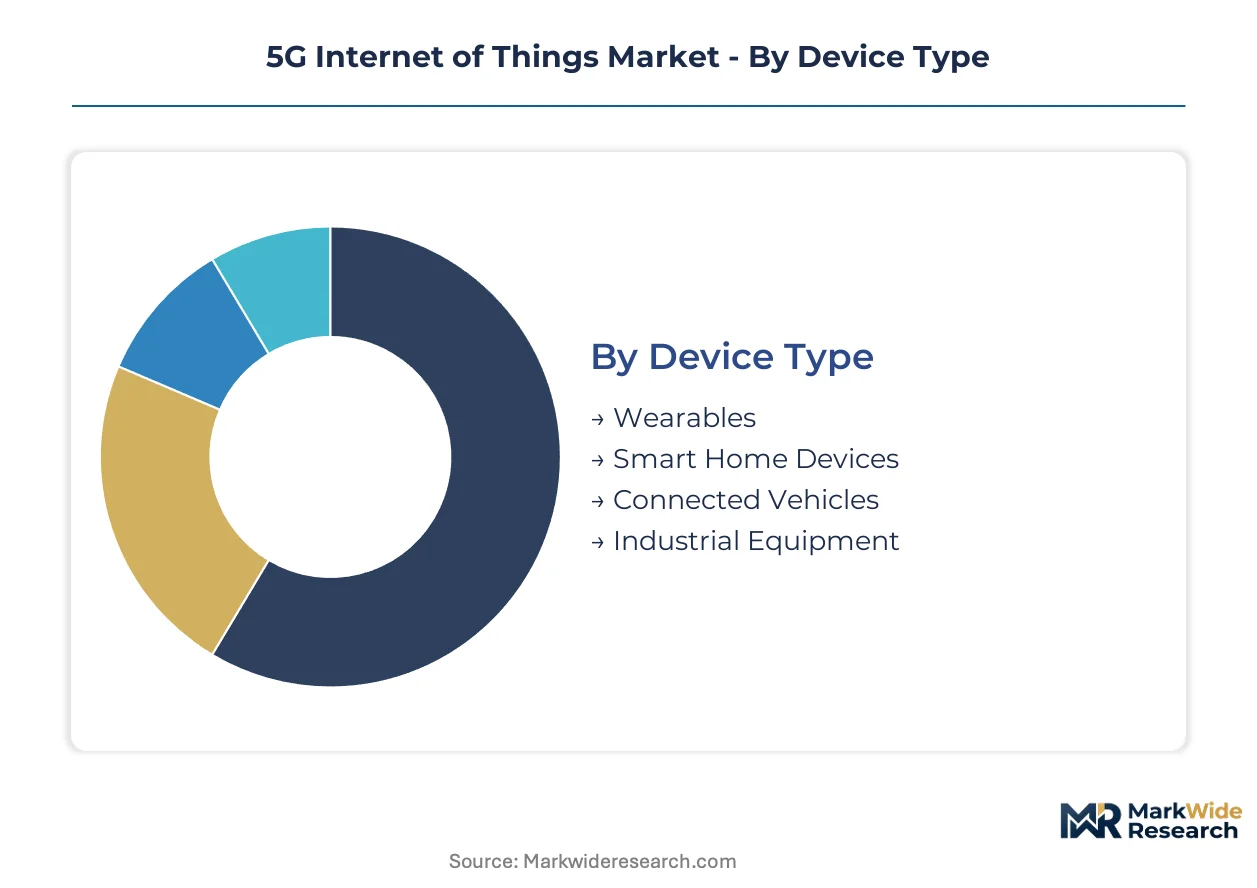
Segmentation reveals how 5G-IoT value pools concentrate across hardware form factors, radio technologies, deployment scenarios, and buyer verticals. Each dimension carries distinct procurement rhythms, certification requirements, and margin structures that shape vendor strategy.
Device Type:
The use-case spectrum spans consumer wearables through heavy industrial machinery, with latency tolerance and environmental ruggedness defining hardware design trade-offs.
- Industrial Equipment:Ruggedized actuators, programmable logic controllers, and wireless sensor nodes replace wired fieldbus architectures in factory floors. Demand concentrates in China's manufacturing corridor where Huawei and ZTE build integrated ecosystems for automotive and electronics assembly automation.
- Connected Vehicles:Telematics control units, V2X communication modules, and autonomous driving sensor arrays require sub-10 millisecond latency guarantees. Fleet operators in Germany's automotive belt specify these modules for predictive maintenance and platooning coordination on freight corridors.
- Wearables:Health monitors, fitness trackers, and enterprise safety badges leverage reduced complexity chipsets for extended battery life.
- Smart Home Devices:Connected appliances, security systems, and energy management terminals prioritize cost-optimized connectivity over industrial-grade reliability.
Established volume favors Industrial Equipment; emerging adoption favors Connected Vehicles.
Technology:
Radio access technologies stratify by power budget, spectrum efficiency, and architectural location within the connectivity stack.
- Edge Computing:Containerized network functions and AI inference engines deployed at cell tower bases or factory floors process data locally rather than backhauling to centralized clouds. Mining operators in Australia's Pilbara region deploy these virtualized architectures for autonomous haul truck coordination.
- Massive MIMO:Antenna arrays with 64+ elements boost spectral efficiency through beamforming, enabling high-density device connectivity in urban environments.
- NB-IoT:Narrowband protocols optimize for infrequent small-payload transmission across utility meters and agricultural sensors.
- LTE-M:Machine-type communication extends mobility support and voice capability for asset tracking and wearable applications.
Deployment maturity favors NB-IoT; margin expansion favors Edge Computing.
Application:
Solution architectures diverge between municipal infrastructure scale and precision industrial control requirements.
- Smart Cities:Integrated traffic signal control, energy grid optimization, and public safety sensor networks bundle procurement across municipal departments. Barcelona and Seoul accelerate deployment of connected infrastructure with unified command platforms.
- Industrial Automation:Time-sensitive networking gateways synchronize robotic cells and quality inspection systems with deterministic latency bounds.
- Healthcare Monitoring:Remote patient monitoring and connected medical devices demand HIPAA-compliant data handling and FDA device certification pathways.
- Asset Tracking:Logistics fleet management and supply chain visibility solutions prioritize geolocation accuracy and battery longevity.
Budget concentration favors Industrial Automation; steepest expansion trajectory favors Smart Cities.
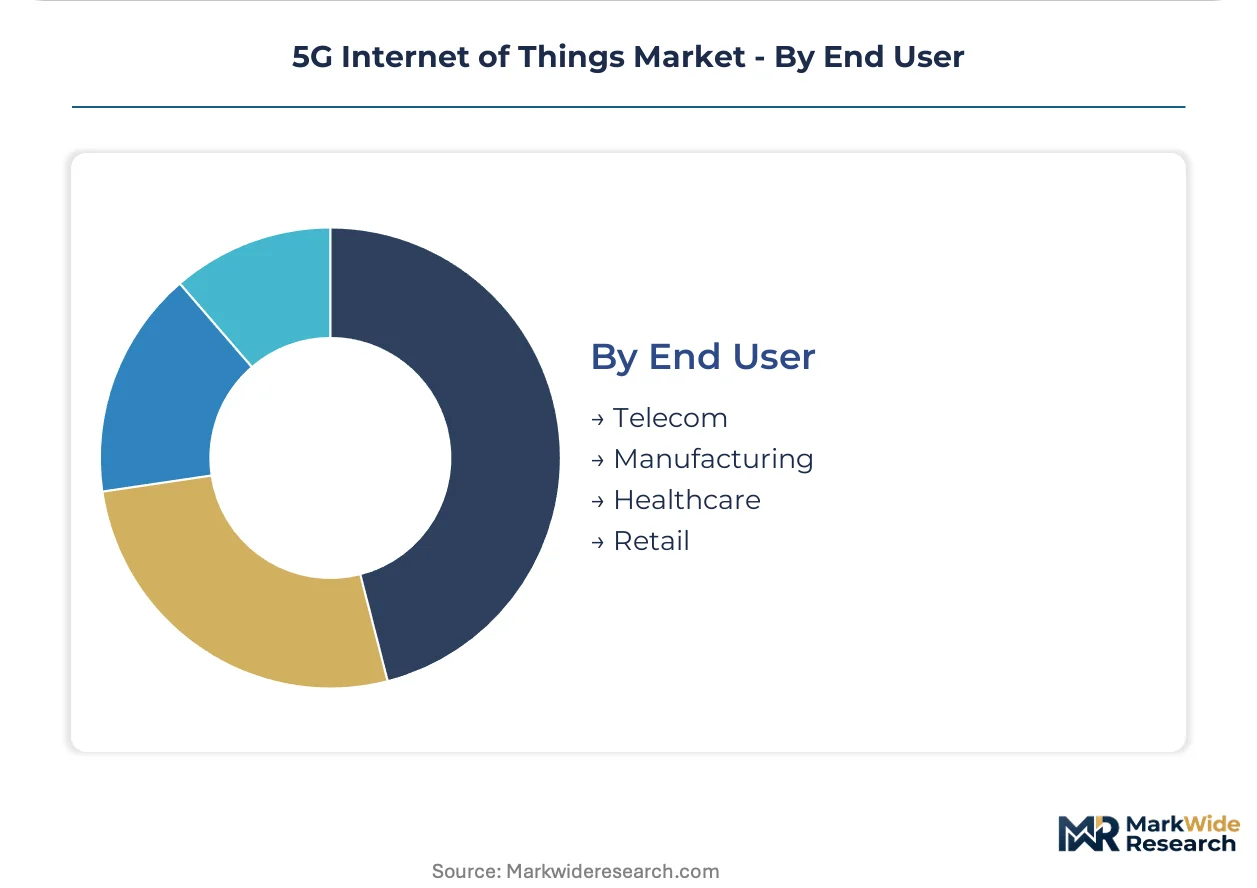
End User:
Buyer sophistication ranges from carrier-grade network operators to vertical specialists with domain-specific integration requirements.
- Manufacturing:Discrete and process industries procure private 5G networks with integrated edge compute for factory automation retrofit cycles. Japanese conglomerates now specify single-contract accountability rather than procuring radio, core, and edge separately.
- Telecom:Mobile network operators monetize network slicing and SLA-guaranteed connectivity tiers for enterprise and consumer segments.
- Healthcare:Hospital systems and payers deploy connected devices with stringent cybersecurity and patient privacy compliance frameworks.
- Retail:Inventory management, customer analytics, and supply chain optimization drive connected sensor deployment in distribution centers and storefronts.
Contract value favors Telecom; integration complexity favors Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations in Bude, UK and Marseille, France anchor Europe's data throughput capacity for edge computing workloads. These fiber-optic interconnects enable the low-latency backhaul that 5G-IoT smart city deployments require.
United States
Factory automation retrofits in Michigan's automotive belt and Texas's semiconductor corridor drive private 5G network procurement. The FCC's CBRS spectrum reallocation at 3.5 GHz unlocks licensed-shared access for industrial operators, bypassing carrier dependency. Pittsburgh's robotics cluster deploys connected sensors for autonomous manufacturing cells.
Germany
Automotive OEMs in Baden-Württemberg specify time-sensitive networking gateways for robotic cell synchronization. The EU AI Act mandates explainability documentation for sensor-driven safety decisions, forcing algorithmic audit trail investments. Munich's industrial IoT hub integrates edge AI inference with 5G-TSN convergence.
China
Shenzhen's electronics assembly ecosystem and Shanghai's port automation projects concentrate demand for integrated 5G-IoT hardware. MIIT enforces GB standards and dual carbon goals that extend product development timelines through thermal design constraints. Huawei and ZTE anchor domestic vendor ecosystems for factory wireless retrofit cycles.
Japan
Manufacturing conglomerates in Toyota's supply chain specify single-contract accountability for private 5G deployment. METI promotes open RAN interoperability standards that reduce vendor lock-in for industrial users. Yokohama's smart city pilot bundles traffic-energy-safety procurement across municipal departments.
South Korea
Seoul's municipal government accelerates connected infrastructure deployment with unified command platforms for traffic and energy optimization. MFDS regulates medical device connectivity standards for hospital system IoT integration. Busan's port authority deploys autonomous logistics fleets with SLA-guaranteed network slicing.
5G Internet of Things Market Competitive Environment
On the supply side, the industry is consolidating around full-stack systems integrators capable of delivering unified connectivity-compute-storage solutions. Tiered competitive dynamics separate radio access network specialists from edge computing platform providers and semiconductor module fabricators. Strategic archetypes include infrastructure-scale telecom equipment vendors, chipset-level integration specialists, and carrier-service hybrid operators. Dominant competitive moves encompass vertical integration into captive silicon supply and strategic partnerships with municipal smart city authorities.
Within the infrastructure equipment tier, Huawei Technologies and Nokia Corporation exemplify contrasting geographic positioning strategies. ZTE Corporation anchors the integrated ecosystem approach for manufacturing corridor deployments. Qualcomm Technologies occupies a specialist position in chipset-level integration across wearables and connected vehicle modules. These three named entities represent the primary competitive anchors without exhaustive market coverage.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Qualcomm Technologies |
| AT&T |
| Verizon Communications |
| China Mobile Limited |
| Cisco Systems |
| ZTE Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian RF component foundries compresses supplier margins and forces extended payment term concessions to maintain offtake volumes, while simultaneously enabling aggressive module pricing for private 5G network deployers in Germany and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SLA-guaranteed network slicing from best-effort connectivity and basic sensor telemetry. Price differentiation rests on certification grade — CE marking and open RAN compliance command 15-20% premiums — and volume scale for municipal smart city bundles. Cost compression in the economy tier intensifies because Huawei and ZTE flood China's manufacturing corridor with integrated ecosystem hardware. Municipal procurement offices exhibit highest price sensitivity, while German automotive OEMs prioritize deterministic latency guarantees over unit economics.
Supply Chain Analysis
Supplier-financing facilities with 120-day extended payment terms have become standard for Gallium Nitride substrate procurement from East Asian foundries. Geographic supply concentration centers on China, South Korea, and Taiwan for RF power amplifiers, baseband processors, and antenna arrays. Raw material dependencies include GaN-on-SiC wafers, millimeter-wave beamforming modules, and precision timing oscillators. Single-source vulnerability in GaN substrate production exposes module manufacturers to foundry allocation disruptions. Distribution runs through carrier-direct enterprise sales, systems integrator channels, and municipal procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation retrofit cycles in China's manufacturing corridor signal a cyclical recovery as wired PLC replacement demand accelerates through the analysis window.
For Market Incumbents: Pre-empt open RAN disaggregation by anchoring full-stack integration contracts with Japanese manufacturing conglomerates. Capture captive silicon supply for GaN power amplifiers to neutralize single-source substrate fragility. Defend against ZTE's integrated ecosystem bundling through edge-native compute-storage convergence offerings. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for private 5G-as-a-service offerings bypassing carrier infrastructure. India's PLI scheme for telecom equipment manufacturing enables module assembly relocation with 15-20% landed cost advantages. Partner with local systems integrators rather than competing for direct municipal procurement contracts. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because containerized network functions decouple hardware replacement cycles from software monetization. Target edge AI inference chip specialists with built-in EU AI Act logging capabilities. Monitor CBRS spectrum auction participation rates as inflection indicator for private network deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Network Slicing Monetization | SLA-guaranteed tiers for autonomous logistics fleets in Busan enable premium pricing above consumer connectivity. |
| Edge Computing Platform Integration | Containerized functions at Australian mining towers decouple software upgrades from hardware depreciation schedules. |
| Open RAN Interoperability Certification | ETSI-3GPP framework convergence reduces certification duplication costs for European equipment vendors. |
| GaN Substrate Backward Integration | In-house production of RF power amplifier substrates neutralizes East Asian foundry concentration risk. |
| Smart City Bundled Procurement | Unified traffic-energy-safety contracts in Barcelona concentrate margin with full-stack systems integrators. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with private 5G network architects, industrial automation procurement leads, and municipal smart city program managers; and secondary validation through FCC spectrum allocation records, MIIT GB standard filings, 3GPP release documentation, and ETSI interoperability certification databases. Bottom-up equipment shipment estimates triangulated against top-down infrastructure capex disclosures from carrier and enterprise buyers.
Forecast inputs span device type segmentation across industrial equipment and connected vehicles, technology layers from NB-IoT through edge computing, and application dimensions including smart cities and industrial automation. CAGRs derive from regression analysis against historical retrofit cycle timing and spectrum allocation trajectories. Modeling incorporates private network deployment velocity, open RAN adoption curves, and dual carbon compliance timeline impacts.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, semiconductor foundry utilization rates, or cross-border technology trade restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding CBRS auction participation, ETSI-3GPP framework implementation schedules, and MIIT energy efficiency mandate enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Global Military IoT Market