
 Europe IoT Device Market | 2026-2036
Europe IoT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT Device Market Insights
REACH is recalibrating material compliance costs for IoT hardware entering the European market. Robert Bosch GmbH leverages its sensor foundry footprint in Germany to anchor component supply for automotive and industrial clients. Siemens AG sustains dominance in industrial gateway platforms through deep PLC integration. STMicroelectronics N.V. competes on low-power microcontroller architectures purpose-built for battery-constrained edge nodes.
An IoT device comprises embedded processors, wireless transceivers, sensors, and firmware operating at sub-watt power envelopes, purpose-built to collect environmental or operational data and transmit it to cloud or edge analytics platforms. Industrial IoT Devices command the deepest margin pools due to extended service contracts and safety-critical certification requirements, while Smart Sensors represent the fastest-expanding category as predictive maintenance programs spread across European manufacturing plants. Cellular connectivity carries premium positioning for wide-area asset tracking, though Wi-Fi and Bluetooth retain volume leadership in building automation and consumer applications.
EMA guidelines on connected medical device cybersecurity, CE marking under the EU Radio Equipment Directive, and GDPR data-localization mandates collectively shape product architecture and liability exposure for vendors serving European buyers. The EU Green Deal's embodied-carbon reporting rules are tightening supply-chain disclosure requirements for IoT hardware imports. Stakeholders must weigh certification lag against first-mover advantage as the EU AI Act's risk-classification framework extends to autonomous edge decision-making.
Market Dynamics
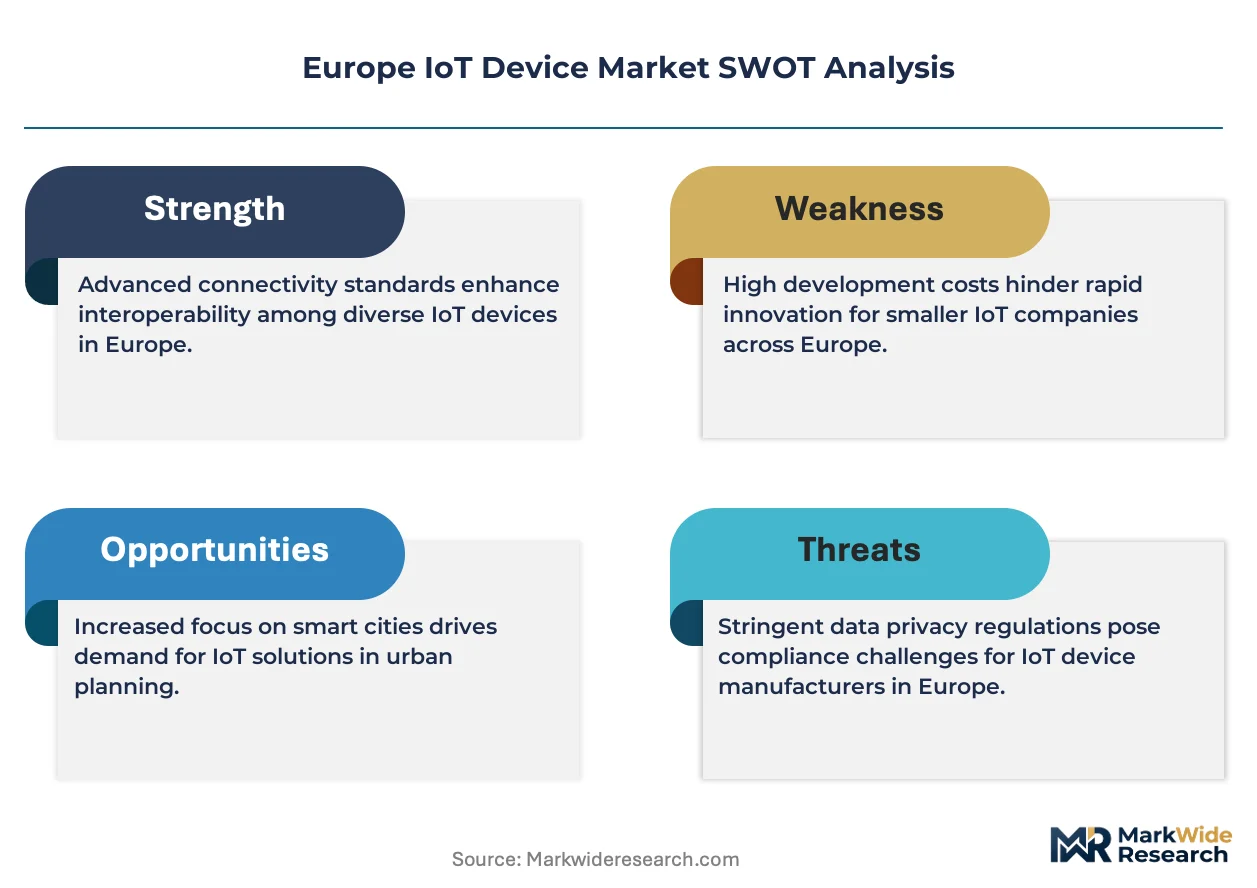
EU AI Act risk-classification rules are forcing edge-device vendors to redesign firmware architectures before products reach certification, compressing product launch timelines and redistributing R&D budgets toward compliance documentation.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Supply-chain disclosure requirements for IoT hardware imports are accelerating demand for low-carbon sensor foundries and recycled-material component sourcing.
- Predictive maintenance adoption:European manufacturing plants are expanding smart-sensor deployments to monitor equipment health, pulling battery-constrained edge nodes into factory floors.
- German automotive telemetry:Connected-vehicle programs at OEMs are scaling fleet-wide data collection, driving orders for cellular-enabled telematics control units.
Market Restraints
- Silicon supply concentration:Wafer fabrication for low-power microcontrollers remains concentrated in Asian foundries, exposing European device vendors to geopolitical shipping disruptions.
- REACH compliance costs:Material substance restrictions on solder alloys and flame-retardant plastics are inflating bill-of-materials expenses for hardware entering European distribution.
- GDPR data-localization friction:Cross-border data flows from edge devices to cloud analytics platforms face jurisdictional storage requirements that fragment software architecture.
Strategic Opportunities
- French smart-grid infrastructure:Utility modernization programs are creating procurement windows for grid-edge sensors and industrial gateway platforms.
- EU AI Act edge-autonomy carve-outs:Limited-risk classification pathways for fixed-function devices offer faster certification routes than full AI system conformity.
- Bluetooth-WiFi convergence:Hybrid radio architectures are opening building-automation applications previously segmented by protocol incompatibility.
Industry Challenges
- Embedded cybersecurity engineering scarcity:Vendors struggle to hire firmware developers with EMA-connected-device security guideline expertise.
- CE marking timeline under RED:Radio Equipment Directive testing for multi-protocol transceivers extends certification cycles by four to six months.
- Legacy PLC integration complexity:Industrial gateway vendors face engineering overhead bridging proprietary automation bus protocols to IP-based edge analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT Device Market |
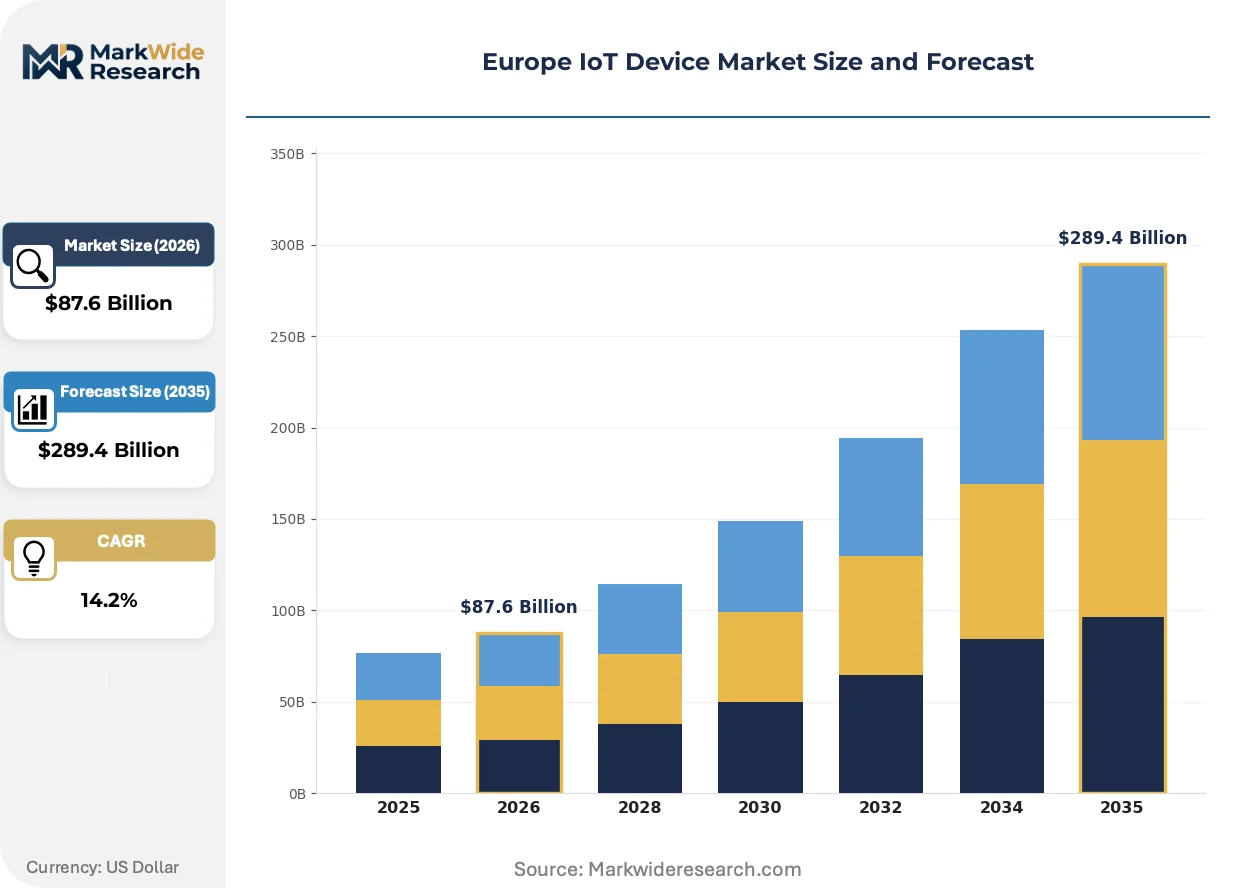
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Sensors, Wearable Devices, Home Automation Systems, Industrial IoT Devices Connectivity Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Healthcare Providers, Retailers, Smart Cities, Manufacturing Plants Application: Energy Management, Smart Home, Industrial Automation, Healthcare Monitoring |
| Companies Covered | Robert Bosch GmbH, Siemens AG, STMicroelectronics N.V., NXP Semiconductors N.V., Schneider Electric, ABB Ltd., Infineon Technologies, Ericsson, Nokia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT Device Market Trends and Innovations
Edge-native AI inference is compressing latency requirements and reshaping hardware specifications across European industrial deployments. Vendors are racing to localize decision-making without triggering high-risk classification under emerging frameworks.
Ultra-wideband positioning chips are electrifying asset-tracking accuracy in manufacturing and logistics environments. Automotive suppliers in Stuttgart and Munich are adopting the technology for indoor vehicle-location systems. The shift is electrifying demand for dedicated antenna design services and RF calibration tooling.
EMA cybersecurity guidelines for connected medical devices are mandating firmware signing and encrypted boot sequences. Device vendors serving diagnostic equipment markets must revalidate existing product lines. French and German health technology clusters are absorbing the compliance costs fastest.
Subscription telemetry models are displacing perpetual-license hardware sales in fleet management. Logistics operators in the Netherlands and Belgium prefer per-vehicle monthly fees covering hardware, connectivity, and analytics. The pattern concentrates margin capture with platform vendors who control cloud infrastructure.
Europe IoT Device Market Segmentation
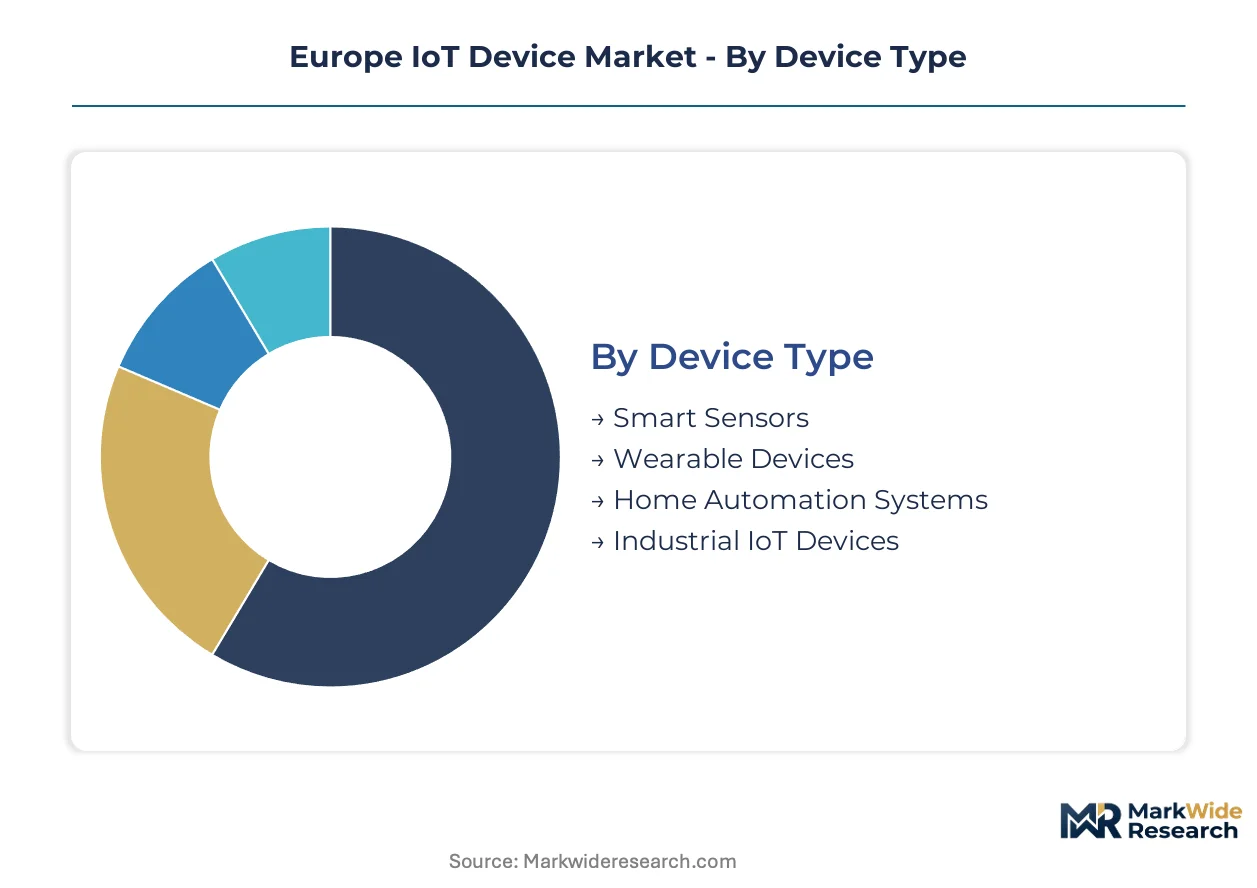
Segmentation in the Europe IoT Device Market reveals divergent compliance pathways. CE marking under the EU Radio Equipment Directive applies unevenly across device classes, while the EU AI Act's risk tiers reshape firmware architecture investments by category.
Device Type:
Certification burdens stratify sharply across device categories. Industrial IoT Devices demand functional safety approvals under Machinery Directive harmonized standards, while Wearable Devices face lighter conformity assessment under RED's internal production control route.
- Smart Sensors:Battery-constrained edge nodes integrating MEMS transducers with sub-milliwatt wireless transceivers. Predictive maintenance programs at German automotive stamping plants and French nuclear facilities are absorbing volume, though REACH substance restrictions on solder alloys inflate unit costs.
- Industrial IoT Devices:Ruggedized gateways and edge controllers bridging proprietary fieldbuses to IP networks. Siemens AG and Robert Bosch GmbH anchor supply through extended service contracts, with safety-critical SIL certifications extending sales cycles by eight to fourteen months.
- Wearable Devices:Wrist-worn or body-mounted units collecting biometric or environmental data. GDPR data-localization mandates complicate cloud synchronization architectures for vendors serving Dutch and Belgian logistics operators.
- Home Automation Systems:Integrated hubs and distributed controllers managing lighting, HVAC, and security. Wi-Fi and Zigbee protocol fragmentation forces multi-radio hardware designs that extend RED certification timelines.
Leading the category by volume: Smart Sensors. Expanding most quickly: Industrial IoT Devices.
Connectivity Technology:
Radio hardware choices determine regulatory jurisdiction and margin structure. Cellular modules trigger network operator certification layers absent in unlicensed spectrum alternatives.
- Cellular:LTE-M and NB-IoT transceivers enabling wide-area asset tracking without local infrastructure. German OEM telemetry programs and French utility smart-grid deployments are pulling volume, though module costs run three to five times above unlicensed alternatives.
- Wi-Fi:High-throughput radios for video-heavy and cloud-dependent applications. Building automation in Spanish and Italian commercial real estate concentrates demand, with WPA3 security mandates forcing firmware revalidation cycles.
- Bluetooth:Low-energy stacks dominating wearable and proximity-sensing applications. Hybrid Bluetooth-WiFi architectures are penetrating smart home segments previously segmented by protocol incompatibility.
- Zigbee:Mesh-native radios for sensor-dense industrial and residential deployments. Thread protocol convergence is fragmenting Zigbee's historical dominance in home automation.
Commanding premium positioning: Cellular. Retaining volume leadership: Wi-Fi and Bluetooth.
End User:
Procurement sophistication varies by buyer technical capacity. Manufacturing Plants specify integrated edge-to-cloud architectures, while Smart Cities fragment purchasing across municipal departments.
- Manufacturing Plants:Discrete and process automation operators deploying predictive maintenance and digital twin infrastructure. German automotive and French aerospace clusters are absorbing industrial gateway platforms with deep PLC integration requirements.
- Healthcare Providers:Hospitals and clinics integrating connected diagnostic and monitoring equipment. EMA cybersecurity guidelines mandate firmware signing and encrypted boot sequences, revalidation costs falling heaviest on smaller device vendors.
- Smart Cities:Municipal governments procuring streetlight controllers, environmental monitors, and traffic sensors. GDPR data-localization friction complicates multi-city analytics platforms.
- Retailers:Chains deploying inventory tracking, cold-chain monitoring, and customer analytics. Ultra-wideband positioning adoption is accelerating in Dutch and Belgian logistics hubs.
Driving deepest margin pools: Manufacturing Plants. Facing steepest compliance escalation: Healthcare Providers.
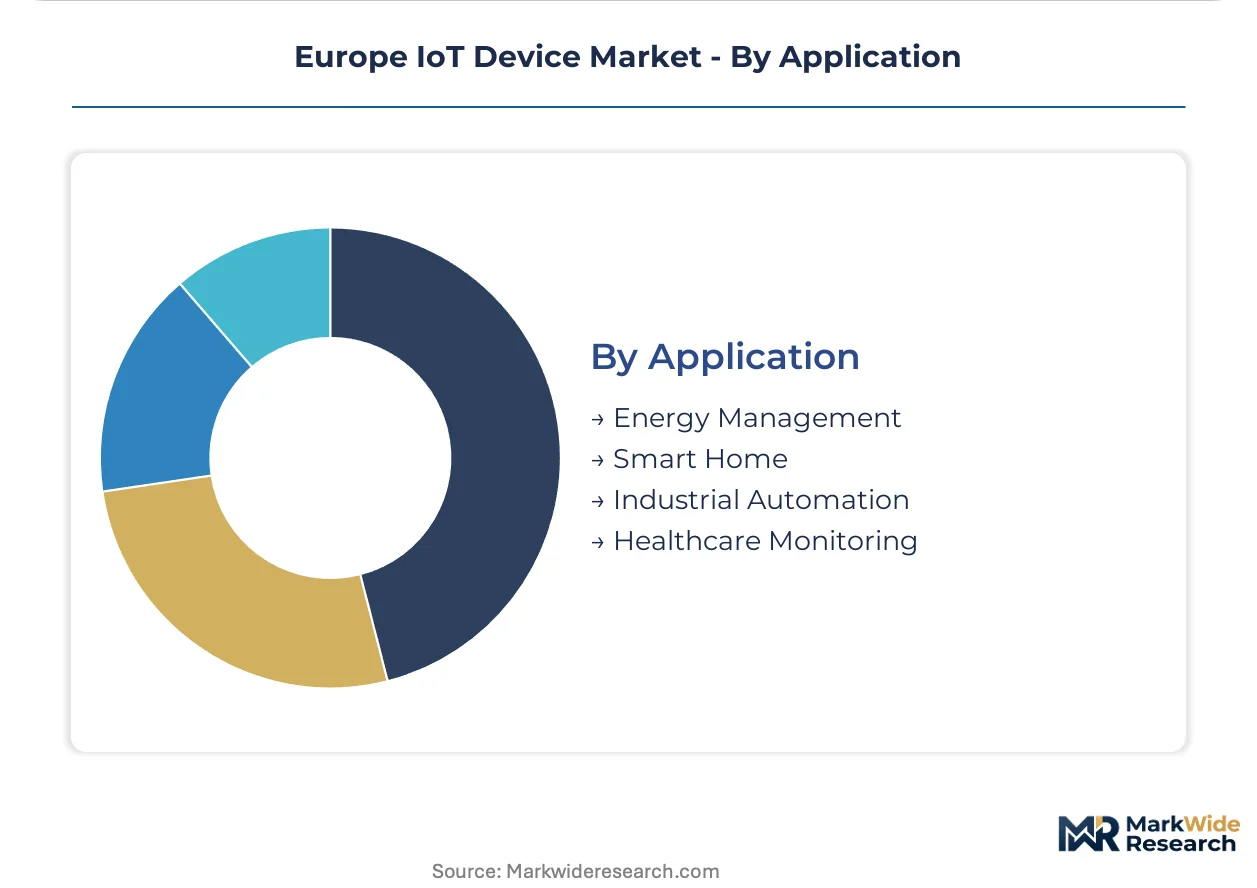
Application:
Use-case maturity determines pricing power and service attach rates. Industrial Automation commands multi-year service contracts, while Smart Home remains hardware-centric.
- Industrial Automation:Process optimization, predictive maintenance, and safety systems across factory floors. Extended service contracts and SIL certification requirements generate recurring revenue streams for gateway vendors.
- Healthcare Monitoring:Remote patient monitoring and connected diagnostic equipment. EMA guidelines and MDR conformity assessment create dual regulatory tracks for vendors serving diagnostic versus wellness segments.
- Energy Management:Grid-edge sensors, building automation, and demand-response systems. French utility modernization programs are opening procurement windows for industrial gateway platforms.
- Smart Home:Residential lighting, climate, security, and entertainment control. Subscription telemetry models are displacing perpetual-license sales among Netherlands and Belgium logistics operators, though residential adoption lags.
Generating highest service attach rates: Industrial Automation. Climbing the fastest: Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for IoT devices concentrates in German automotive clusters and French utility modernization programs, with regulatory compliance costs reshaping vendor prioritization across the continent.
Germany
Automotive OEMs in Stuttgart and Munich are scaling connected-vehicle telemetry programs, pulling cellular-enabled telematics control units into fleet-wide deployments. KBA vehicle-type approval requirements intersect with EU AI Act risk classifications for autonomous edge decision-making. The Baden-Württemberg industrial corridor anchors sensor foundry investments serving predictive maintenance programs at automotive stamping plants.
France
Utility modernization programs are opening procurement windows for grid-edge sensors and industrial gateway platforms in smart-grid infrastructure. ANSM cybersecurity guidelines for connected medical devices add compliance layers for diagnostic equipment vendors. The Île-de-France health technology cluster is absorbing EMA-mandated firmware revalidation costs faster than peripheral regions.
Netherlands
Logistics operators in Rotterdam and Amsterdam prefer subscription telemetry models covering hardware, connectivity, and analytics through per-vehicle monthly fees. GDPR data-localization mandates complicate cloud synchronization architectures for wearable device vendors. The Dutch-Belgian logistics corridor is accelerating ultra-wideband positioning adoption for indoor asset tracking.
United Kingdom
Building automation in London commercial real estate concentrates Wi-Fi-enabled demand for video-heavy and cloud-dependent applications. CE marking under RED extends certification cycles for multi-protocol transceivers entering European distribution. The Southeast England technology cluster faces REACH compliance cost inflation on solder alloys and flame-retardant plastics.
Italy
Spanish and Italian commercial real estate segments are absorbing high-throughput Wi-Fi radios for climate and security control systems. WPA3 security mandates are forcing firmware revalidation cycles for existing product lines. The Lombardy manufacturing belt is expanding smart-sensor deployments for equipment health monitoring under predictive maintenance programs.
Europe IoT Device Market Competitive Landscape
German producers anchor one tier in industrial gateway platforms and sensor foundries; Dutch and French specialists hold positions in connectivity modules and utility infrastructure. The vendor base stratifies around three strategic archetypes: integrated industrial conglomerates with deep PLC integration capabilities, semiconductor specialists competing on low-power microcontroller architectures, and telecom equipment vendors leveraging cellular infrastructure relationships. M&A activity concentrates on firmware cybersecurity capabilities, while geographic expansion targets French smart-grid procurement windows and German automotive telemetry programs.
Within the integrated industrial tier, Robert Bosch GmbH and Siemens AG exemplify archetypes combining sensor manufacturing with extended service contract structures. STMicroelectronics N.V. occupies a position among semiconductor specialists optimizing architectures for battery-constrained edge nodes. These three entities represent distinct competitive vectors: hardware-to-service integration, component-level power optimization, and safety-critical certification depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Siemens AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Schneider Electric |
| ABB Ltd. |
| Infineon Technologies |
| Ericsson |
| Nokia |
| Others |
Pricing and Supply Chain Analysis
Edge-native AI inference hardware is compressing unit economics while redistributing manufacturing concentration toward low-power foundry specialists. This transition simultaneously elevates R&D amortization costs for firmware-heavy architectures and fragments component sourcing across specialized geographies.
Pricing Analysis
Volume concentrates in Wi-Fi and Bluetooth modules at thin margins, while cellular-enabled industrial gateways capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with SIL-rated safety devices commanding multiples above RED-only hardware. Price differentiation hinges on EU AI Act compliance documentation and REACH substance certification. Cost compression in consumer-grade sensors is intensifying because Asian foundry overcapacity feeds module glut. Manufacturing plants show lowest price sensitivity due to service-contract bundling, while smart home retailers negotiate aggressively on per-unit hardware.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and French utilities are forcing qualification of secondary foundries for microcontroller wafers. Supply concentrates in Taiwan for advanced node fabrication, South Korea for memory integration, and Malaysia for backend packaging and testing. Raw material dependencies include rare-earth magnets for sensor actuation, high-purity silicon substrates, and REACH-compliant solder alloys. Single-source vulnerability runs through TSMC's dominance in sub-40nm low-power processes. Distribution runs through authorized distributors serving industrial integrators, with direct procurement relationships dominating high-volume cellular module sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IoT Device Market sits in a connectivity-transition phase, with cellular LPWAN architectures displacing legacy proprietary fieldbus installations across industrial floors.
For Market Incumbents: Anchor defensive positioning through captive sensor foundry investments in Germany and Poland, insulating against Asian supply disruption. Deepen firmware cybersecurity engineering benches to meet EMA guideline mandates before smaller competitors can revalidate product lines. Prioritize extended service contract structures that embed hardware refresh cycles, locking out modular competitors from manufacturing plant accounts. For New Entrants and Emerging Players: EU AI Act limited-risk classification pathways in France open a window for fixed-function edge devices without full AI system conformity burdens. Target French smart-grid infrastructure procurement windows where incumbent relationships remain underdeveloped. Pursue ultra-wideband positioning specialization for Dutch-Belgian logistics corridors, leveraging antenna design partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with firmware cybersecurity boutiques given EMA guideline enforcement as the catalyst for capability premiums. Five-to-ten year viability favors targets with embedded base service revenue rather than hardware-only models. Monitor CE marking timeline compression under RED as the inflection signal for consolidation pressure on undercapitalized module vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Firmware architecture redesign ahead of certification deadlines preserves market access for German automotive clients. |
| Sensor Foundry Capacity Expansion | Baden-Württemberg facility investments reduce REACH compliance friction and shorten procurement cycles for Bosch and Siemens. |
| Cellular Module Partnership | Nokia and Ericsson infrastructure relationships unlock utility-scale smart-grid deployments in France. |
| Cybersecurity Acquisition | Firmware signing and encrypted boot expertise addresses EMA guideline mandates for connected diagnostic equipment. |
| Bluetooth-WiFi Hybrid Launch | Converged radio architectures penetrate building automation segments previously segmented by protocol incompatibility in Spanish commercial real estate. |
Research Methodology
Multi-period observation of cellular module pricing trajectories, CE marking timeline durations, and predictive maintenance adoption rates anchored the trend analysis, supplemented by interviews with industrial gateway product managers, semiconductor procurement leads at German automotive OEMs, French utility smart-grid engineers, and EMA regulatory affairs specialists. Secondary validation drew from EU Radio Equipment Directive filing databases, REACH substance restriction updates, customs import records for IoT hardware, and hyperscaler edge infrastructure capex disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting across device type, connectivity technology, end user, and application dimensions informed the analytical framework across the projection horizon. CAGRs derived from logistic diffusion modeling of predictive maintenance program adoption, cellular LPWAN network coverage expansion, and EU AI Act implementation phase-ins. Industry-specific forecast inputs included KBA vehicle-type approval timelines and ANSM cybersecurity guideline revision schedules.
The model assumes a particular technology adoption path; alternative pathways for edge-native AI inference localization would alter the outlook if on-device training architectures bypass current risk-classification frameworks. Deviation in REACH substance restriction scope or EU AI Act enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Global IoT Elevators Market