
 Qatar Cybersecurity Market | 2026-2036
Qatar Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Cybersecurity Market Analytics
Managed security services is restructuring how Qatar's enterprises consume cyber protection, shifting capital expenditure into operational models with embedded threat intelligence. Palo Alto Networks dominates the high-end enterprise segment with platform consolidation. IBM Corporation anchors consulting-heavy engagements for government digital transformation. Barikat Cyber Security specializes in Arabic-language incident response and regional compliance.
Qatar cybersecurity encompasses hardware, software, and service layers designed to protect digital assets across on-premise, cloud, and hybrid infrastructures, with next-generation firewalls processing traffic at 100 Gbps and zero-trust architectures enforcing continuous verification. Network Security leads solution spending as Qatar's oil and gas operators harden SCADA and industrial control systems against targeted intrusions. Cloud Security represents the fastest-expanding solution category as sovereign cloud mandates push government workloads onto compliant hyperscale platforms. Managed Security Services captures the strongest margin pools by bundling 24/7 SOC operations with regulatory reporting.
The National Cybersecurity Agency enforces Qatar's Critical Information Infrastructure Protection regulations, mandating sector-specific baselines for energy, finance, and healthcare operators. The Qatar Central Bank issues binding cybersecurity guidelines for BFSI institutions, requiring annual penetration testing and incident disclosure protocols. Stakeholders must monitor how sovereign data localization rules intersect with multinational cloud provider architectures.
Market Dynamics
Qatar's cybersecurity landscape is being fundamentally restructured by sovereign cloud mandates that force government and critical infrastructure operators onto compliant domestic data centers, creating a parallel procurement ecosystem distinct from standard commercial IT channels.
Growth Catalysts
- Critical Information Infrastructure Protection regulations:The National Cybersecurity Agency mandates sector-specific baselines for energy, finance, and healthcare operators, creating compulsory upgrade cycles for legacy systems.
- SCADA hardening in oil and gas:Qatar's petroleum operators face intensified threat actor targeting, driving sustained investment in industrial control system monitoring and segmentation solutions.
- Lusail smart city deployment:The $45 billion urban development embeds cybersecurity into municipal infrastructure from inception, generating integrated platform demand across transportation, utilities, and public safety networks.
Market Restraints
- Specialized talent scarcity:Qatar's domestic workforce lacks depth in Arabic-language incident response and industrial control system forensics, forcing reliance on expensive expatriate specialists.
- Hyperscale provider concentration:Sovereign cloud requirements limit operator choice to a handful of certified multinational platforms, creating vendor lock-in and pricing power asymmetries.
- Legacy OT integration friction:Decades-old SCADA protocols in Ras Laffan industrial zones resist modern zero-trust architectures without costly operational downtime.
Strategic Opportunities
- Managed detection and response services:Mid-market enterprises in Doha's expanding fintech corridor seek 24/7 SOC capabilities without capital-intensive internal buildouts.
- Post-quantum cryptography preparation:Qatar National Bank and sovereign wealth funds are piloting quantum-resistant algorithms ahead of regional peers, creating first-mover advisory revenue pools.
- Education sector endpoint protection:Qatar Foundation's research universities and branch campuses represent an underpenetrated vertical with complex intellectual property protection requirements.
Industry Challenges
- Multi-framework compliance mapping:Operators must simultaneously satisfy Qatar Central Bank guidelines, NCA Critical Information Infrastructure mandates, and sector-specific healthcare or energy regulations.
- OT-IT convergence complexity:Petroleum engineers and cybersecurity teams operate with mismatched risk vocabularies, delaying unified governance frameworks in upstream operations.
Report Scope
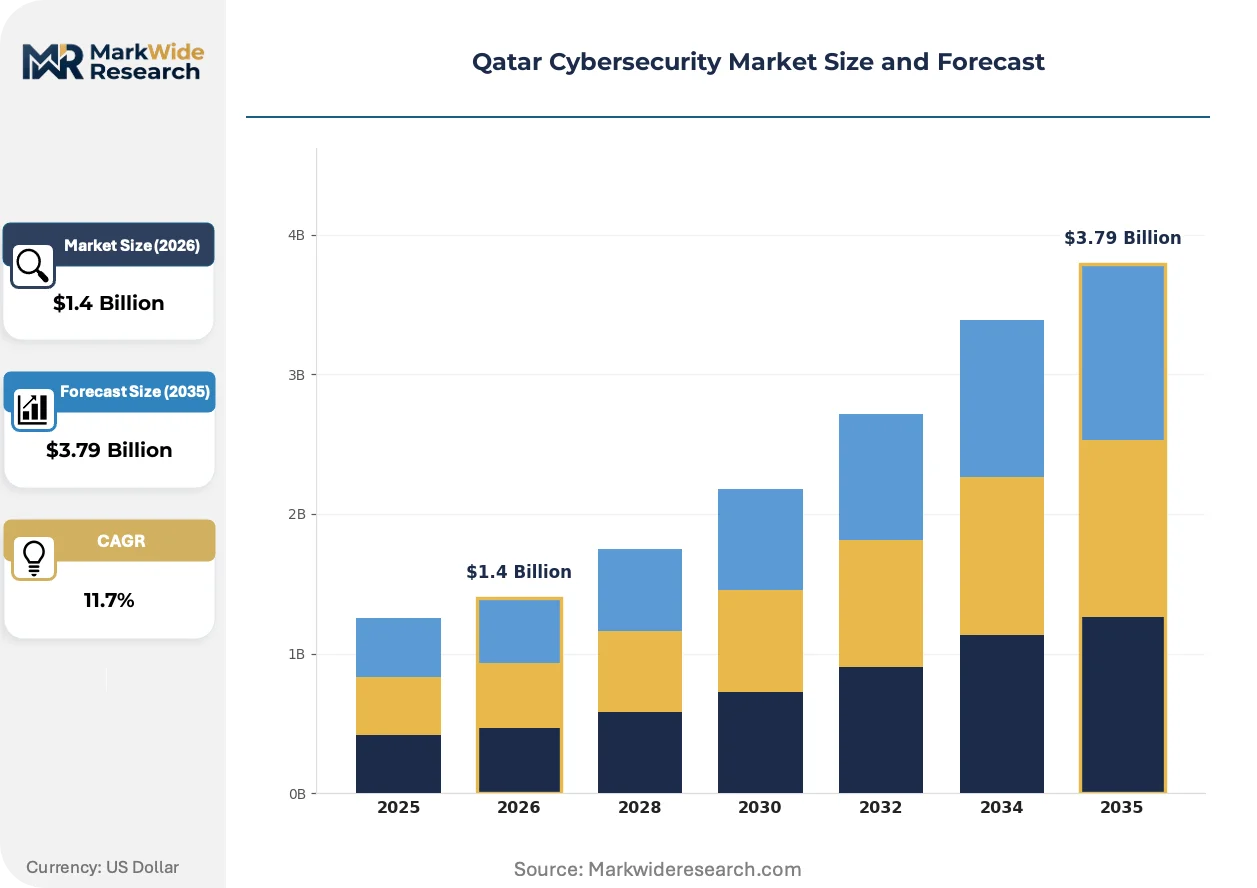
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Cybersecurity Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Endpoint Security, Network Security, Cloud Security, Application Security Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Government, BFSI, Healthcare, Telecom Service Type: Consulting, System Integration, Managed Security, Incident Response |
| Companies Covered | Palo Alto Networks, Arista Technologies, IBM Corporation, Barikat Cyber Security, QRTD Information Technology, Cisco Systems, Huawei Technologies, HIT Services, Fortinet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Cybersecurity Market Evolving Landscape
Zero-trust architecture deployment is accelerating across Qatar's financial and energy sectors, replacing perimeter-based security models with continuous verification protocols that treat internal networks as hostile by default.
Extended detection and response platforms are expanding into Qatar's mid-market enterprise segment, consolidating endpoint, network, and cloud telemetry into unified analyst workflows. Manufacturing and logistics operators in Mesaieed Industrial City are adopting these platforms faster than regional peers, compressing the traditional multi-vendor security stack into single-pane-of-glass consoles. This consolidation is forcing independent point-solution vendors to reposition around niche compliance reporting or specialized OT monitoring capabilities.
The National Cybersecurity Agency's 2023 Critical Information Infrastructure Protection amendments impose mandatory incident disclosure timelines and annual penetration testing for designated operators. Financial institutions must now report breaches within 72 hours, compressing response preparation cycles and driving retainer-based relationships with specialized forensics providers. Energy sector operators in Ras Laffan are investing heavily in tabletop exercise programs to meet these accelerated disclosure readiness requirements.
Outcome-based security contracting is displacing traditional hourly consulting arrangements among Qatar's largest government entities and sovereign wealth funds. Procurement teams at Qatar Investment Authority and Qatar Petroleum now specify measurable risk reduction targets rather than staff augmentation volumes, shifting vendor compensation toward achieved security posture improvements. This model is most visible in Doha's West Bay financial district, where CISOs face board-level pressure to demonstrate return on security investment through quantified threat exposure reduction.
Qatar Cybersecurity Market Segmentation
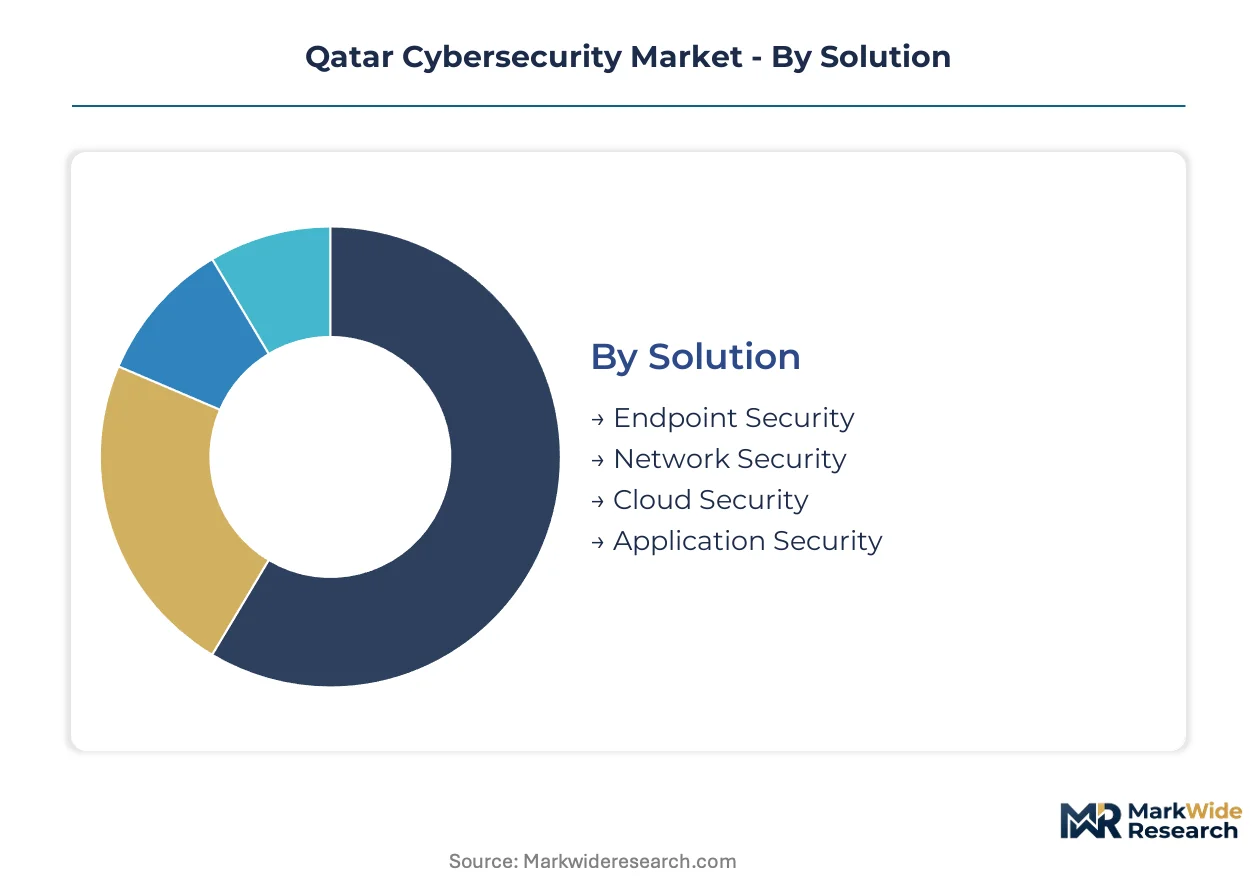
Qatar's cybersecurity procurement patterns fragment across four intersecting dimensions that determine technology selection, contract structure, and vendor engagement models. Each segmentation layer reveals distinct integration requirements between legacy infrastructure and emerging sovereign cloud mandates.
Solution:
Integration depth varies sharply — Network Security and Cloud Security function as embedded platform layers requiring architectural overhaul, while Endpoint and Application Security deploy more flexibly atop existing stacks.
- Network Security:Next-generation firewalls and segmentation appliances process traffic at 100 Gbps across Qatar Petroleum's Ras Laffan industrial zones. QatarEnergy operators drive sustained procurement as SCADA hardening mandates intensify targeting of upstream control systems.
- Cloud Security:Sovereign cloud compliance tools enforce data residency for government workloads migrating to certified hyperscale platforms. Lusail smart city developers generate integrated demand across transportation, utilities, and public safety networks as municipal infrastructure embeds security from inception.
- Endpoint Security:EDR and XDR platforms consolidate detection capabilities for Qatar Foundation's research universities and branch campuses.
- Application Security:SAST and DAST tools protect custom-developed fintech applications in Doha's West Bay financial district.
Volume placements concentrate in Network Security; the faster expansion belongs to Cloud Security.
Deployment:
Cost tiering separates capital-intensive on-premise builds from operational expenditure models favored by mid-market enterprises lacking internal security operations centers.
- Managed Services:24/7 SOC operations bundled with regulatory reporting capture the strongest margin pools in Qatar's market. Doha's expanding fintech corridor seeks these capabilities without capital-intensive internal buildouts, compressing procurement cycles for MSS providers.
- Hybrid:Split architectures accommodate petroleum operators bridging decades-old OT systems with modern zero-trust overlays. Ras Laffan industrial zones resist full cloud migration due to operational downtime risks from legacy protocol integration.
- On-Premise:Air-gapped deployments persist in Qatar Central Bank-regulated financial institutions with strict data sovereignty requirements.
- Cloud-Based:Native SaaS security tools gain traction among Qatar Investment Authority portfolio companies prioritizing agility over control.
Revenue concentration sits with Managed Services; the steepest climb belongs to Hybrid configurations.
End User:
Application criticality drives procurement sophistication — government and BFSI sectors face binding compliance deadlines absent in healthcare and telecom verticals.
- Government:National Cybersecurity Agency mandates enforce sector-specific baselines across ministries and sovereign wealth funds. Qatar Petroleum and Qatar Investment Authority procurement teams now specify measurable risk reduction targets rather than staff augmentation volumes.
- BFSI:Qatar Central Bank guidelines require annual penetration testing and 72-hour breach disclosure protocols. Financial institutions in West Bay face board-level pressure to demonstrate return on security investment through quantified threat exposure reduction.
- Healthcare:Hamad Medical Corporation facilities adopt endpoint protection for patient data systems with complex multi-framework compliance mapping.
- Telecom:Ooredoo and Vodafone Qatar harden 5G core networks against supply chain intrusions.
Contract value aggregates in Government; the most rapid scaling occurs in BFSI.
Service Type:
Customer maturity separates advisory-heavy engagements from operational delivery — consulting and integration dominate transformation phases, while managed services and incident response sustain ongoing relationships.
- Managed Security:Continuous monitoring and threat hunting services displace traditional hourly consulting arrangements among Qatar's largest entities. Outcome-based contracting ties vendor compensation to achieved security posture improvements.
- Incident Response:Retainer-based relationships with specialized forensics providers compress response preparation cycles under accelerated disclosure requirements. Arabic-language capabilities remain scarce, forcing reliance on expensive expatriate specialists.
- Consulting:Advisory services support post-quantum cryptography pilot programs at Qatar National Bank ahead of regional peers.
- System Integration:Deployment services bridge OT-IT convergence complexity where petroleum engineers and cybersecurity teams operate with mismatched risk vocabularies.
Recurring revenue pools deepest in Managed Security; the fastest share gain belongs to Incident Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar consumes cybersecurity solutions at rates exceeding domestic production capacity, forcing reliance on imported platforms and expatriate expertise. The emirate's procurement patterns concentrate in Doha and Lusail while industrial zones generate specialized demand for OT-hardened systems.
Doha Metropolitan Area
Financial institutions in West Bay drive enterprise-grade platform procurement as Qatar Central Bank mandates compress compliance timelines. The central bank's 72-hour breach disclosure rule forces retainer-based relationships with incident response specialists. CISOs at Qatar National Bank and sovereign wealth funds face board pressure to demonstrate quantified threat exposure reduction through outcome-based contracting.
Lusail Smart City
The $45 billion urban development embeds cybersecurity into municipal infrastructure from inception across transportation, utilities, and public safety networks. National Cybersecurity Agency sovereign cloud mandates push government workloads onto certified hyperscale platforms with compliant domestic data centers. Integrated platform demand spans smart grid monitoring, autonomous vehicle networks, and critical building management systems.
Ras Laffan Industrial City
QatarEnergy operators sustain procurement of SCADA-hardened segmentation appliances as upstream control systems face intensified threat actor targeting. Decades-old OT protocols resist modern zero-trust architectures without costly operational downtime, creating hybrid deployment friction. Petroleum engineers and cybersecurity teams operate with mismatched risk vocabularies, delaying unified governance frameworks.
Education City
Qatar Foundation's research universities and branch campuses represent an underpenetrated vertical with complex intellectual property protection requirements. Endpoint detection and response platforms consolidate capabilities across multi-institutional research networks with heterogeneous device populations. Post-quantum cryptography pilot programs at partner institutions generate first-mover advisory revenue pools ahead of regional peers.
Mesaieed Industrial Zone
Manufacturing and logistics operators adopt extended detection and response platforms faster than regional peers, compressing multi-vendor security stacks into single-pane-of-glass consoles. Mid-market enterprises seek managed detection and response capabilities without capital-intensive internal SOC buildouts. Independent point-solution vendors reposition around niche compliance reporting or specialized OT monitoring capabilities.
Qatar Cybersecurity Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light managed service providers for procurement share in Qatar's cybersecurity market. The vendor base organizes around three tiers: multinational platform consolidators with sovereign cloud certifications, regional specialists delivering Arabic-language incident response, and local system integrators bridging OT-IT convergence complexity. Dominant competitive moves include outcome-based contracting that ties vendor compensation to achieved security posture improvements, and strategic partnerships between hyperscale providers and domestic data center operators to satisfy data residency mandates.
Within the multinational platform tier, Palo Alto Networks anchors high-end enterprise engagements with consolidated security stacks, while IBM Corporation represents the consulting-heavy archetype for government digital transformation programs. Barikat Cyber Security occupies a specialist position focused on regional compliance and Arabic-language forensics capabilities. These three exemplify the competitive structure: global platforms compete on architectural integration, professional services firms compete on transformation advisory, and regional boutiques compete on linguistic and regulatory proximity.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Arista Technologies |
| IBM Corporation |
| Barikat Cyber Security |
| QRTD Information Technology |
| Cisco Systems |
| Huawei Technologies |
| HIT Services |
| Fortinet |
| Others |
Value Network & Pricing Analysis
Zero-trust architecture migration simultaneously compresses implementation costs and concentrates procurement power among certified platform vendors. Sovereign cloud mandates at Qatar's National Cybersecurity Agency reshape supplier economics by limiting eligible providers to hyperscale operators with domestic data center partnerships.
Pricing Analysis
Margin tightening in managed security services reflects outcome-based contracting adoption at Qatar Petroleum and Qatar Investment Authority. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth and Arabic-language support availability. Pricing pressure intensifies in cloud security as sovereign data residency requirements reduce vendor pool elasticity. Mid-market fintech operators in Doha's West Bay exhibit highest price sensitivity; government entities with sovereign wealth backing show lowest.
Supply Chain Analysis
Hardware refresh cycles and appliance refurbishment flows concentrate through Dubai's Jebel Ali logistics corridor before final Qatar deployment. Core platform components originate from Taiwan semiconductor foundries, USA-based security software development centers, and UAE regional distribution hubs. Supply chain risk centers on single-source vulnerability for certified sovereign cloud infrastructure. Distribution runs through value-added resellers with NCA compliance accreditation rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's cybersecurity market consolidates around platform vendors with sovereign cloud certifications, squeezing point-solution specialists unable to meet National Cybersecurity Agency data residency mandates.
For Market Incumbents: To counter hyperscale provider lock-in, Palo Alto Networks and IBM Corporation should deepen Arabic-language incident response capabilities and pursue backward integration into domestic SOC operations. Certification investment in Qatar Central Bank penetration testing frameworks anchors long-term retainer relationships. For New Entrants and Emerging Players: Cloud-native SaaS distribution channels offer lowest-friction entry into Qatar Foundation's Education City research networks, an underpenetrated vertical with complex intellectual property protection requirements. Post-quantum cryptography advisory services represent a white-space target with first-mover revenue potential. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational platform consolidators seeking regional compliance expertise. Long-term viability favors regional boutiques with Arabic-language forensics depth and NCA certification relationships. Practitioners should monitor sovereign cloud provider certification expansions as inflection signals for vendor pool widening.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Domestic data center alliances satisfy NCA data residency mandates for government workloads. |
| Arabic-Language SOC Buildout | Native incident response capabilities address talent scarcity forcing expatriate reliance. |
| OT-IT Integration Specialist Acquisition | Ras Laffan petroleum operators require unified governance bridging engineering and security teams. |
| Post-Quantum Cryptography Advisory Launch | Qatar National Bank pilots position ahead of regional peer institutions. |
| Outcome-Based Contracting Platform | Measurable risk reduction targets displace hourly consulting at sovereign wealth funds. |
Research Methodology
Document review covered National Cybersecurity Agency regulatory filings, Qatar Central Bank cybersecurity guidelines, and hyperscaler sovereign cloud certification disclosures, complemented by interviews with CISOs at Qatar Petroleum, Qatar National Bank, and Qatar Foundation, plus security procurement officers at Hamad Medical Corporation and Ooredoo. Secondary validation drew from SEC filings of listed cybersecurity vendors, customs import data for security hardware, and project development databases for Lusail smart city infrastructure. Bottom-up segmentation modeling triangulated against top-down market sizing from energy sector IT expenditure disclosures.
Market value and volume outputs derive from multi-dimensional segmentation across solution type, deployment model, end-user vertical, and service tier throughout the forecast period. The analytical framework modeled network security, cloud security, endpoint security, and application security as solution categories; managed services, hybrid, on-premise, and cloud-based as deployment modes; government, BFSI, healthcare, and telecom as end-user segments; and managed security, incident response, consulting, and system integration as service types. CAGRs were derived from regression analysis against Qatar's energy sector capital expenditure trajectories and sovereign cloud migration timelines.
The model holds under sustained enforcement of Critical Information Infrastructure Protection regulations; deviation in NCA certification requirements or sovereign cloud provider eligibility would shift competitive positioning. Forecasts reflect assumptions of continued SCADA hardening investment at Ras Laffan and Lusail smart city security integration spend. Practitioners should monitor Qatar Central Bank disclosure timeline amendments and post-quantum cryptography standardization signals for early indicators of contract structure evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
France Cybersecurity Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Oman Cybersecurity Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
Application Programming Interface Security Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
E-Mail Security Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Data Security Market
Cybersecurity
Poland Cybersecurity Market