
 Data Center Renovation Market | 2026-2036
Data Center Renovation Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Renovation Market Analysis
EU Energy Efficiency Directive enforcement is hardening the cost-of-entry calculus for legacy data center operators across Europe. Schneider Electric leverages its integrated power and cooling portfolio to anchor retrofit projects in constrained urban sites. Vertiv competes through thermal management specialization in high-density rack conversions. ABB sustains its position via energy management system integration that extends building-level automation into critical infrastructure environments.
Data center renovation encompasses the structural, mechanical, and electrical overhaul of existing computing facilities to extend operational life, typically involving replacement of uninterruptible power systems, cooling plant upgrades from N+1 to 2N redundancy, and hot-aisle containment retrofitting to achieve power usage effectiveness below 1.3. Infrastructure upgrade services dominate current contract value as hyperscale operators face end-of-life equipment cascades across facilities built during the 2010-2015 construction wave. Modular design adoption is accelerating fastest among edge computing sites where prefabricated power and cooling skids reduce on-site construction duration and permit risk.
FERC interconnection standards in the United States, EU Green Deal carbon reporting through CSRD, and China's GB 50174 data center design standards collectively shape equipment selection, disclosure obligations, and facility access across the three largest renovation addressable markets. Compliance timelines now overlap with equipment depreciation cycles, forcing capital planning integration between sustainability and infrastructure teams. Stakeholders must monitor how grid interconnection queues and carbon border adjustment mechanisms reshape the geographic prioritization of renovation spend versus greenfield alternatives.
Market Dynamics
The EU Energy Efficiency Directive is compressing refresh timelines for legacy facilities built during the 2010-2015 construction wave, forcing simultaneous replacement of end-of-life UPS systems and cooling infrastructure while meeting new PUE thresholds.
Growth Catalysts
- Grid constraint pressure:Frankfurt's data center cluster faces acute retrofit mandates from local heat reuse ordinances and transmission bottlenecks that prevent greenfield expansion.
- CSRD carbon disclosure:The EU's Corporate Sustainability Reporting Directive compels hyperscale operators to document Scope 2 emissions, accelerating equipment replacement cycles ahead of depreciation schedules.
- Liquid cooling retrofit kits:Direct-to-chip cooling modules are enabling 50kW+ rack density upgrades without full plant reconstruction, preserving stranded real estate assets.
Market Restraints
- Copper and electrical steel volatility:Transformer and busbar material costs swing with commodity markets, eroding fixed-price renovation contract margins.
- Specialized contractor scarcity:Germany and the Netherlands face acute shortages of technicians certified for live electrical work in operational facilities.
- Permit timeline uncertainty:Municipal zoning for diesel generator upgrades or cooling tower placement extends project schedules unpredictably across European jurisdictions.
Strategic Opportunities
- Edge computing retrofits:Telecommunication central offices in Spain and Italy present underpenetrated conversion opportunities for 5G-driven micro data centers.
- Waste heat district heating:Copenhagen and Stockholm regulatory frameworks mandate heat export, creating annuity revenue streams from cooling infrastructure.
- Prefabricated power skids:Factory-integrated UPS and switchgear modules compress on-site construction duration, reducing permit risk and labor exposure.
Industry Challenges
- Live migration complexity:Maintaining SLA uptime during phased electrical cutovers requires specialized sequencing protocols and redundant temporary power.
- Legacy BMS integration:Building management systems from the 2010s lack API compatibility with modern DCIM platforms, forcing middleware development or full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Renovation Market |
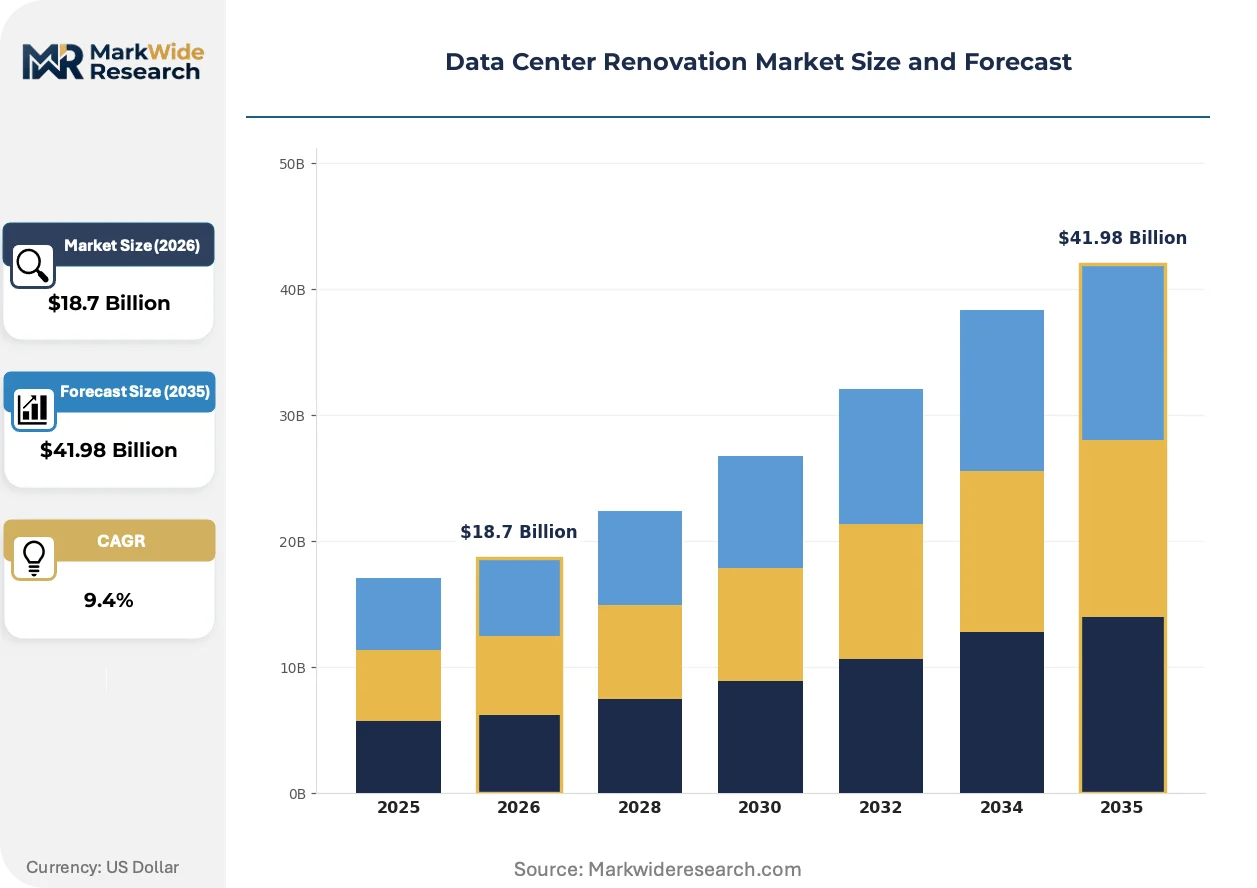
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure Upgrade, Cooling System Replacement, Power Supply Enhancement, Security Improvement Application: Hyperscale Data Centers, Colocation Facilities, Edge Computing Sites, Enterprise Data Centers Technology: Virtualization Solutions, Energy Management Systems, Modular Design, High-Density Racks End User: IT Companies, Telecom Providers, Government Agencies, Financial Institutions |
| Companies Covered | Schneider Electric, Vertiv, Dell, Hewlett Packard Enterprise, ABB, Eaton, Huawei, Rittal, Supermicro Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Renovation Market Emerging Trajectories
Digital twin deployment is compressing design validation cycles for complex retrofit projects. Operators now simulate thermal and electrical load scenarios before committing to physical infrastructure changes.
AI-driven predictive maintenance platforms are automating cooling plant optimization across heterogeneous equipment vintages. Colocation providers in Frankfurt and Amsterdam deploy these systems to extend chiller life while meeting F-Gas Regulation phase-down schedules. The technology is automating workload placement decisions that previously required manual engineering review.
F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing chiller replacement or costly refrigerant conversions. Operators face 2027 phase-down deadlines that overlap with equipment depreciation cycles, compressing capital planning windows. High-GWP refrigerant-dependent sites in Southern Europe confront earlier obsolescence than Nordic facilities already using ammonia or CO2 systems.
Performance-based service contracting is displacing traditional capex-heavy procurement for cooling and power infrastructure. Hyperscale operators in Ireland and Denmark now pay per kW of guaranteed cooling capacity rather than owning depreciating assets. This shift transfers operational risk to vendors while aligning incentives around PUE outcomes and uptime performance.
Data Center Renovation Market Segmentation
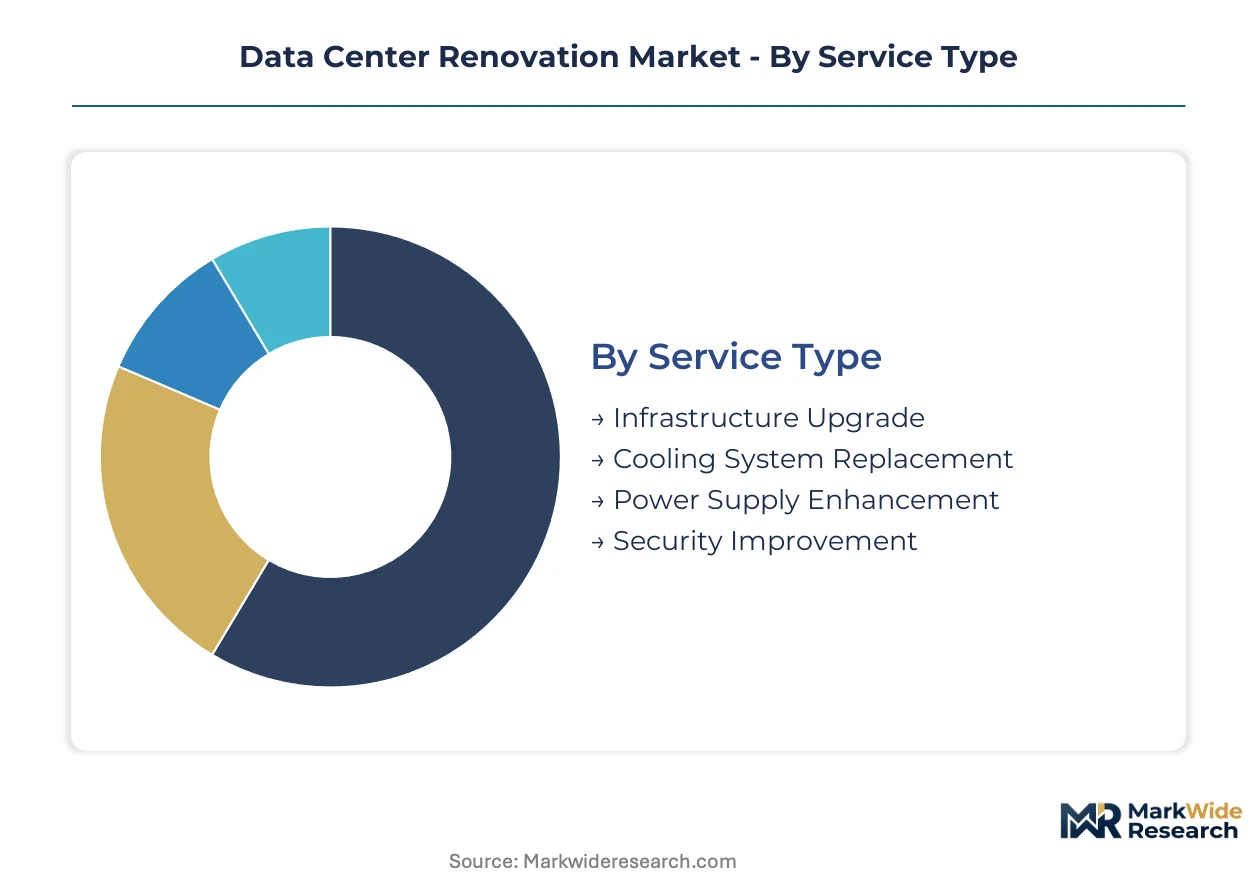
Renovation spending concentrates where aging infrastructure intersects with regulatory deadlines. Segment boundaries blur when cooling retrofits bundle with power upgrades and security hardening to meet compressed compliance windows.
Service Type:
Upgrade cycles accelerate where end-of-life equipment cascades coincide with new efficiency mandates.
- Infrastructure Upgrade:Structural, mechanical, and electrical overhaul extending facility operational life through UPS replacement, redundancy upgrades from N+1 to 2N, and hot-aisle containment retrofitting. Demand concentrates in Germany's Frankfurt cluster where grid constraints and local heat reuse ordinances force simultaneous multi-system replacement.
- Cooling System Replacement:Chiller plant modernization and refrigerant conversion driven by F-Gas Regulation phase-down deadlines. Operators in Southern Europe face earlier obsolescence than Nordic facilities using ammonia or CO2 systems.
- Power Supply Enhancement:Transformer and switchgear upgrades responding to rack density increases.
- Security Improvement:Physical and cyber hardening of perimeter systems and access controls.
Infrastructure Upgrade sits at the top of the volume ranking, with Cooling System Replacement climbing the fastest.
Application:
Facility scale determines retrofit complexity and vendor selection criteria.
- Hyperscale Data Centers:Massive single-tenant facilities requiring phased cutover protocols to maintain SLA uptime during electrical work. Ireland and Denmark operators increasingly adopt performance-based service contracting, paying per kW of guaranteed cooling capacity rather than owning depreciating assets.
- Colocation Facilities:Multi-tenant environments where tenant migration schedules constrain renovation timing. Frankfurt and Amsterdam providers deploy AI-driven predictive maintenance to extend chiller life while meeting disclosure obligations.
- Edge Computing Sites:Telecommunication central offices in Spain and Italy present conversion opportunities for 5G-driven micro data centers.
- Enterprise Data Centers:Captive facilities facing capital allocation competition from cloud migration alternatives.
Hyperscale Data Centers dominates contract value, while Edge Computing Sites expands most quickly.
Technology:
Technology selection hinges on compatibility with legacy building management systems and API integration requirements.
- Virtualization Solutions:Software-defined infrastructure enabling workload consolidation and reduced physical footprint. Demand concentrates among IT companies seeking to defer capital-intensive facility expansion through server utilization improvements.
- Energy Management Systems:Building-level automation extending into critical infrastructure with real-time PUE monitoring. Financial institutions in Frankfurt deploy these platforms to document Scope 2 emissions for CSRD compliance.
- Modular Design:Prefabricated power and cooling skids compressing on-site construction duration and permit risk.
- High-Density Racks:Direct-to-chip cooling modules supporting 50kW+ densities without full plant reconstruction.
Energy Management Systems leads deployment volume, with Modular Design gaining share fastest.
End User:
Procurement authority varies across organizational structures, influencing contract terms and risk allocation.
- IT Companies:Cloud service providers accelerating refresh cycles for aging facilities built during the 2010-2015 construction wave. These operators face overlapping compliance timelines and equipment depreciation cycles, forcing capital planning integration between sustainability and infrastructure teams.
- Telecom Providers:Central office conversion for 5G edge infrastructure. Spain and Italy present underpenetrated opportunities where prefabricated skids reduce labor exposure.
- Government Agencies:Public sector facilities subject to extended procurement timelines and budget cycle constraints.
- Financial Institutions:Trading and transaction processing sites with zero-tolerance downtime requirements driving redundant temporary power configurations.
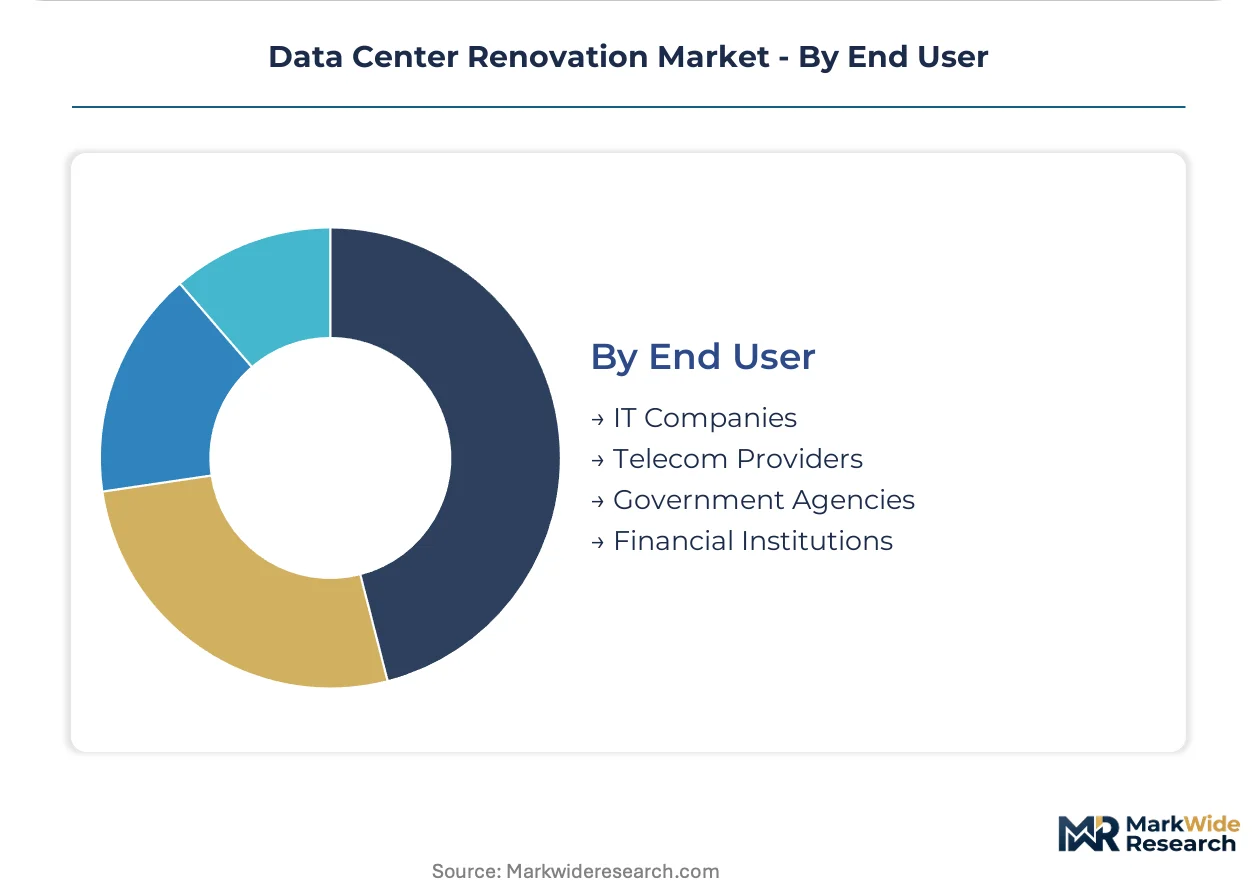
IT Companies occupies the largest share of renovation spend, with Telecom Providers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified electrical technicians in Germany, the Netherlands, and Ireland anchor European renovation capacity, while specialized contractors in Northern Virginia and Silicon Valley command premium rates for live-site work.
Germany
Frankfurt's data center cluster faces acute retrofit pressure from grid transmission bottlenecks and municipal heat reuse ordinances. The EU Energy Efficiency Directive mandates power usage effectiveness thresholds that compress equipment replacement timelines. Bavaria and Hesse host the densest concentrations of hyperscale facilities requiring simultaneous UPS and cooling plant overhaul.
United States
FERC interconnection standards reshape equipment selection for facilities seeking grid access in constrained markets. Northern Virginia's Ashburn corridor and Silicon Valley's Santa Clara County concentrate legacy facilities built during the 2010-2015 construction wave. Live electrical work protocols in these jurisdictions demand specialized contractors certified for operational facility modifications.
Ireland
Hyperscale operators in Dublin adopt performance-based service contracting for cooling infrastructure, paying per kilowatt of guaranteed capacity rather than owning depreciating assets. The EU's Corporate Sustainability Reporting Directive compels Scope 2 emissions documentation ahead of depreciation schedules. County Meath and Kildare host the primary facility clusters facing compressed compliance windows.
Netherlands
Amsterdam's data center providers deploy AI-driven predictive maintenance to extend chiller life while meeting F-Gas Regulation phase-down deadlines. Specialized contractor scarcity for live electrical work extends project timelines unpredictably. North Holland province concentrates the highest renovation contract values as multi-tenant colocation facilities navigate tenant migration constraints.
China
GB 50174 data center design standards govern equipment selection and facility access across the renovation addressable market. Beijing-Tianjin-Hebei and the Yangtze River Delta host aging facilities facing dual pressure from carbon reduction targets and rack density upgrades. Provincial grid interconnection queues reshape capital planning between renovation and greenfield alternatives.
Data Center Renovation Market Vendor Landscape
The competitive structure tilts toward integrated power and cooling specialists capable of anchoring complex retrofit projects in constrained urban sites. Market concentration reflects vendor capacity to bundle electrical infrastructure with thermal management under unified project delivery. Two strategic archetypes dominate: diversified industrial conglomerates with building automation heritage, and focused infrastructure specialists with critical power expertise. Competitive moves center on prefabricated skid manufacturing partnerships and energy management system integration capabilities.
Among integrated infrastructure providers, Schneider Electric and ABB exemplify the conglomerate archetype with building-level automation extending into critical environments. Vertiv occupies a distinct position as a thermal management specialist competing through high-density rack conversion expertise. These three anchors represent the primary competitive vectors: unified power-cooling portfolios, thermal specialization, and energy management integration.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Dell |
| Hewlett Packard Enterprise |
| ABB |
| Eaton |
| Huawei |
| Rittal |
| Supermicro Computer |
| Others |
Supply Flow & Price Mechanics
Copper and electrical steel volatility cascades from commodity exchanges through transformer and busbar manufacturing into fixed-price renovation contract margins, compressing vendor pricing power as hyperscale operators demand cost certainty across multi-year infrastructure refresh programs.
Pricing Analysis
Bundled infrastructure upgrade contracts command premium positioning against unbundled component procurement, with pricing stratifying across integrated power-cooling packages, standalone thermal retrofits, and discrete electrical component replacement. Price differentiation hinges on certification tier for live electrical work and volume scale of rack density upgrades, with hyperscale operators leveraging aggregate demand for preferential terms. Cost compression in standard-tier cooling retrofits is intensifying because F-Gas Regulation deadlines compress vendor delivery windows. Enterprise data centers exhibit highest price sensitivity due to capital allocation competition from cloud migration alternatives, while financial institutions prioritize uptime guarantees over unit cost minimization.
Supply Chain Analysis
Certified technician qualification gates constrain supply chain throughput, with factory-integrated UPS and switchgear modules requiring specialized assembly labor in Germany, the Netherlands, and Ireland. Manufacturing concentrates in these jurisdictions alongside Northern Virginia and Silicon Valley, where live-site electrical work protocols demand vendor proximity. Raw material dependencies center on copper winding stock, electrical-grade steel laminations, and refrigerant compounds subject to phase-down schedules. Single-source vulnerability runs through specialized contractors certified for operational facility modifications. Distribution runs through direct vendor-operator relationships for hyperscale accounts and regional systems integrators serving mid-tier colocation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Center Renovation Market reads as a late-cycle quality story where operator procurement shifts toward integrated power-cooling portfolios with guaranteed PUE outcomes and unified project accountability.
For Market Incumbents: Extend prefabricated skid manufacturing partnerships to compress on-site construction duration and reduce permit risk exposure in Frankfurt and Amsterdam where grid constraints prevent greenfield expansion. Anchor retrofit projects through energy management system integration that extends building-level automation into critical infrastructure environments, defending against thermal management specialists competing on high-density rack conversion expertise. For New Entrants and Emerging Players: Enter via underpenetrated telecommunication central office conversions in Spain and Italy where 5G-driven micro data center demand outpaces established vendor presence. Target edge computing retrofits with factory-integrated power and cooling modules that reduce labor exposure in jurisdictions facing acute technician shortages. Position through performance-based service contracting that transfers operational risk from capital-constrained operators. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized contractor scarcity extends project timelines unpredictably across European jurisdictions, favoring acquisition of certified live electrical work capabilities. Long-term viability centers on vendors with unified power-cooling portfolios capable of anchoring complex retrofit projects in constrained urban sites. The signal to watch is hyperscale operator adoption of per-kW guaranteed cooling capacity contracts that displace traditional capex-heavy procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Power Skid Manufacturing | Factory integration compresses on-site duration in permit-constrained Frankfurt and Amsterdam clusters. |
| AI-Driven Predictive Maintenance Platform Deployment | Colocation providers in Frankfurt extend chiller life while meeting F-Gas Regulation disclosure obligations. |
| Waste Heat District Heating Infrastructure | Copenhagen and Stockholm regulatory mandates create annuity revenue streams from cooling plant exports. |
| Direct-to-Chip Cooling Retrofit Kit Development | Liquid cooling modules enable 50kW+ rack densities without full plant reconstruction in stranded assets. |
| Energy Management System Integration | Building automation extension into critical infrastructure supports CSRD Scope 2 emissions documentation. |
Methodological Framework
Coverage spans Germany, the United States, Ireland, the Netherlands, and China, with primary inputs from each market combining structured interviews with data center infrastructure executives, facility engineering directors, procurement leads at hyperscale operators, and certified electrical contractors with live-site work credentials. Secondary validation draws from FERC interconnection filings, EU Energy Efficiency Directive implementation guidance, GB 50174 design standard documentation, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline assessment triangulates against top-down market sizing across service type, application, technology, and end user segmentation.
Rate-of-change decomposition separates equipment replacement cycle acceleration from regulatory deadline compression and rack density upgrade demand across the projection horizon. Segmentation dimensions modeled include infrastructure upgrade intensity, cooling system replacement urgency, power supply enhancement scale, and facility scale tier from edge computing through hyperscale. CAGRs derive from equipment vintage analysis overlaid with compliance timeline clustering and contractor capacity constraints. Forecast inputs incorporate grid interconnection queue depth and carbon border adjustment mechanism exposure.
Inputs from hyperscale operator procurement teams and specialized electrical contractors were available through the study window; gaps in real-time commodity price indexing for copper and electrical steel introduce uncertainty bands around fixed-price contract margin assumptions. Forecasts reflect documented assumptions regarding F-Gas Regulation enforcement consistency and municipal heat reuse ordinance adoption velocity. A model refresh is warranted upon material change in EU grid interconnection priority protocols or CSRD disclosure requirement scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Chile Data Center Market