
 Global Dye-Sensitized Solar Cells (Dssc) Market | 2026-2036
Global Dye-Sensitized Solar Cells (Dssc) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dye-Sensitized Solar Cells (Dssc) Market Foresight
Building-integrated photovoltaics is recalibrating demand patterns for dye-sensitized architectures across commercial and residential construction. Exeger Operations AB leverages its proprietary Powerfoyle material to dominate indoor and low-light energy harvesting for consumer devices. Fujikura Ltd. anchors its position through specialized manufacturing of flexible DSSC substrates for automotive and telecommunications applications. Solaronix SA competes via deep specialization in photoelectrochemical electrolytes and custom module engineering for research clients.
Dye-sensitized solar cells employ a photoanode of titanium dioxide nanoparticles coated with organic or organometallic dye sensitizers, immersed in an electrolyte containing a redox mediator such as iodide/triiodide, generating electron flow under visible light even at low irradiance levels. Flexible DSSC leads commercial deployment due to compatibility with curved architectural surfaces and wearable form factors, while solid-state technology variants capture expanding margin pools by eliminating liquid electrolyte leakage risks in portable electronics and IoT sensor networks. Tandem DSSC configurations represent the fastest-growing technology segment as stacked junction designs push power conversion efficiencies toward competitive thresholds for building-integrated installations.
EMA guidelines on photovoltaic device biocompatibility, REACH substance restrictions on volatile electrolyte components, and Japan's METI feed-in tariff revisions for building-integrated systems collectively shape product certification pathways and market access conditions across Europe and East Asia. The EU AI Act and CSRD reporting requirements are extending disclosure obligations to embedded energy systems in smart buildings, tightening supply chain documentation for DSSC module imports. Stakeholders must monitor evolving electrolyte material classifications under ECHA substance review cycles and anticipate METI efficiency benchmarking updates that could redirect procurement toward solid-state architectures.
Market Dynamics
Building-integrated photovoltaics is compressing the adoption timeline for dye-sensitized architectures as architects and developers prioritize aesthetic solar integration over conventional panel efficiency metrics.
Growth Catalysts
- EU Green Deal procurement mandates:Public building renovations across Germany, France, and Italy now require renewable energy integration, creating standardized demand channels for semi-transparent DSSC facades.
- Low-light performance thresholds:Indoor photovoltaic applications in retail environments and smart building corridors exploit DSSC sensitivity at irradiance levels below conventional silicon viability.
- South Korea urban density:Seoul's vertical construction boom and rooftop utilization restrictions favor thin-film solar solutions that conform to curved architectural geometries.
Market Restraints
- Ruthenium dye supply concentration:Organometallic sensitizer precursors depend on limited refinery capacity in South Africa and Russia, exposing module manufacturers to geopolitical input volatility.
- Iodide electrolyte REACH restrictions:ECHA substance review cycles threaten reclassification of volatile redox mediators, forcing reformulation investments ahead of compliance deadlines.
- Perovskite tandem substitution:Hybrid organic-inorganic alternatives achieve comparable low-light performance with simpler manufacturing, eroding DSSC differentiation in consumer electronics.
Strategic Opportunities
- Japan METI feed-in tariff revisions:Building-integrated system premiums now explicitly include aesthetic performance criteria, advantaging DSSC over conventional panels in heritage district retrofits.
- Automotive interior energy harvesting:Dashboard-integrated photovoltaic sensors and ambient lighting power systems represent untapped vehicle electrification adjacencies.
- Solid-state electrolyte convergence:Polymer gel and ionic liquid architectures eliminate leakage risks, opening medical device and wearable applications previously closed to liquid-cell designs.
Industry Challenges
- Photoelectrochemical engineering talent scarcity:Specialized expertise in nanoparticle synthesis and dye anchoring chemistry concentrates in Swiss and Japanese research institutes, constraining manufacturing scale-up.
- EMA biocompatibility certification timelines:Implantable and skin-contact applications require extended toxicological testing protocols that delay commercialization by 18-24 months.
- Module-to-inverter integration complexity:Low-voltage DSSC output mismatches with standard power electronics, demanding custom conditioning hardware for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dye-Sensitized Solar Cells (Dssc) Market |
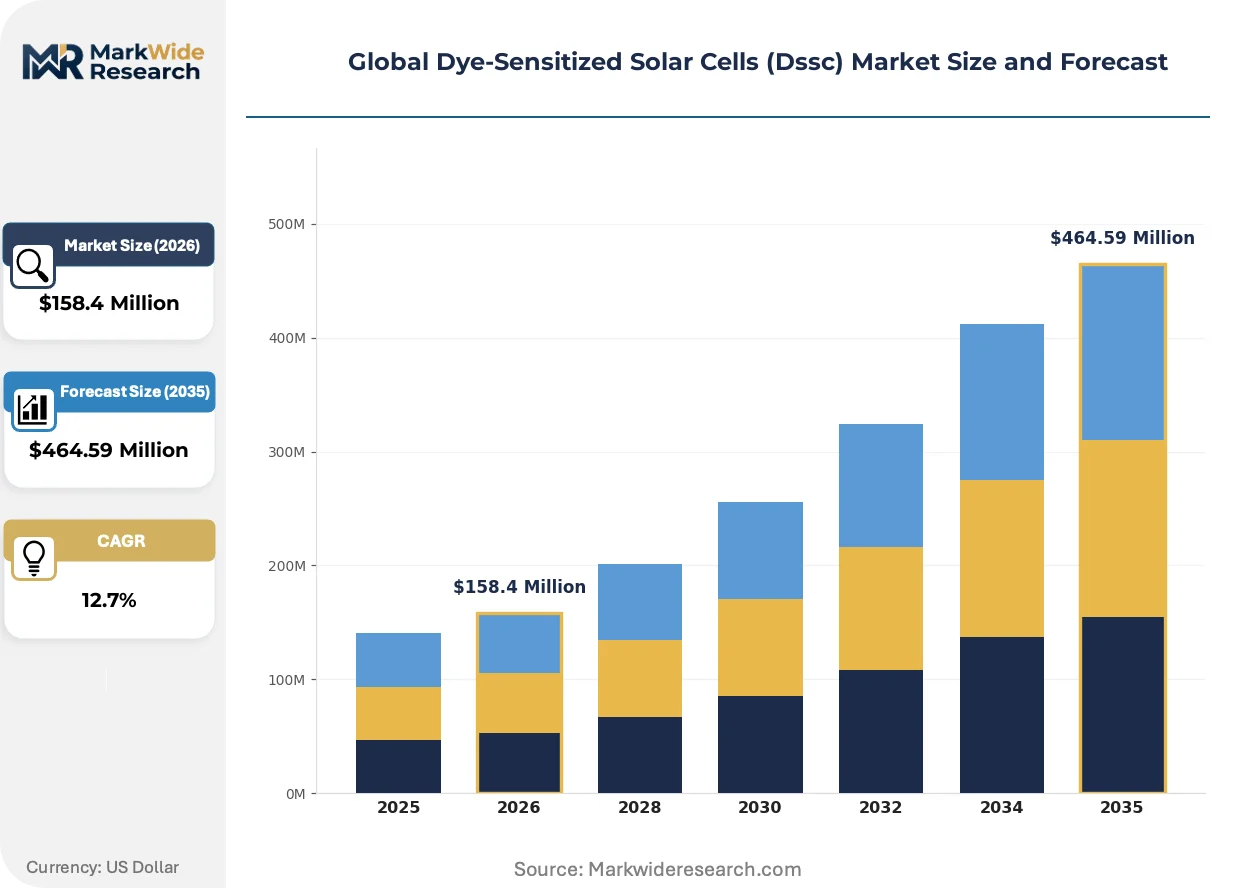
| Market Size in 2026 | $158.4 Million |
| Market Size in 2035 | $464.59 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible DSSC, Rigid DSSC, Transparent DSSC, Tandem DSSC Technology: Photoelectrochemical, Solid-State, Gel Electrolyte, Quasi-Solid Electrolyte Application: Building-Integrated Photovoltaics, Portable Electronics, Wearable Devices, IoT Sensors End User: Research Institutes, Telecommunications, Consumer Electronics, Automotive OEMs |
| Companies Covered | Exeger Operations AB, Fujikura Ltd., Solaronix SA, 3GSolar Photovoltaics, Greatcell Solar, Ricoh, Sharp Corporation, Dyenamo AB, Peccell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dye-Sensitized Solar Cells (Dssc) Market Shifts & Advancements
Material substitution and regulatory disclosure requirements are compressing product development cycles while expanding the addressable application space beyond conventional photovoltaic markets.
Solid-state electrolyte architectures are overtaking liquid-cell designs in portable electronics and IoT sensor deployments. Wearable manufacturers in Japan and South Korea now specify gel-based DSSC for fitness trackers and health monitors. This transition eliminates encapsulation failure modes and extends operational lifespan in humid environments, compressing warranty risk premiums for device OEMs.
CSRD reporting obligations and EU AI Act documentation requirements now extend to embedded energy systems in smart buildings. Real estate investment trusts and commercial developers must disclose supply chain provenance for photovoltaic materials. German and Dutch building certification schemes have responded by integrating DSSC module traceability into BREEAM and LEED-equivalent scoring, redirecting procurement toward suppliers with established substance documentation.
Buyer concentration in commercial construction is consolidating specification authority among a handful of multinational architecture-engineering firms. These firms now maintain pre-approved photovoltaic material libraries that exclude uncertified suppliers. Japanese and German engineering consultancies have tightened their vendor qualification protocols, forcing smaller DSSC manufacturers to pursue third-party validation or abandon commercial building channels entirely.
Global Dye-Sensitized Solar Cells (Dssc) Market Segmentation
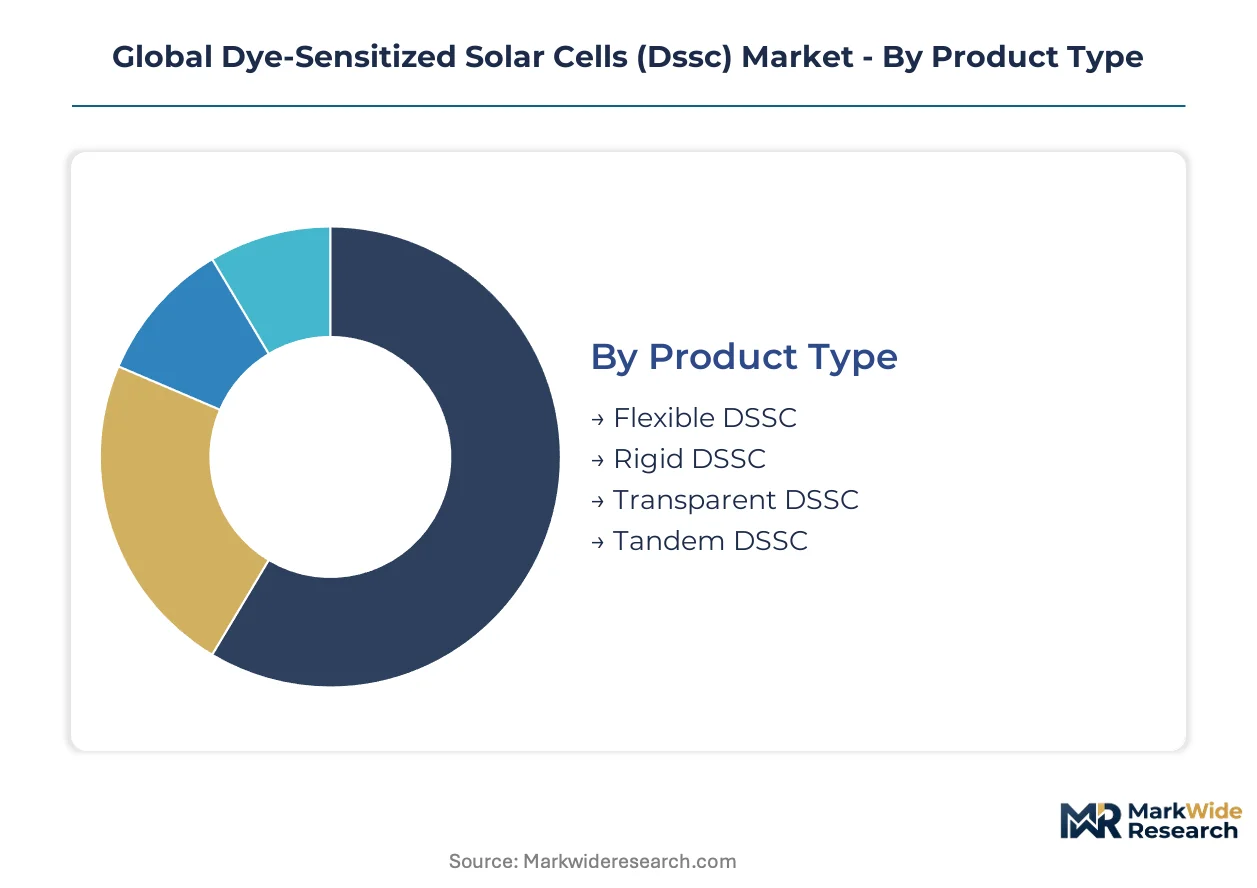
DSSC technology fragments across four orthogonal dimensions that determine manufacturing investment profiles and customer access pathways. Product type and technology choices lock in capital equipment requirements, while application and end-user selections dictate certification complexity and margin structures.
Product Type:
Capital intensity varies dramatically across substrate architectures, with tandem and flexible configurations demanding specialized deposition equipment that rigid glass-based lines cannot repurpose.
- Flexible DSSC:Polymer or metal foil substrates enable roll-to-roll coating of titanium dioxide nanoparticle layers. Demand concentrates in Japan and South Korea for curved building facades and wearable integration, driven by Seoul's vertical construction density restrictions that favor conformable photovoltaic surfaces.
- Tandem DSSC:Stacked junction designs pair DSSC absorbers with complementary bandgap materials to push power conversion efficiencies toward silicon-competitive thresholds. Germany's heritage district retrofits under METI-influenced aesthetic criteria drive procurement, though manufacturing requires sequential deposition chambers that triple equipment costs versus single-junction lines.
- Rigid DSSC:Glass substrate architectures dominate research-scale production with established supply chains for titanium dioxide pastes and dye sensitizers.
- Transparent DSSC:Semi-transparent variants trade efficiency for visible light transmission in window-integrated applications.
Most installed capacity flows through Flexible DSSC. Expansion is steepest in Tandem DSSC.
Technology:
Electrolyte architecture determines operational lifespan and regulatory exposure, with liquid systems facing REACH substance restrictions that solid-state alternatives bypass.
- Solid-State:Polymer and small-molecule hole conductors replace volatile redox mediators, eliminating encapsulation failure modes in portable electronics. South Korean wearable manufacturers specify gel-derived architectures for fitness trackers, compressing warranty risk premiums through humidity-resistant operation.
- Photoelectrochemical:Conventional iodide/triiodide liquid electrolytes deliver proven low-light sensitivity but face ECHA reclassification threats that force reformulation investments ahead of compliance deadlines.
- Gel Electrolyte:Viscous polymer-solvent hybrids retain ionic conductivity while reducing leakage probability in medical device applications.
- Quasi-Solid Electrolyte:Nanoparticle-thickened electrolytes bridge liquid and solid performance characteristics for IoT sensor networks.
Volume concentrates in Photoelectrochemical systems. Steepest expansion occurs in Solid-State architectures.
Application:
Customer procurement authority consolidates among distinct buyer types—architects specifying building systems versus OEM engineers designing embedded power—creating divergent sales channel requirements.
- Building-Integrated Photovoltaics:Semi-transparent facades and rooftop installations exploit DSSC performance under diffuse irradiance where silicon viability collapses. EU Green Deal procurement mandates across Germany, France, and Italy create standardized demand channels for aesthetic solar integration in public building renovations.
- Portable Electronics:Indoor energy harvesting for retail displays and smart building corridors leverages sub-lux sensitivity thresholds. Japanese consumer device OEMs integrate DSSC into ambient-powered sensors, though perovskite alternatives erode differentiation through simpler manufacturing.
- Wearable Devices:Skin-contact and garment-integrated applications require EMA biocompatibility certification that extends timelines 18-24 months.
- IoT Sensors:Low-power wireless nodes in smart buildings and industrial monitoring deploy DSSC for maintenance-free operation.
Building-Integrated Photovoltaics captures the dominant revenue share. Portable Electronics gains share fastest.
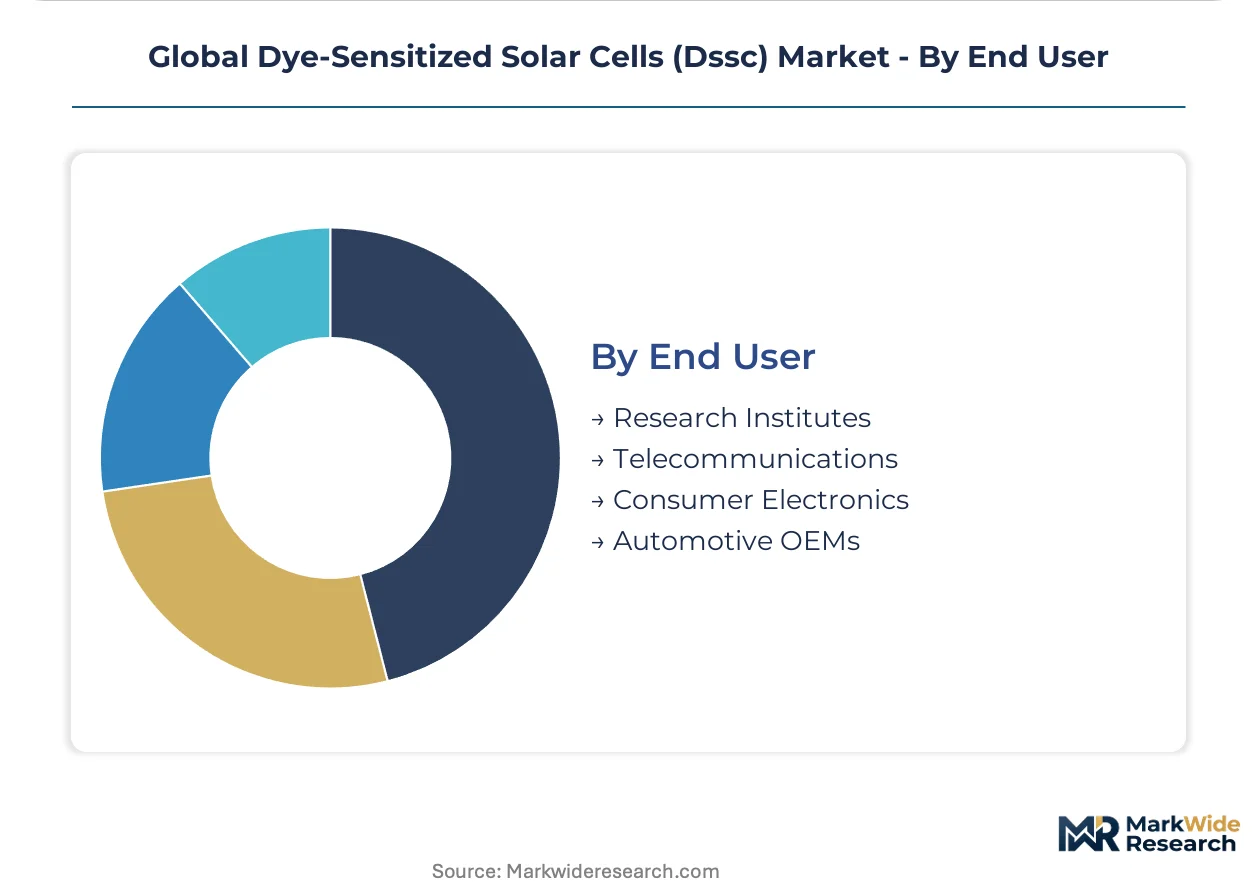
End User:
Research institutes tolerate performance variability and extended lead times that commercial OEMs reject, segmenting supplier capabilities and pricing power.
- Consumer Electronics:Device OEMs in Japan and South Korea demand traceable supply chains and REACH-compliant material documentation under CSRD-extended disclosure obligations. Exeger Operations AB and Fujikura Ltd. anchor qualification programs with established electrolyte substance libraries.
- Research Institutes:Academic and national laboratory procurement prioritizes custom module geometries and experimental dye formulations over manufacturing scale. Solaronix SA competes through photoelectrochemical electrolyte specialization and flexible engineering protocols.
- Telecommunications:Base station and network infrastructure operators specify DSSC for remote power in grid-constrained locations.
- Automotive OEMs:Dashboard-integrated sensors and ambient lighting systems represent emerging vehicle electrification adjacencies with untapped specification development.
Research Institutes account for the deepest historical penetration. Consumer Electronics shows the steepest order book expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined substance certification pathways, exploiting gaps between ECHA's REACH enforcement and Japan's METI efficiency benchmarking timelines.
Germany
Heritage district retrofits in Berlin and Munich drive specification of semi-transparent DSSC facades under EU Green Deal procurement mandates. ECHA substance review cycles on iodide electrolytes force domestic reformulation investments ahead of compliance deadlines. The Dresden-Leipzig corridor hosts specialized nanoparticle synthesis facilities serving architectural glass integrators.
Japan
METI feed-in tariff revisions explicitly weight aesthetic performance criteria, advantaging DSSC over conventional panels in dense urban corridors. The country's national regulator maintains stringent efficiency benchmarking that redirects procurement toward solid-state architectures. Osaka-based engineering consultancies consolidate specification authority through pre-approved photovoltaic material libraries.
South Korea
Seoul's vertical construction boom and rooftop utilization restrictions favor thin-film solutions conforming to curved geometries. Domestic wearable manufacturers specify gel-derived DSSC architectures for fitness trackers under humidity-resistant operation standards. The Busan-Ulsan industrial cluster houses roll-to-roll coating facilities for polymer substrate production.
United States
Indoor photovoltaic applications in retail environments exploit DSSC sensitivity below conventional silicon viability thresholds. EPA and state-level environmental regulations create fragmented compliance landscapes that slow electrolyte import standardization. California's building efficiency codes increasingly reference embedded energy system disclosure requirements for commercial developments.
Switzerland
Photoelectrochemical engineering expertise concentrates in Swiss research institutes, constraining manufacturing scale-up beyond pilot production. Swissmedic and EU regulatory alignment requirements shape biocompatibility certification timelines for medical device applications. The Lake Geneva region anchors specialized dye anchoring chemistry development for research-scale module production.
Global Dye-Sensitized Solar Cells (Dssc) Market Competitive Landscape
Strategic partnerships dominate the current landscape as specialized material suppliers ally with architectural system integrators to bypass certification bottlenecks. The vendor base separates into three tiers: multinational conglomerates with captive electrolyte supply, mid-scale specialists in flexible substrate architectures, and research-oriented custom module engineers. Technology licensing agreements and backward integration into dye synthesis represent the primary competitive vectors as firms seek to insulate margins from ruthenium precursor volatility.
Among Nordic-origin material innovators, Exeger Operations AB and Dyenamo AB exemplify the specialized electrolyte archetype, occupying positions between research-scale chemistry and commercial module qualification. Japanese industrial conglomerates Fujikura Ltd., Sharp Corporation, and Ricoh anchor the scale-driven tier, leveraging established manufacturing infrastructure from adjacent electronics segments. Swiss-based Solaronix SA represents the research-service hybrid model, bridging photoelectrochemical expertise with custom engineering protocols for academic and national laboratory procurement channels.
| Leading Market Players |
|---|
| Exeger Operations AB |
| Fujikura Ltd. |
| Solaronix SA |
| 3GSolar Photovoltaics |
| Greatcell Solar |
| Ricoh |
| Sharp Corporation |
| Dyenamo AB |
| Peccell Technologies |
| Others |
Supply & Pricing Matrix
Japanese and South Korean consumer electronics OEMs concentrate procurement authority through pre-approved vendor qualification programs, compressing margin structures around REACH-compliant material documentation and solid-state electrolyte performance tiers rather than commodity efficiency metrics.
Pricing Analysis
Distributor margins for DSSC modules typically absorb 15-25 points before architectural system integrators apply project-based markups for building-integrated installations. Three-tier pricing structure across premium, standard, and economy levels separates tandem configurations with silicon-competitive efficiency from flexible substrates for curved facades and research-grade rigid panels. Cost compression in standard-tier flexible modules is intensifying because South Korean roll-to-roll coating capacity expansion feeds oversupply into the wearable device channel. Research institutes show least price sensitivity due to tolerance for extended lead times and custom geometries, while commercial construction procurement teams negotiate hardest on volume commitments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Japanese consumer device manufacturers, while architectural system integrators in Germany and South Korea source through specialized distributors with substance certification libraries. Ruthenium dye precursor refining concentrates in South Africa and Russia, titanium dioxide nanoparticle synthesis anchors in Germany and Japan, and polymer substrate roll-to-roll coating clusters in South Korea. The supply chain draws from iodide electrolyte formulations facing ECHA reclassification exposure and solid-state polymer gel alternatives with constrained qualified supplier bases. Single-source vulnerability in organometallic sensitizer precursors exposes module manufacturers to geopolitical input disruption. Distribution runs through engineering consultancies maintaining pre-approved material libraries that exclude uncertified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DSSC demand is shifting toward premium solid-state architectures as EMA biocompatibility certification and METI aesthetic performance criteria redefine procurement specifications beyond raw efficiency metrics.
For Market Incumbents: Acquire specialized photoelectrochemical engineering talent concentrated in Swiss and Japanese research institutes to defend against perovskite tandem substitution threats. Establish captive ruthenium dye precursor supply through backward integration into South African or Russian refinery partnerships, or accelerate solid-state electrolyte reformulation to bypass REACH substance restrictions entirely. Channel control through pre-approved vendor qualification programs with German and Dutch engineering consultancies locks out emerging competitors from commercial building procurement. For New Entrants and Emerging Players: Solid-state electrolyte architectures for medical device and wearable applications offer the most penetrable white-space target, as EMA certification timelines have deterred established players from pursuing skin-contact revenue pools. Automotive interior energy harvesting for dashboard-integrated sensors represents an adjacent specification channel with untapped OEM procurement development. A technology-first go-to-market angle emphasizing humidity-resistant polymer gel operation in South Korean wearable manufacturing qualification programs bypasses liquid-cell incumbent scale advantages. For Investors and Strategic Acquirers: Japanese industrial conglomerates with adjacent electronics manufacturing infrastructure are the most active acquirers in this space, seeking electrolyte material specialization to complete captive supply chains. The 5-10 year viability window hinges on solid-state architectures achieving cost parity with liquid-cell production while maintaining biocompatibility certification pathways. Acquisition target archetypes include Swiss and Nordic research-service hybrids with established photoelectrochemical expertise and custom module engineering protocols. The signal to watch is METI efficiency benchmarking updates that could redirect procurement volumes toward qualified solid-state suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Precursor Supply | Insulates margins from South African and Russian ruthenium refinery volatility. |
| Solid-State Electrolyte Certification Investment | Opens EMA biocompatibility pathways for medical device and wearable revenue pools. |
| Architectural System Integrator Partnership | Secures placement in German and Dutch pre-approved photovoltaic material libraries. |
| Roll-to-Roll Coating Capacity Expansion | Captures Seoul vertical construction demand for curved conformable substrates. |
| Research Institute Collaboration Program | Accesses Swiss photoelectrochemical expertise for custom module engineering protocols. |
Research Methodology
Direct dialogue with DSSC module engineering directors, architectural specification consultants, EHS compliance officers at consumer electronics OEMs, and photoelectrochemical research leads grounded the qualitative foundation. Secondary validation drew from ECHA substance review databases, METI feed-in tariff revision filings, EU Green Deal procurement mandate documentation, and SEC disclosures from Japanese industrial conglomerates with photovoltaic segments. Bottom-up module shipment estimates by product type and technology architecture triangulated against top-down building-integrated photovoltaic demand projections across Germany, Japan, and South Korea.
Bottom-up modeling segmented volume and value across flexible, tandem, rigid, and transparent product types; solid-state, photoelectrochemical, gel, and quasi-solid electrolyte technologies; building-integrated, portable electronics, wearable, and IoT sensor applications; and consumer electronics, research institute, telecommunications, and automotive OEM end users. CAGRs derived from installation growth trajectories in heritage district retrofits, vertical construction density restrictions, and indoor photovoltaic penetration in retail environments. Forecast inputs included EMA biocompatibility certification timeline assumptions and ECHA substance reclassification probability assessments across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to perovskite tandem substitution rates, ruthenium supply disruption events, and METI efficiency benchmarking revisions that could redirect procurement architectures. Periodic stress-testing of base assumptions against regulatory filing updates and OEM qualification program changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Rooftop Sales Market