
 Cordless Router Market | 2026-2036
Cordless Router Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Router Market Analytics
Buyer concentration among construction contractors is rebalancing as mid-sized woodworking shops and independent tradespeople expand cordless router procurement. Robert Bosch GmbH leverages its brushless motor IP across European and North American distribution channels. Makita Corporation anchors its position through dense battery platform ecosystems that lock in repeat tool purchases. Techtronic Industries Co. Ltd competes on value-engineered platforms targeting price-sensitive DIY enthusiasts.
A cordless router is a portable, battery-driven rotary cutting tool that spins a collet-mounted bit at variable speeds, typically between 10,000 and 30,000 RPM, to shape, trim, or join wood and composite materials. Compact routers lead volume shipments for edge profiling and light trimming tasks where maneuverability trumps power. Plunge routers command premium positioning among woodworking professionals executing deep mortises and stopped grooves. Brushless motor technology is displacing brushed architectures as the dominant design standard due to thermal efficiency and extended duty cycles.
The US Consumer Product Safety Commission and OSHA enforce electrical tool safety standards that mandate double-insulation and kickback mitigation features, directly shaping product development roadmaps. The EU Machinery Directive and CE marking requirements impose ergonomic and electromagnetic compatibility testing that filters out low-cost entrants. Stakeholders must monitor battery platform interoperability standards and state-level contractor licensing changes that favor cordless fleet certifications.
Market Dynamics
Brushless motor architectures and lithium-ion energy density gains are compressing the performance gap between cordless and corded routers, forcing incumbent manufacturers to accelerate platform transitions or surrender professional-grade segments.
Growth Catalysts
- OSHA Electrical Tool Standards:US workplace safety mandates for double-insulation and kickback mitigation favor cordless designs that eliminate ground-fault risks on job sites.
- Woodworking Professionals:Cabinet shops and finish carpenters are replacing corded bench setups with mobile routing stations to reduce setup time and improve dust collection integration.
- Brushless Motor Thermal Efficiency:Extended duty cycles without brush degradation enable continuous profiling operations that previously required corded power.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Cobalt and nickel price swings compress margin structures for battery pack integration, particularly affecting mid-tier product lines.
- Single-Source Battery Platform Risk:Concentration among three dominant cell suppliers in East Asia creates supply vulnerability for manufacturers without captive chemistry partnerships.
- Plunge Depth Limitations:Mechanical constraints on battery-powered plunge mechanisms restrict maximum cutting depth versus corded alternatives in heavy joinery applications.
Strategic Opportunities
- India Woodworking Infrastructure:Furniture manufacturing clusters in Gujarat and Tamil Nadu lack cordless penetration, presenting first-mover positioning for battery-platform entrants.
- EU Green Deal Public Procurement:Carbon footprint disclosure requirements for construction equipment favor cordless electrification in municipal renovation contracts.
- Battery-Platform Convergence:Cross-compatibility between outdoor power equipment and woodworking tools enables shared fleet economics for landscaping contractors expanding into finish carpentry.
Industry Challenges
- Brushless Motor Controller Engineering Talent:Scarcity of power electronics specialists with motor control firmware expertise extends product development timelines.
- CE Marking Electromagnetic Compatibility Testing:EU Machinery Directive compliance for variable-speed drives requires expensive third-party certification cycles that delay market entry.
- Legacy Corded Inventory Liquidation:Channel partners face margin pressure from obsolete stock displacement as cordless SKUs capture shelf space.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Router Market |
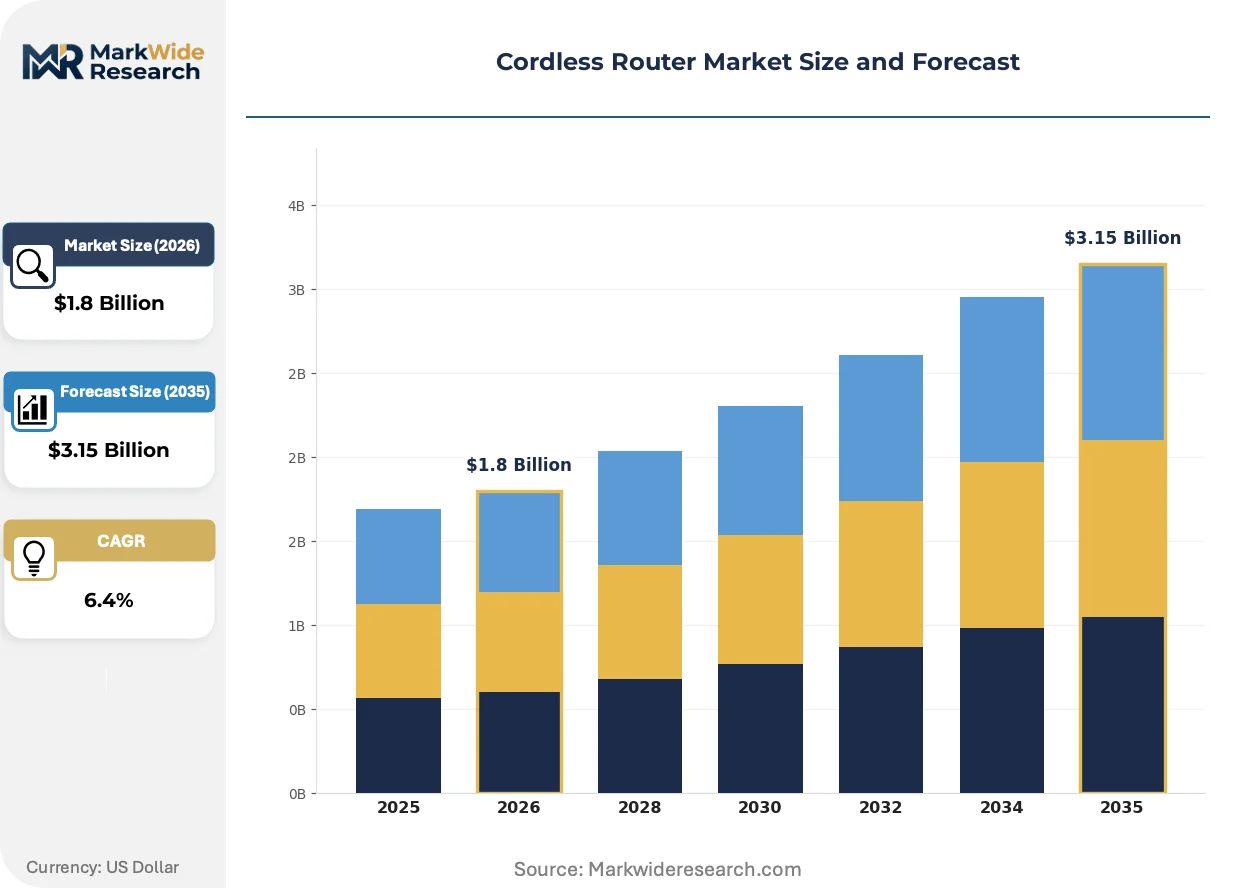
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Router, Plunge Router, Laminate Trim Router, Fixed Base Router Technology: Brushless Motors, Lithium-Ion Batteries, Electronic Speed Control, LED Lighting End User: DIY Enthusiasts, Woodworking Professionals, Construction Contractors, Hobbyists Power Rating: Battery Powered, 18V, 20V, 24V |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker, Makita Corporation, Techtronic Industries Co. Ltd, Milwaukee, DeWalt, Ryobi, Ridgid, Metabo HPT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Router Market Evolving Landscape
Intelligent speed control and connected tool ecosystems are transforming cordless routers from standalone cutting devices into integrated workflow components that communicate with dust extractors and edge guides.
Adaptive electronic load sensing is rewriting how professional woodworkers manage bit engagement in dense hardwoods. Sensors detect cutting resistance and auto-adjust RPM to prevent stall-out, a feature now standard in premium compact routers. Cabinet shops in Germany and Austria are specifying these units for continuous edge-banding operations where torque consistency determines finish quality.
REACH substance restrictions on hexavalent chromium plating are forcing collet and guide bushing manufacturers to migrate toward ceramic or titanium nitride surface treatments. The EU Machinery Directive's updated ergonomic requirements are simultaneously mandating reduced vibration transmission, creating dual compliance pressure on spindle bearing designs. Japanese manufacturers with advanced materials IP are capturing specification share in European professional channels.
Subscription-based fleet management is replacing transactional tool purchases among US commercial contractors. Large woodworking operations in Texas and Florida now lease battery platforms with included maintenance and automatic upgrade cycles, shifting capital expenditure to operating budgets. This model concentrates procurement authority with facility managers rather than individual tradespeople, compressing brand loyalty and prioritizing interoperability over feature differentiation.
Cordless Router Market Segmentation
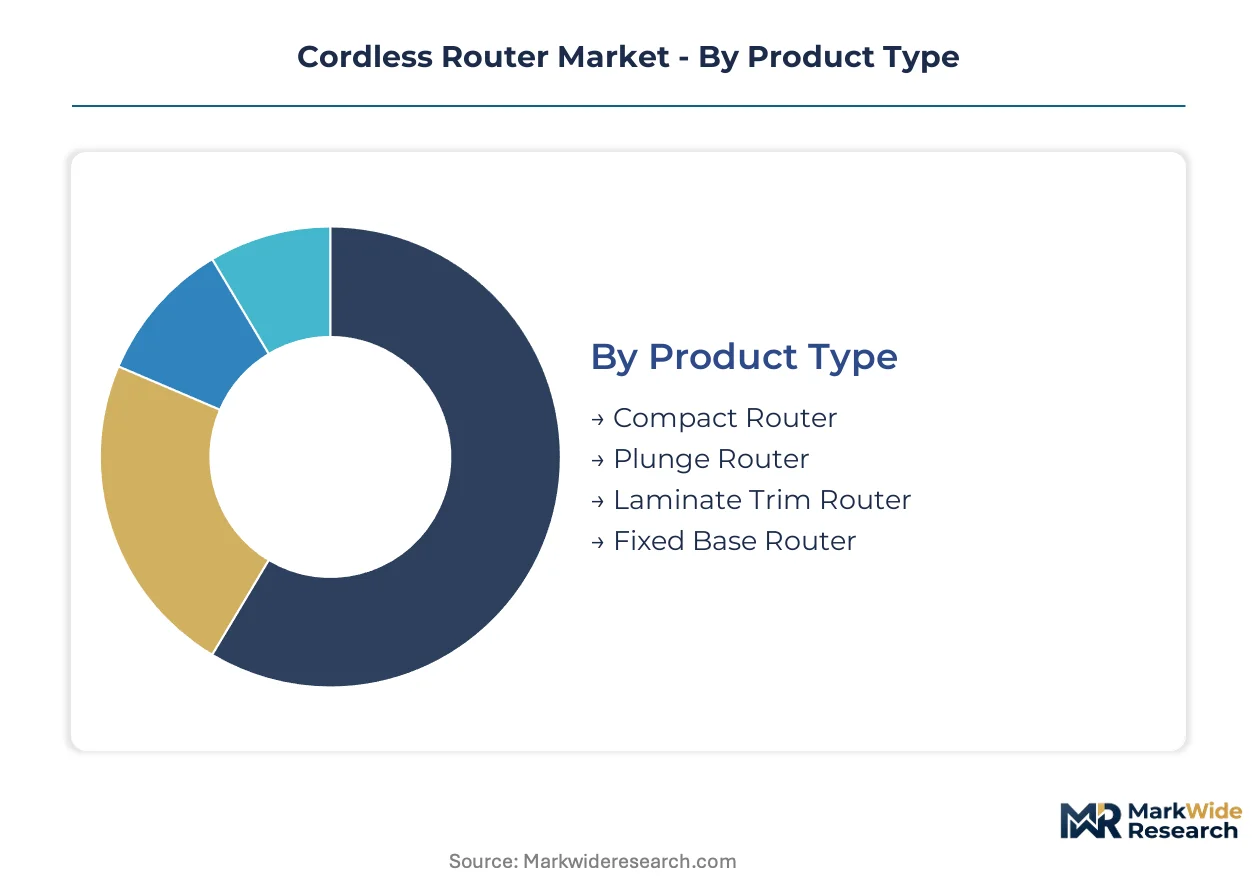
Cordless router manufacturers calibrate platform specifications against distinct user workflows. Product architecture, motor technology, and power band selection determine addressable market scope and margin capture.
Product Type:
Compact routers dominate shipment volumes while plunge configurations command premium positioning through professional-grade duty cycles.
- Compact Router:Single-hand grip designs with 1.0 to 1.5 horsepower equivalent output target edge profiling and laminate trimming. Demand concentrates among finish carpenters in residential renovation markets where maneuverability outweighs plunge capacity.
- Plunge Router:Spring-loaded motor housings enable vertical bit entry for stopped grooves and mortises. Woodworking professionals in cabinet shops specify these units for joinery operations where corded alternatives previously held exclusive position.
- Laminate Trim Router:Ultra-lightweight sub-compact form factors with ¼-inch collet capacity. Hobbyists and flooring installers drive procurement for flush-trimming countertop and veneer applications.
- Fixed Base Router:Ring-adjustable depth mechanisms suit repetitive groove cutting and edge molding. Mid-sized woodworking operations favor these for dedicated bench stations with dust collection integration.
Mature deployment sits with fixed base units in stationary shop environments. Newer deployment is concentrated in compact and laminate trim configurations serving mobile job site workflows.
Technology:
Brushless motor architectures and battery chemistry improvements are compressing performance gaps against corded alternatives while electronic intelligence adds operational safety layers.
- Brushless Motors:Electronically commutated rotor designs eliminate brush friction losses and thermal degradation. Extended duty cycles enable continuous profiling operations in hardwoods that previously stalled brushed motors.
- Lithium-Ion Batteries:Nickel-manganese-cobalt and lithium-iron-phosphate cell chemistries deliver 4.0Ah to 12.0Ah capacity within platform ecosystems. Cell cost volatility constrains margin structures for mid-tier product lines.
- Electronic Speed Control:Microprocessor-governed RPM maintenance under load prevents bit stall-out. Load-sensing variants auto-adjust torque delivery based on cutting resistance feedback.
- LED Lighting:Integrated work illumination improves bit visibility in enclosed routing operations. Standard inclusion in premium SKUs; optional accessory attachment for value-tier platforms.
Brushless motor penetration is climbing the fastest among professional-grade product tiers. Electronic speed control deployment lags in DIY-oriented SKUs where cost engineering dominates specification decisions.
End User:
Procurement authority is shifting from individual tradespeople toward facility managers overseeing fleet standardization and interoperability requirements.
- DIY Enthusiasts:Price-sensitive purchasers prioritizing single-tool acquisition over platform ecosystem investment. Big-box retail channels and online marketplaces capture this segment through promotional bundling.
- Woodworking Professionals:Cabinet shops and finish carpenters demanding thermal efficiency and dust collection compatibility. Brushless platforms with 20V and 24V battery architectures are displacing corded bench setups.
- Construction Contractors:Commercial operations leasing battery platforms with maintenance-inclusive service contracts. Procurement authority concentrates with facility managers prioritizing interoperability over brand loyalty.
- Hobbyists:Occasional-use purchasers with low duty cycle requirements and minimal platform lock-in sensitivity. Entry-level compact routers with brushed motors retain position here.
Woodworking professionals represent the steepest expansion trajectory as cordless mobility replaces corded infrastructure. Hobbyist and DIY segments face margin compression from private-label and value-engineered import competition.
Power Rating:
Voltage platform selection determines battery ecosystem compatibility and runtime-duration tradeoffs across user segments.
- Battery Powered:Generic voltage-agnostic designation covering proprietary platform architectures. Cross-compatibility limitations between outdoor power equipment and woodworking tools constrain fleet economics.
- 18V:Legacy platform standard with mature cell supply chains and broad aftermarket battery availability. Compact router SKUs dominate this voltage tier.
- 20V:Max-voltage marketing designation for lithium-ion platforms with nominal 18V operation. Professional-grade plunge routers and fixed base units concentrate here.
- 24V:Extended-runtime architecture targeting heavy joinery applications with sustained high-torque demand. Limited platform ecosystem breadth constrains adoption outside specialized professional channels.
18V infrastructure retains installed base concentration among residential users. 20V platforms are capturing specification share fastest in commercial contractor fleets standardizing across multiple tool categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential renovation expenditure and contractor fleet electrification concentrate demand in the United States, while woodworking infrastructure investments in India and regulatory pressure in Europe reshape procurement patterns across distinct national markets.
United States
OSHA electrical tool standards mandating double-insulation and kickback mitigation favor cordless designs that eliminate ground-fault risks on commercial job sites. The US Consumer Product Safety Commission enforces stringent safety protocols that filter non-compliant imports from retail channels. Cabinet shops in Texas and Florida are adopting subscription-based battery platform leasing with maintenance-inclusive contracts, shifting procurement authority toward facility managers.
Germany
The EU Machinery Directive and CE marking requirements impose electromagnetic compatibility testing that excludes low-cost entrants from professional distribution. REACH substance restrictions on hexavalent chromium plating force collet manufacturers toward ceramic surface treatments. Woodworking clusters in Bavaria and Baden-Württemberg specify adaptive electronic load-sensing routers for continuous edge-banding operations where torque consistency determines finish quality.
China
Dual carbon goals and provincial emissions targets accelerate cordless electrification in municipal construction procurement across Yangtze River Delta manufacturing zones. GB standards for portable power tools establish baseline safety architectures that domestic producers must satisfy for domestic market access. Furniture manufacturing clusters in Guangdong and Zhejiang provinces lack cordless penetration, presenting positioning opportunities for battery-platform entrants with localized supply chains.
India
Bureau of Indian Standards certification requirements for electrical hand tools create compliance barriers for unbranded imports in woodworking equipment distribution. PLI scheme incentives for domestic manufacturing of power tool components attract joint venture investments from multinational battery platform operators. Furniture manufacturing clusters in Gujarat and Tamil Nadu currently rely on corded bench setups, creating first-mover windows for cordless mobility solutions targeting mid-sized woodworking shops.
Japan
METI energy efficiency regulations for industrial equipment favor brushless motor architectures with superior thermal performance in continuous-duty applications. JIS standards for vibration emission in handheld power tools mandate reduced transmission designs that increase spindle bearing engineering complexity. Advanced materials specialists in Osaka and Nagoya supply ceramic collet treatments that satisfy REACH-compliant European export specifications.
Cordless Router Market Competitive Landscape
German and Japanese producers anchor the premium-tier professional segment; Chinese fabricators and value-engineered specialists hold volume positions in DIY-oriented channels. The vendor base stratifies across three archetypes: integrated battery platform operators with dense ecosystem lock-in, component technology licensors monetizing motor control IP, and contract manufacturers serving private-label retail programs. Dominant competitive moves include strategic partnerships for cell chemistry access and geographic expansion through distributor acquisition in underpenetrated woodworking clusters.
Among the named participants, Robert Bosch GmbH represents the integrated platform archetype with brushless motor IP deployed across European and North American distribution channels. Makita Corporation exemplifies ecosystem density strategy through battery platform interoperability that captures repeat tool purchases. Techtronic Industries Co. Ltd occupies the value-engineered tier targeting price-sensitive DIY enthusiasts through promotional retail bundling. These three entities illustrate how competitive positioning diverges across professional-grade specification and mass-market volume vectors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker |
| Makita Corporation |
| Techtronic Industries Co. Ltd |
| Milwaukee |
| DeWalt |
| Ryobi |
| Ridgid |
| Metabo HPT |
| Others |
Value Network & Pricing Analysis
Subscription-based fleet management among US commercial contractors is compressing transactional pricing power and forcing manufacturers toward platform-leasing economics that tether margin capture to battery ecosystem density rather than per-unit markups.
Pricing Analysis
Volume shipments concentrate in compact routers where three-tier pricing structure across premium, standard, and economy levels reflects motor architecture and battery platform maturity. Price differentiation hinges on brushless motor certification grade and dust collection integration depth. Cost compression in mid-tier SKUs is intensifying because lithium-ion cell cost volatility erodes pack integration margins. DIY enthusiasts exhibit highest price sensitivity while woodworking professionals prioritize thermal efficiency over unit cost.
Supply Chain Analysis
CE marking electromagnetic compatibility testing and OSHA double-insulation certification requirements filter out low-cost entrants before channel placement. Cell production concentrates in China, South Korea, and Japan, while brushless motor controller fabrication rests on Taiwanese semiconductor foundries. Cobalt and nickel price swings create commodity price volatility for battery pack integrators. Distribution runs through construction supply houses and big-box retail channels with divergent service bundling expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where captive battery chemistry partnerships and in-house brushless motor controller production determine who captures professional-grade margin pools.
For Market Incumbents: Lock in battery platform interoperability standards to prevent customer defection to rival ecosystems. Defend against value-engineered import competition by securing exclusive cell chemistry allocations with East Asian suppliers. Prioritize backward integration into motor control firmware development to reduce reliance on scarce power electronics engineering talent. For New Entrants and Emerging Players: Capture first-mover positioning in India's Gujarat and Tamil Nadu furniture manufacturing clusters where corded bench setups still dominate. Target mid-sized woodworking shops with localized battery platform leasing models that bypass upfront capital barriers. Lead with dust collection integration as the go-to-market differentiator against established brands. For Investors and Strategic Acquirers: The window for entry favors component technology licensors with captive brushless motor IP and established CE marking compliance pathways. Long-term viability centers on manufacturers controlling both battery platform density and professional channel specification authority. Watch for state-level contractor licensing changes mandating cordless fleet certification as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Locks in repeat tool purchases through proprietary 20V and 24V architecture interoperability. |
| Brushless Motor Controller Acquisition | Secures scarce power electronics firmware expertise that extends product development timelines. |
| CE Marking Pre-Certification Investment | Accelerates EU market entry by front-loading electromagnetic compatibility testing cycles. |
| India Distribution Partnership | Establishes Bureau of Indian Standards compliant channel presence ahead of PLI scheme maturation. |
| Subscription Fleet Management Launch | Shifts contractor procurement from transactional purchases to recurring operating expenditure models. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with power tool product managers, woodworking shop owners, construction fleet procurement directors, battery platform engineers, and aftermarket service heads. OSHA electrical tool standards documentation, EU Machinery Directive compliance databases, and Bureau of Indian Standards certification registries provided regulatory validation. Bottom-up shipment estimates triangulated against top-down battery platform deployment metrics.
Data-stream reconciliation across product type, voltage architecture, end-user segment, and regional regulatory cluster enabled consistent volume and value outputs across the projection horizon. CAGRs derived from battery chemistry improvement curves and professional cordless adoption rate modeling. Brushless motor penetration trajectories and subscription fleet management uptake served as industry-specific forecast inputs alongside residential renovation expenditure indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cell cost volatility and East Asian supplier concentration. Forecasts reflect assumptions regarding OSHA enforcement consistency and EU Green Deal procurement acceleration. A model refresh is warranted upon material change in state-level contractor licensing mandates favoring cordless fleet certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Exoskeleton Systems Market