
 Asia-Pacific Robotics Technology Market | 2026-2036
Asia-Pacific Robotics Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Robotics Technology Market Analytics
Small and mid-sized electronics contract manufacturers is reorganizing procurement patterns across the Asia-Pacific robotics landscape. Fanuc Corporation anchors high-volume servo motor production from its Yamanashi headquarters, sustaining supply leverage across Japanese automotive lines. Kawasaki Heavy Industries Ltd dominates heavy-payload welding robot systems for shipbuilding yards in South Korea and Japan. Hyundai Robotics Co. Ltd positions its cobot portfolio to capture refurbishment demand from Vietnam's expanding electronics assembly sector.
Asia-Pacific robotics technology encompasses programmable electromechanical systems with six-axis articulation, repeatability tolerances below 0.1 millimeters, and payload capacities spanning 3 kilograms to over 1,000 kilograms, deployed to execute material handling, precision assembly, inspection, and human-collaborative tasks across factory and service environments. Industrial robots command the largest installed base across Chinese automotive stamping plants and Korean battery gigafactories, though collaborative robots generate the fastest deployment velocity among Thailand and Indonesia's tier-two component suppliers seeking flexible reconfiguration without safety cage infrastructure. Computer vision integration within logistics applications is concentrating margin pools around palletizing accuracy and real-time defect detection systems.
Japan's METI enforces JIS B 8433 safety standards for industrial robot integration, while China's SAMR administers compulsory certification for robotic product categories under evolving GB standards frameworks. South Korea's MFDS and KOSHA jointly oversee medical and workplace safety compliance for healthcare assistance and manufacturing automation deployments respectively. Stakeholders must monitor divergence between Japan's precision-centric certification pathways and China's scale-oriented compliance regimes when configuring regional product portfolios.
Market Dynamics
China's MIIT safety certification tightening is compressing product approval timelines while South Korean and Taiwanese electronics manufacturers accelerate precision robot procurement, creating simultaneous compliance pressure and demand pull across the regional value chain.
Growth Catalysts
- Automotive battery gigafactory expansion:Korean and Chinese EV manufacturers are deploying heavy-payload robots for electrode stacking and cell assembly, with Nagoya-Toyota City corridors serving as the primary demand concentration.
- GB standards framework evolution:China's SAMR compulsory certification pathways are forcing equipment upgrades across legacy stamping plants, generating replacement cycles for compliant six-axis systems.
- Collaborative robot flexibility:Thailand and Indonesian tier-two component suppliers are eliminating safety cage infrastructure through cobot adoption, enabling rapid production line reconfiguration for multi-SKU contracts.
Market Restraints
- Servo motor supply concentration:Yamanashi-based production clusters create vulnerability for Japanese automotive lines dependent on single-source precision actuator supply.
- JIS B 8433 integration costs:METI enforcement of safety standard compliance adds engineering overhead and extends deployment timelines for mid-sized contract manufacturers.
- High-resolution vision system pricing:Real-time defect detection hardware remains capital-intensive for Vietnam's emerging electronics assembly sector.
Strategic Opportunities
- Indonesian tier-two supplier penetration:Cobot deployment velocity lags regional peers, creating whitespace for flexible automation without infrastructure retrofit requirements.
- Medical robotics regulatory pathway:South Korea's MFDS oversight of healthcare assistance robots opens specialized certification channels distinct from industrial safety frameworks.
- Computer vision-logistics convergence:Palletizing accuracy demands are concentrating margin pools around integrated vision-guided material handling systems.
Industry Challenges
- Multi-standard certification complexity:Divergence between Japan's precision-centric JIS pathways and China's scale-oriented GB regimes forces redundant testing for regional product portfolios.
- Six-axis integration expertise scarcity:Programming repeatability below 0.1 millimeters requires specialized technician pools concentrated in Japanese and Korean industrial corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Robotics Technology Market |
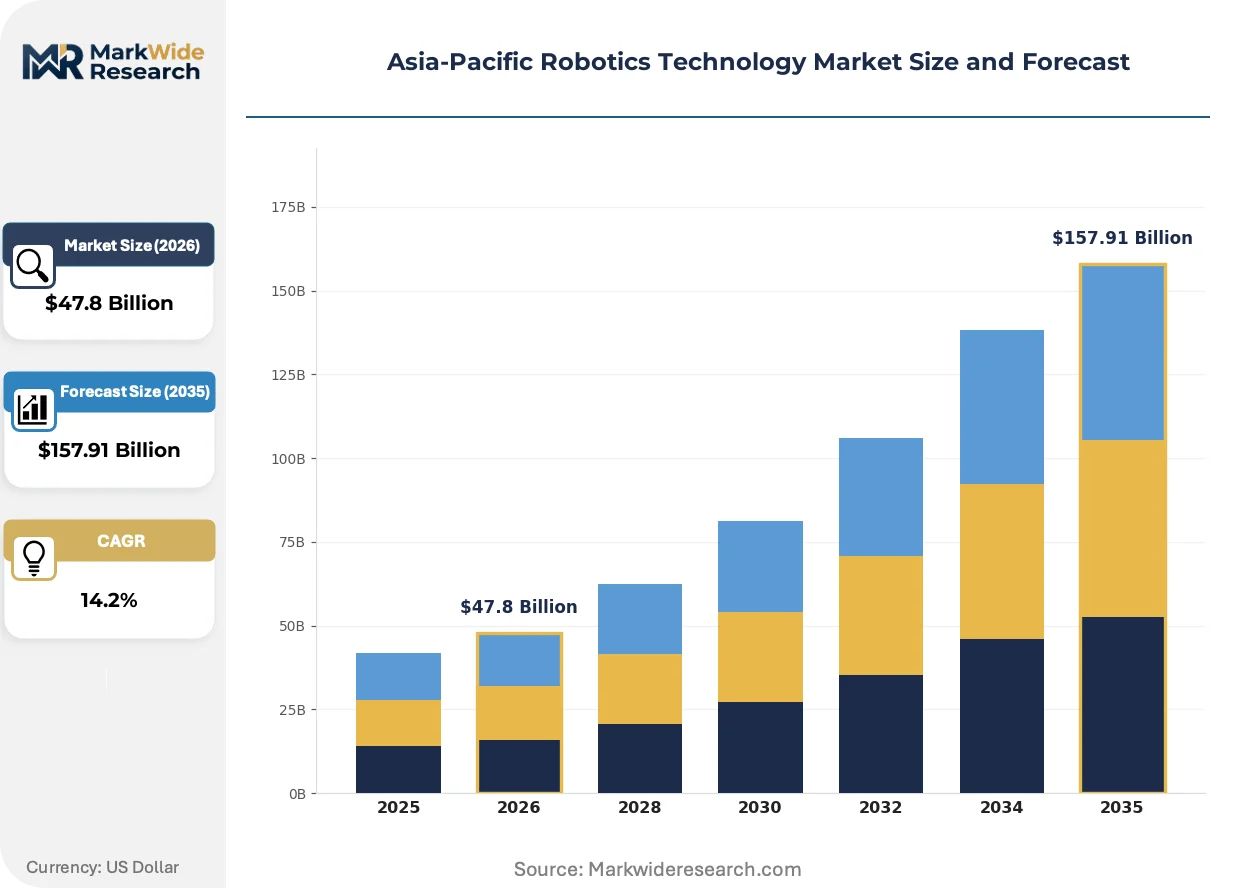
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $157.91 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots Technology: AI, Machine Learning, Computer Vision, Sensors Application: Manufacturing Automation, Healthcare Assistance, Agriculture, Logistics End User: Manufacturers, Hospitals, Agricultural Firms, Warehousing Companies |
| Companies Covered | Kawasaki Heavy Industries Ltd, Denso Corporation, Fanuc Corporation, UBTECH Robotics Inc., Omron Corporation, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Hyundai Robotics Co. Ltd, ABB Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Robotics Technology Market Evolving Landscape
Software-defined control architectures are fragmenting traditional hardware-locked value chains across Asia-Pacific robotics, enabling modular capability upgrades without full system replacement and compressing supplier power.
Edge-native robot controllers with embedded AI inference engines are decomposing centralized PLC-dependent architectures. Taiwanese and Korean electronics contract manufacturers are adopting these systems at twelve-to-eighteen-month refresh cycles. The technology is decomposing traditional tier-one automation vendor lock-in by enabling third-party software stack integration.
Japan's METI is tightening JIS B 8433 enforcement timelines for collaborative robot deployments, mandating documented risk assessment protocols before operational clearance. Industrial consequence includes extended pre-deployment engineering phases for human-robot workcell integration. Japanese automotive suppliers around Toyota City are responding by embedding compliance documentation into early-stage system design rather than post-procurement retrofit.
Thai and Indonesian component manufacturers are unbundling after-sales service contracts from initial hardware procurement, shifting toward third-party maintenance networks and software subscription models. Traditional Japanese and Korean system integrators face margin compression as local service providers capture recurring revenue streams. This pattern is most visible in Bangkok and Jakarta industrial zones where multi-brand robot fleets require vendor-agnostic technical support.
Asia-Pacific Robotics Technology Market Segmentation
Asia-Pacific robotics technology spans programmable electromechanical systems with six-axis articulation, repeatability tolerances below 0.1 millimeters, and payload capacities from 3 kilograms to over 1,000 kilograms. Regulatory divergence between Japan's JIS B 8433 precision standards and China's GB scale-oriented frameworks forces manufacturers to configure distinct regional product portfolios rather than unified platforms.
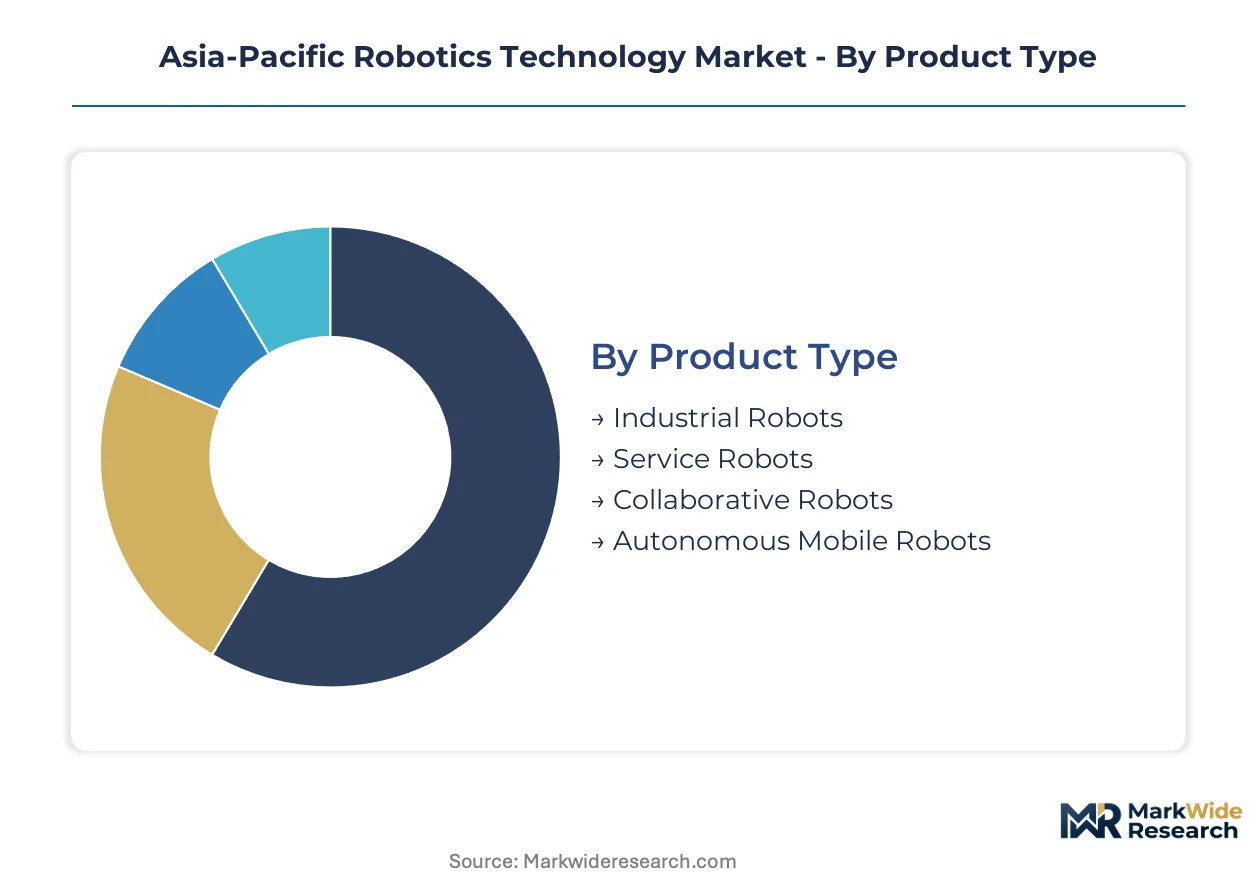
Product Type:
Japan's METI enforces JIS B 8433 safety protocols for collaborative deployments while China's SAMR administers compulsory certification under evolving GB standards, creating divergent compliance pathways for each robot category.
- Industrial Robots:Heavy-payload systems with six-axis articulation dominate Chinese automotive stamping plants and Korean battery gigafactories. Demand concentrates in Nagoya-Toyota City corridors where electrode stacking and cell assembly operations require repeatability below 0.1 millimeters.
- Collaborative Robots:Human-collaborative systems eliminate safety cage infrastructure through force-limiting actuators and proximity sensing. Thailand and Indonesian tier-two component suppliers are adopting these for rapid production line reconfiguration under multi-SKU contracts.
- Service Robots:Non-industrial automation platforms span cleaning, security, and customer interaction functions across commercial facilities.
- Autonomous Mobile Robots:Self-navigating platforms transport materials across warehouse and factory floors without fixed infrastructure.
Industrial robots handle the majority of throughput; collaborative robots are expanding most quickly on share.
Technology:
Cost stratification separates vision-guided premium systems from sensor-dependent standard configurations across the regional installed base.
- AI:Embedded inference engines enable real-time path optimization and predictive maintenance algorithms. Edge-native controllers with AI capabilities are decomposing traditional PLC-dependent architectures at twelve-to-eighteen-month refresh cycles.
- Computer Vision:High-resolution defect detection systems command capital premiums that constrain adoption in Vietnam's emerging electronics assembly sector. Palletizing accuracy demands are concentrating margin pools around integrated vision-guided material handling.
- Machine Learning:Adaptive control algorithms improve task performance through operational data accumulation.
- Sensors:Force-torque and proximity detection hardware enables human-robot collaboration without physical guarding.
Computer vision captures the highest margin per unit; AI integration is gaining share fastest through controller refresh cycles.
Application:
Volume concentration tracks automotive and electronics manufacturing density across Japanese and Korean industrial corridors.
- Manufacturing Automation:Material handling, precision assembly, and inspection tasks deploy across Chinese automotive stamping plants and Korean battery gigafactories. GB standards framework evolution is forcing equipment upgrades across legacy facilities.
- Logistics:Palletizing accuracy and real-time tracking systems concentrate demand around integrated vision-guided material handling. Bangkok and Jakarta industrial zones are unbundling after-sales service contracts toward third-party maintenance networks.
- Healthcare Assistance:Patient mobility and surgical support systems fall under South Korea's MFDS oversight with specialized certification channels.
- Agriculture:Autonomous harvesting and crop monitoring applications remain nascent across the regional installed base.
Manufacturing automation handles the majority of throughput; logistics is climbing the fastest on deployment velocity.
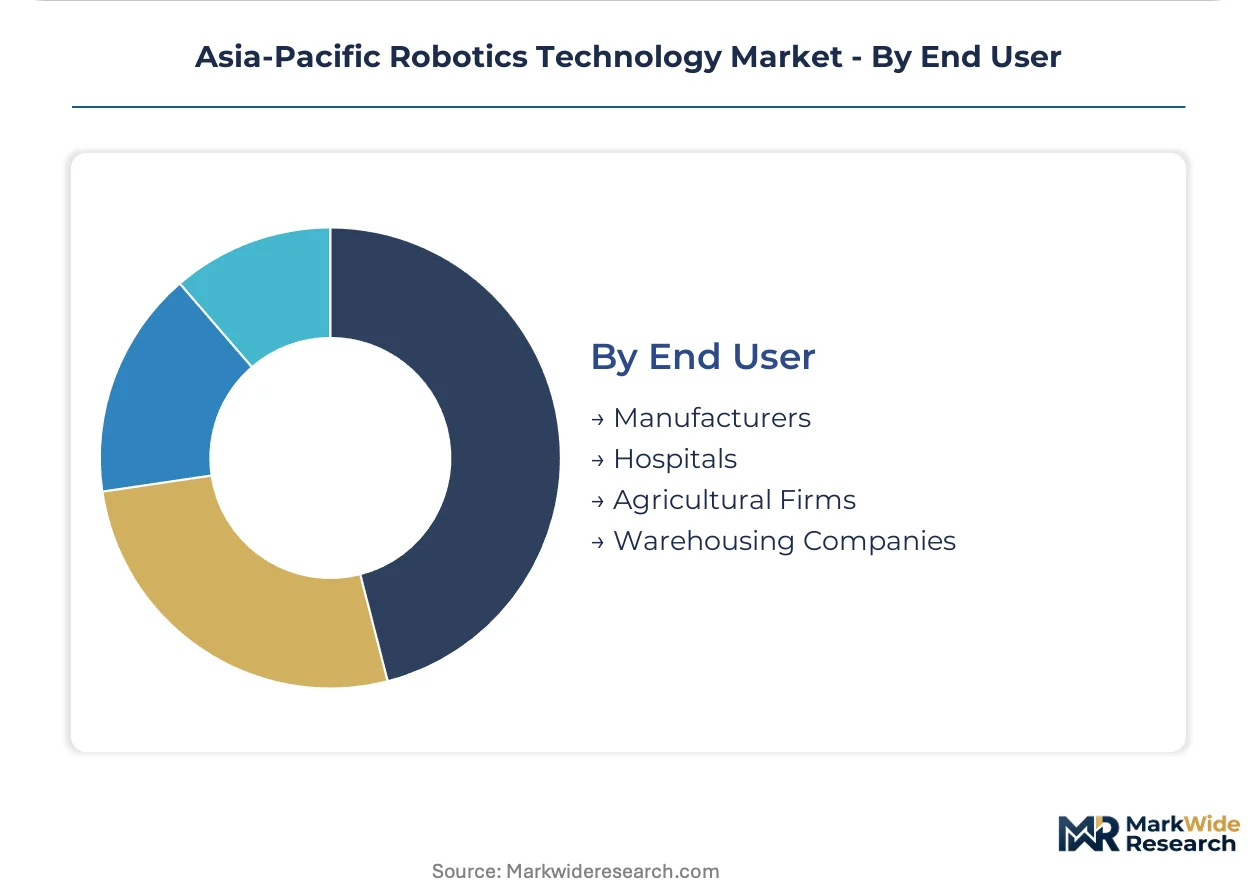
End User:
Customer scale determines procurement pattern complexity from integrated turnkey systems to unbundled hardware and service contracts.
- Manufacturers:Automotive and electronics producers dominate procurement volume with multi-axis system deployments. Japanese automotive suppliers around Toyota City are embedding compliance documentation into early-stage system design.
- Warehousing Companies:Third-party logistics operators are shifting toward software subscription models and vendor-agnostic technical support for multi-brand robot fleets.
- Hospitals:Healthcare facilities require MFDS-certified systems for patient-facing assistance applications.
- Agricultural Firms:Farm operators represent emerging demand with limited current installed base penetration.
Manufacturers represent the dominant procurement volume; warehousing companies are shifting fastest toward service-unbundled contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision servo motors and six-axis systems to automotive corridors in South Korea and China, while Chinese manufacturers supply cost-optimized components to Southeast Asian electronics assemblers. This trade architecture shapes procurement patterns across the region.
China
Automotive battery gigafactories in Shenzhen and Ningbo deploy heavy-payload robots for electrode stacking operations. SAMR administers compulsory certification under evolving GB standards frameworks. Shanghai's industrial zones are forcing equipment upgrades across legacy stamping plants as compliance timelines compress.
Japan
Precision assembly demand from Toyota City and Nagoya automotive suppliers sustains high-volume servo motor production. METI enforces JIS B 8433 safety standards for collaborative robot deployments. Yamanashi prefecture anchors supply leverage for repeatability-tolerant actuators serving domestic automotive lines.
South Korea
EV manufacturers in Ulsan and Gwangju are procuring heavy-payload welding systems for shipbuilding and battery cell assembly. MFDS and KOSHA jointly oversee medical and workplace safety compliance respectively. Busan industrial corridors concentrate demand for refurbishment-ready cobot portfolios.
Taiwan
Electronics contract manufacturers in Hsinchu and Taichung are expanding precision robot deployments for semiconductor packaging and component assembly. The island's national standards body aligns product certification with regional export requirements. Taipei industrial zones are adopting edge-native controllers at accelerated refresh cycles.
Vietnam
Emerging electronics assemblers in Ho Chi Minh City and Hanoi are seeking flexible automation without safety cage infrastructure. The country's national industrial regulator is developing conformity assessment pathways for imported automation equipment. Northern industrial parks are experiencing cobot deployment velocity as tier-two suppliers scale capacity.
Asia-Pacific Robotics Technology Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive robotics divisions, creating tiered competition between integrated automation vendors and specialized motion-control firms. Japanese and Korean heavy-industry groups anchor high-volume production through in-house component manufacturing. Strategic archetypes include precision-centric system integrators, scale-oriented hardware fabricators, and software-defined control specialists. Geographic expansion and portfolio diversification dominate competitive moves as vendors navigate divergent certification regimes.
Within the diversified-industrial tier, Fanuc Corporation and Kawasaki Heavy Industries Ltd represent archetypes of integrated production control, while Hyundai Robotics Co. Ltd exemplifies regional challengers targeting refurbishment cycles in emerging manufacturing corridors. Denso Corporation and Yaskawa Electric Corporation occupy positions in motion-control specialization, anchoring supply relationships across Japanese automotive clusters. These groupings illustrate how vendor structure maps to certification jurisdiction and end-use concentration.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries Ltd |
| Denso Corporation |
| Fanuc Corporation |
| UBTECH Robotics Inc. |
| Omron Corporation |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Hyundai Robotics Co. Ltd |
| ABB Limited |
| Others |
Value Network & Pricing Analysis
Edge-native controller substitution for legacy PLC architectures is redrawing procurement geography across the Asia-Pacific robotics landscape, compressing hardware-locked premium tiers while opening software-defined margin pools for Taiwanese and Korean electronics contract manufacturers.
Pricing Analysis
Current-generation edge-native controllers with embedded AI inference engines command hardware-plus-subscription premiums against prior-generation PLC-dependent systems, while next-generation modular software stacks threaten to collapse both tiers into pure licensing models. Three-tier pricing structure across premium vision-guided, standard sensor-dependent, and economy actuator-only configurations stratifies by certification grade and after-sales bundling. Cost compression in the standard tier is intensifying because Thai and Indonesian manufacturers are unbundling service contracts from initial procurement. Emerging electronics assemblers in Vietnam exhibit highest price sensitivity; Japanese automotive suppliers around Toyota City demonstrate lowest sensitivity due to compliance-embedded system design requirements.
Supply Chain Analysis
Inventory lead times for precision servo motors from Yamanashi-based production clusters have extended vulnerability windows for Japanese automotive lines dependent on single-source repeatability-tolerant actuators. Component sourcing draws from Japan for high-precision motion control systems, South Korea for heavy-payload welding platforms, and China for cost-optimized controllers serving Southeast Asian markets. Single-source concentration in Yamanashi prefecture creates structural exposure to regional logistics disruption. Distribution runs through integrated system integrators in Tokyo and Seoul industrial corridors, though Bangkok and Jakarta zones are shifting toward vendor-agnostic third-party technical support networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized six-axis programming expertise below 0.1 millimeter repeatability thresholds remains concentrated in Japanese and Korean industrial corridors, creating asymmetric capability access that shapes competitive outcomes across the regional installed base.
For Market Incumbents: Secure captive supply relationships for precision servo motor production against emerging software-defined controller substitution threatening hardware-locked value chains. Anchor compliance documentation investment early in system design cycles to preempt METI JIS B 8433 enforcement timeline compression. Defend margin position through backward integration into edge-native AI controller development rather than pure hardware fabrication scale. For New Entrants and Emerging Players: China's SAMR fast-track certification pathways for GB standards compliance offer entry velocity against incumbent JIS B 8433 documentation overhead. Indonesian tier-two component suppliers present the most penetrable whitespace, with cobot deployment velocity lagging regional peers and infrastructure retrofit requirements eliminated. Pursue software subscription models with unbundled hardware procurement to capture recurring revenue streams from Bangkok and Jakarta industrial zones. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision system integrators holding Toyota City and Nagoya automotive supplier relationships that face software-defined margin compression. Five-to-ten year viability hinges on controller architecture transition timing rather than pure manufacturing scale. Watch for edge-native controller refresh cycle acceleration in Hsinchu and Taichung electronics corridors as inflection signal for value migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Controller Development | Decomposes traditional PLC-dependent architectures and compresses tier-one vendor lock-in across Taiwanese electronics manufacturers. |
| GB Standards Fast-Track Certification | Accelerates market access velocity against JIS B 8433 documentation overhead for Chinese SAMR compliance pathways. |
| Cobot Portfolio Expansion | Captures refurbishment demand from Vietnam's emerging electronics assembly sector without safety cage infrastructure requirements. |
| Third-Party Maintenance Network Buildout | Captures recurring revenue streams from unbundled service contracts in Bangkok and Jakarta industrial zones. |
| Vision-Guided Logistics Integration | Concentrates margin pools around palletizing accuracy demands in warehouse and factory floor material handling applications. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and industrial automation equipment certification registries preceded structured interviews with plant engineers at Japanese automotive suppliers, procurement leads at Korean battery gigafactories, and aftermarket service heads at Thai component manufacturers. Primary fieldwork across Nagoya-Toyota City corridors, Shenzhen industrial zones, and Bangkok manufacturing parks validated secondary intelligence on deployment velocity and compliance timeline compression. Bottom-up installation base modeling triangulated against top-down electronics and automotive production capacity forecasts.
Variance decomposition across product type, technology integration level, application intensity, and end-user scale dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory blending rather than single-point extrapolation. Forecast inputs incorporated MIIT certification timeline evolution, JIS B 8433 enforcement intensity gradients, and edge-native controller refresh cycle acceleration patterns observed in Hsinchu and Taichung electronics corridors.
Decision-makers should treat outputs as directional under sustained EV battery gigafactory expansion and stable regulatory divergence between Japanese precision-centric and Chinese scale-oriented certification regimes; material deviation in either assumption would warrant model refresh. Specific risks include tariff exposure on precision actuator imports, sudden GB standards framework convergence with JIS pathways, and software-defined architecture adoption velocity exceeding hardware replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Robot Pedestal Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market