
 Foundry and Forging Robots Market | 2026-2036
Foundry and Forging Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Foundry and Forging Robots Market Analysis
Market Context
The direct sales channel between robot OEMs and tier-one foundries is narrowing as system integrators consolidate procurement decisions for large automotive and aerospace buyers. FANUC Corporation leverages its captive servo motor production to control cost structures across articulated robot lines for molten metal handling. KUKA AG anchors European demand through specialized heavy-payload systems engineered for forging press tending. Yaskawa Electric Corporation competes aggressively in Asia-Pacific with motion control architectures optimized for high-repeatability casting applications.
Technical Definition and Segment Structure
Foundry and forging robots encompass articulated, SCARA, gantry, and collaborative robotic systems designed to withstand ambient temperatures exceeding 50°C while manipulating payloads above 500 kg in molten metal pouring, die lubrication, and hot forging transfer operations. Articulated robots dominate installed value due to six-axis flexibility in constrained casting cell layouts, though collaborative robot penetration is accelerating where Computer Vision and AI-enabled force limiting permit reduced fencing. The Application dimension reveals Metal Casting as the mature revenue base while Surface Treatment commands margin premiums for explosion-proof robot specifications in shot blasting and grinding.
Regulatory Environment
ISO 10218 safety standards, OSHA 1910.212 machine guarding requirements, and EU Machinery Directive 2006/42/CE compliance certifications shape product design cycles and market access timelines for foundry robot deployments. The EU AI Act adds algorithmic transparency obligations for AI-enabled vision systems that classify casting defects in real time. Stakeholders must monitor evolving CE marking protocols for collaborative robots operating unguarded near molten aluminum pour streams.
Market Dynamics
OSHA workplace safety mandates and ISO 10218 robot safety standards are compressing deployment timelines for human-robot collaboration in high-temperature metalworking environments. Automotive foundries now face accelerated compliance deadlines for unguarded collaborative robot operations near molten aluminum pour streams.
Growth Catalysts
- EU Machinery Directive 2006/42/CE:CE marking requirements for collaborative robots are forcing European foundries to upgrade legacy die casting cells with certified systems. Tier-one automotive suppliers in Germany are retrofitting facilities ahead of enforcement deadlines.
- AI-enabled defect classification:Machine vision systems trained on casting porosity patterns are reducing manual inspection headcount in China's Yangtze River Delta foundry cluster. MIIT smart manufacturing subsidies are covering deployment costs for qualifying facilities.
- Forging press tending automation:Heavy-payload articulated robots are displacing manual transfer operations in Japanese automotive component plants. METI productivity targets are accelerating capital allocation toward unmanned hot forging lines.
Market Restraints
- High-grade servo motor supply concentration:Captive production at Japanese and German OEMs limits third-party sourcing options for system integrators. Foundry operators face extended lead times for six-axis systems above 500 kg payload.
- Explosion-proof certification costs:ATEX and IECEx compliance for shot blasting robot specifications adds engineering overhead that mid-tier foundries cannot absorb. Surface treatment applications remain concentrated at tier-one suppliers.
- Residual manual intervention requirements:Die lubrication and ladle skimming operations still demand human judgment in complex casting geometries. Full unmanned operation remains technically constrained for low-volume, high-mix production.
Strategic Opportunities
- Collaborative robot penetration in forging:Force-limited cobots with Computer Vision and thermal shielding can access constrained press layouts previously reserved for fencing-protected articulated systems. German automotive suppliers are piloting unguarded tending operations.
- Retrofit integration services:System integrators are capturing procurement decisions from direct OEM channels by bundling legacy PLC migration with new robot deployment. This channel shift concentrates margin capture at engineering firms.
- EU AI Act algorithmic transparency:Real-time defect classification systems will require documented training data provenance. Early compliance investments create positioning advantages for European vision system vendors serving CE-marked robot deployments.
Industry Challenges
- Multi-generational control architecture integration:Legacy Siemens S7 and Allen-Bradley PLC systems in aging foundries require custom gateway development for modern robot fieldbuses. Project timelines extend by months.
- Thermal protection engineering talent:Design of ambient-tolerant cable routing and sealed joint packages for 50°C+ environments sits with a narrow pool of specialists. Compensation inflation is compressing system integrator margins.
Report Scope
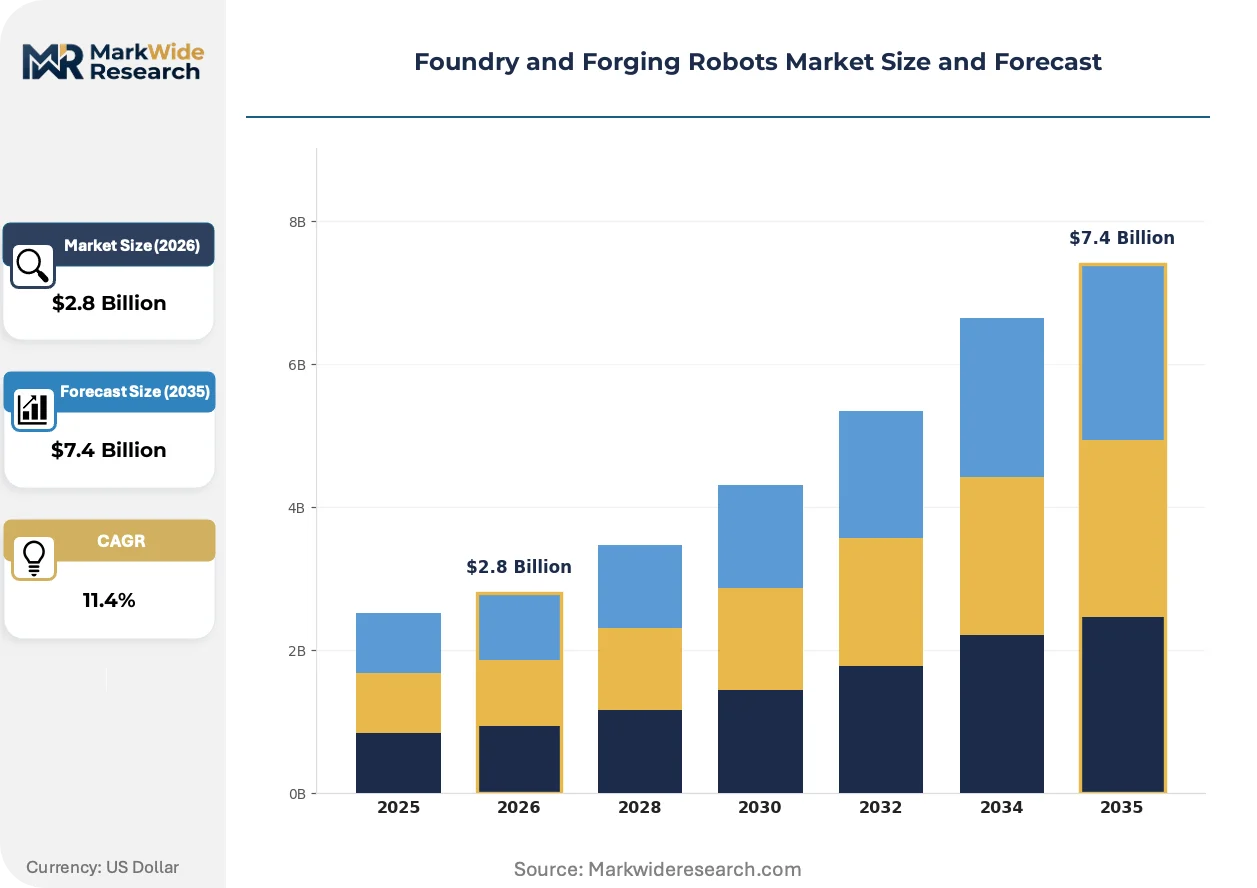
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundry and Forging Robots Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Gantry Robots, Collaborative Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, IoT Application: Metal Casting, Metal Cutting, Surface Treatment, Assembly End User: Aerospace, Automotive, Heavy Machinery, Electronics |
| Companies Covered | ABB Ltd., FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries, Ltd., Nachi-Fujikoshi Corp., OMRON Corporation, Comau S.p.A., Stäubli International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundry and Forging Robots Market Emerging Trajectories
Digital twin technology is virtualizing commissioning workflows for foundry robot cells, compressing startup timelines and reducing molten metal spill risks during physical testing. Three convergent developments are restructuring competitive positioning.
Digital twin platforms are virtualizing entire die casting cell layouts before physical installation. Tier-one automotive foundries in Germany and Japan are adopting these tools to validate robot reach envelopes and thermal interference patterns virtually. This virtualization is compressing commissioning timelines from weeks to days while eliminating molten metal exposure during trial runs.
The EU AI Act is imposing algorithmic transparency obligations on vision systems that classify casting defects in real time. European foundry operators must now document training data provenance and model decision boundaries for regulatory audits. Collaborative robot deployments with integrated quality inspection are most affected, with vendors accelerating CE marking protocol updates.
Automotive OEMs are consolidating robot procurement through captive system integrators rather than direct OEM relationships. Large buyers in Germany and the United States are awarding multi-site contracts to engineering firms that bundle hardware, integration, and aftermarket service. This channel compression is marginalizing smaller foundries that lack volume leverage for negotiated terms.
Foundry and Forging Robots Market Segmentation
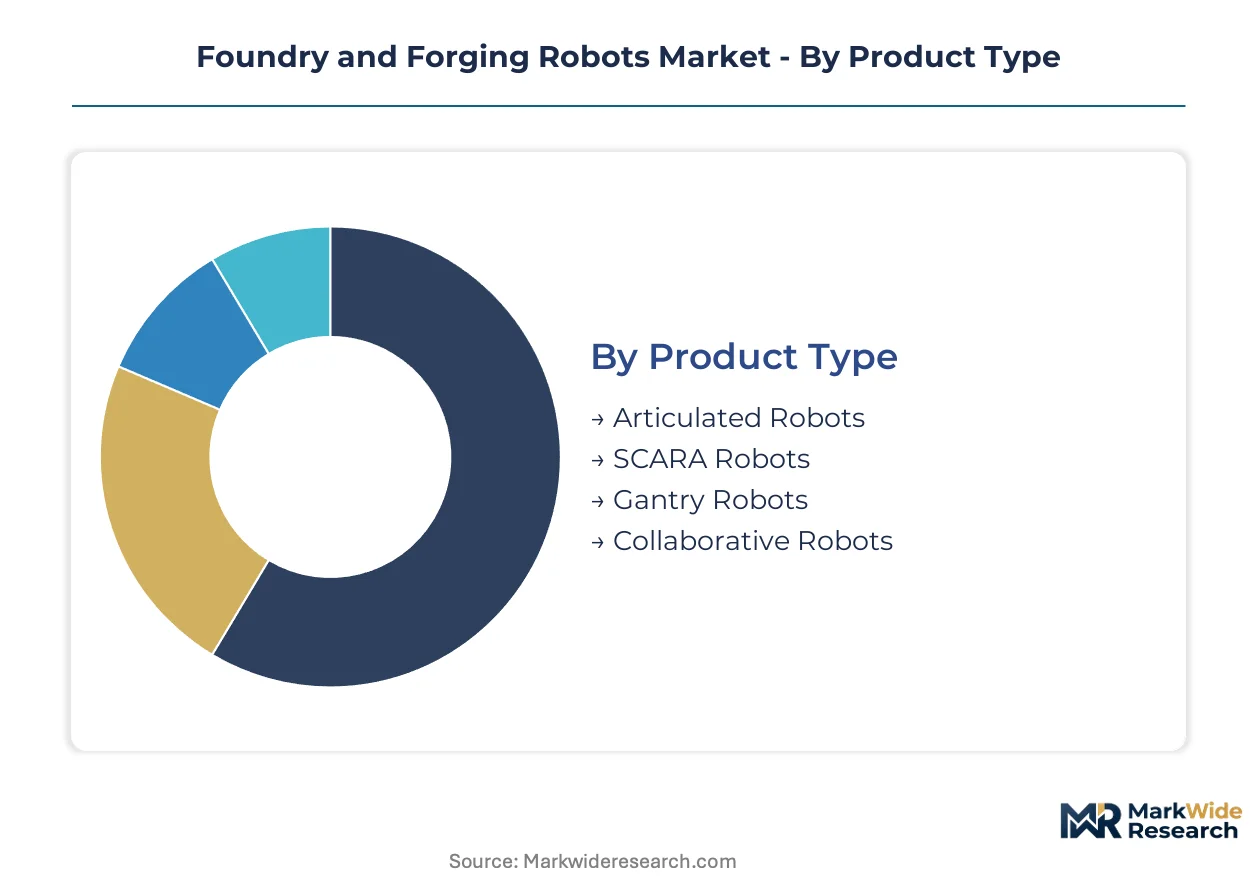
Foundry and forging robots serve distinct thermal, payload, and precision requirements across metalworking operations. Segment boundaries reflect technical trade-offs between flexibility, speed, and human proximity tolerance in high-temperature environments.
Product Type:
Use cases span heavy-payload molten metal handling to fenceless collaborative tending in constrained press layouts.
- Articulated Robots:Six-axis systems manipulate payloads exceeding 500 kg in die casting cells and hot forging transfer lines. German automotive foundries deploy these for press tending where reach envelopes must clear complex die geometries.
- Collaborative Robots:Force-limited cobots with thermal shielding and AI-enabled vision operate unguarded near molten aluminum pour streams. German tier-one suppliers pilot these in constrained layouts previously requiring extensive fencing.
- SCARA Robots:Selective compliance assembly robots deliver high-speed precision for electronics foundry applications and small-component handling in automated cells.
- Gantry Robots:Overhead linear systems cover large work envelopes in heavy machinery casting operations where floor space constraints limit floor-mounted alternatives.
Established volume favors articulated systems; emerging adoption favors collaborative robots with force-limiting architectures.
Technology:
Cost tiers separate foundational automation from premium AI-enabled quality systems.
- Computer Vision:Real-time defect classification systems trained on casting porosity patterns reduce manual inspection headcount. China's Yangtze River Delta foundry cluster deploys these under MIIT smart manufacturing subsidies.
- Artificial Intelligence:Algorithmic transparency obligations under the EU AI Act now govern vision systems that classify defects in real time, forcing documented training data provenance for CE-marked deployments.
- Machine Learning:Predictive maintenance models analyze thermal cycling patterns in robot joint packages to forecast seal degradation before failure.
- IoT:Sensor networks monitor ambient temperatures exceeding 50°C and vibration signatures across distributed foundry cells for centralized fleet management.
Premium positioning concentrates in AI-enabled vision; baseline automation relies on IoT connectivity layers.
Application:
Margin structures diverge between mature casting operations and certified surface treatment specifications.
- Metal Casting:Molten metal pouring, die lubrication, and ladle skimming operations constitute the mature revenue base. Full unmanned operation remains constrained for low-volume, high-mix production geometries.
- Surface Treatment:Explosion-proof robot specifications for shot blasting and grinding command margin premiums. ATEX and IECEx certification costs limit penetration to tier-one suppliers with engineering absorption capacity.
- Metal Cutting:Automated trimming and degating systems remove cast part runners with repeatable precision in high-volume automotive component lines.
- Assembly:Foundry-adjacent operations integrate cast components into subassemblies, requiring robots with both thermal tolerance and fine positioning accuracy.
Volume concentration sits with metal casting; steepest expansion trajectory belongs to surface treatment as certification barriers slowly erode.
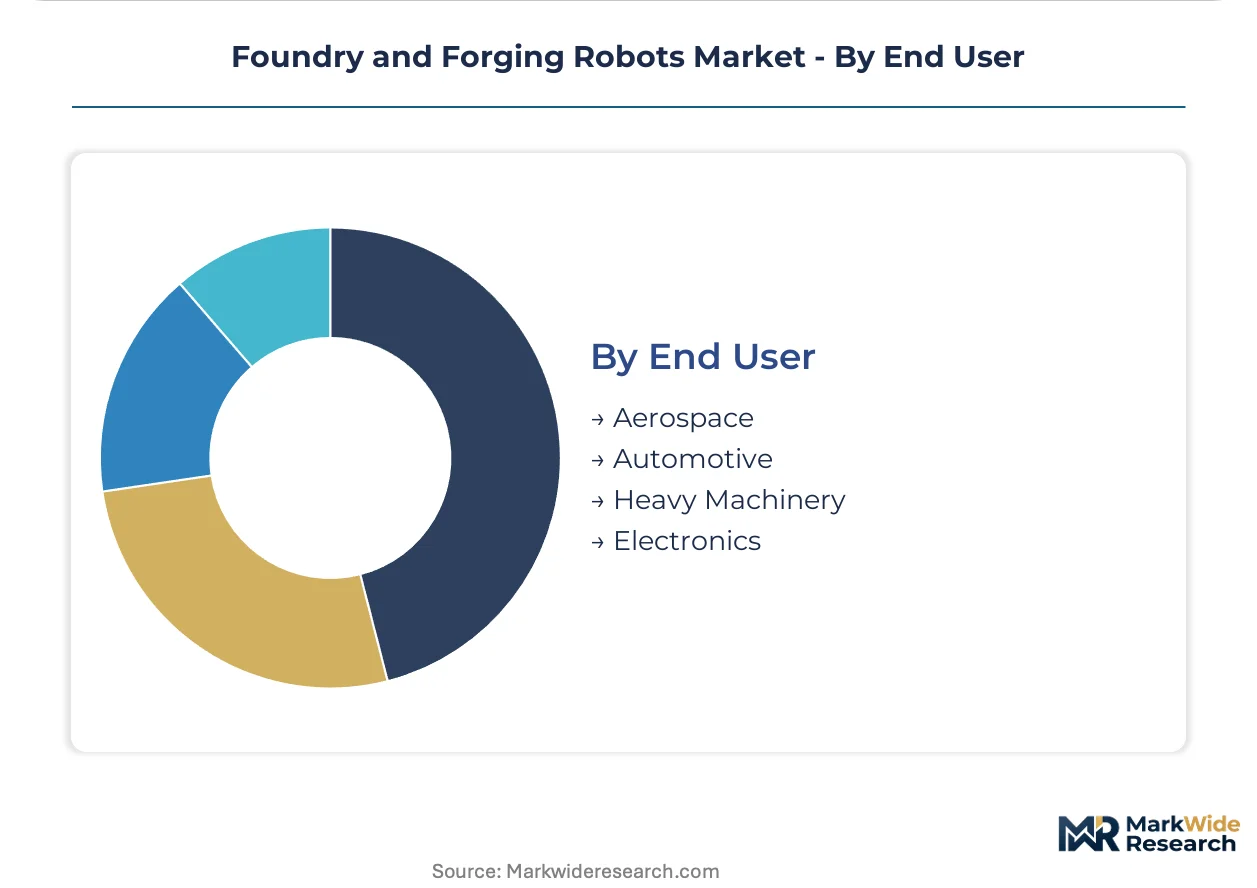
End User:
Customer scale determines procurement channel access and integration service bundling.
- Automotive:Tier-one suppliers in Germany, Japan, and the United States consolidate procurement through captive system integrators, marginalizing direct OEM relationships and squeezing smaller foundries.
- Aerospace:Precision forging operations for turbine disks and structural components demand heavy-payload systems with six-axis flexibility for complex die geometries.
- Heavy Machinery:Large casting producers utilize gantry configurations for earthmoving equipment components where work envelopes span multiple meters.
- Electronics:Miniaturized SCARA deployments handle precision metal components in connector and heat sink manufacturing.
Procurement leverage concentrates in automotive; technical specification complexity peaks in aerospace forging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German system integrators extract pricing premiums for CE-marked collaborative robot deployments that Chinese foundry clusters cannot match under MIIT subsidy regimes. This asymmetry concentrates margin capture in European engineering services while Asian markets compete on deployment velocity.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg retrofit legacy die casting cells ahead of EU Machinery Directive enforcement deadlines. METI-aligned productivity targets in sister Japanese operations create technology transfer pipelines for KUKA AG heavy-payload systems. The Stuttgart industrial corridor anchors European demand for forging press tending automation.
China
State-backed smart manufacturing initiatives under MIIT guidance retrofit legacy facilities in the Yangtze River Delta with AI-enabled robotic systems. GB standards compliance for collaborative robot safety lags ISO 10218 adoption timelines. Shanghai and Suzhou foundry clusters deploy machine vision systems for casting porosity inspection under subsidy coverage.
United States
OSHA 1910.212 machine guarding mandates accelerate compliance investments for unguarded collaborative robot operations near molten aluminum pour streams. Detroit-area automotive foundries consolidate procurement through captive system integrators rather than direct OEM channels. Southeast Michigan casting operations face compressed deployment timelines for human-robot collaboration.
Japan
METI productivity targets drive capital allocation toward unmanned hot forging lines in Nagoya and Osaka automotive component plants. Captive servo motor production at domestic OEMs limits third-party sourcing options for regional system integrators. Toyota supplier networks in Aichi Prefecture deploy heavy-payload articulated robots for press tending automation.
Italy
ATEX and IECEx certification requirements for explosion-proof shot blasting specifications concentrate surface treatment automation at tier-one suppliers in Lombardy and Emilia-Romagna. CE marking protocols for collaborative robots operating near molten metal streams align with German enforcement timelines. Turin-area automotive foundries pilot force-limited cobot deployments in constrained press layouts.
Foundry and Forging Robots Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive supply of servo motors and motion control architectures. The vendor base organizes around three strategic archetypes: Japanese OEMs with backward integration into precision electromechanics, German engineering firms with heavy-payload specialization, and Chinese system integrators capturing procurement decisions through bundled retrofit services. Competitive moves center on channel compression through captive integrator relationships and geographic expansion via MIIT-subsidized deployment partnerships.
Among the precision electromechanics tier, FANUC Corporation and Yaskawa Electric Corporation exemplify the Japanese archetype of captive component production. KUKA AG occupies a position representing German heavy-payload engineering specialization for forging applications. These three anchors illustrate how competitive positioning stratifies across thermal tolerance specifications, payload categories, and regional regulatory compliance capabilities rather than converging on undifferentiated hardware supply.
| Leading Market Players |
|---|
| ABB Ltd. |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries, Ltd. |
| Nachi-Fujikoshi Corp. |
| OMRON Corporation |
| Comau S.p.A. |
| Stäubli International AG |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese and German servo motor production determines both the premium-to-economy pricing spread across articulated robot tiers and the elongated supply chain shape that favors captive OEM relationships over open component markets. Foundry operators face compressed negotiation leverage when high-payload system procurement hinges on exclusive supply agreements with vertically integrated precision electromechanics producers.
Pricing Analysis
Configured-to-order pricing for heavy-payload articulated systems commands substantial premiums over standard catalog configurations. Three-tier pricing structure across premium CE-certified collaborative robots, mid-grade articulated systems, and economy gantry configurations reflects certification grade and after-sales service bundling. Pricing pressure stems from Chinese system integrators bundling retrofit services at compressed margins under MIIT subsidy regimes. Mid-tier foundries exhibit highest price sensitivity, while tier-one automotive suppliers prioritize compliance velocity over unit cost.
Supply Chain Analysis
High-grade servo motor feedstock concentrates in Japan, Germany, and select Chinese production enclaves with captive OEM supply arrangements. Precision gearboxes, thermal-resistant cabling, and sealed joint packages constitute critical component dependencies. Single-source vulnerability pervades six-axis systems above 500 kg payload where FANUC and Yaskawa in-house production limits third-party sourcing. Distribution runs through system integrators consolidating procurement decisions for large automotive and aerospace buyers, marginalizing direct OEM channels for smaller foundry operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foundry robotics market approaches a platform-economics inflection as digital twin virtualization and AI-enabled vision systems create interoperability standards that favor ecosystem orchestrators over hardware specialists. Control architecture convergence around unified fieldbus protocols is consolidating competitive advantage at engineering firms that bundle hardware, software, and integration services.
For Market Incumbents: Build captive integration service moats by acquiring regional system integrators with established PLC migration expertise and legacy foundry relationships. Consolidation of procurement decisions by tier-one automotive suppliers threatens direct OEM margins; backward integration into servo motor production protects cost structures against supply concentration. ISO 10218 compliance certification investments create switching costs that lock in automotive foundry accounts. For New Entrants and Emerging Players: Build out collaborative robot retrofit services targeting China's Yangtze River Delta foundry cluster where MIIT subsidies cover deployment costs but local system integration capabilities lag. Surface treatment applications with explosion-proof specifications offer the most penetrable white space as ATEX and IECEx certification barriers slowly erode. Position around AI-enabled defect classification as EU AI Act transparency requirements create demand for documented training data provenance. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by elevating European vision system vendors with pre-positioned CE marking protocols and algorithmic transparency documentation. Long-term viability centers on engineering services firms capturing procurement consolidation from direct OEM channels. Monitor collaborative robot pilot deployments at German tier-one suppliers as the signal indicating unguarded operation readiness and regulatory acceptance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual commissioning compresses startup timelines and eliminates molten metal exposure during physical testing phases. |
| Backward Integration into Servo Motors | FANUC and Yaskawa captive production controls cost structures and limits third-party sourcing options for competitors. |
| CE Marking Protocol Acceleration | Early EU AI Act compliance investments position European vision vendors for algorithmic transparency audit requirements. |
| System Integrator Acquisition | Channel compression favors engineering firms bundling hardware, legacy PLC migration, and aftermarket service contracts. |
| Collaborative Robot Thermal Shielding R&D | Force-limited cobots with 50°C+ ambient tolerance access constrained press layouts previously requiring extensive fencing. |
Methodological Framework
Cross-validation between primary interviews with foundry operations directors, system integrator engineering leads, and OEM product managers anchors the qualitative findings against secondary validation from SEC filings, MIIT smart manufacturing subsidy disclosures, and ISO standards documentation. Bottom-up triangulation across robot deployment records and top-down reconciliation with automotive production capacity data ensures segmentation integrity. Field perspectives from thermal protection engineering specialists and PLC migration consultants inform supply chain risk assessments.
Calibration against historical deployment velocity in Germany's Stuttgart industrial corridor and China's Yangtze River Delta foundry cluster validates projection assumptions across the analysis window. Segmentation modeling spans product type, application, technology tier, and end-user scale with industry-specific dimensions for thermal tolerance specifications and payload categories. CAGR derivation incorporates foundry automation capital expenditure cycles, regulatory compliance deadline clustering, and MIIT subsidy phase-out trajectories.
Stress conditions across servo motor supply disruption, EU AI Act enforcement acceleration, and Chinese subsidy regime modification were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding collaborative robot safety standard adoption timelines and digital twin virtualization penetration rates. Cross-checking against automotive OEM foundry automation budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Robot Pedestal Market