
 Smart Payment Market | 2026-2036
Smart Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Payment Market Insights
Enterprise procurement departments is collapsing as the dominant buyer archetype in smart payment infrastructure, while small merchant aggregators and platform-native sellers gain share. PayPal Holdings Inc. leverages its two-sided network to sustain checkout conversion advantages across mid-market e-commerce. Stripe competes on developer experience and API depth, anchoring its position in software-embedded financial services. Adyen differentiates through unified acquiring and issuing capabilities, dominating omnichannel payment orchestration for global enterprises.
Smart payment systems encompass digitally enabled transaction infrastructure that authenticates, routes, and settles payments through encrypted channels with sub-second latency requirements. These systems employ tokenization to replace sensitive card data with non-sensitive equivalents, PCI-DSS compliant architecture, and real-time authorization protocols to secure commerce across physical and virtual environments. Cloud-based deployment models are capturing the fastest expansion as merchants abandon capital-intensive on-premise terminals for elastic, API-driven infrastructure. Artificial Intelligence and Machine Learning segments within the technology dimension are deepening fraud detection precision and dynamic authorization scoring, concentrating margin pools in risk-management adjacencies. Mobile Wallets and NFC Payments within the payment method dimension are maturing in developed markets while QR Code Payments extend penetration in cost-sensitive merchant segments across emerging economies.
The European Banking Authority enforces PSD2 strong customer authentication requirements that mandate two-factor verification for electronic payments above threshold limits, elevating biometric and token-based method adoption. The Reserve Bank of India operationalizes UPI framework guidelines through the National Payments Corporation of India, mandating zero Merchant Discount Rate for small transactions and forcing infrastructure providers to monetize through value-added services. Stakeholders must monitor how central bank digital currency pilots across multiple jurisdictions will recast settlement rails and interchange economics.
Market Dynamics
The collapse of enterprise procurement dominance and the ascent of platform-native merchants is compressing sales cycles and forcing infrastructure vendors to rearchitect distribution for self-serve onboarding.
Growth Catalysts
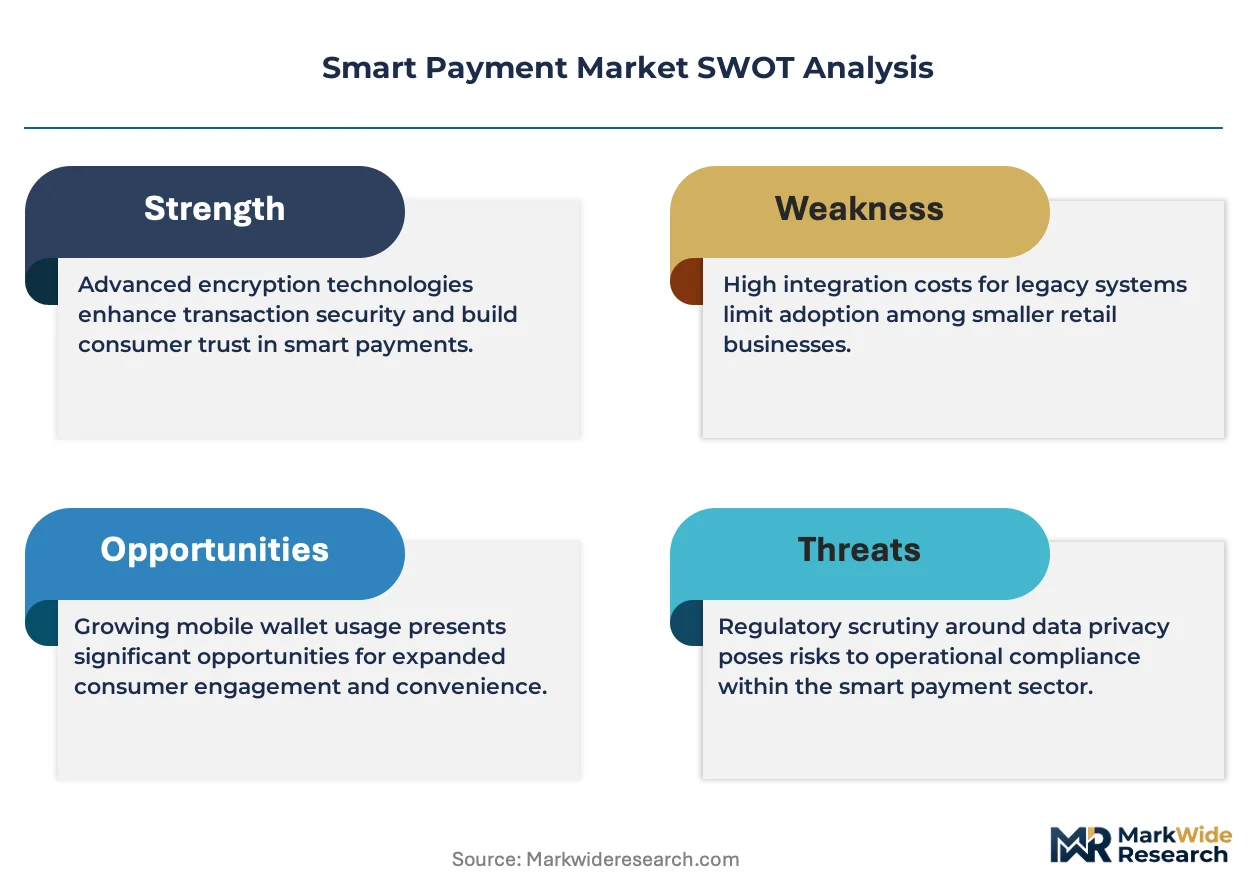
- PSD2 Strong Customer Authentication:The European Banking Authority's two-factor mandate for electronic payments above threshold limits is accelerating biometric and token-based method deployment across EU merchant terminals.
- UPI Rail Expansion:India's zero Merchant Discount Rate policy for small transactions under RBI operational guidelines is forcing infrastructure providers to build value-added service stacks atop real-time settlement rails.
- Cloud API Migration:Elastic, consumption-priced payment infrastructure is displacing capital-intensive on-premise terminal estates among mid-market retailers seeking operational flexibility.
Market Restraints
- Interdependence Concentration:Critical tokenization and fraud-scoring capabilities concentrate among three specialized vendors, creating single-point-of-failure exposure for downstream orchestration platforms.
- Certification Friction:PCI-DSS Level 1 compliance timelines stretch 12-18 months for new entrants, freezing out capital-constrained challengers from enterprise merchant segments.
- Central Bank Digital Currency Uncertainty:Pilot programs across multiple jurisdictions threaten to recast settlement economics and interchange structures before commercial models mature.
Strategic Opportunities
- QR Code Penetration:Cost-sensitive merchant segments across Southeast Asia and Latin America remain underpenetrated by NFC infrastructure, opening white space for camera-based payment rails.
- AI-ML Convergence:Machine learning fraud detection layered atop real-time authorization streams enables dynamic scoring premiums in risk-management adjacencies.
- Embedded Finance Channels:Software platforms serving vertical SaaS merchants represent a direct distribution channel bypassing traditional ISO and acquiring bank relationships.
Industry Challenges
- Legacy Core Integration:Bank-grade payment processors face multi-year replatforming cycles to replace COBOL-based authorization engines with cloud-native architectures.
- Specialized Talent Scarcity:Cryptographic security engineering and real-time systems architecture expertise concentrates among a narrow cohort of fintech alumni and defense-sector migrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Payment Market |
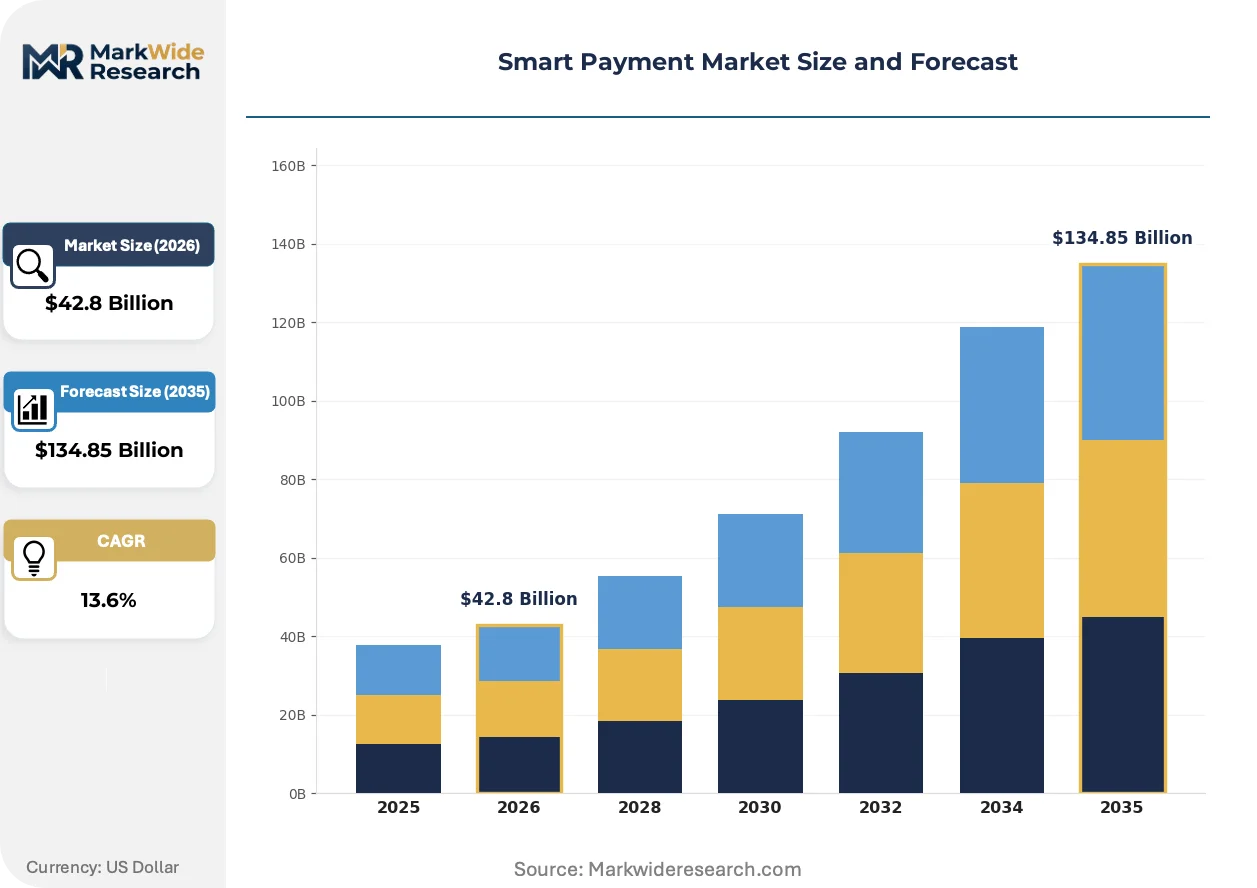
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Contactless Cards, Mobile Wallets, QR Code Payments, NFC Payments, Biometric Payments Technology: Blockchain, Cloud-based, Artificial Intelligence, Machine Learning, Tokenization End User: Retailers, Hospitality Operators, Transportation Providers, Educational Institutions, Government Agencies Deployment Type: On-Premise, Hosted, Cloud, Hybrid, SaaS |
| Companies Covered | PayPal Holdings Inc., Google LLC, Apple Inc., MasterCard, Samsung Electronics, American Express Company, Stripe, Square Inc., Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Payment Market Trends and Innovations
Tokenization architectures and biometric authentication layers are compressing fraud exposure windows while expanding merchant acceptance modalities beyond traditional card-present boundaries.
SoftPOS technology is miniaturizing merchant acceptance hardware by converting standard NFC-enabled smartphones into payment terminals without dedicated peripheral devices. Small merchant aggregators and sole proprietors across India and Brazil are adopting SoftPOS at rates exceeding traditional POS deployment. This is miniaturizing the capital barrier to payment acceptance and collapsing the addressable market for conventional terminal manufacturers.
The EU AI Act's risk-based classification framework is imposing algorithmic transparency requirements on automated fraud scoring systems deployed across European payment networks. Providers must now document training data provenance and decision logic for high-risk AI applications. Machine learning-based authorization platforms serving EU merchants are rearchitecting model governance stacks to satisfy conformity assessment obligations.
Merchant acquisition is fragmenting away from bank-direct relationships toward platform-embedded onboarding flows. Vertical SaaS providers in restaurant management, fitness scheduling, and professional services are integrating payment acceptance as a native feature. This pattern is most visible in the United States and United Kingdom where software penetration among small merchants exceeds traditional financial institution reach.
Smart Payment Market Segmentation
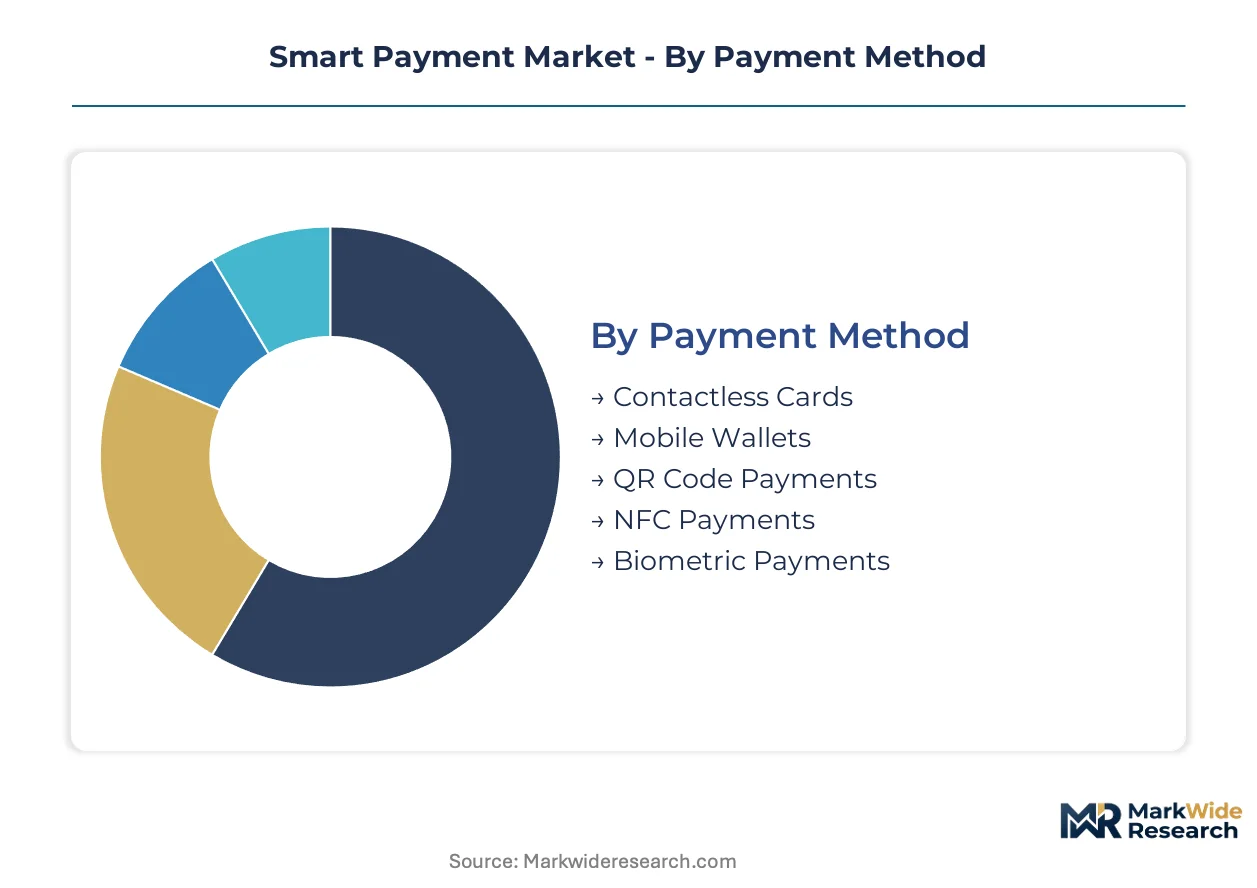
Smart payment infrastructure fragments across multiple technical and commercial dimensions. Each segmentation layer reveals distinct capital requirements, regulatory exposure, and margin structures that shape vendor positioning and buyer procurement patterns.
Payment Method:
Mobile Wallets and Contactless Cards dominate transaction volumes in North American and European retail environments, while QR Code Payments anchor emerging market penetration strategies.
- Contactless Cards:EMV-compliant chip cards with near-field communication capability enable tap-to-pay functionality at physical terminals. Demand concentrates among mid-market retailers in Germany and the United Kingdom seeking checkout velocity improvements without smartphone dependency. The European Banking Authority's PSD2 strong customer authentication mandate has accelerated dual-interface card issuance across EU member states.
- Mobile Wallets:Smartphone-embedded payment credentials stored in secure elements or host card emulation environments. Apple Pay and Google Pay integration drives merchant adoption in United States urban corridors, where platform-native consumers expect seamless in-app and physical checkout experiences. Tokenization requirements under PCI standards elevate infrastructure compliance costs for wallet providers.
- QR Code Payments:Camera-scanned static or dynamic codes linking to payment rails. India's UPI ecosystem processes billions of monthly transactions through merchant-displayed QR codes, bypassing terminal hardware costs entirely.
- NFC Payments:Proximity-based radio frequency protocols enabling sub-second authentication loops. Transit authorities in Japan and South Korea deploy NFC for fare gates, prioritizing throughput over interoperability.
- Biometric Payments:Fingerprint, facial recognition, or palm vein authentication replacing card-present verification. Pilot deployments in Brazil and Saudi Arabia test consumer acceptance of behavioral biometrics at point-of-sale.
Contactless Cards hold the largest share; momentum sits with QR Code Payments.
Technology:
Cloud-based architectures and tokenization layers command premium pricing, while blockchain deployments remain experimental outside cross-border remittance corridors.
- Cloud-based:Elastic compute infrastructure delivering payment orchestration through API endpoints rather than physical data center tenancy. Mid-sized retailers in France and Canada abandon on-premise terminal estates for consumption-priced models that scale with transaction seasonality. Latency requirements below 500 milliseconds demand edge computing partnerships with regional cloud providers.
- Tokenization:Cryptographic substitution of primary account numbers with non-sensitive equivalents that preserve transaction routing logic. Card networks mandate token vault integration for any merchant storing credentials for recurring billing, concentrating vendor relationships around three specialized infrastructure providers. Fraud liability shifts from merchants to issuers when tokenized credentials are compromised.
- Artificial Intelligence:Neural network models detecting anomalous transaction patterns in real-time authorization streams. Acquirers in Singapore deploy AI scoring to reduce false positives on legitimate cross-border purchases.
- Machine Learning:Adaptive algorithms refining risk models through continuous feedback loops on declined transaction outcomes. Brazilian processors apply ML to dynamic 3D Secure challenge flows, reducing cart abandonment.
- Blockchain:Distributed ledger settlement rails eliminating correspondent banking intermediaries. Central bank digital currency pilots in China and Sweden test wholesale settlement applications, not retail payment scalability.
Cloud-based deployment captures the steepest expansion trajectory; tokenization anchors revenue stability through compliance mandates.
End User:
Retailers and hospitality operators drive hardware refresh cycles, while transportation providers and government agencies shape standardization through procurement scale.
- Retailers:Physical and digital merchants requiring omnichannel payment acceptance across storefront, e-commerce, and mobile contexts. Grocery chains in Australia and Mexico prioritize unified transaction reconciliation across formats to reduce finance team overhead. Self-checkout kiosk deployments accelerate demand for contactless reader modules.
- Hospitality Operators:Hotels, restaurants, and event venues managing card-not-present reservations alongside card-present settlement. European boutique hotel groups integrate payment into property management systems to capture guest spending data for loyalty program optimization.
- Transportation Providers:Airlines, railways, and urban transit authorities processing high-velocity, low-margin transactions. Contactless open-loop systems in London and New York City accept bank cards directly at fare gates, eliminating closed-loop card issuance costs.
- Educational Institutions:Universities and school districts managing tuition collection, campus commerce, and donor processing. PCI scope reduction drives SaaS preference over self-managed payment environments.
- Government Agencies:Tax authorities, licensing bureaus, and social service departments requiring citizen-facing payment interfaces. India's state electricity boards migrated to UPI rails for bill collection, eliminating cash handling infrastructure.
Retailers command the largest procurement volume; hospitality operators are gaining share fastest through platform-embedded onboarding.
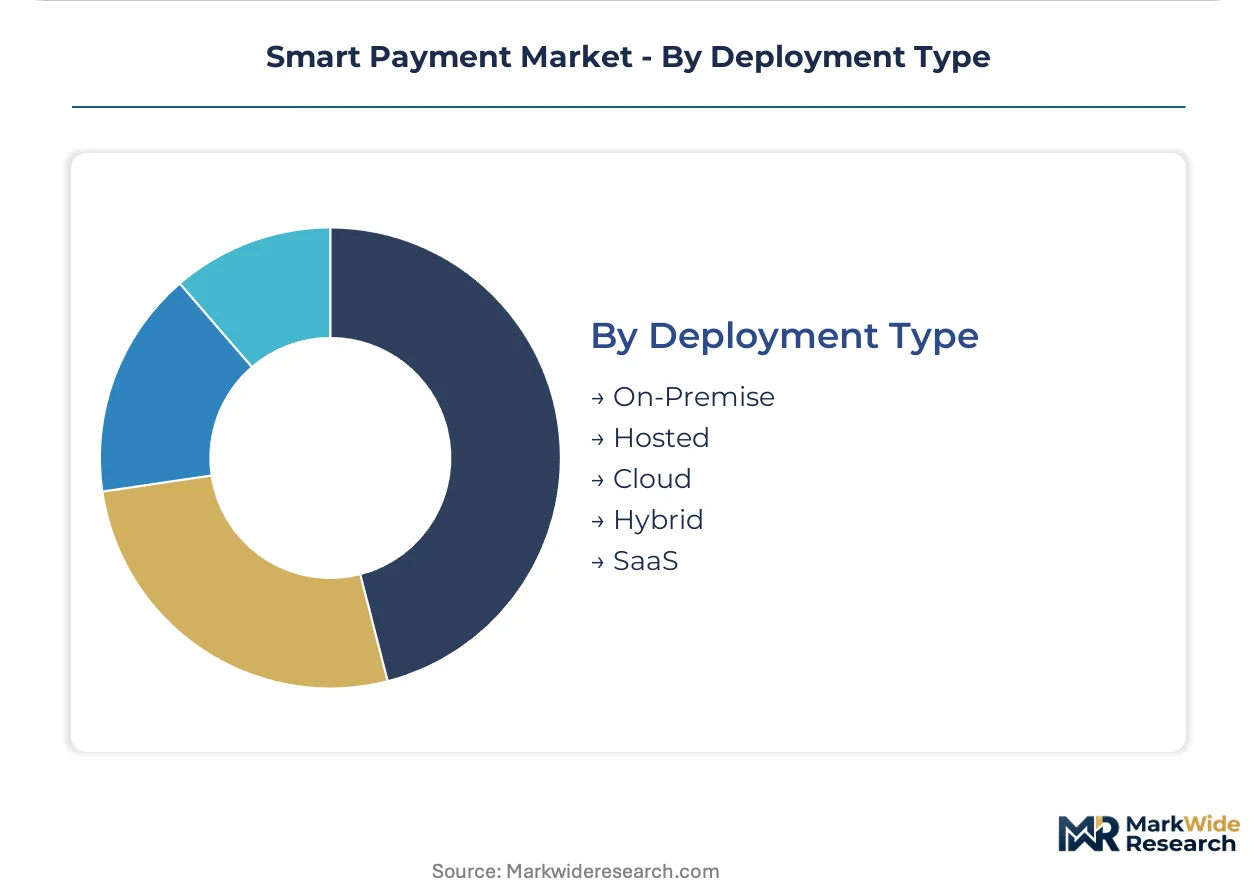
Deployment Type:
Capital intensity and compliance liability distribute unevenly across deployment models, with SaaS and Cloud configurations displacing Hosted alternatives among growth-stage merchants.
- Cloud:Fully managed infrastructure where payment processors maintain PCI-DSS Level 1 certification and data residency controls. Dutch and Danish merchants favor EU-sovereign cloud regions to satisfy GDPR data localization expectations without self-managing security operations.
- SaaS:Software-embedded payment modules where vertical applications integrate acceptance as a native feature. Fitness scheduling platforms in the United States embed Stripe or Square functionality, bypassing traditional merchant acquiring relationships entirely.
- Hybrid:Split architectures retaining sensitive authentication on-premise while routing settlement through cloud orchestration. Large German retailers deploy hybrid models to satisfy Bundesbank audit requirements for transaction logging.
- Hosted:Single-tenant managed services with dedicated infrastructure segmentation. Declining preference as multi-tenant SaaS security models mature and compliance documentation standardizes.
- On-Premise:Self-managed terminal estates and authorization engines requiring direct PCI certification. Legacy bank processors in Italy and Spain maintain COBOL-based systems awaiting multi-year replatforming cycles.
Cloud deployment holds the largest share; SaaS configurations are climbing the fastest through vertical software integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure vendors cluster in jurisdictions with mature regulatory sandboxes and deep capital pools. The Reserve Bank of India, European Banking Authority, and Monetary Authority of Singapore each shape distinct deployment patterns through licensing frameworks and interoperability mandates.
United States
Platform-native merchants in Austin and Miami drive self-serve onboarding demand for API-first payment infrastructure. The Federal Reserve's FedNow instant payment rail forces legacy processors to modernize authorization engines. Stripe and Square anchor developer ecosystems in San Francisco and New York, embedding acceptance into vertical SaaS workflows.
Germany
Mid-market retailers in Hamburg and Munich prioritize unified acquiring for omnichannel reconciliation. The Bundesbank enforces stringent audit requirements for transaction logging that slow cloud migration timelines. COBOL-based legacy systems in Frankfurt's banking cluster face multi-year replatforming cycles.
India
Small merchant aggregators in Bangalore and Delhi-NCR adopt SoftPOS at rates exceeding traditional terminal deployment. The Reserve Bank of India's zero Merchant Discount Rate policy for UPI transactions forces infrastructure providers to monetize through value-added services. The National Payments Corporation of India operationalizes real-time settlement rails processing billions of monthly transactions.
United Kingdom
Fitness scheduling and restaurant management platforms in London embed payment acceptance as native features. The Financial Conduct Authority's open banking standards under PSD2 enable third-party provider access to account data. Vertical SaaS penetration among small merchants exceeds traditional financial institution reach.
Brazil
Sole proprietors in São Paulo and Rio de Janeiro leverage camera-based QR code rails to bypass NFC hardware costs. The central bank's Pix instant payment system mandates interoperability standards that compress merchant onboarding friction. SoftPOS adoption accelerates among street vendors and micro-merchants excluded from conventional acquiring relationships.
Smart Payment Market Competitive Landscape
Concentration sits with platform-embedded orchestrators and unified acquiring specialists rather than traditional bank processors. Two-sided network effects and developer experience moats define tier-one positioning. Strategic archetypes include API-first infrastructure vendors, omnichannel orchestration platforms, and vertical SaaS-embedded payment modules. Competitive moves center on M&A for tokenization capabilities and strategic partnerships with cloud hyperscalers.
Within the two-sided network tier, PayPal Holdings Inc. and Apple Inc. exemplify platform-native checkout conversion advantages. Stripe occupies a position anchoring developer-centric API depth in software-embedded financial services. Adyen represents unified acquiring and issuing capabilities for global enterprise orchestration. These three anchors illustrate how infrastructure vendors defend positioning through distinct distribution architectures rather than price competition.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Google LLC |
| Apple Inc. |
| MasterCard |
| Samsung Electronics |
| American Express Company |
| Stripe |
| Square Inc. |
| Adyen |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts between cloud payment processors and tokenization vault providers lock in both infrastructure access and per-transaction price visibility across multi-year horizons. These arrangements concentrate pricing power among three specialized tokenization vendors while forcing downstream orchestration platforms to absorb margin compression through value-added service stacking.
Pricing Analysis
Volume-discount tiering structures dominate SaaS-embedded payment modules, with per-transaction rates compressing as merchant processing volumes scale past monthly thresholds. Pricing stratifies across enterprise orchestration, mid-market API tiers, and micro-merchant flat-rate bundles, with the latter segment exhibiting acute price sensitivity due to razor-thin retail margins. Cost compression in the micro-merchant tier is intensifying because SoftPOS and QR-code rails eliminate terminal hardware revenue pools. Enterprise buyers demonstrate least price sensitivity, prioritizing unified reconciliation and fraud liability transfer over rate minimization.
Supply Chain Analysis
Strait of Malacca transit chokepoints concentrate semiconductor shipments for NFC controller chips, creating vulnerability exposure for terminal manufacturers dependent on just-in-time component flows. Taiwan, South Korea, and China anchor secure element and cryptographic processor fabrication, while India and Vietnam assemble terminal hardware for cost-sensitive merchant segments. Supply chain risk centers on single-source dependency for EMV kernel certification stacks held by two specialized laboratories. Distribution runs through direct merchant acquiring relationships, ISO channel partners, and vertical SaaS platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in two-sided network effects that compound with each incremental merchant and consumer node. Regulatory entrenchment through PCI-DSS certification timelines and PSD2 strong customer authentication mandates further hardens incumbent positions against capital-constrained challengers.
For Market Incumbents: Fortify tokenization vault relationships through exclusive capacity reservations or captive acquisition of specialized cryptographic infrastructure providers. Cloud-native authorization engine investments must accelerate to outpace FedNow and UPI real-time settlement modernization cycles that threaten legacy switching economics. For New Entrants and Emerging Players: Lead with QR-code payment orchestration targeting sole proprietors and street vendors across Brazil, Indonesia, and Nigeria where NFC terminal penetration remains prohibitive. SoftPOS technology partnerships with smartphone OEMs offer the most penetrable go-to-market angle, collapsing hardware distribution barriers entirely. For Investors and Strategic Acquirers: API-first infrastructure vendors with embedded finance distribution channels represent the highest-conviction acquisition archetype for portfolio construction. Long-term viability hinges on vertical software integration density rather than standalone merchant acquiring scale. Watch central bank digital currency pilot operationalization as the critical inflection signal for settlement rail disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Capability Acquisition | PCI-DSS compliance mandates concentrate vendor relationships around three specialized infrastructure providers. |
| Vertical SaaS Platform Partnership | Fitness scheduling and restaurant management platforms in London embed payment acceptance as native features. |
| SoftPOS Technology Deployment | Smartphone-based terminal conversion collapses capital barriers for micro-merchants across India and Brazil. |
| Real-Time Rail Integration | FedNow and UPI settlement modernization forces legacy authorization engine replacement cycles. |
| AI-ML Fraud Scoring Layer | Dynamic authorization premiums concentrate margin pools in risk-management adjacencies for Singapore acquirers. |
Research Methodology
The analysis maps cloud-based orchestration, tokenization infrastructure, AI-ML fraud detection, and embedded finance channels, each validated through payment platform CTOs, merchant acquiring executives, vertical SaaS product leads, and regulatory compliance officers. Primary interview findings triangulate against SEC 10-K filings, National Payments Corporation of India transaction disclosures, European Banking Authority PSD2 implementation reports, and cloud hyperscaler infrastructure capex data. Bottom-up merchant adoption modeling and top-down payment volume aggregation ensure cross-verification.
Consistency checks validate volume and value outputs against central bank payment statistics, card network quarterly disclosures, and mobile wallet provider user metrics across the projection horizon. Segmentation dimensions modeled include deployment architecture, payment method modality, end-user industry vertical, and regional regulatory framework. CAGRs derive from transaction volume elasticity to merchant density and value-added service attach rates, with cloud API migration velocity and SoftPOS adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained UPI transaction growth, PSD2 enforcement continuity, or stable interchange economics would require recalibration. Forecasts reflect documented assumptions regarding merchant aggregator consolidation and central bank digital currency pilot progression. Practitioners should keep alternative scenarios live as biometric authentication mandates and real-time settlement interoperability standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Netherlands Mobile Payments Market
Payments
Contactless Payment Ring Market
Payments
Italy Gift Cards Market
Payments
India Buy Now Pay Later Services Market
Payments
Taiwan Mobile Payments Market
Payments
Social Media Payment Solution Market
Payments
Asia-Pacific Payments Market
Payments
Uganda Mobile Money Market
Payments
Hungary POS Terminal Market
Payments
Netherlands POS Terminal Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Buy Now Pay Later Platform Market
Payments
Estonia POS Terminal Market
Payments
Third Party Payment Market
Payments
India Mobile Payments Market
Payments
North America Payments Market