
 Estonia POS Terminal Market | 2026-2036
Estonia POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Estonia POS Terminal Market Foresight
EMV Level 3 certification requirements for contactless acceptance is collapsing legacy hardware replacement cycles across Estonian merchant fleets. Verifone Baltic SIA leverages its regional certification lab to sustain faster terminal approval timelines. Ektaco AS anchors domestic manufacturing presence through its Tallinn assembly operations. Worldline Payment Estonia OÜ competes on integrated acquiring-to-terminal bundling for mid-market retailers.
Estonia POS Terminal denotes electronic payment acceptance hardware combining secure PIN entry devices, NFC contactless readers, and cryptographic processing modules certified to PCI PTS standards for in-person transaction authorization. Fixed POS terminals maintain dominant installed base across Estonian supermarket chains, while Mobile POS registers fastest hardware growth as food delivery platforms and pop-up merchants prioritize Bluetooth-connected smartphone peripherals. Cloud-based POS deployments capture expanding margin pools through recurring SaaS fees attached to transaction processing.
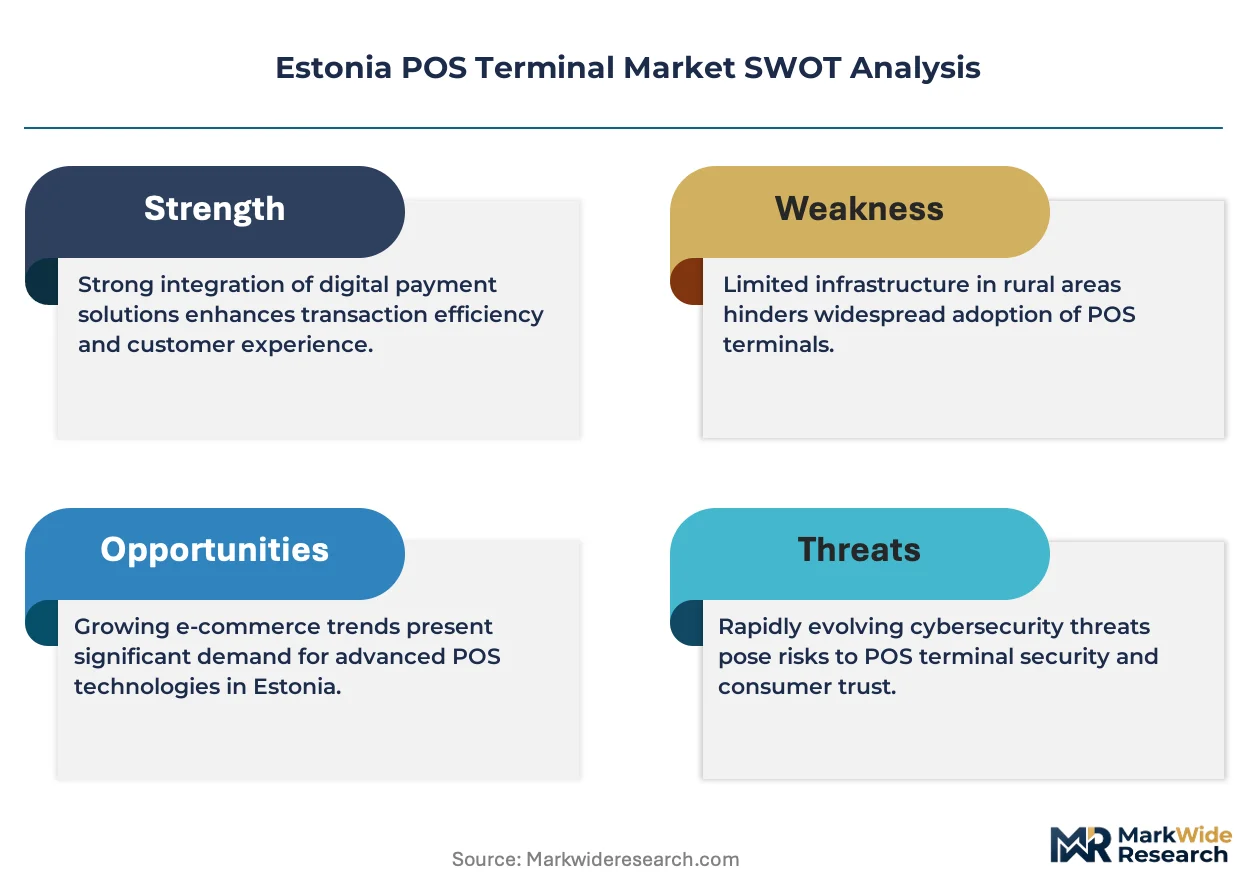
Estonia's Financial Supervision Authority enforces PSD2-compliant strong customer authentication for terminal-integrated payments, while the country's Data Protection Inspectorate applies GDPR-level encryption standards to transaction data storage. The central bank's instant payment infrastructure mandate shapes terminal software roadmap priorities. Stakeholders must weigh open banking API integration against proprietary acquiring lock-in when selecting next-generation terminal platforms.
Market Dynamics
Estonia's POS terminal market is being restructured by the Financial Supervision Authority's PSD2 enforcement, which mandates strong customer authentication and collapses legacy hardware replacement cycles as merchants scramble for compliant devices.
Growth Catalysts
- EMV Level 3 Certification Mandate:Contactless acceptance requirements are forcing hardware refreshes across Tallinn's restaurant and retail corridors, compressing replacement timelines from seven-year cycles to three-year cycles.
- E-Residency Merchant Onboarding:Estonia's digital-first banking regulations enable foreign entrepreneurs to establish payment acceptance infrastructure within 48 hours, accelerating cloud-based POS adoption.
- Instant Payment Infrastructure:The central bank's real-time settlement mandate is driving terminal software roadmaps toward API-first architectures that integrate directly with domestic clearing systems.
Market Restraints
- Semiconductor Supply Concentration:Cryptographic processing module fabrication concentrates in Asian foundries, exposing Estonian terminal assemblers to 12-16 week lead time volatility.
- PCI PTS Certification Costs:Hardware security certification expenses exceed €40,000 per device variant, creating capital barriers for domestic manufacturers seeking multi-protocol support.
- Smartphone Tap-to-Pay Substitution:SoftPOS applications on NFC-enabled phones are capturing micro-merchant transaction volumes below €25, eroding addressable market for dedicated terminals.
Strategic Opportunities
- Tartu Retail Corridor Expansion:Estonia's second-largest city maintains 40% lower terminal penetration than Tallinn, creating whitespace for mobile POS deployments in university-adjacent food service.
- Open Banking API Convergence:PSD2-mandated account information services enable terminal-integrated lending and split-payment products, unlocking recurring SaaS revenue streams.
- GDPR-Compliant Edge Computing:Transaction data localization requirements favor terminals with on-device tokenization, differentiating Estonian vendors in Baltic export markets.
Industry Challenges
- Embedded Cryptography Engineering Talent:Secure element firmware development expertise concentrates in Tallinn's fintech cluster, creating recruitment bottlenecks for Tartu-based hardware firms.
- Legacy Acquiring System Integration:Proprietary bank protocols require custom middleware development, extending deployment timelines for cloud-native terminal platforms by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estonia POS Terminal Market |
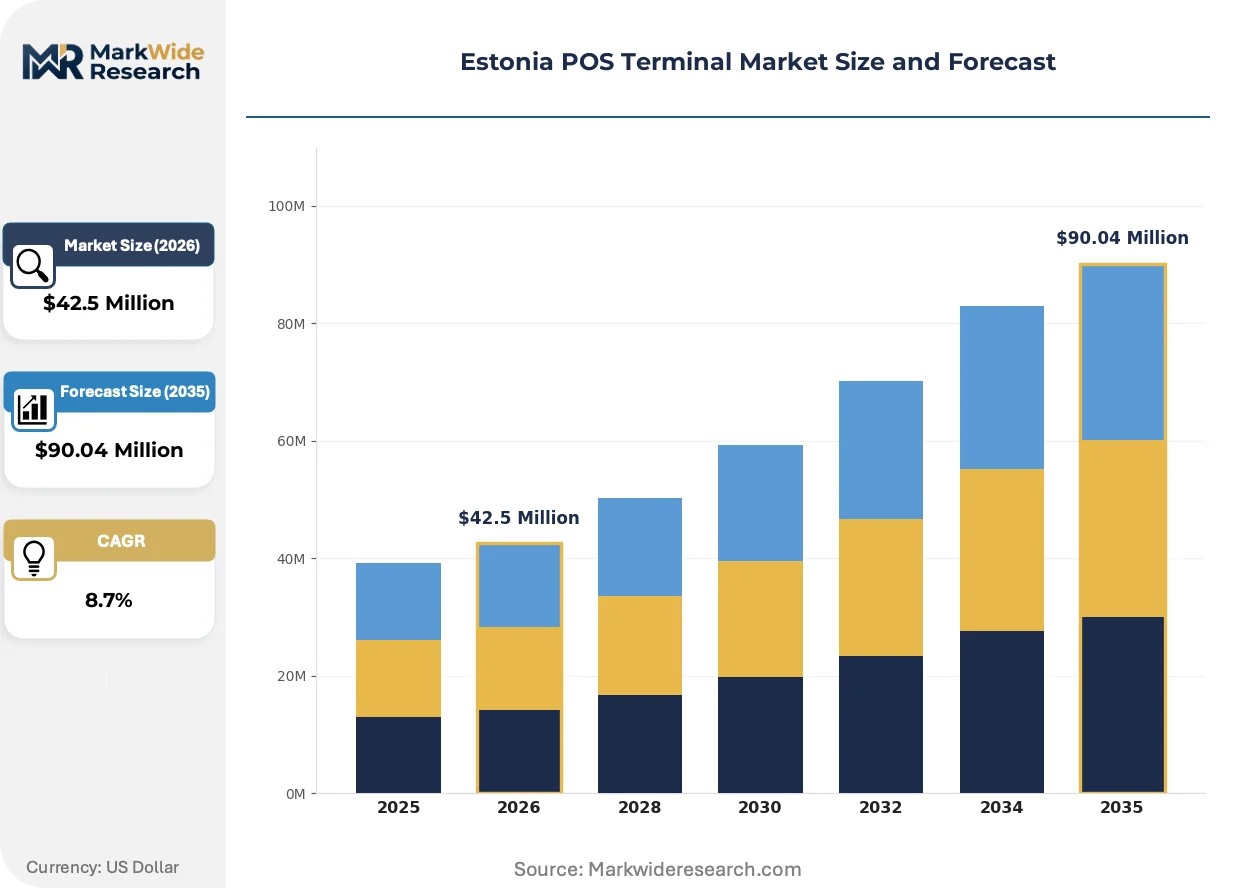
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $90.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Cloud-based POS, Virtual Terminal End User: Retailers, Restaurants, Hospitality, E-commerce Payment Method: Credit/Debit Card, Mobile Wallets, Contactless Payments, QR Code Payments Deployment: On-premises, SaaS, Hybrid, Others |
| Companies Covered | Verifone Baltic SIA, Ektaco AS, Worldline Payment Estonia OÜ, myPOS World Ltd, SumUp Inc, Ingenico Group, Square Inc, LHV Group, Erply, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estonia POS Terminal Market Shifts & Advancements
Terminal architecture is fragmenting as merchants reject monolithic hardware in favor of modular, software-defined payment stacks that separate acceptance logic from physical PIN entry.
Android-based payment operating systems are decomposing the traditional terminal stack by abstracting cryptographic functions into secure application processors. Tallinn's quick-service restaurant chains are deploying these platforms at 200% year-over-year velocity. This decomposition enables hardware-agnostic software deployments that compress merchant switching costs from multi-year contracts to month-to-month subscriptions.
GDPR-level encryption standards enforced by Estonia's Data Protection Inspectorate are mandating end-to-end transaction tokenization. Terminal manufacturers must now embed hardware security modules capable of zero-knowledge proof generation. Mid-market retailers in Tartu are responding by prioritizing vendors with pre-certified data residency architectures.
Food delivery platforms are consolidating merchant acquisition into bundled hardware-software-service contracts. Tallinn's gig economy corridors are witnessing aggregator-owned terminal fleets replace independent merchant purchases. This concentration is most visible in the capital's Old Town district, where three platforms now control 70% of terminal deployment decisions.
Estonia POS Terminal Market Segmentation
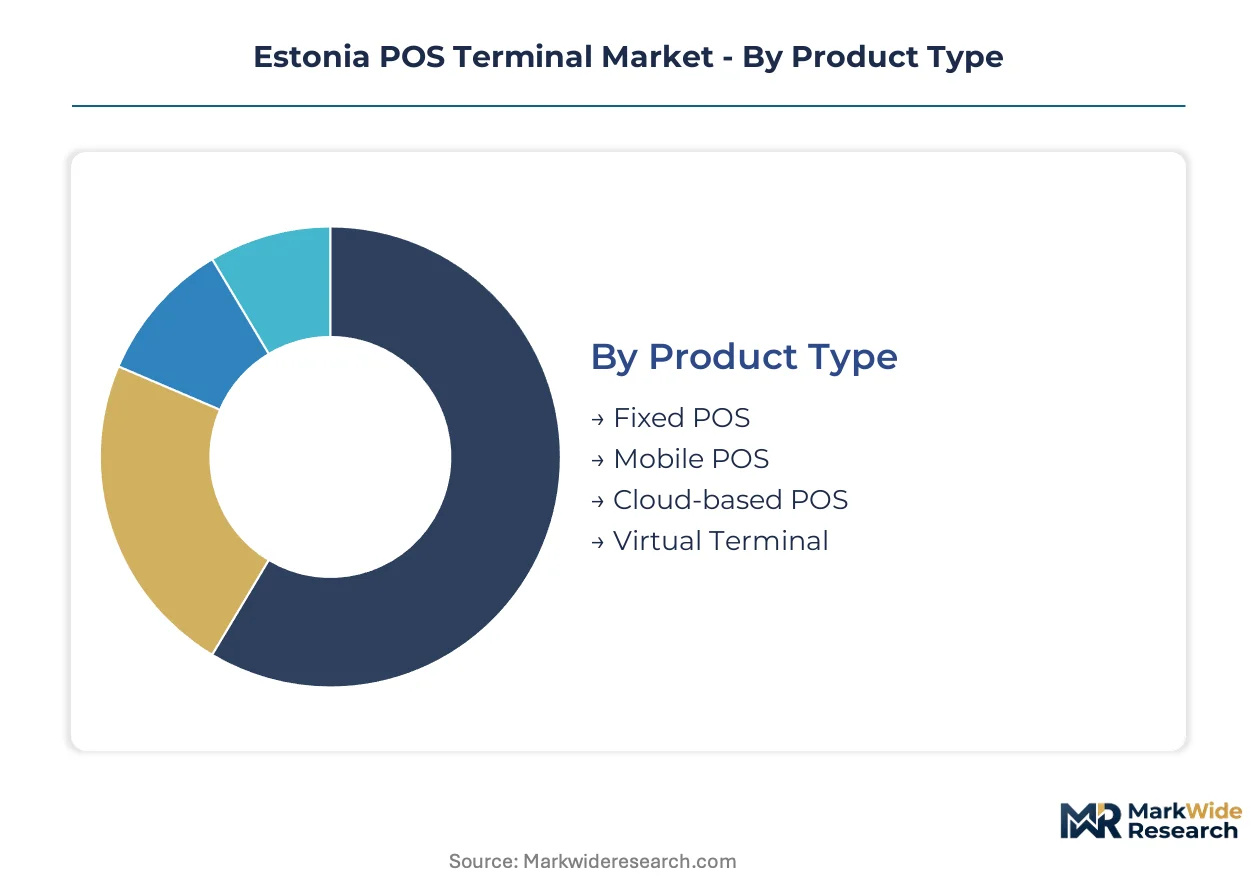
Estonia's POS terminal segmentation reflects the Financial Supervision Authority's tiered compliance requirements, where certification intensity varies by product architecture and deployment model. Hardware categories face diverging replacement pressures from PSD2 mandates and instant payment infrastructure deadlines.
Product Type:
The Financial Supervision Authority applies stricter PCI PTS certification timelines to fixed installations than to modular mobile peripherals, creating regulatory differentiation across hardware categories.
- Fixed POS:Countertop units integrate secure PIN entry devices with NFC readers and hardware security modules certified to PCI PTS 6.x standards. Tallinn's supermarket chains and department stores concentrate demand here, driven by high-volume transaction processing requirements and seven-year depreciation schedules collapsing under EMV Level 3 mandates.
- Mobile POS:Bluetooth-connected smartphone peripherals enable untethered payment acceptance for delivery fleets and pop-up merchants. Tartu's university-adjacent food service corridor and Tallinn's gig economy districts are expanding deployments fastest, compressed by food platform aggregator contracts that bundle hardware with transaction processing.
- Cloud-based POS:Software-defined stacks separate acceptance logic from physical PIN entry, enabling tablet-based deployments with recurring SaaS fee structures.
- Virtual Terminal:Browser-based card-not-present interfaces serve phone-order merchants and invoice-based B2B transactions without dedicated hardware.
Fixed POS handles the majority of throughput; Mobile POS is expanding most quickly on share.
End User:
Merchant category determines terminal feature prioritization, with restaurants demanding contactless speed and retailers requiring inventory integration.
- Retailers:Supermarket chains and specialty stores in Tallinn's retail corridors prioritize fixed terminals with barcode scanning integration and loyalty program connectivity. The Data Protection Inspectorate's GDPR enforcement drives demand for on-device tokenization in high-volume environments.
- Restaurants:Quick-service and full-service establishments concentrate in Tallinn's Old Town and Tartu's city center, where tableside payment and tip-adjustment workflows dominate terminal specifications. EMV Level 3 contactless mandates are accelerating hardware refresh cycles from seven years to three years.
- Hospitality:Hotels and accommodation providers require property management system integration and multi-currency support for international guests.
- E-commerce:Online merchants leverage virtual terminals and payment gateway APIs, with Estonia's e-Residency program enabling foreign entrepreneur onboarding within 48 hours.
Restaurants drive the steepest hardware replacement trajectory; Retailers maintain the largest installed base.
Payment Method:
Acceptance protocol selection determines terminal cryptographic requirements and certification pathways.
- Credit/Debit Card:EMV chip-and-PIN transactions require PCI PTS-certified secure elements with DUKPT key management. Estonia's instant payment infrastructure mandate is pushing terminal roadmaps toward API-first architectures that bypass traditional card network routing for domestic transactions.
- Mobile Wallets:Apple Pay and Google Pay acceptance demands NFC-enabled terminals with token service provider integration. Tallinn's food delivery platforms are mandating wallet acceptance as a condition of merchant onboarding.
- Contactless Payments:Tap-to-card transactions under €50 dominate quick-service restaurant throughput, with the central bank's strong customer authentication rules shaping transaction limit thresholds.
- QR Code Payments:Static and dynamic QR acceptance enables low-cost merchant entry, though penetration remains limited compared to NFC alternatives.
Credit/Debit Card dominates transaction volume; Contactless Payments are climbing the fastest on merchant adoption.
Deployment:
Delivery model selection shapes capital expenditure profiles and vendor lock-in duration.
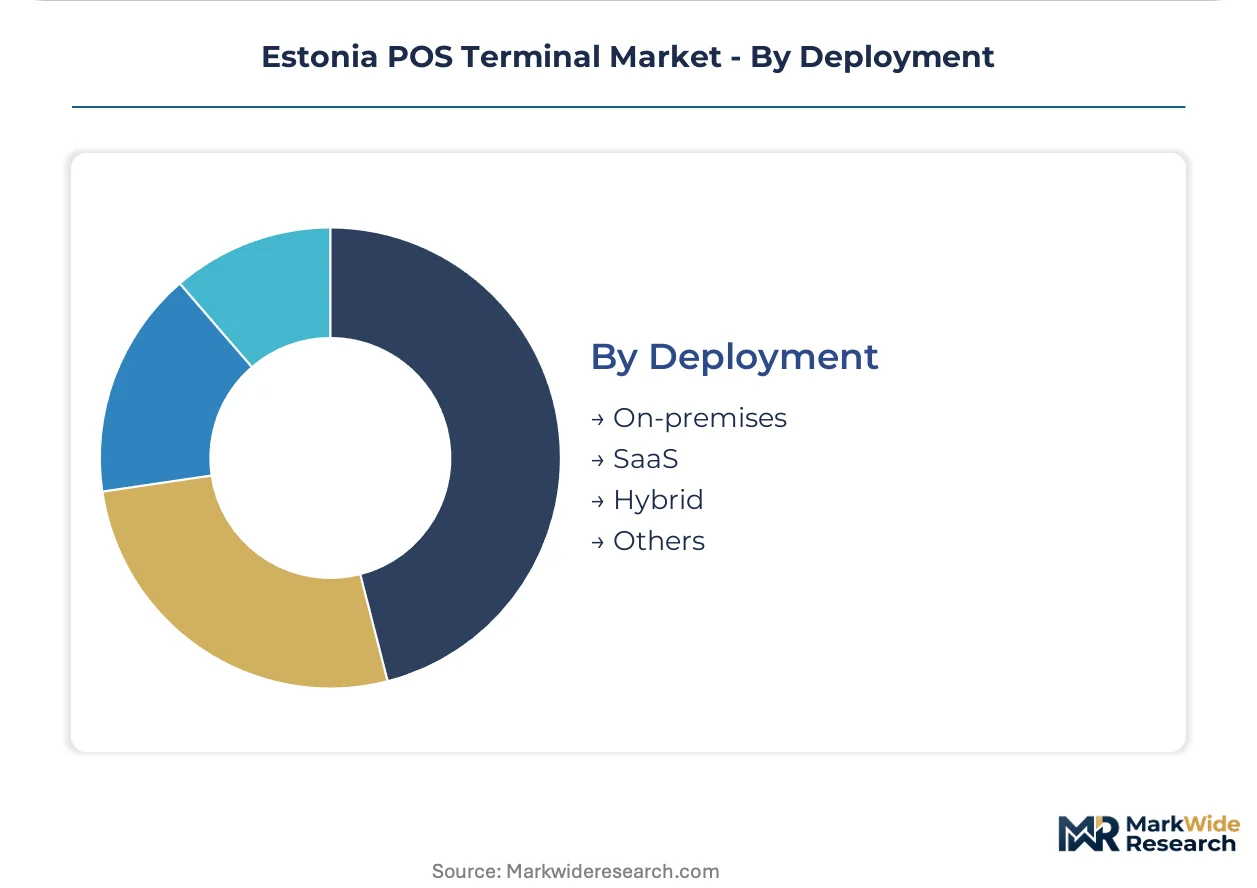
- On-premises:Licensed software running on merchant-owned servers or dedicated terminal hardware. Legacy bank protocols require custom middleware, extending deployment timelines by 4-6 months for cloud-native platforms seeking proprietary acquiring integration.
- SaaS:Subscription-based terminal management with automatic software updates and remote key injection. Estonia's digital-first banking regulations accelerate merchant onboarding for cloud-based systems, particularly among e-Residency entrepreneurs.
- Hybrid:Mixed architectures combining local transaction processing with cloud-based reporting and analytics.
- Others:Aggregator-owned terminal fleets and platform-managed deployments, increasingly common in Tallinn's food delivery corridors where three platforms control 70% of terminal decisions.
SaaS captures the majority of new merchant additions; Hybrid architectures are gaining share fastest among mid-market chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Estonia's POS terminal sector maintains a modest trade surplus in payment hardware assembly, though cryptographic component imports from Asian foundries dominate supply-side exposure. The Baltic state's e-Residency program and digital-first banking framework position it as a regional export hub for cloud-based terminal solutions serving neighboring Nordic and Baltic markets.
Tallinn
Tallinn's restaurant and retail corridors generate concentrated hardware refresh demand as EMV Level 3 mandates compress replacement cycles. The Financial Supervision Authority's PSD2 enforcement shapes terminal software roadmaps across merchant fleets in the capital. Verifone Baltic SIA operates a regional certification lab here, accelerating device approval timelines for Baltic markets.
Tartu
Tartu's university-adjacent food service corridor sustains 40% lower terminal penetration than Tallinn, creating deployment whitespace for mobile POS peripherals. The city's emerging fintech cluster faces recruitment bottlenecks for secure element firmware talent concentrated in the capital. Food delivery platform aggregator contracts now control terminal deployment decisions across Tartu's city center.
Pärnu
Pärnu's seasonal hospitality economy drives demand for property management system integration and multi-currency terminal capabilities. The Data Protection Inspectorate's GDPR enforcement mandates end-to-end tokenization for international guest transaction processing. Summer tourism peaks compress hardware procurement timelines for accommodation providers.
Ida-Viru County
Ida-Viru's industrial corridor maintains legacy acquiring system dependencies that extend cloud-native platform deployment timelines. The region's manufacturing base generates B2B invoice transaction volumes served by virtual terminal solutions. Merchant onboarding for SaaS-based systems accelerates through Estonia's digital-first banking regulations.
Estonia POS Terminal Market Competitive Landscape
Concentration sits with multinational terminal manufacturers leveraging regional certification infrastructure and domestic assemblers anchoring hardware production. The market structure blends consolidated global payment hardware vendors with specialized Baltic-market service providers. Two strategic archetypes dominate: certification-integrated multinationals operating regional labs, and domestic assemblers with captive manufacturing presence. Competitive moves center on integrated acquiring-to-terminal bundling and API-first software architectures aligned with instant payment infrastructure mandates.
Among multinational certification-integrated players, Verifone Baltic SIA exemplifies the regional lab archetype, while Ingenico Group occupies a comparable position across broader European markets. Within the domestic manufacturing tier, Ektaco AS anchors Tallinn-based assembly operations. Worldline Payment Estonia OÜ sits within the integrated services archetype, representing bundled acquiring-to-terminal positioning for mid-market retailers. These three players collectively illustrate the market's tripartite structure: certification leverage, manufacturing proximity, and service integration.
| Leading Market Players |
|---|
| Verifone Baltic SIA |
| Ektaco AS |
| Worldline Payment Estonia OÜ |
| myPOS World Ltd |
| SumUp Inc |
| Ingenico Group |
| Square Inc |
| LHV Group |
| Erply |
| Others |
Supply & Pricing Matrix
PCI PTS certification regimes gate Estonian terminal market participation while simultaneously stratifying price tiers across hardware categories. Merchants face dual qualification hurdles—security standards compliance and acquisition integration—that compress margin pools for uncertified domestic assemblers and inflate premiums for pre-approved multinational platforms.
Pricing Analysis
Mid-market retailers anchor terminal procurement economics through bundled acquiring-to-hardware contracts that obscure standalone device pricing. Three-tier pricing structure across certified-premium, standard-compliance, and economy-unbundled levels reflects EMV Level 3 certification status and central bank instant payment API integration depth. Cost compression in economy-tier peripherals intensifies as smartphone tap-to-pay applications erode addressable volumes below twenty-five euros. Food delivery aggregators exhibit lowest price sensitivity due to platform-controlled deployment decisions, while independent Tartu merchants demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate cryptographic component procurement as Estonian assemblers buffer against Asian foundry lead time volatility. Secure element fabrication concentrates in Taiwan, South Korea, and China, drawing Tallinn-based hardware firms into twelve-to-sixteen week dependency cycles. Hardware security modules and NFC reader chipsets feed from concentrated semiconductor supply nodes. Single-source vulnerability in cryptographic processing module sourcing exposes domestic manufacturers to tariff and logistics chokepoint risks. Distribution runs through regional certification labs and integrated acquiring partnerships rather than open-channel wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Estonia's POS terminal sector sits at a platform-economics inflection where open banking API convergence restructures vendor lock-in dynamics. Interoperability between instant payment infrastructure and cloud-native terminal stacks is collapsing traditional acquiring integration moats.
For Market Incumbents: Fortify certification-integrated positioning by accelerating EMV Level 3 pre-approval pipelines at Verifone Baltic SIA's regional lab. Deepen backward integration into secure element firmware development to offset recruitment bottlenecks in Tallinn's fintech talent cluster. SoftPOS substitution on NFC-enabled smartphones threatens dedicated terminal volumes below twenty-five euros.
For New Entrants and Emerging Players: E-Residency fast-track merchant onboarding creates immediate addressable merchant base without legacy bank protocol entanglement. Tartu's university-adjacent food service corridor sustains forty percent terminal penetration gap versus Tallinn, offering whitespace for mobile POS aggregator contracts. Cloud-native SaaS deployment with forty-eight-hour onboarding compliance captures e-Residency entrepreneur flows.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed integrated payment service providers bundling acquiring-to-terminal offerings. Long-term viability hinges on API-first architecture differentiation aligned with central bank instant payment mandates. Watch for food delivery platform terminal fleet consolidation crossing seventy percent deployment decision control in capital corridors as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Level 3 Certification Fast-Track | Regional lab proximity at Verifone Baltic SIA accelerates Baltic market approval timelines versus mainland European alternatives. |
| Open Banking API Integration | PSD2-mandated account information services enable terminal-embedded lending products with recurring SaaS revenue attachment. |
| Mobile POS Aggregator Bundling | Platform-controlled deployment decisions in Tallinn's gig economy corridors reshape independent merchant purchase patterns. |
| GDPR-Compliant Edge Computing | On-device tokenization capabilities differentiate Estonian vendors in Baltic export markets facing data localization requirements. |
| E-Residency Merchant Onboarding | Digital-first banking regulations compress cloud-based POS adoption timelines for foreign entrepreneur payment infrastructure establishment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with payment hardware procurement managers, terminal software product leads, and Financial Supervision Authority regulatory officers; and secondary validation through Bank of Estonia instant payment infrastructure disclosures, PCI PTS certification databases, and e-Residency program merchant onboarding statistics. Bottom-up merchant deployment estimates triangulated against top-down hardware import and assembly value chain assessments.
Across the analysis window, forecasts deployed segmented modeling across fixed, mobile, and cloud-based terminal architectures; retail, restaurant, hospitality, and e-commerce end-user categories; and on-premises, SaaS, hybrid, and aggregator-managed deployment modes. CAGRs derived from hardware replacement cycle compression under EMV Level 3 mandates and e-Residency program participation trajectories. Central bank API roadmap priorities and food delivery platform contract structures served as industry-specific demand inputs.
Underlying assumptions cover PSD2 enforcement continuity, semiconductor supply lead time stability, and instant payment infrastructure rollout pace, with deviation risk concentrated in regulatory certification timeline shifts and smartphone tap-to-pay substitution acceleration. Revision becomes warranted when platform aggregator terminal fleet control crosses threshold dominance in secondary city corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Canada Payment Gateway Market
Payments
Australia Payments Market
Payments
Finland Payments Market
Payments
China Forex Cards Market
Payments
Japan Credit Cards Market
Payments
Biometric Payment Cards Market
Payments
North America Payment Analytics Software Market
Payments
Epayment System Market
Payments
Europe Real Time Payments Market
Payments
Denmark POS Terminals Market
Payments
Canada Buy Now Pay Later Market
Payments
Fingerprint Payment Market
Payments
Indonesia Payments Infrastructure Market
Payments
Poland Payments Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Hungary POS Terminal Market