
 India Mobile Payments Market | 2026-2036
India Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
India Mobile Payments Market Foresight
Merchant-side buyer concentration is rebalancing as India's kirana stores and street vendors migrate from cash to QR-code acceptance. PhonePe leverages its UPI transaction volume to sustain merchant network effects across Tier-2 and Tier-3 cities. Google Pay anchors customer acquisition through rewards-linked bill payments, while Paytm Payments Bank Limited differentiates via soundbox devices that confirm transactions audibly for low-literacy merchants.
India mobile payments encompass digital fund transfers executed through smartphones using UPI rails, QR codes, NFC chips, or app-based interfaces, with transaction authentication relying on device binding, PIN entry, or biometric verification. The primary purpose is replacing cash handling with real-time, interoperable settlement between consumers, merchants, and enterprises. UPI dominates transaction volume among payment methods, while QR code technology leads deployment due to zero hardware cost for merchants. Small businesses represent the fastest-growing end user category as RBI's zero-MDR policy on UPI removes acceptance friction.
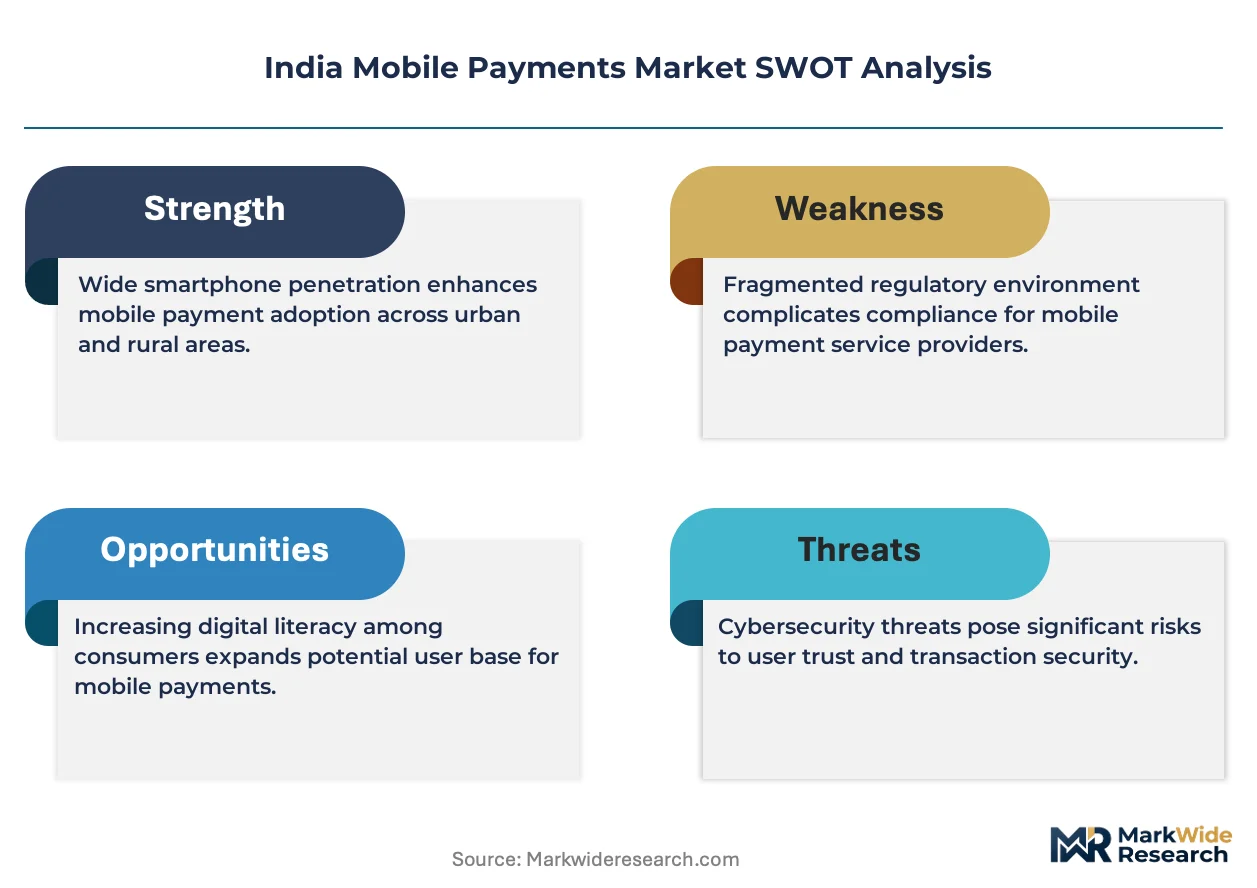
RBI regulates wallet licensing and UPI architecture, while TRAI governs telecom infrastructure that carries SMS-based authentication flows. BIS standards for data localization and the PLI scheme for semiconductor assembly shape hardware cost curves for POS terminals and smartphones. Stakeholders must monitor NPCI's UPI credit line pilots and the central bank digital currency rollout trajectory to anticipate shifts in transaction economics and platform loyalty.
Market Dynamics
RBI's zero-MDR mandate on UPI transactions has collapsed merchant acceptance costs, triggering a structural shift from cash to QR-code settlement across India's informal retail economy. This regulatory compression is redrawing platform economics and forcing wallet providers to monetize through credit distribution rather than interchange.
Growth Catalysts
- UPI interoperability mandates:NPCI's technical specifications force wallet-to-wallet settlement, preventing platform lock-in and expanding addressable merchant pools for all participants.
- Kirana digitization:India's 12 million neighborhood stores are adopting soundbox devices and static QR codes, converting cash-heavy trade corridors into digital transaction zones.
- PLI scheme for fintech infrastructure:Domestic manufacturing incentives for POS terminals and semiconductor assembly are compressing hardware deployment costs for rural merchant acquisition.
Market Restraints
- Zero-MDR compression:RBI's prohibition on merchant discount rates eliminates interchange revenue, forcing platforms to fund operations through alternative monetization vectors.
- Telecom infrastructure concentration:SMS-based OTP flows depend on TRAI-regulated carrier networks where rural coverage gaps create authentication failure points.
- Feature phone persistence:Basic handsets without app ecosystems exclude approximately 40 percent of India's handset base from smartphone-dependent payment interfaces.
Strategic Opportunities
- Tier-3 and Tier-4 urban expansion:Merchant density in cities like Indore, Coimbatore, and Lucknow remains underpenetrated relative to smartphone ownership rates.
- UPI credit line pilots:NPCI's sanctioned overdraft facilities embedded directly into payment rails enable buy-now-pay-later distribution without separate app onboarding.
- CBDC integration trajectory:RBI's digital rupee wholesale and retail pilots position early wallet integrators for central bank liability settlement advantages.
Industry Challenges
- Biometric authentication standardization:Device-level fingerprint and facial recognition APIs fragment across Android OEMs, creating inconsistent user experience patterns.
- Data localization compliance:BIS standards for domestic server storage impose infrastructure replication costs that strain lean fintech operating models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Mobile Payments Market |
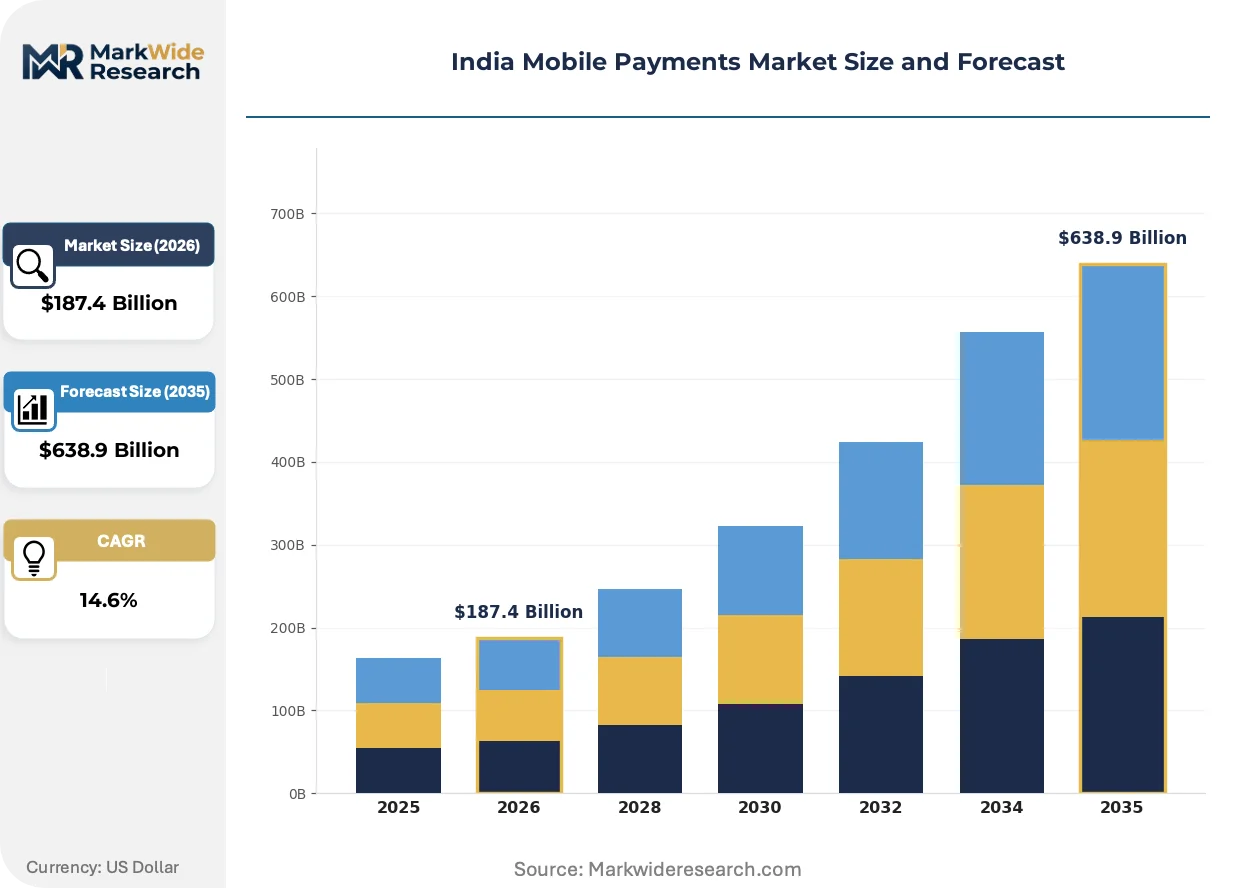
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: UPI, Mobile Wallets, Credit Cards, Debit Cards End User: Retail Consumers, Small Businesses, Large Enterprises, Online Merchants Transaction Type: Person-to-Person, Bill Payments, In-Store Purchases, Online Transactions Technology: NFC, QR Code, SMS-based, App-based |
| Companies Covered | Amazon Pay, ICICI Bank, PhonePe, HDFC Bank, Bharti Airtel, Paytm Payments Bank Limited, MobiKwik, State Bank of India, Google Pay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Mobile Payments Market Shifts & Advancements
Soundbox devices with vernacular audio confirmations are spreading through India's low-literacy merchant base, converting silent QR-code transactions into auditable settlement events. This hardware layer is creating a new interface category between payment rails and informal commerce.
Soundbox technology is overtaking static QR displays as the primary merchant-side interface in India's Tier-2 cities. Kirana operators in Gujarat and Rajasthan are adopting these devices fastest, driven by demand for tamper-proof transaction confirmation. The technology is compressing dispute resolution costs while deepening platform stickiness through hardware lock-in.
RBI's phased implementation of UPI credit lines is reshaping working capital access for micro-merchants who lack formal banking relationships. The policy enables regulated entities to embed overdraft facilities directly into settlement rails. Small traders in Maharashtra and Karnataka are piloting these facilities first, substituting informal moneylender credit with formal digital liquidity.
Merchant acquisition patterns are fragmenting as vertical-specific payment apps target niche trade corridors. Dairy cooperatives in Gujarat, textile clusters in Tamil Nadu, and mandi commissions in Punjab are deploying customized settlement interfaces. These segment-specific platforms are displacing horizontal wallet apps in concentrated supply chains where trade timing and reconciliation rules differ from standard retail.
India Mobile Payments Market Segmentation
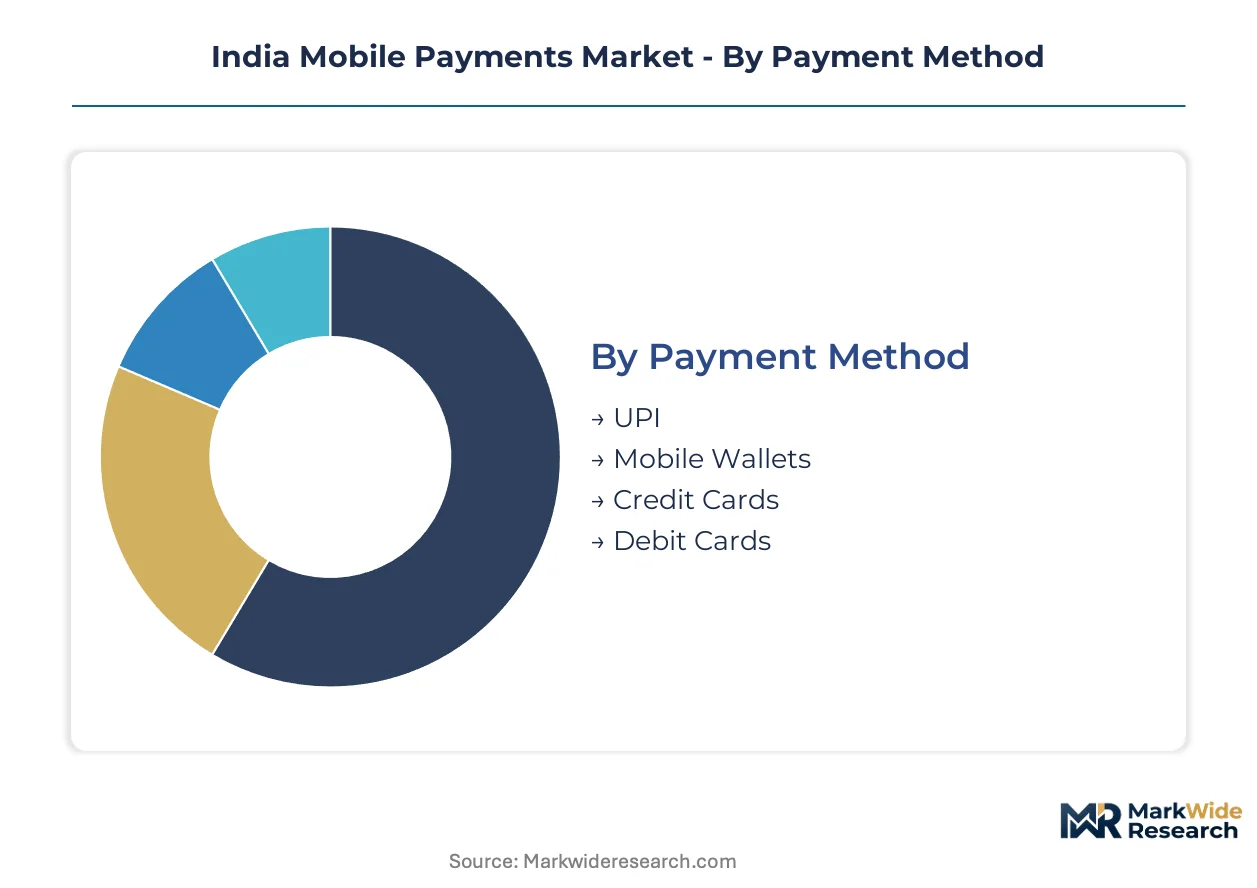
India's mobile payments architecture fragments across four distinct dimensions that determine platform economics and merchant acquisition strategy. Payment method selection drives revenue model viability under RBI's zero-MDR regime. Technology deployment choices separate urban smartphone penetration from rural feature phone constraints.
Payment Method:
Volume concentration favors rails with regulatory cost advantages, while premium monetization clusters around credit-linked instruments.
- UPI:Real-time interoperable settlement protocol operating on NPCI infrastructure with direct bank account linkage. Demand concentrates in Maharashtra and Karnataka where kirana store density overlaps with smartphone penetration, driven by RBI's zero-MDR mandate eliminating merchant acceptance friction.
- Mobile Wallets:Stored-value instruments requiring prepaid license from RBI with closed-loop restrictions until interoperability compliance. Growth concentrates among urban retail consumers seeking rewards-linked bill payment consolidation, constrained by KYC verification bottlenecks in Tier-3 cities.
- Credit Cards:Revolving credit instruments with interchange-funded reward programs and merchant discount rate obligations.
- Debit Cards:Direct account deduction tools with PIN-based authentication and ATM network interoperability.
Mature deployment sits with Debit Cards. Newer deployment is concentrated in UPI.
End User:
Merchant-side adoption patterns diverge sharply between informal cash-heavy trade corridors and formal enterprise procurement systems.
- Small Businesses:Kirana stores, street vendors, and micro-merchants with sub-Rs. 50 lakh annual turnover. Adoption clusters in Gujarat and Rajasthan where soundbox device distribution has converted silent QR transactions into auditable settlement events, propelled by vernacular audio confirmation demand among low-literacy operators.
- Retail Consumers:Individual account holders executing peer-to-peer transfers and merchant payments through smartphone interfaces. Concentration tracks Delhi NCR and Bangalore smartphone penetration curves, with expansion constrained by feature phone persistence in rural handset bases.
- Large Enterprises:Corporate treasury departments managing supplier payments and payroll distribution through bulk transaction APIs.
- Online Merchants:E-commerce platforms and digital service providers integrating checkout SDKs and payment gateway aggregation.
Enterprise deployment commands premium integration fees. Micro-merchant acquisition is expanding most quickly through hardware-subsidized onboarding.
Transaction Type:
Use case segmentation separates high-frequency low-value flows from scheduled high-value obligations with distinct authentication requirements.
- Person-to-Person:Direct fund transfers between individual account holders using mobile number or UPI ID mapping. Volume concentrates in urban migrant corridors for remittance substitution, with growth driven by NPCI's interoperability mandates preventing platform lock-in.
- Bill Payments:Recurring utility, telecom, and subscription settlements with scheduled execution and reward program linkage. Demand clusters among metro retail consumers using Google Pay's rewards-anchored acquisition strategy, constrained by telecom infrastructure gaps affecting SMS-based OTP delivery.
- In-Store Purchases:Physical merchant checkout through QR scan or NFC tap at point of sale.
- Online Transactions:E-commerce checkout flows with escrow protection and dispute resolution protocols.
Scheduled obligations dominate mature transaction profiles. Spontaneous merchant payments represent the steepest expansion trajectory.
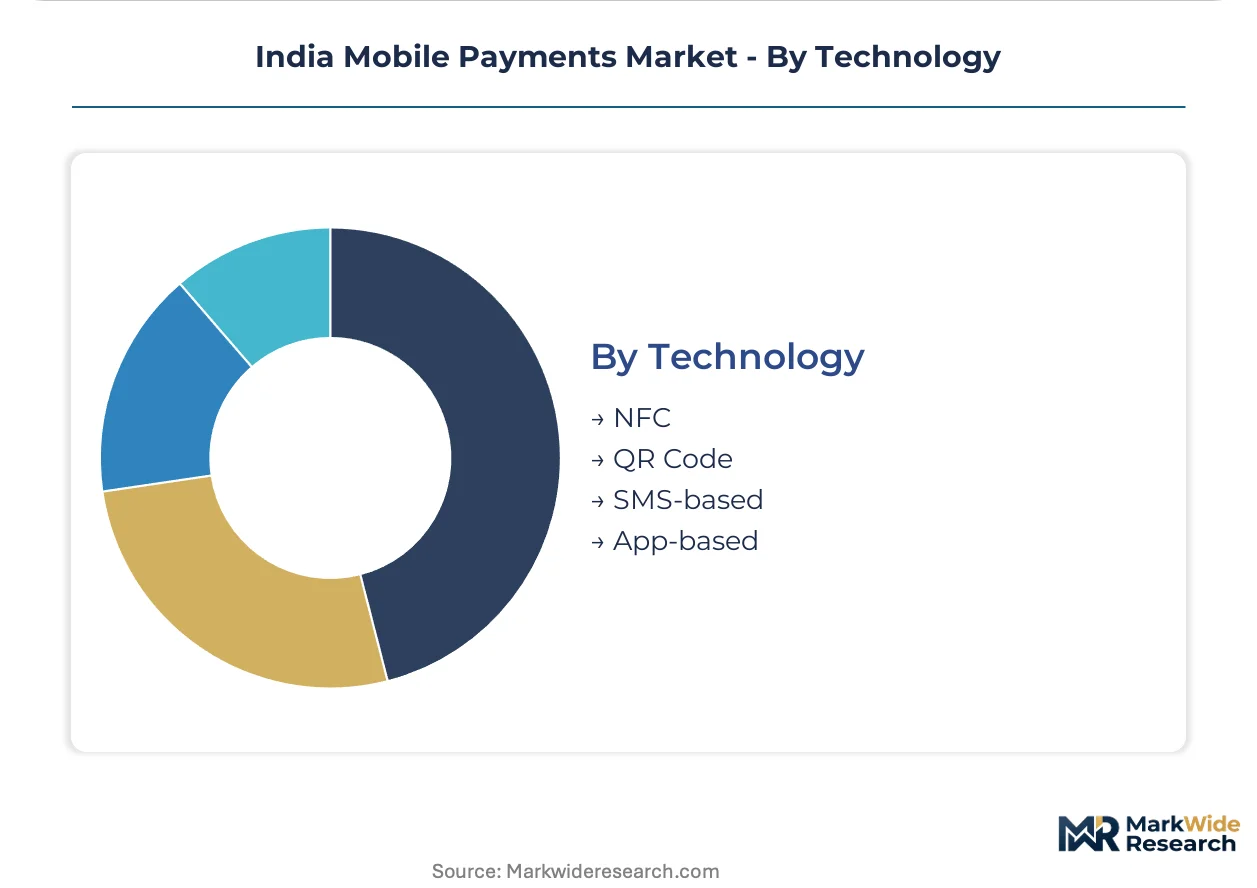
Technology:
Hardware deployment costs and handset ecosystem dependencies create tiered access patterns across India's income distribution.
- QR Code:Static or dynamic matrix barcode displays requiring camera-equipped smartphones for scan initiation. Penetration concentrates in Tier-2 cities like Indore and Lucknow where zero hardware cost enables kirana store adoption, propelled by PhonePe's merchant network effects.
- App-based:Native smartphone applications with biometric authentication, device binding, and SDK-integrated checkout experiences. Deployment tracks premium smartphone ownership in Maharashtra and Karnataka, constrained by Android OEM fragmentation in biometric API standardization.
- NFC:Near-field communication chip protocols with contactless tap authentication and tokenized security.
- SMS-based:Text message instruction flows for feature phone users with USSD fallback protocols.
App-based interfaces anchor premium user experiences. QR code deployment delivers the broadest merchant coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Maharashtra, Karnataka, and Delhi NCR, where urban merchant density and smartphone penetration overlap. Kirana store digitization is accelerating merchant-side adoption across Tier-2 and Tier-3 cities. RBI's UPI interoperability mandates and the PLI scheme for fintech infrastructure have reshaped competitive entry.
Maharashtra
Mumbai and Pune anchor transaction volume through dense kirana networks and corporate treasury adoption. RBI's zero-MDR mandate eliminates merchant friction in Mumbai's informal retail corridors. Small traders in Pune are piloting UPI credit line facilities first, substituting informal moneylender credit with formal digital liquidity.
Karnataka
Bangalore's smartphone penetration drives app-based payment interfaces among tech-savvy retail consumers. TRAI-regulated telecom infrastructure supports SMS-based OTP flows, though rural coverage gaps create authentication failure points. Dairy cooperatives in rural Karnataka are deploying customized settlement interfaces, displacing horizontal wallet apps in concentrated supply chains.
Delhi NCR
The National Capital Region clusters bill payment demand among metro retail consumers seeking rewards-linked consolidation. BIS standards for data localization impose infrastructure replication costs on fintech operating models. Soundbox devices with vernacular audio confirmations are spreading fastest through low-literacy merchant bases in Ghaziabad and Faridabad.
Gujarat
Textile clusters in Surat and Ahmedabad drive vertical-specific payment app adoption with customized reconciliation rules. NPCI's technical specifications force wallet-to-wallet settlement, preventing platform lock-in. Kirana operators in Gujarat are adopting soundbox devices fastest, driven by demand for tamper-proof transaction confirmation.
Tamil Nadu
Chennai's merchant density combines with Coimbatore's underpenetrated Tier-3 expansion potential. The PLI scheme for fintech infrastructure compresses hardware deployment costs for rural merchant acquisition. Textile mandi commissions in Tiruppur are deploying segment-specific settlement interfaces with trade timing rules differing from standard retail.
India Mobile Payments Market Competitive Landscape
Mumbai-based private banks anchor one tier; Bangalore and Noida fintech specialists hold network-effect positions in merchant acquisition. The market structure tilts toward platform consolidation around UPI rails, with horizontal wallet apps defending share against vertical-specific challengers. Three archetypes dominate: bank-owned UPI apps with balance sheet depth, pure-play fintechs with hardware-subsidized onboarding, and telecom-coupled wallets with distribution reach. Competitive moves concentrate on soundbox device deployment subsidies and UPI credit line pilot participation.
Among bank-owned platforms, ICICI Bank and HDFC Bank occupy positions leveraging existing corporate relationships for merchant acquisition. PhonePe and Google Pay exemplify the fintech archetype driving network effects through Tier-2 and Tier-3 city expansion. Paytm Payments Bank Limited anchors the integrated wallet-bank model with soundbox hardware differentiation for low-literacy merchant segments.
| Leading Market Players |
|---|
| Amazon Pay |
| ICICI Bank |
| PhonePe |
| HDFC Bank |
| Bharti Airtel |
| Paytm Payments Bank Limited |
| MobiKwik |
| State Bank of India |
| Google Pay |
| Others |
Supply & Pricing Matrix
Semiconductor assembly cost indices from Taiwan and South Korea cascade through POS terminal manufacturing into three-tier pricing structures across premium soundbox devices, standard QR-code displays, and economy-grade static stickers for India's kirana merchants.
Pricing Analysis
Volume concentration in UPI rails splits from margin capture in credit-linked instruments. Three-tier pricing structure across premium, standard, and economy levels separates soundbox-equipped merchants from static QR adopters from cash-retaining holdouts. Pricing pressure stems from RBI's zero-MDR mandate eliminating interchange revenue, forcing platforms to subsidize hardware acquisition. Micro-merchants in Tier-3 cities exhibit highest price sensitivity, while large enterprise treasury clients accept premium API integration fees.
Supply Chain Analysis
POS terminal assembly rests on semiconductor fabs in Taiwan, display panel manufacturers in South Korea, and battery cell producers in China. Critical inputs include NFC chips, audio confirmation modules, and tamper-evident casings. Single-source vulnerability concentrates in advanced semiconductor nodes where geopolitical export controls threaten hardware cost curves. Distribution runs through fintech infrastructure integrators deploying directly to merchant associations in Gujarat and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's mobile payments sector is consolidating around UPI rails as zero-MDR compression forces sub-scale wallet providers toward exit or acquisition. RBI's interoperability mandates prevent platform lock-in, eroding defensive moats for undifferentiated players.
For Market Incumbents: Deepen merchant hardware lock-in through soundbox device subsidies and vernacular audio confirmation patents. Defend against vertical-specific payment apps by embedding customized reconciliation rules for dairy cooperatives and textile mandis. Prioritize UPI credit line pilot participation to capture working capital flows before regional banks consolidate micro-merchant relationships.
For New Entrants and Emerging Players: The premium-to-economy price gap in merchant acquisition hardware exposes white-space opportunity in Tier-4 towns where smartphone penetration exceeds QR-code deployment. Target Indore, Coimbatore, and Lucknow merchant corridors with feature-phone-compatible SMS-USSD fallback protocols. Anchor go-to-market through dairy cooperative and mandi commission verticals where horizontal wallet apps lack trade-timing customization.
For Investors and Strategic Acquirers: Distressed-cycle entries favor soundbox hardware specialists with locked-in kirana relationships in Rajasthan and Gujarat. Long-term viability hinges on central bank digital currency integration readiness and NPCI credit line distribution licenses. Monitor RBI's phased CBDC retail pilot expansion as inflection signal for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Soundbox Device Deployment Subsidy | Hardware lock-in converts silent QR transactions into auditable, dispute-resistant settlement events for low-literacy merchants. |
| UPI Credit Line Pilot Participation | NPCI-sanctioned overdraft embedding captures micro-merchant working capital flows ahead of regional bank consolidation. |
| CBDC Integration Development | RBI digital rupee readiness positions early movers for central bank liability settlement advantages in wholesale corridors. |
| Vernacular Audio Confirmation Patent | Intellectual property in Tamil, Gujarati, and Hindi voice modules creates defensive moats against hardware commoditization. |
| Vertical-Specific SDK Customization | Tailored reconciliation rules for Surat textile clusters and Tiruppur mandis displace horizontal apps in concentrated supply chains. |
Research Methodology
Independent corroboration across NPCI transaction volume disclosures, RBI circular archives, and PLI scheme beneficiary registries underwrites the qualitative findings. Primary interviews with payment platform executives, merchant acquisition heads, and kirana association leaders combined with secondary validation from TRAI telecom coverage reports, BIS data localization standards, and state-level financial inclusion surveys. Bottom-up merchant density modeling and top-down UPI volume aggregation triangulate market sizing.
Comparable-period anchoring to pre-interoperability mandate transaction structures established baseline platform economics across the projection horizon. Segmentation dimensions modeled include payment method rails, end-user merchant categories, transaction type use cases, and technology deployment tiers. CAGRs derive from smartphone penetration curves, kirana digitization rates, and hardware cost compression trajectories. Forecast inputs incorporate RBI CBDC pilot velocity and NPCI credit line sanction timelines.
Inputs from NPCI, RBI, and state financial inclusion departments were available through the study window; gaps in real-time Tier-4 merchant adoption telemetry introduce uncertainty bands around penetration trajectories. Forecasts reflect documented assumptions regarding regulatory continuity in zero-MDR policy and PLI scheme extension. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Forex Cards Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Recurring Payments Market
Payments
Bill Splitting Apps Market
Payments
Romania POS Terminals Market
Payments
Transaction Monitoring Market
Payments
GCC Payment Gateway Market
Payments
US Buy Now Pay Later Services Market
Payments
Mexico Real Time Payments Market
Payments
Mobile Payment Security Market
Payments
Kenya Mobile Money Market
Payments
Money Transfer Agencies Market
Payments
Africa Mobile Money Market
Payments
Canada Prepaid Cards Market
Payments
EMV Card Market
Payments
Clearing Houses and Settlements Market