
 India Buy Now Pay Later Services Market | 2026-2036
India Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Buy Now Pay Later Services Market Foresight
A shortage of certified credit risk analysts and embedded finance engineers is redrawing competitive boundaries in Indian BNPL. Flipkart Pay Later leverages its captive e-commerce traffic to sustain low customer acquisition costs. Paytm Postpaid anchors its position through UPI-linked credit lines that compete directly with traditional card products. Bajaj Finserv differentiates via its offline merchant network that dominates electronics and appliance financing in semi-urban markets.
Buy Now Pay Later services constitute short-term, point-of-sale credit products typically structured as interest-free installments or revolving credit lines with tenures under ninety days, underwritten through alternative data models rather than traditional bureau scores. The primary commercial purpose is converting price-sensitive consumers into immediate purchasers while shifting default risk to specialized non-bank lenders. Retail customers and working professionals represent the deepest addressable pools, while instant credit and flexible payment plans capture disproportionate transaction volume due to their frictionless checkout integration. E-commerce and electronics verticals concentrate margin pools because higher average order values justify the cost of real-time underwriting infrastructure.
RBI guidelines on digital lending, the CEA's oversight of payment system stability, and BIS standards for data security collectively shape product design, forcing platforms to disclose all-in costs upfront and maintain escrow-based fund flows. SEBI's evolving stance on securitization of BNPL receivables will determine whether originators can access institutional capital at scale. Stakeholders must monitor how the central bank's periodic tightening of consumer credit norms affects approval rates and portfolio quality in a market where regulatory arbitrage once drove expansion.
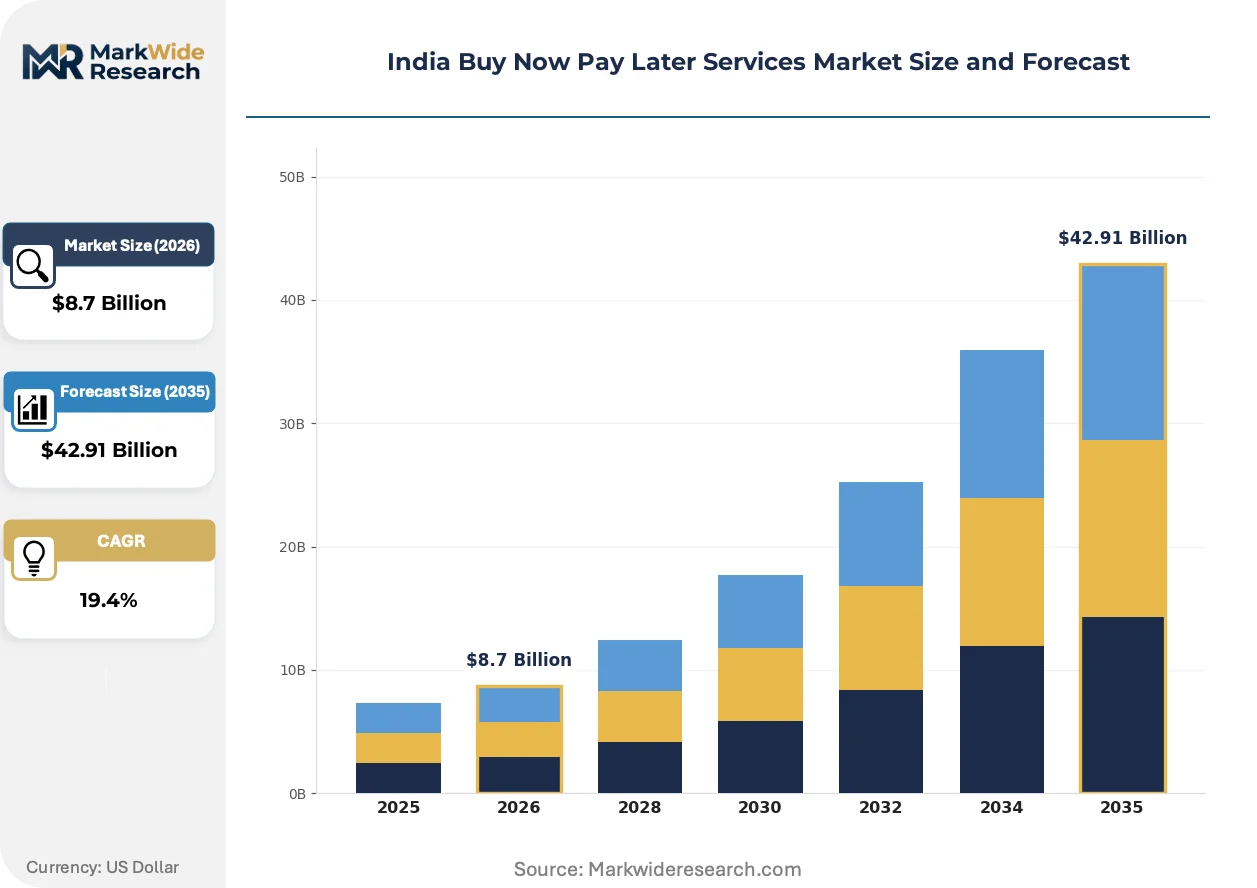
Market Dynamics
RBI's digital lending guidelines and UPI's integration with credit lines are forcing BNPL providers to rebuild core infrastructure around escrow-based fund flows and upfront cost disclosure, compressing margins while raising compliance barriers for new entrants.
Growth Catalysts
- UPI-linked credit infrastructure:The National Payments Corporation of India's UPI 2.0 credit line feature enables real-time disbursement at merchant checkouts, accelerating adoption in tier-two and tier-three cities where card penetration remains minimal.
- Electronics and appliance financing:High average order values in consumer durables justify real-time underwriting investments, with merchant-embedded BNPL converting price-sensitive buyers into immediate purchasers at point-of-sale.
- Maharashtra-Karnataka-Telangana corridor:Concentrated merchant network density and smartphone penetration above national averages create self-reinforcing adoption loops in these three states.
Market Restraints
- Certified credit risk analyst shortage:Talent scarcity in alternative data underwriting and embedded finance engineering limits platform scaling and forces wage inflation for specialized roles.
- CEA payment system oversight:Heightened scrutiny of non-bank payment system operators imposes operational compliance costs and restricts certain fund flow structures previously used for capital efficiency.
- Traditional credit card substitution:Sustained bank marketing of zero-cost EMI conversions on existing cards competes directly with BNPL value propositions among prime borrowers.
Strategic Opportunities
- Tier-three city expansion:Underpenetrated markets in Uttar Pradesh, Bihar, and Madhya Pradesh offer first-mover advantages for platforms building offline merchant networks in electronics retail.
- SEBI securitization framework evolution:Regulatory clarity on BNPL receivables pooling would unlock institutional capital access at scale, lowering originator funding costs.
- Alternative data + AI convergence:Integration of telecom payment histories, utility bill patterns, and e-commerce behavior signals enables approval rate expansion without bureau score dependency.
Industry Challenges
- Real-time underwriting infrastructure capex:Sub-second decision engines require sustained investment in cloud compute and data pipeline architecture, straining balance sheets before portfolio scale.
- RBI periodic consumer credit norm tightening:Unpredictable regulatory adjustments to exposure limits and debt-to-income thresholds force continuous product reconfiguration and approval algorithm recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Buy Now Pay Later Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Retail Customers, Online Shoppers, Students, Working Professionals Service Type: Instant Credit, Flexible Payment Plans, Short-Term Financing, Interest-Free Options Industry Vertical: E-Commerce, Travel, Electronics, Fashion Platform: Mobile Apps, Websites, In-Store Solutions, Third-Party Integrations |
| Companies Covered | MobiKwik ZIP, Flipkart Pay Later, Paytm Postpaid, ePayLater, Simpl, LazyPay, ZestMoney, Bajaj Finserv, Amazon Pay Later, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Buy Now Pay Later Services Market Shifts & Advancements
Product architecture in Indian BNPL is converging around three vectors: embedded checkout experiences, regulatory-compliant fund flow engineering, and alternative data-driven underwriting that bypasses traditional credit infrastructure.
Embedded finance SDKs are miniaturizing the integration burden for mid-tier e-commerce platforms and offline POS systems. Merchant developers in apparel and grocery verticals are adopting pre-built checkout modules within weeks rather than months. This compression is miniaturizing the technical moat that once separated large platforms from regional competitors, forcing differentiation toward underwriting sophistication rather than distribution control.
RBI's 2022 digital lending guidelines mandate escrow account structures and prohibit balance sheet commingling, fundamentally altering capital flow architecture. Non-bank lenders must now maintain stricter segregation between own funds and borrowed capital, raising operational complexity. The guidelines most affect platforms previously reliant on synthetic securitization structures, which are reconstituting as direct assignment models with enhanced disclosure obligations.
First-time digital credit users in semi-urban India are gravitating toward single-purpose credit lines tied to specific merchant relationships rather than general-purpose revolving products. This preference shift favors platforms with captive e-commerce traffic or dense offline electronics networks. The behavior is most visible in Karnataka and Telangana, where smartphone-first users demonstrate higher stickiness to merchant-anchored products than to standalone credit apps.
India Buy Now Pay Later Services Market Segmentation
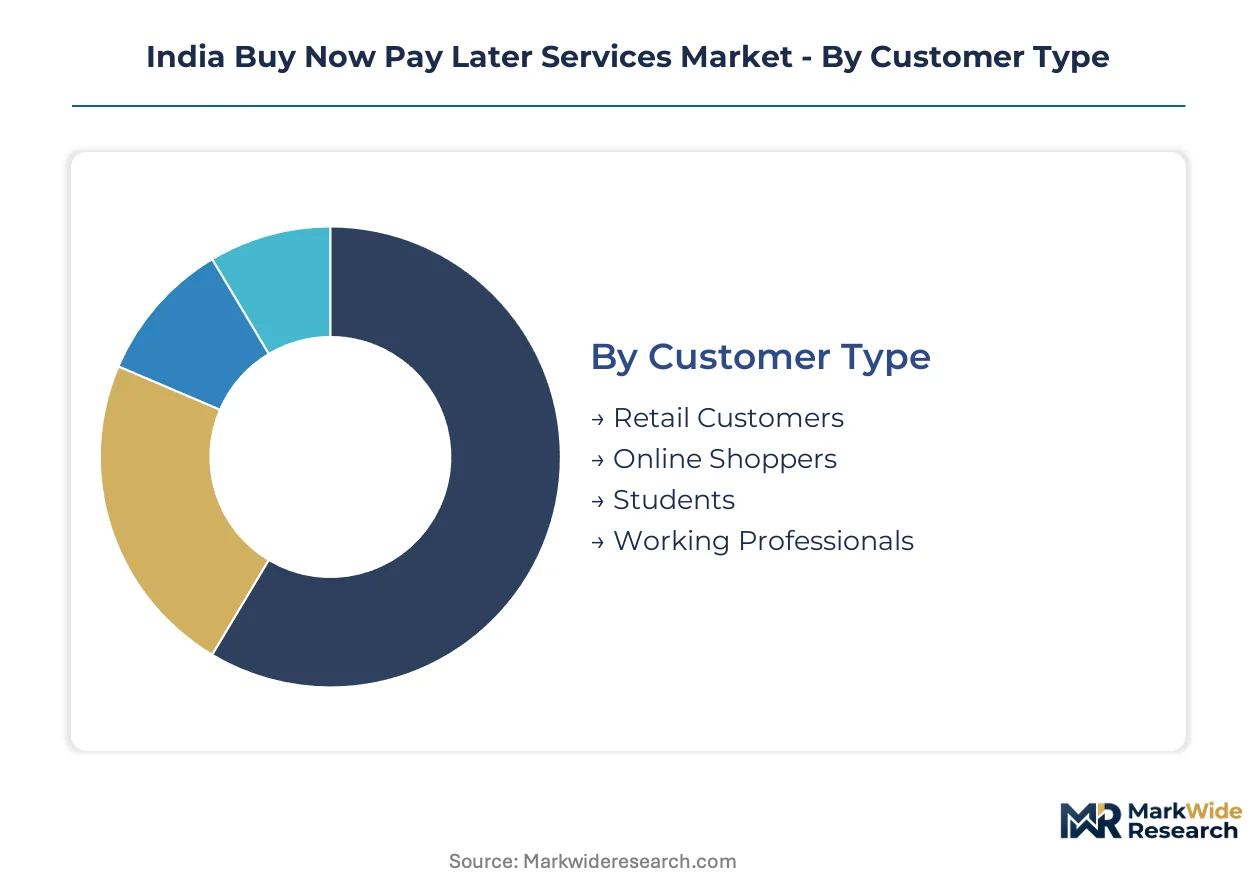
Segmentation in Indian BNPL reveals how regulatory treatment varies across customer profiles and transaction architectures. RBI's digital lending guidelines apply differential compliance burdens based on fund flow structures and borrower sophistication levels.
Customer Type:
RBI's debt-to-income thresholds and disclosure mandates hit retail segments unevenly, with salaried professionals facing streamlined KYC while students trigger enhanced verification protocols.
- Retail Customers:Price-sensitive households in tier-two and tier-three cities dominate transaction volumes. Maharashtra and Karnataka concentrate this demand due to merchant density and smartphone penetration creating frictionless onboarding environments.
- Working Professionals:Salaried employees with documented income streams access higher credit limits and longer tenures. Their predictable cash flows reduce underwriting costs for platforms, making this segment margin-accretive despite lower per-transaction fees.
- Online Shoppers:E-commerce-embedded users convert at checkout with minimal decision friction.
- Students:Campus-linked credit lines require parental guarantees or institutional partnerships under RBI consumer protection norms.
Established volume favors working professionals; emerging adoption favors retail customers in semi-urban markets.
Service Type:
Cost-to-serve varies dramatically across product architectures, with interest-free models demanding subsidy recovery through merchant discount rates while credit lines require sustained funding cost management.
- Instant Credit:Sub-second approval engines powered by alternative data models enable checkout-embedded disbursement. Telangana and Karnataka merchants report highest activation rates where UPI infrastructure density supports real-time fund flows.
- Flexible Payment Plans:Customizable installment schedules accommodate irregular income patterns common in gig economy and informal sector employment. The product architecture demands more sophisticated servicing infrastructure but generates superior customer lifetime value through repeat utilization.
- Short-Term Financing:Thirty-to-ninety-day tenures align with salary cycles and reduce rollover risk.
- Interest-Free Options:Merchant-subsidized structures convert price-sensitive browsers into immediate purchasers.
Merchant subsidy burdens concentrate in interest-free options; platform margin sustainability depends on flexible payment plans.
Industry Vertical:
Geographic purchasing power and average order values reshape vertical prioritization, with electronics financing justifying underwriting infrastructure investments that apparel transactions cannot support.
- Electronics:High-value durable purchases in semi-urban Karnataka and Telangana justify real-time decision engine deployment. The vertical's average ticket sizes absorb customer acquisition costs that would render lower-value categories unprofitable.
- E-Commerce:Platform-embedded checkout experiences capture impulse purchase intent before cart abandonment. Maharashtra's dense logistics networks enable same-day delivery confirmation that accelerates credit utilization at point-of-sale.
- Fashion:Apparel BNPL relies on return-rate management and seasonal demand spikes.
- Travel:Ticket financing faces cancellation risk and refund complexity under RBI escrow guidelines.
Electronics anchors current revenue pools; e-commerce is climbing the fastest as checkout integration deepens.
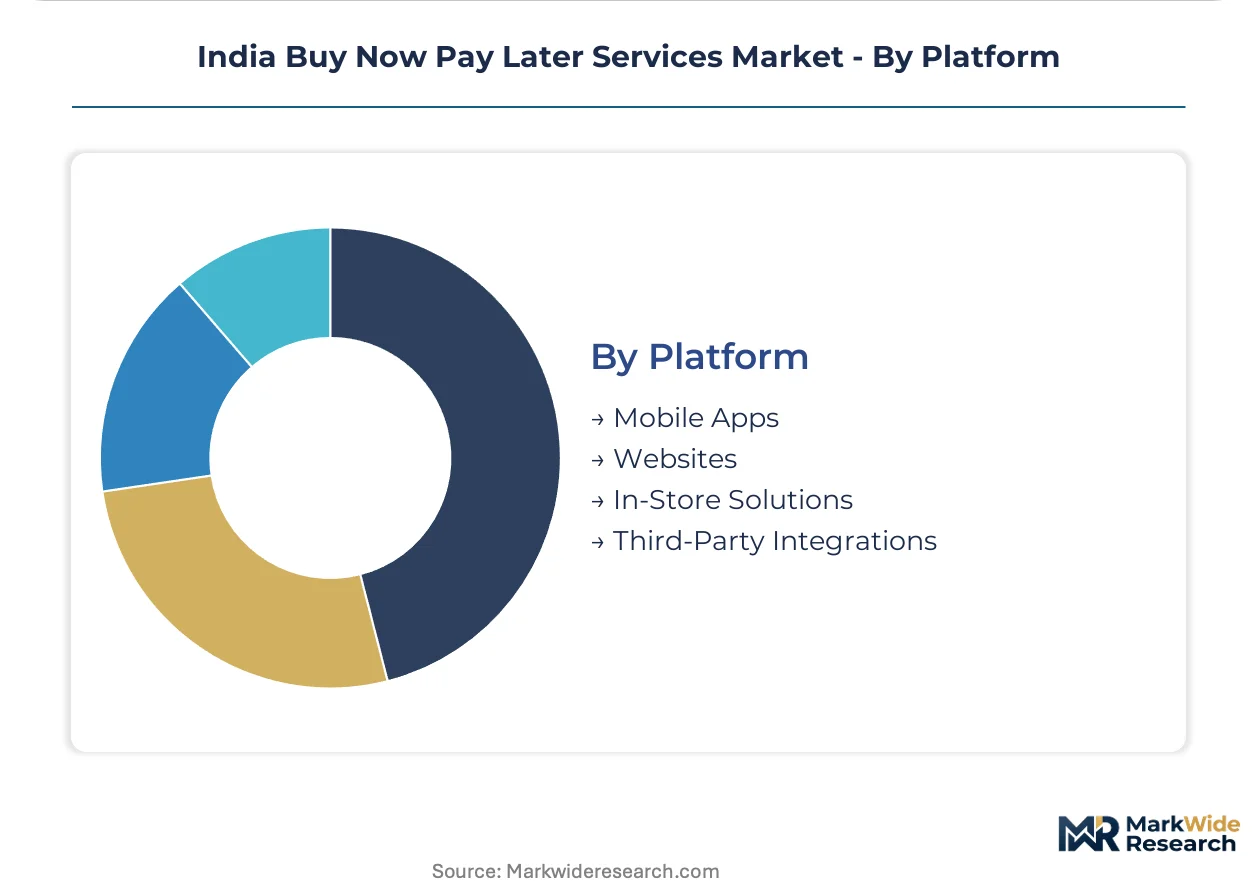
Platform:
Distribution economics favor mobile-first architectures where customer acquisition costs compress through organic app store discovery rather than paid merchant integration campaigns.
- Mobile Apps:Native smartphone applications dominate customer engagement in tier-three cities across Uttar Pradesh and Bihar where desktop penetration remains minimal. Push notification-driven repayment reminders reduce delinquency rates compared to email-dependent channels.
- In-Store Solutions:Offline POS-embedded credit at electronics retailers in semi-urban Telangana converts cash-preferred buyers into digital credit users. The platform requires merchant staff training investments that slow scaling but lock in exclusive relationships.
- Websites:Browser-based checkout experiences serve returning customers with saved credentials.
- Third-Party Integrations:SDK-based embedding spreads technical architecture costs across multiple merchant platforms.
Mobile apps command current transaction dominance; in-store solutions are gaining share fastest through offline merchant exclusivity arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's digital lending guidelines anchor regulatory architecture across Indian states, with UPI credit line integration creating divergent adoption velocities between coastal corridors and interior markets.
Maharashtra
Mumbai's dense logistics networks accelerate same-day delivery confirmation that triggers credit utilization at checkout. The state's consumer protection bureau enforces strict debt-to-income disclosure mandates for BNPL originators. Pune electronics clusters concentrate merchant-embedded financing for smartphone and appliance purchases.
Karnataka
Bengaluru's tech workforce sustains predictable cash flows that reduce underwriting costs for salaried-focused platforms. Karnataka's state-level fintech sandbox permits controlled testing of alternative data models. Mysuru and Mangaluru semi-urban markets demonstrate highest merchant activation rates where UPI infrastructure density supports real-time disbursement.
Telangana
Hyderabad's pharmaceutical and IT salary bases generate stable repayment pools for short-tenure credit products. The state's digital payment adoption initiatives compress merchant onboarding timelines for offline POS solutions. Warangal and Nizamabad electronics retailers convert cash-preferred buyers through exclusive BNPL partnerships.
Uttar Pradesh
Kanpur and Lucknow's underpenetrated tier-three markets offer first-mover positioning for platforms building offline merchant networks. The state's consumer affairs department coordinates with RBI on grievance redressal protocols for digital lending disputes. Varanasi and Agra tourism-dependent merchants experiment with ticket financing despite refund complexity under escrow guidelines.
Tamil Nadu
Chennai's manufacturing workforce accesses flexible payment plans aligned with irregular production cycle incomes. The state's information technology department promotes SDK-based checkout integration for mid-tier e-commerce platforms. Coimbatore and Madurai appliance retail clusters justify real-time underwriting infrastructure deployment through high average order values.
India Buy Now Pay Later Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Indian BNPL ecosystem. E-commerce captives leverage captive traffic for customer acquisition efficiency while independent fintechs invest in alternative data underwriting sophistication. Three archetypes dominate: platform-embedded lenders with merchant exclusivity, UPI-anchored credit line providers, and offline electronics financiers with dense semi-urban networks. Competitive intensity centers on merchant acquisition campaigns and alternative data model calibration.
Among platform-embedded lenders, Flipkart Pay Later and Amazon Pay Later exemplify e-commerce captive strategies that compress acquisition costs through checkout integration. Paytm Postpaid occupies a distinct position anchoring UPI-linked credit infrastructure that competes directly with traditional card products. Bajaj Finserv represents the offline network archetype with merchant exclusivity arrangements in consumer durables financing.
| Leading Market Players |
|---|
| MobiKwik ZIP |
| Flipkart Pay Later |
| Paytm Postpaid |
| ePayLater |
| Simpl |
| LazyPay |
| ZestMoney |
| Bajaj Finserv |
| Amazon Pay Later |
| Others |
Supply & Pricing Matrix
RBI's digital lending guidelines gate both platform qualification and pricing differentiation in Indian BNPL, forcing escrow-based fund flow architectures that raise operational costs while compressing merchant discount rate flexibility across tiered service tiers.
Pricing Analysis
Maharashtra commands premium merchant discount rates compared to Uttar Pradesh and Bihar, where price-sensitive tier-three markets drive subsidy-heavy structures. Interest-free installment products recover costs through merchant fees ranging from premium electronics verticals to economy grocery checkouts. Pricing pressure stems from UPI-linked credit line commoditization as Paytm Postpaid and bank-issued competing products erode differentiation. Retail customers in semi-urban Karnataka exhibit highest price elasticity, while working professionals in Hyderabad and Bengaluru accept modest convenience premiums for flexible payment plans.
Supply Chain Analysis
Container availability constraints at Mumbai and Chennai ports inflate inbound cloud compute infrastructure costs for real-time underwriting engines deployed across Indian platforms. Core technology draws from United States hyperscaler data centers, Singapore-based fintech middleware providers, and domestic Indian cloud zones. Critical dependencies center on sub-second decision algorithms, alternative data pipelines, and UPI switch connectivity. Single-source vulnerability concentrates in NPCI's UPI infrastructure monopoly. Distribution runs through merchant-embedded SDKs, direct bank partnerships, and captive e-commerce checkout integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UPI 2.0's credit line integration disrupts traditional card economics, creating a regulatory-technology inflection that rewards platforms with pre-built compliance infrastructure and punishes late adopters facing rebuild costs.
For Market Incumbents: Consolidate merchant exclusivity arrangements in Karnataka and Telangana electronics clusters before alternative data underwriting capabilities diffuse to regional competitors. Lock in long-term UPI switch access agreements. Invest in certified credit risk analyst pipelines to defend against talent poaching from emerging fintechs.
For New Entrants and Emerging Players: Lead with offline POS-embedded solutions in underpenetrated Uttar Pradesh and Madhya Pradesh tier-three cities where Bajaj Finserv network density remains thin. Target cash-preferred appliance retailers seeking digital conversion. Deploy white-label embedded finance SDKs to compress merchant onboarding timelines.
For Investors and Strategic Acquirers: SEBI's evolving securitization framework reshapes the acquisition landscape by determining which originators unlock institutional capital access. Favor platforms with direct assignment fund flow architectures over synthetic securitization legacies. Watch RBI consumer credit norm tightening frequency as portfolio quality inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| UPI Credit Line Infrastructure Buildout | Real-time disbursement capability at merchant checkout anchors competitive positioning in tier-two cities. |
| Alternative Data Model Certification | RBI-compliant underwriting engines reduce regulatory friction and accelerate approval rate expansion. |
| Merchant Exclusivity Network Expansion | Offline electronics partnerships in semi-urban Telangana lock in high-ticket transaction flows. |
| Escrow-Based Fund Flow Reconfiguration | Digital lending guideline compliance eliminates balance sheet commingling risks for non-bank lenders. |
| Embedded Finance SDK Deployment | Pre-built checkout modules compress integration timelines for mid-tier e-commerce platforms. |
Research Methodology
Operator-level perspectives from BNPL platform executives, merchant acquisition leads, UPI infrastructure engineers, and RBI regulatory affairs specialists anchored the qualitative base. Secondary validation drew from NPCI circulars, SEBI securitization discussion papers, RBI digital lending guideline notifications, and platform disclosure filings. Bottom-up transaction volume modeling triangulated against top-down addressable credit market sizing.
Sensitivity analysis tested approval rate assumptions and funding cost trajectories across the projection horizon. Segmentation dimensions modeled encompass customer type, service architecture, industry vertical, and platform delivery mode. CAGRs derived from cohort-based utilization curves and merchant network expansion run rates. Alternative data model accuracy and UPI credit line activation velocity served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained UPI infrastructure investment and stable regulatory treatment would require recalibration. Forecasts reflect documented assumptions regarding smartphone penetration curves and merchant onboarding velocity. SEBI securitization clarity delays or RBI consumer credit tightening beyond historical patterns would necessitate model revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Third Party Payment Market
Payments
Mobile Wallet Market
Payments
United States Mobile Payment Market
Payments
B2B Payments Market
Payments
United States Clearing Houses and Settlements Market
Payments
Proximity Mobile Payment Market
Payments
Kenya Mobile Money Market
Payments
Asia Pacific Real Time Payment Market
Payments
Freight Audit and Payment Service Market
Payments
Cash Management Software Market
Payments
Australia Payments Market
Payments
Fuel and Convenience Store POS Market
Payments
Consumer Mobile Payment Market
Payments
Denmark Mobile Payments Market
Payments
Germany POS Terminal Market
Payments
Mobile Card Reader Market