
 Asia-Pacific Payments Market | 2026-2036
Asia-Pacific Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Payments Market Outlook
PCI DSS Level 1 certification is unwinding competitive access for cross-border payment processors across the Asia-Pacific region. Alipay leverages its merchant network density to anchor super-app payment ecosystems across mainland China. Visa Inc. sustains infrastructure partnerships with central banks in Thailand and the Philippines to extend real-time settlement rails. Airwallex competes on multi-currency treasury capabilities for mid-market enterprises operating across ASEAN trade lanes.
Asia-Pacific payments encompass the electronic transfer of monetary value between transacting parties through card networks, digital wallets, bank rails, and emerging tokenized instruments, with settlement latency ranging from instantaneous real-time gross settlement to T+2 correspondent banking cycles depending on the underlying infrastructure and jurisdictional clearing arrangements. The primary commercial purpose is to reduce friction in consumer commerce, B2B trade, and remittance corridors while generating interchange revenue and float income for platform operators. Mobile wallet penetration among retail consumers leads transaction volume growth across the region, while QR code technology captures dominant share in street-level merchant acceptance across Southeast Asia's informal economy. Bank transfer infrastructure maintains primacy in large-value B2B settlements, though online payment gateways are displacing legacy wire formats for mid-market cross-border procurement.
India's Reserve Bank oversees the UPI protocol that mandates zero merchant discount rates for transactions below defined thresholds, compressing interchange pools while expanding addressable user bases. China's SAMR enforces antitrust scrutiny against payment platform exclusivity arrangements, fragmenting merchant acquisition channels previously monopolized by dominant wallets. Australia's ACCC open banking regime compels incumbent banks to share transaction data with licensed fintech competitors, eroding deposit stickiness. Stakeholders must monitor how India's central bank digital currency pilot and China's e-CNY expansion reshape liability structures and clearing economics for private payment platforms.
Market Dynamics
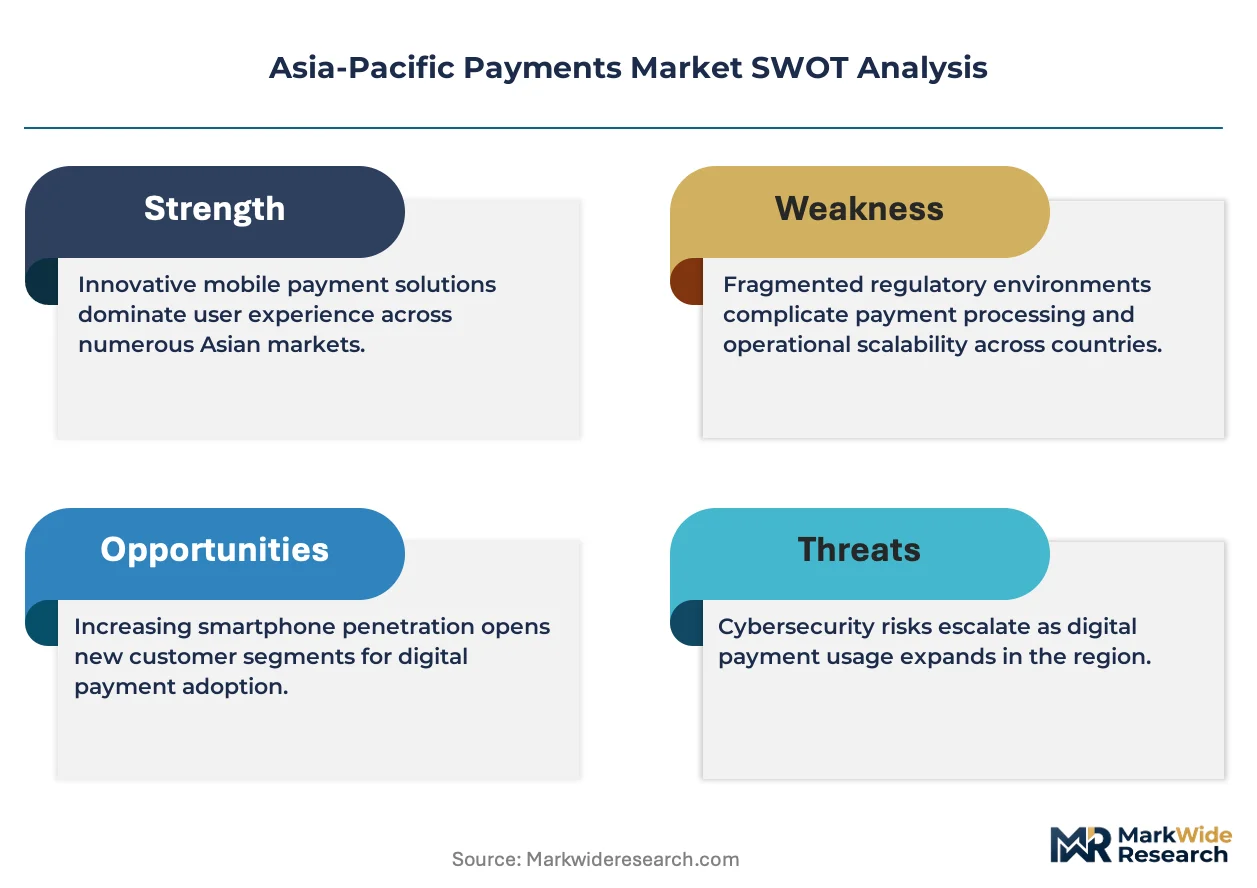
India's zero-merchant-discount-rate mandate under UPI is compressing interchange economics while forcing processors to build volume-dependent revenue models across Southeast Asian corridors. This regulatory price control is reshaping how platforms monetize transaction flows.
Growth Catalysts
- Real-time settlement infrastructure:Thailand's Bank of Thailand and the Philippines' central bank have extended instant payment rails to cross-border corridors, reducing correspondent banking latency from T+2 to near-instantaneous for regional trade settlements.
- QR code standardization:ASEAN's cross-border QR payment linkage is eliminating currency conversion friction for tourists and micro-merchants across Thailand, Singapore, Malaysia, and Indonesia.
- Manufacturing belt digitization:Vietnam's northern industrial provinces are displacing cash-based supplier payments with automated escrow and invoice financing embedded into procurement workflows.
Market Restraints
- Compliance cost escalation:PCI DSS Level 1 certification requirements are concentrating processor viability among capitalized incumbents, raising barriers for mid-market entrants.
- Float income compression:Near-zero interest rate environments across Australia and Japan are eroding the yield on stored-value balances that subsidize wallet operations.
- Data localization mandates:Indonesia's financial data sovereignty rules are fragmenting cloud infrastructure architectures and raising operational complexity for regional platforms.
Strategic Opportunities
- Archipelago logistics corridors:Indonesia's 17,000-island geography creates white space for drone-enabled remittance and merchant settlement networks bypassing terrestrial infrastructure gaps.
- Open banking data monetization:Australia's ACCC regime is enabling licensed fintechs to build predictive cash-flow products for SMEs using incumbent transaction histories.
- Tokenized trade finance:Singapore's regulatory sandbox for programmable money is converging blockchain settlement with letter-of-credit automation for commodity traders.
Industry Challenges
- Cross-border reconciliation complexity:Fragmented FX hedging standards across ASEAN central banks are forcing treasury teams to maintain multiple nostro relationships.
- Legacy core banking integration:Indonesian rural banks still operate on COBOL-based systems, creating API middleware bottlenecks for real-time wallet connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Payments Market |
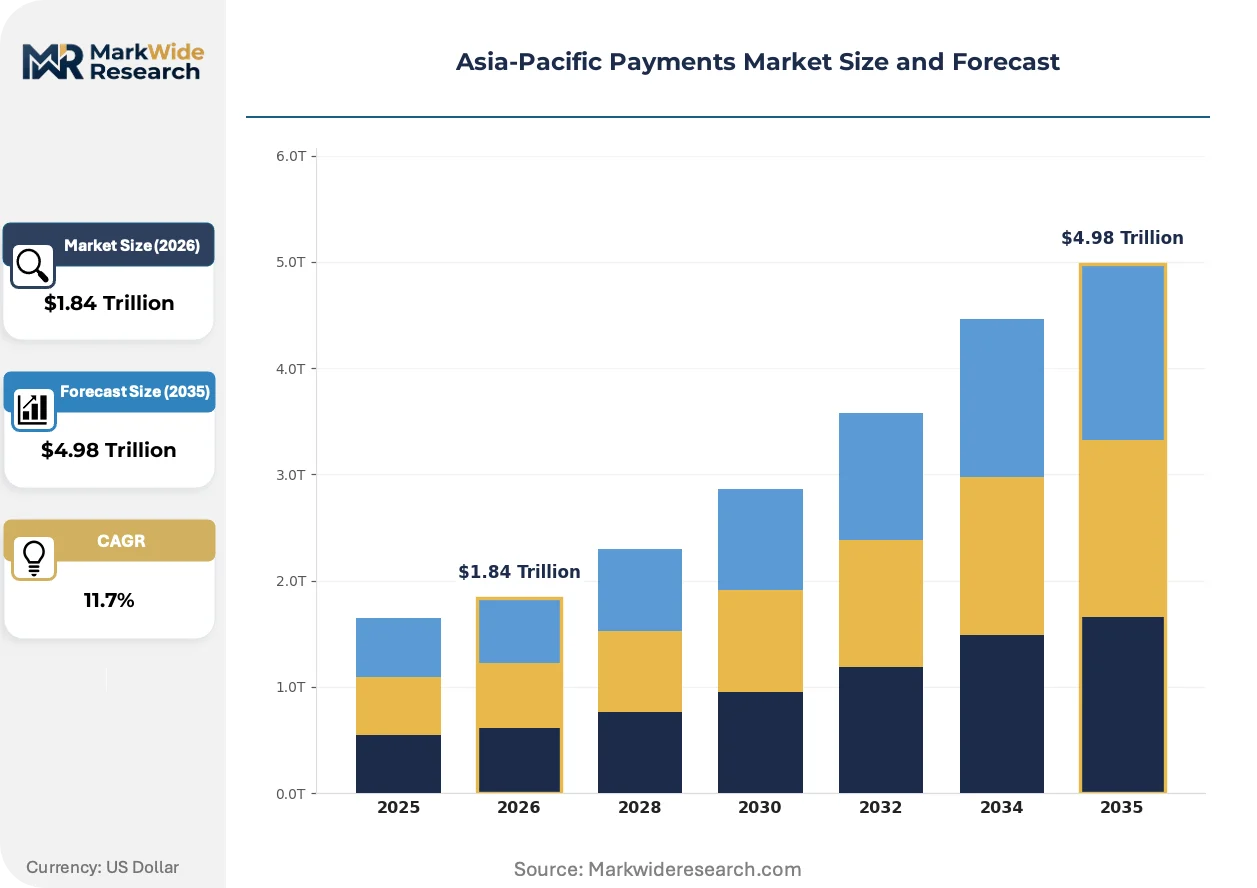
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $4.98 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Technology: Contactless, NFC, QR Code, Online Payment Gateway User Type: Retail Consumers, Businesses, E-commerce Platforms, Financial Institutions Transaction Size: Small Value, Medium Value, Large Value, Microtransactions |
| Companies Covered | Mastercard Incorporated, Naver Pay, Alipay, Airwallex, GCash, WeChat Pay, American Express Company, Nium, Visa Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Payments Market Strategic Shifts
Embedded finance architectures are dissolving the boundary between payment acceptance and software workflows, with platforms competing on developer experience rather than interchange rates alone.
Biometric authentication is fragmenting the traditional card-present versus card-not-present dichotomy. Facial recognition terminals are capturing share in China's retail environments, while voice-print verification gains traction in India's rural banking correspondent networks. This convergence of identity and payment credentials is compressing fraud liability pools while raising data governance stakes.
Singapore's Monetary Authority has mandated climate risk disclosure for financial institutions, compelling payment processors to quantify and report the carbon footprint of data center operations and settlement infrastructure. This regulatory pressure is accelerating migration to renewable-powered server farms and liquid cooling technologies across the city-state's fintech corridor.
Merchant acquisition is rotating from hardware-dependent terminal deployment toward software-only onboarding. Vietnam's street-level vendors are adopting smartphone-based acceptance without dedicated POS devices, while Australia's hospitality sector is unbundling payment acceptance from property management systems. This channel compression is visible most acutely in Indonesia's warung economy, where super-app mini-programs now dominate customer checkout flows.
Asia-Pacific Payments Market Segmentation
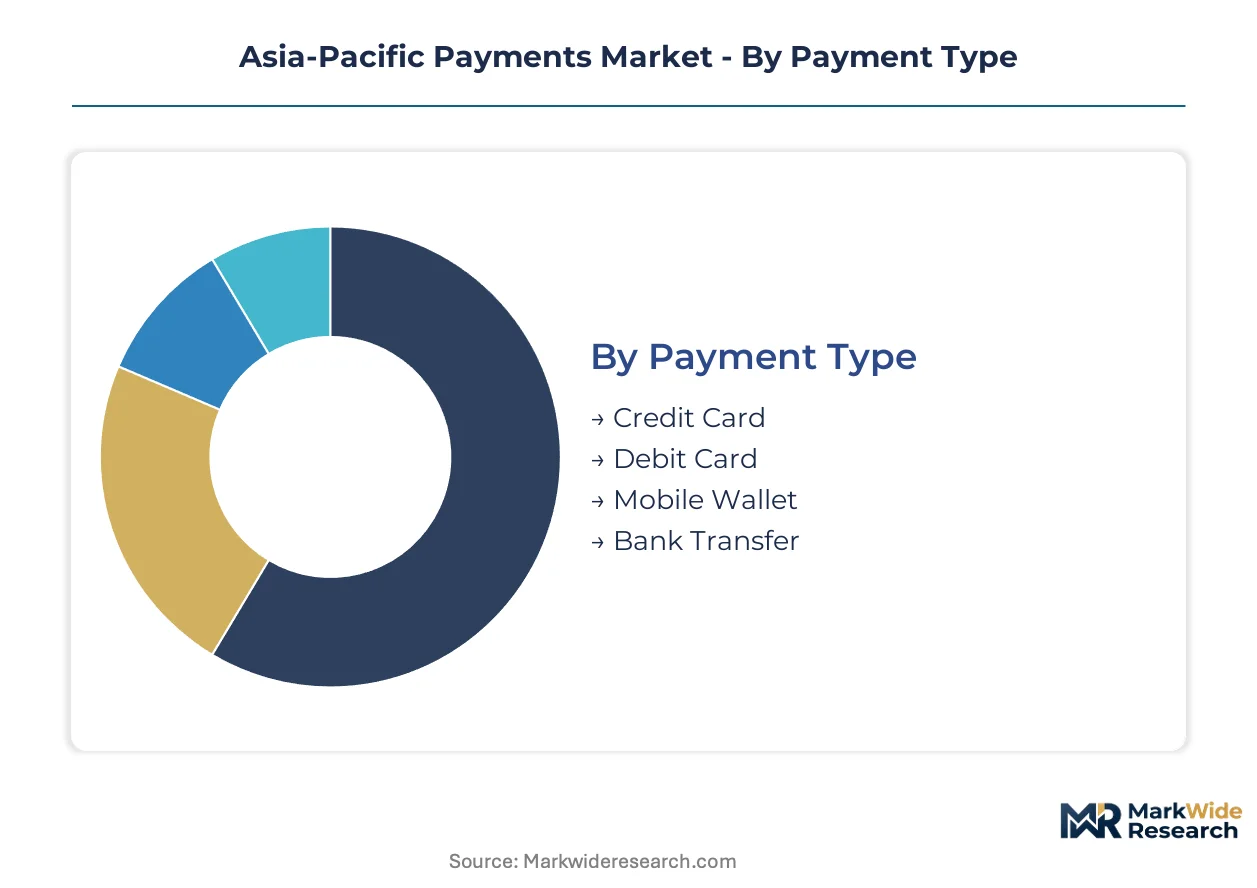
Segmentation in Asia-Pacific payments reveals how infrastructure maturity and regulatory architecture fragment revenue pools across instrument types and settlement rails. Understanding these divisions exposes where zero-merchant-discount-rate mandates compress margins versus where cross-border corridors sustain interchange economics.
Payment Type:
Domestic corridors in India and Indonesia favor mobile wallets and account-based transfers, while export-led manufacturing settlements across Vietnam and Thailand still anchor on card rails and bank transfers for B2B liquidity.
- Credit Card:Revolving credit instruments with tiered interchange schedules set by network operators. Demand concentrates in Australia's hospitality sector and Thailand's tourism corridors, where foreign card acceptance generates premium merchant discount rates that subsidize reward programs.
- Debit Card:Direct account-linked instruments with regulated interchange caps. Indonesia's archipelago logistics networks and the Philippines' remittance corridors drive volume as rural banks displace cash-on-delivery for supplier payments.
- Mobile Wallet:Stored-value accounts accessible via smartphone applications. Singapore's transit integration and Vietnam's street-level merchant economy anchor adoption.
- Bank Transfer:Direct account-to-account settlement through clearing house infrastructure. India's UPI protocol and Australia's NPP rails dominate real-time use cases.
Bank transfer commands the established base. The steepest expansion runs through mobile wallet.
Technology:
Cost tier differentiation separates premium contactless deployments in developed economies from low-cost QR acceptance across emerging Southeast Asian corridors.
- Contactless:Near-field communication-enabled tap-to-pay functionality embedded in cards and devices. Australia's retail infrastructure and Japan's transit networks sustain demand as legacy terminal upgrades reach saturation.
- NFC:Short-range wireless protocol enabling device-to-terminal communication. South Korea's smartphone ecosystem and Singapore's unified POS standards anchor merchant deployment.
- QR Code:Two-dimensional barcode scanning for payment initiation without dedicated hardware. Indonesia's warung economy and Vietnam's informal sector displace cash through smartphone-only acceptance.
- Online Payment Gateway:API-integrated checkout infrastructure for e-commerce merchants. Thailand's cross-border marketplace sellers and India's direct-to-consumer brands drive middleware demand.
QR code captures volume leadership in emerging corridors. Online payment gateway climbs fastest as B2B procurement digitizes.
User Type:
Application logic distinguishes consumer-facing convenience from enterprise treasury workflows, with platform economics fragmenting further by transaction velocity and data monetization potential.
- Retail Consumers:Individual transactors using payments for daily commerce. India's UPI user base and Indonesia's super-app ecosystems concentrate demand.
- Businesses:Corporate entities managing supplier payments and employee disbursements. Vietnam's manufacturing belt and Australia's professional services sector anchor B2B adoption.
- E-commerce Platforms:Marketplace operators integrating checkout and escrow functionality. Southeast Asia's regional marketplace networks drive embedded finance demand.
- Financial Institutions:Banks and non-bank payment service providers building proprietary rails. Singapore's banking consortiums and Hong Kong's virtual banks compete on developer experience.
Retail consumers anchor transaction volume. Financial institutions represent the fastest-growing trajectory as open banking mandates expand addressable data pools.
Transaction Size:
Customer type and settlement urgency stratify across value bands, with microtransaction infrastructure enabling new monetization models in gaming and content while large-value rails retain correspondent banking primacy.
- Small Value:Transactions below threshold limits for instant settlement without friction. India's UPI zero-MDR band and Indonesia's BI-FAST retail corridor concentrate volume.
- Medium Value:B2B supplier payments and professional service fees requiring invoice reconciliation. Thailand's manufacturing supply chains and Australia's SME ecosystem drive gateway adoption.
- Large Value:Corporate treasury movements and cross-border trade settlements. Singapore's commodity traders and Hong Kong's FX corridors anchor demand for real-time gross settlement.
- Microtransactions:Sub-dollar payments for digital content and in-app purchases. South Korea's gaming platforms and Japan's content ecosystems pioneer wallet-based micropayment rails.
Small value commands daily transaction frequency. Microtransactions gain share fastest as super-app ecosystems embed frictionless tipping and content unlocking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's zero-merchant-discount-rate mandate under UPI is compressing interchange economics while forcing processors to build volume-dependent revenue models across Southeast Asian corridors. This regulatory price control is reshaping how platforms monetize transaction flows.
China
Ant Group's Alipay and Tencent's WeChat Pay dominate merchant acquisition through super-app ecosystems integrating commerce, messaging, and financial services. SAMR enforces antitrust scrutiny against payment platform exclusivity arrangements, fragmenting merchant channels previously monopolized by dominant wallets. The Yangtze River Delta manufacturing clusters and Pearl River Delta export corridors anchor B2B payment digitization for cross-border trade settlements.
India
UPI protocol processes billions of monthly transactions with zero merchant discount rates below threshold limits, expanding financial inclusion while compressing processor margins. RBI oversees central bank digital currency pilots reshaping liability structures for private payment platforms. Mumbai's financial district and Bangalore's technology corridor concentrate fintech development and wallet infrastructure deployment.
Singapore
Monetary Authority of Singapore mandates climate risk disclosure for financial institutions, compelling payment processors to quantify carbon footprints of data center operations. The regulatory sandbox for programmable money converges blockchain settlement with letter-of-credit automation for commodity traders. Marina Bay fintech corridor hosts regional headquarters for cross-border payment infrastructure providers.
Indonesia
BI-FAST real-time retail payment system displaces cash-on-delivery across 17,000-island archipelago logistics networks. Financial data sovereignty rules fragment cloud infrastructure architectures, raising operational complexity for regional platforms. Jakarta's urban corridor and Surabaya's manufacturing belt drive mobile wallet adoption among street-level warung merchants.
Australia
ACCC open banking regime compels incumbent banks to share transaction data with licensed fintech competitors, eroding deposit stickiness. Near-zero interest rate environments compress float income on stored-value balances that subsidize wallet operations. Sydney's financial district and Melbourne's SME ecosystem anchor B2B gateway adoption for professional services procurement.
Asia-Pacific Payments Market Competitive Environment
Listed leaders compete with private specialists across infrastructure depth and geographic coverage. Visa Inc. and Mastercard Incorporated anchor the publicly traded tier through network scale and central bank partnerships, while private fintechs compete on developer experience and embedded finance architectures. Three archetypes dominate: card network incumbents with established interchange economics, super-app wallets leveraging merchant density, and cross-border specialists building multi-currency treasury capabilities. Consolidation pressure concentrates among PCI DSS Level 1 certified processors, while strategic partnerships with central banks extend real-time settlement rails.
Within the super-app wallet tier, Alipay and WeChat Pay exemplify merchant network density strategies across mainland China. Among ASEAN-focused specialists, Airwallex occupies a position on multi-currency treasury capabilities for mid-market enterprises, while GCash represents the mobile-first archetype penetrating the Philippines' remittance corridors. At the infrastructure end, Visa Inc. anchors real-time settlement partnerships with Thailand's Bank of Thailand and the Philippines' central bank.
| Leading Market Players |
|---|
| Mastercard Incorporated |
| Naver Pay |
| Alipay |
| Airwallex |
| GCash |
| WeChat Pay |
| American Express Company |
| Nium |
| Visa Inc. |
| Others |
Value Chain & Pricing Dynamics
Scale economies in PCI DSS Level 1 certification infrastructure compress cost structures for incumbent processors while erecting capital barriers that protect price floors across Southeast Asian corridors. This concentration dynamic concentrates pricing power among network-scale operators and fragments margin recovery pathways for mid-market entrants.
Pricing Analysis
Certification level creates the primary spread between premium interchange rates and compressed zero-merchant-discount-rate tiers. Pricing stratifies across PCI DSS Level 1 certified infrastructure, volume-scaled transaction corridors, and unlicensed wallet operators facing regulatory exclusion. Cost compression in India's UPI corridor is intensifying because RBI mandates eliminate merchant discount rates below threshold limits, forcing processors toward data monetization and float-dependent models. Small-value street merchants across Indonesia's warung economy exhibit highest price sensitivity, while Singapore's commodity traders demonstrate lowest sensitivity due to embedded treasury value.
Supply Chain Analysis
Singapore and Hong Kong anchor cloud infrastructure and data center capacity for regional payment processing, while India and Indonesia concentrate API middleware and wallet application development. Hardware dependencies draw from Taiwan's semiconductor fabrication for secure element chips and China's POS terminal manufacturing. Single-source vulnerability sits with SWIFT correspondent banking rails for large-value settlements. Distribution runs through bank-led merchant acquisition networks in developed corridors and super-app mini-program ecosystems in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through central bank partnerships creates switching costs that lock in infrastructure providers across multi-year settlement rail contracts.
For Market Incumbents: Compound network density through deeper central bank partnerships extending real-time settlement rails into secondary ASEAN corridors. Defend against super-app wallet disintermediation by embedding treasury capabilities directly into enterprise ERP workflows. Prioritize certification maintenance as PCI DSS Level 1 compliance concentrates competitive viability. For New Entrants and Emerging Players: Lead with drone-enabled remittance infrastructure targeting Indonesia's 17,000-island logistics gaps where terrestrial network coverage fails. Penetrate Vietnam's manufacturing belt through automated escrow and invoice financing embedded into procurement workflows. Build developer-first API architectures that unbundle payment acceptance from legacy core banking integration bottlenecks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure providers with central bank partnerships over consumer-facing wallets facing interchange compression. Long-term viability rests on regulatory entrenchment and data network effects rather than transaction volume scale alone. Target acquisition archetypes include PCI DSS Level 1 certified processors with ASEAN corridor coverage. Watch India's central bank digital currency pilot expansion as inflection signal for private platform liability restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Central Bank Partnership Extension | Thailand's Bank of Thailand and Philippines central bank real-time rail partnerships lock in settlement infrastructure dominance. |
| Super-App Ecosystem Integration | Alipay and WeChat Pay merchant network density anchors customer retention through commerce-messaging-finance convergence. |
| Drone-Enabled Remittance Infrastructure | Indonesia's archipelago geography creates white space bypassing terrestrial gaps in last-mile settlement networks. |
| Open Banking Data Monetization | Australia's ACCC regime enables licensed fintechs to build predictive cash-flow products using incumbent transaction histories. |
| Climate Risk Disclosure Compliance | Singapore's MSA mandate accelerates migration to renewable-powered data centers across the city-state's fintech corridor. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment network executives, central bank regulatory leads, merchant acquisition heads, and fintech platform engineers. Secondary validation drew from RBI circulars, MAS regulatory sandbox disclosures, BI-FAST implementation reports, and ASEAN cross-border QR payment linkage documentation. Bottom-up transaction volume modeling triangulated against top-down GDP-attributed payment flow estimates.
Across the analysis window, projections integrated payment type segmentation by instrument, technology tier by acceptance infrastructure, user archetype by transaction velocity, and transaction size band by settlement urgency. CAGRs derived from historical adoption curve fitting adjusted for regulatory intervention points. Forecast inputs incorporated UPI volume trajectories, e-CNY expansion pacing, and open banking mandate implementation schedules.
Forecasts assume regulatory continuity in India's UPI zero-MDR regime, Singapore's climate disclosure mandates, and Indonesia's data sovereignty rules; material policy shifts would require re-modeling. Specific risks include central bank digital currency liability displacement, antitrust fragmentation of super-app exclusivity, and interest rate normalization affecting float income economics. Recalibration cycles align with material shifts in named regulatory drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Norway Mobile Payments Market
Payments
Canada Mobile Payments Market
Payments
POS Terminals Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Europe Payments Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Convergent Billing Market
Payments
North America Mobile Payments Market
Payments
Japan Virtual Cards Market
Payments
Dual Interface Payment Card Market
Payments
Netherlands Mobile Payments Market
Payments
Latin America Payment Gateway Market
Payments
United States Payment Gateways Market
Payments
Japan Credit Cards Market
Payments
Mobile Card Reader Market
Payments
Canada Real Time Payments Market