
 Third Party Payment Market | 2026-2036
Third Party Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Third Party Payment Market Analytics
Payment engineering talent scarcity is unwinding infrastructure buildouts across emerging markets. Stripe Inc. leverages developer-centric APIs to occupy high-growth SaaS verticals. Adyen NV anchors enterprise merchant relationships through unified platform architecture. Alipay.com Co. Ltd dominates domestic transaction density with super-app integration.
Third party payment denotes an intermediary financial service that processes transactions between buyers and sellers without direct fund transfer between parties, typically operating through encrypted tokenization protocols and real-time authorization networks to reduce counterparty risk. The primary commercial purpose centers on decoupling payment acceptance from banking infrastructure, enabling merchants to aggregate multiple tender types within unified settlement cycles. Digital wallet penetration is accelerating fastest among consumer-facing segments, while payment processing services capture the deepest margin pools through volume-based interchange economics. Corporate customer types are expanding as B2B platforms adopt automated reconciliation workflows.
PCI DSS compliance requirements, PSD2 open banking mandates from European Banking Authority, and SAMR fintech licensing rules in China collectively elevate operational barriers for non-compliant entrants. These frameworks shape demand by forcing infrastructure investments in tokenization security and real-time fraud detection capabilities. Stakeholders must monitor regulatory divergence between privacy-centric European standards and data-integrated Asian models when allocating platform development resources.
Market Dynamics
Super-app ecosystems are consolidating transaction density into single-platform environments, forcing standalone payment processors to embed deeper into merchant software stacks or cede consumer-facing volume to integrated providers.
Growth Catalysts
- PSD2 open banking mandates:European Banking Authority regulations force banks to expose account data via standardized APIs, enabling third-party payment providers to initiate direct account-to-account transfers that bypass card networks entirely.
- Embedded checkout adoption:E-commerce platforms are integrating native payment processing into their storefront infrastructure, eliminating redirects and reducing cart abandonment through seamless tokenization workflows.
- China's super-app density:Domestic consumers execute the majority of daily transactions within WeChat and Alipay ecosystems, creating template demand for similar consolidated payment experiences across Southeast Asian markets.
Market Restraints
- PCI DSS compliance costs:Level 1 merchant certification requires annual third-party audits, penetration testing, and network segmentation investments that consume operating budgets of emerging market entrants.
- Core banking system concentration:Legacy mainframe architectures at major financial institutions create integration bottlenecks, delaying real-time settlement capabilities for payment aggregators dependent on batch-file reconciliation.
- Account-to-account substitution:Faster payment rails and FedNow instant settlement infrastructure in the United States enable direct bank transfers that compress interchange fee pools supporting processor margins.
Strategic Opportunities
- B2B automated reconciliation:Corporate treasury departments are adopting API-driven payment workflows that match invoice data to settlement records, opening enterprise segments historically served by manual wire transfers.
- India's UPI expansion:National Payments Corporation of India's real-time payment infrastructure enables zero-MDR transactions at massive scale, creating template architectures for other developing economies to emulate.
- Biometric authentication convergence:Facial recognition and behavioral biometrics are merging with tokenized credentials to eliminate password friction in high-risk transaction scenarios.
Industry Challenges
- Payment engineering scarcity:Specialized talent in distributed systems architecture and cryptographic protocol design commands premium compensation, constraining platform buildout timelines for regional challengers.
- Multi-jurisdiction licensing complexity:SAMR fintech licensing in China, state-level money transmitter registrations in the United States, and EMI authorizations across EU member states create compliance timelines that extend market entry by quarters.
- Legacy ERP integration friction:Corporate finance systems from SAP and Oracle require custom middleware development to ingest real-time payment data, delaying enterprise customer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third Party Payment Market |
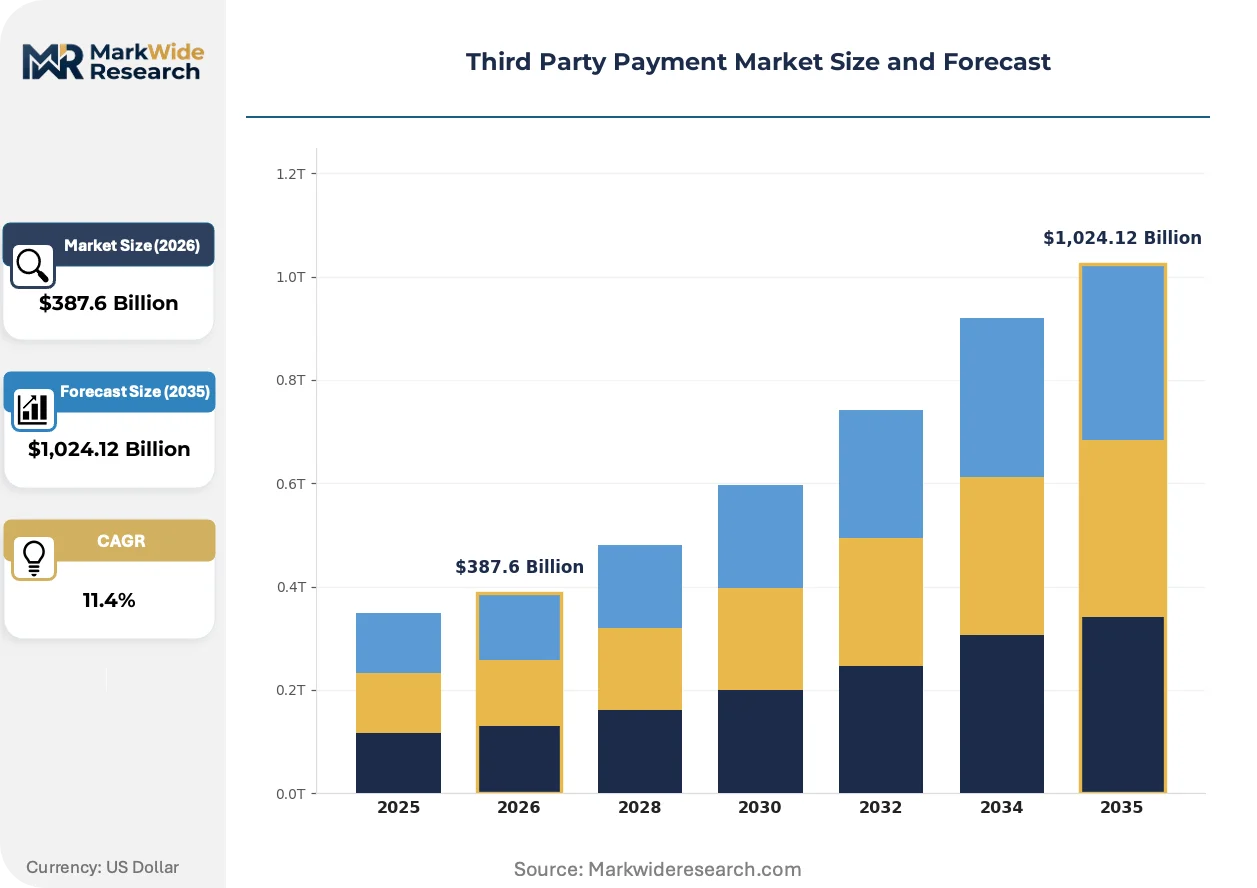
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Digital Wallet, Bank Transfer Customer Type: Consumer, Merchant, Corporate, Government Service Type: Payment Processing, Fraud Detection, Settlement, Reconciliation Technology: Blockchain, NFC, QR Code, Mobile Payments |
| Companies Covered | PayPal Holdings Inc., Stripe Inc., Alipay.com Co. Ltd, Adyen NV, Amazon Payments Inc., Fiserv Inc., Ant Group Co. Ltd., Tencent Holdings Ltd., Block Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third Party Payment Market Evolving Landscape
Tokenization infrastructure is migrating from card-present environments to cloud-native vault architectures, compressing the attack surface for credential theft while enabling cross-channel payment continuity.
Software development kits are supplanting hosted checkout pages as the dominant merchant integration pattern. Mid-market SaaS vendors embed these tools directly into subscription billing workflows, eliminating consumer exposure to external domains. This architecture is supplanting traditional redirect-based authentication flows that fragmented purchase journeys across multiple interfaces.
GDPR data localization requirements intersect with SAMR cross-border data transfer restrictions to create divergent compliance architectures. European processors must maintain isolated infrastructure for biometric template storage, while Chinese operators face mandatory domestic server placement for transaction logs. Payment platforms serving both jurisdictions are responding by deploying region-segregated token vaults with no inter-zone replication.
Merchant acquisition is rotating from independent sales organizations toward direct API-driven self-service onboarding. Developer documentation quality and sandbox environment fidelity now determine platform selection more than relationship management for digital-native businesses. This pattern is most visible in Germany and the Netherlands, where technical procurement committees dominate vendor evaluation for mid-sized e-commerce operators.
Third Party Payment Market Segmentation
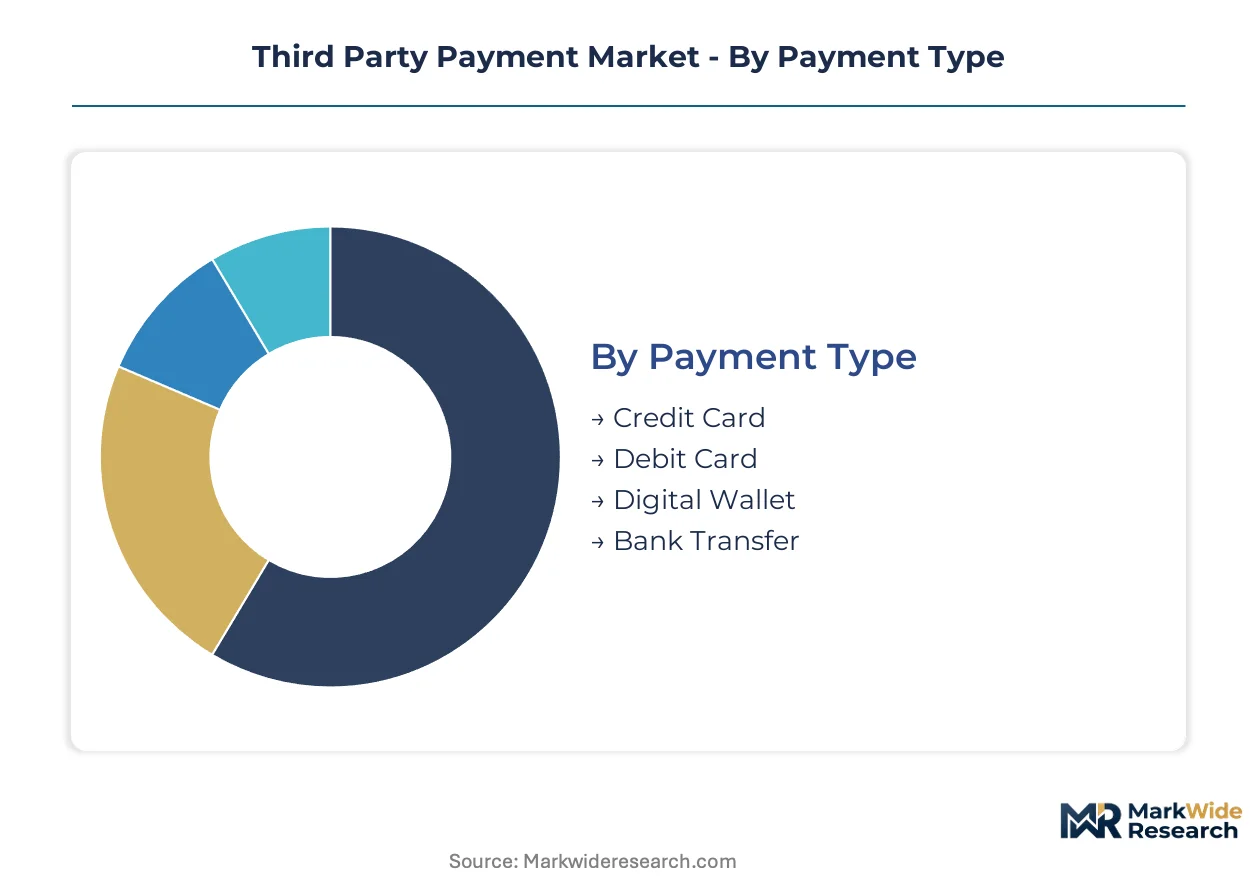
Third party payment infrastructure fragments across four structural dimensions that determine channel economics and platform architecture. Payment type and customer type together dictate settlement velocity and fraud risk profiles. Service type and technology orientation shape margin capture and capital intensity requirements.
Payment Type:
Credit card rails still carry the highest transaction values through merchant acquirers, while digital wallets are capturing frequency-driven consumer touchpoints. Bank transfer volumes are accelerating where open banking APIs enable account-to-account initiation.
- Credit Card:Tokenized credential networks dominate high-value retail and travel bookings. Interchange economics sustain processor margins in North American and European markets where card penetration remains deepest.
- Digital Wallet:Super-app embedded credentials consolidate daily transaction frequency into single-platform environments. China and Southeast Asian markets concentrate demand where Alipay and WeChat Pay templates have normalized QR-code checkout behaviors.
- Debit Card:PIN and signature debit rails capture budget-conscious consumer segments with lower chargeback exposure. Real-time authorization networks from Visa and Mastercard enable sub-second approval workflows.
- Bank Transfer:Account-to-account initiation bypasses card networks entirely where PSD2 or UPI infrastructure enables direct API-driven debits. European and Indian regulatory frameworks are accelerating adoption among cost-sensitive merchants.
By volume, Credit Card leads. By growth pace, Digital Wallet is ahead.
Customer Type:
Merchant acquisition costs vary dramatically across these segments, with corporate and government clients demanding customized reconciliation workflows that extend sales cycles.
- Merchant:Small and mid-sized sellers drive platform scale through aggregated processing volumes. E-commerce operators prioritize embedded checkout solutions that reduce cart abandonment.
- Consumer:Individual payers select platforms based on credential portability and reward program integration. Mobile-first onboarding experiences determine retention in competitive markets.
- Corporate:Treasury departments require API-driven payment workflows that match invoice data to settlement records. SAP and Oracle ERP integrations create implementation friction that extends contract timelines.
- Government:Public sector procurement mandates compliance with specific audit trails and domestic data residency requirements. SAMR licensing in China and GDPR frameworks in Europe impose divergent infrastructure obligations.
Merchant segments generate the deepest transaction density. Corporate adoption is climbing the fastest as B2B platforms automate legacy wire transfer workflows.
Service Type:
Payment processing captures the core revenue pool, while adjacent services determine customer stickiness and switching costs.
- Payment Processing:Authorization, clearing, and settlement orchestration form the foundational revenue layer. Volume-based interchange economics reward platforms that aggregate merchant density.
- Fraud Detection:Machine learning models analyze behavioral biometrics and transaction velocity patterns to flag anomalous activity. Real-time scoring capabilities differentiate premium service tiers.
- Settlement:Funds aggregation and disbursement scheduling determine merchant cash flow predictability. Faster payment rails and FedNow infrastructure are compressing settlement windows in the United States.
- Reconciliation:Automated matching of payment records to invoice data reduces manual accounting overhead. Corporate treasury departments prioritize this capability when evaluating platform migrations.
Processing commands the largest revenue share. Fraud detection is gaining share fastest as chargeback liability shifts toward merchants.
Technology:
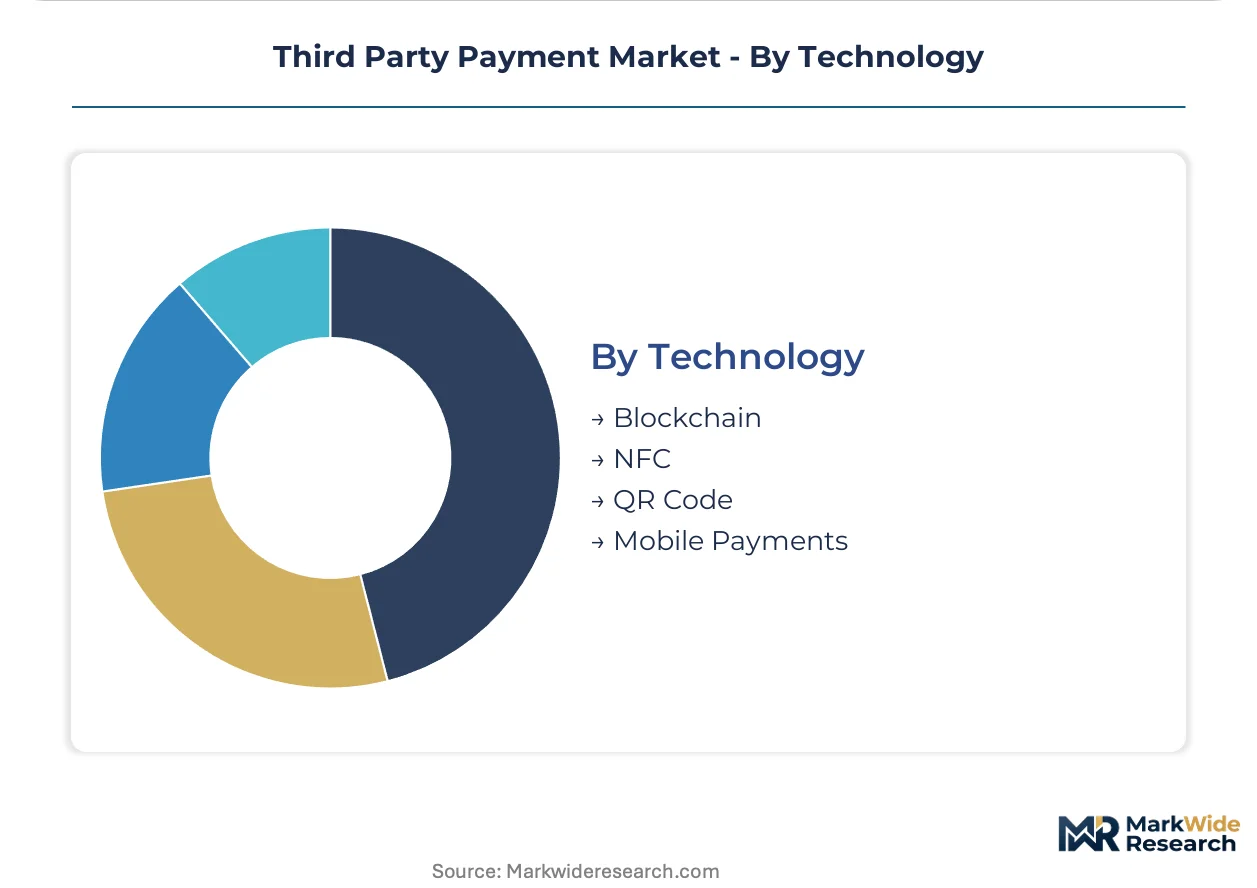
Technology selection determines hardware requirements, integration complexity, and geographic addressability for platform operators.
- Mobile Payments:SDK-embedded checkout experiences eliminate redirects and reduce cart abandonment. SaaS vendors prioritize this architecture for subscription billing workflows.
- QR Code:Low-cost merchant acceptance infrastructure dominates emerging market penetration strategies. India's UPI ecosystem demonstrates massive-scale deployment feasibility.
- NFC:Contactless credential transmission enables tap-to-pay experiences at physical point-of-sale terminals. Transit and quick-service restaurant verticals drive terminal deployment economics.
- Blockchain:Distributed ledger settlement experiments target cross-border remittance and stablecoin corridors. Regulatory uncertainty constrains mainstream merchant adoption.
Mobile Payments leads by deployment velocity. QR Code infrastructure is scaling most rapidly in developing economies with limited legacy terminal penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR licensing requirements in China establish the dominant regulatory anchor for third party payment infrastructure development worldwide, with super-app transaction density creating template demand patterns that adjacent markets emulate through localized adaptations.
China
WeChat Pay and Alipay process the majority of domestic consumer transactions through embedded super-app environments. SAMR fintech licensing mandates domestic server placement for transaction logs and cross-border data transfer restrictions. The Yangtze River Delta cluster around Shanghai anchors merchant acquisition density, with Hangzhou hosting Ant Group's headquarters operations.
United States
FedNow instant settlement infrastructure and faster payment rails enable direct bank transfers that compress traditional interchange economics. State-level money transmitter registrations create fragmented licensing requirements across fifty jurisdictions. The San Francisco Bay Area concentrates developer-centric payment platforms, while New York anchors enterprise merchant relationships and treasury banking integration.
Germany
PSD2 open banking mandates from the European Banking Authority force account data exposure via standardized APIs, enabling account-to-account initiation. GDPR data localization requirements isolate biometric template storage within European infrastructure. Berlin hosts embedded finance startups targeting mid-market SaaS verticals, with Frankfurt anchoring traditional banking processor relationships.
India
UPI real-time payment infrastructure from the National Payments Corporation of India enables zero-MDR transactions at massive scale, creating template architectures for developing economies. RBI oversight governs payment aggregator licensing and wallet balance caps. Mumbai anchors corporate treasury automation demand, while Bangalore concentrates engineering talent for mobile SDK development.
United Kingdom
Open banking adoption through the Competition and Markets Authority regime accelerates account-to-account payment initiation for cost-sensitive merchants. FCA authorization requirements impose capital adequacy and operational resilience standards on payment institutions. London's fintech corridor concentrates API-first payment processors targeting European cross-border commerce, with Manchester emerging as a secondary hub for B2B reconciliation platforms.
Third Party Payment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform consolidation favoring unified architecture providers over point-solution vendors. The upper tier captures enterprise merchant density through multi-product bundling, while specialists occupy vertical niches requiring customized reconciliation workflows. Two strategic archetypes dominate: developer-centric API platforms targeting SaaS verticals, and super-app integrated providers capturing consumer transaction frequency. Competitive moves center on embedded checkout partnerships with e-commerce platforms and geographic licensing expansion to capture cross-border settlement flows.
Within the integrated platform tier, Stripe Inc. and Adyen NV exemplify contrasting geographic and vertical positioning strategies, with the former anchoring developer-centric merchant acquisition and the latter anchoring enterprise unified commerce relationships. Alipay.com Co. Ltd occupies a distinct super-app integrated archetype that domestic Chinese competitors and Southeast Asian emulators reference as a structural template.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Stripe Inc. |
| Alipay.com Co. Ltd |
| Adyen NV |
| Amazon Payments Inc. |
| Fiserv Inc. |
| Ant Group Co. Ltd. |
| Tencent Holdings Ltd. |
| Block Inc. |
| Others |
Value Network & Pricing Analysis
Scale economies in token vault infrastructure compress marginal processing costs for incumbents while erecting capital barriers that protect price floors for PCI DSS Level 1 certification tiers. This dynamic concentrates supply-side leverage among platforms operating multi-jurisdiction tokenization networks, forcing regional challengers into higher-cost per-transaction pricing or niche vertical specialization.
Pricing Analysis
Geographic price spreads widen substantially between European PSD2-mandated markets and China's zero-MDR UPI environment, with interchange economics sustaining premium processor margins in North American card-dominant corridors. Three-tier pricing structure across enterprise, mid-market, and developer-tier levels separates volume-based interchange rebates from flat-rate SaaS subscription models. Cost compression in emerging market processing tiers is intensifying because India's UPI infrastructure demonstrates zero-MDR scalability that merchant acquirers elsewhere must match to retain price-sensitive digital wallet volume. Corporate treasury departments exhibit lowest price sensitivity due to reconciliation automation value, while micro-merchants drive fiercest rate negotiation.
Supply Chain Analysis
China and the United States anchor tokenization security module production and cloud-native vault architecture development respectively. Hardware security module fabrication draws from Taiwanese semiconductor foundries and South Korean memory component suppliers. Single-source vulnerability concentrates in cryptographic protocol design talent pools concentrated in San Francisco Bay Area and Bangalore clusters. Distribution runs through direct API-driven self-service onboarding platforms supplanting independent sales organization networks, with developer documentation quality now determining merchant acquisition velocity more than relationship management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized payment engineering talent scarcity constrains platform buildout timelines and elevates acquisition premiums for teams with distributed systems architecture expertise. This capability gap shapes competitive positioning across all stakeholder archetypes.
For Market Incumbents: Compound platform density through embedded checkout partnerships with mid-market SaaS vendors, defending against super-app disintermediation by deepening token vault integration into merchant software stacks. Prioritize vertical integration into real-time fraud detection model training to capture shifting chargeback liability burdens. For New Entrants and Emerging Players: Differentiate on B2B automated reconciliation workflows targeting corporate treasury departments underserved by legacy wire transfer infrastructure. Penetrate India's UPI ecosystem through zero-MDR merchant acquisition, leveraging National Payments Corporation of India infrastructure templates for Southeast Asian market entry via API-first developer relations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with region-segregated token vault architectures capable of serving both GDPR-isolated European infrastructure and SAMR-mandated Chinese domestic server placement. Long-term viability hinges on biometric authentication convergence capabilities and FedNow instant settlement integration. Watch faster payment rail adoption velocity as inflection indicator for interchange compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Checkout Partnership | Stripe and Adyen anchor SaaS vertical dominance through native tokenization workflows. |
| Biometric Authentication Convergence | Facial recognition integration with tokenized credentials eliminates password friction in high-risk transactions. |
| Region-Segregated Token Vault Deployment | GDPR and SAMR divergent data residency mandates force isolated infrastructure with no inter-zone replication. |
| B2B Reconciliation Platform Development | API-driven invoice-to-settlement matching opens enterprise segments historically served by manual wire transfers. |
| UPI Architecture Licensing | India's zero-MDR real-time payment template enables developing economy market entry without interchange economics. |
Research Methodology
A spread of perspectives from payment engineering directors, merchant acquisition leads at SaaS platforms, corporate treasury automation officers, and regulatory compliance specialists at EMI-authorized institutions converged on the working assumptions underlying transaction volume and pricing trajectory estimates. Primary interview insights combined with secondary validation from European Banking Authority PSD2 implementation reports, SAMR fintech licensing disclosures, National Payments Corporation of India UPI volume publications, and SEC 10-K filings from listed payment processors. Bottom-up merchant density modeling and top-down addressable payment flow estimation triangulated on segment-level projections.
Segmentation dimensions modeled span payment type, customer archetype, service tier, and technology orientation across the analysis window. Volume and value outputs reflect reconciliation between authorization network data, settlement flow aggregates, and merchant acquisition cost curves. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure deployment timelines. Industry-specific forecast inputs incorporate open banking API adoption velocity and super-app transaction density normalization patterns.
Material uncertainties — regulatory divergence between privacy-centric European standards and data-integrated Asian models, faster payment rail substitution compressing interchange pools, and payment engineering talent scarcity extending platform buildout timelines — sit outside the modeled envelope. Forecasts reflect assumptions about PSD2 mandate enforcement consistency, SAMR licensing approval velocity, and FedNow merchant adoption curves. Recalibration cycles align with material shifts in open banking API standardization and biometric authentication regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany Mobile Payments Market
Payments
Norway Mobile Payments Market
Payments
Global Payment Monitoring Market
Payments
France POS Terminal Market
Payments
LAMEA Payment Gateway Market
Payments
Smart Home Payments Market
Payments
Wireless POS Terminals Market
Payments
Canada Mobile Payments Market
Payments
Bulgaria POS Terminals Market
Payments
South Korea POS Terminals Market
Payments
Indonesia Prepaid Cards Market
Payments
Saudi Arabia Payments Market
Payments
E-Commerce Payments Market
Payments
Thailand Mobile Payments Market
Payments
Poland Payments Market
Payments
Middle East Gift Card and Incentive Card Market