
 Netherlands POS Terminal Market | 2026-2036
Netherlands POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands POS Terminal Market Foresight
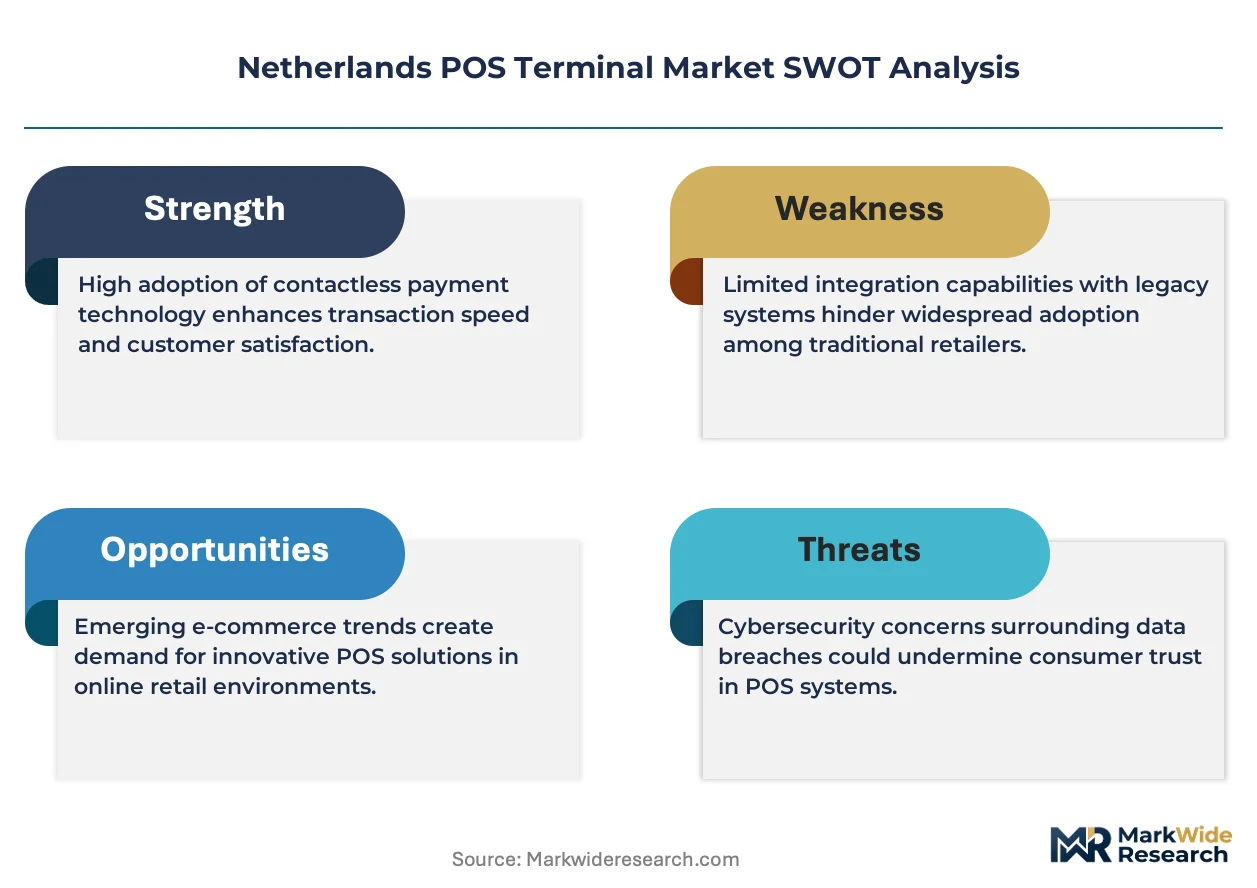
The gap between premium integrated payment platforms and commodity hardware-only terminals is hardening in the Netherlands. Adyen leverages its unified commerce stack to anchor high-margin merchant relationships across Dutch retail. Verifone Payments BV sustains broad channel control through distributor networks serving mid-market hospitality. Newland Europe BV specializes in ruggedized mobile units for logistics-adjacent use cases.
A Netherlands POS Terminal is an electronic device engineered to process card and digital payments through integrated hardware-software systems, typically featuring PCI-DSS compliant encryption, ARM-based processors, and connectivity via Ethernet, Wi-Fi, or cellular modules. Its commercial purpose is to authenticate transactions, route payment data to acquiring banks, and generate audit trails for merchant reconciliation. Mobile POS units are gaining fastest in the Dutch market as tableside and curbside checkout expand across hospitality. Fixed POS retains dominance in high-volume supermarket chains where throughput speed governs lane design. Contactless technology leads transaction volume as Dutch consumers default to tap-to-pay behavior.
The Dutch Data Protection Authority enforces GDPR-mandated data minimization for payment records, compelling terminal vendors to embed privacy-by-design architectures. De Nederlandsche Bank supervises payment system integrity under the EU Payment Services Directive, shaping certification requirements for terminal deployment. Stakeholders must monitor how forthcoming EU AI Act provisions classify fraud-detection algorithms embedded in smart POS terminals.
Market Dynamics
The Dutch POS terminal landscape is undergoing structural compression as GDPR-mandated data minimization forces hardware redesigns and mobile-first hospitality workflows accelerate terminal refresh cycles across Amsterdam and Rotterdam retail corridors.
Growth Catalysts
- GDPR-Aligned Data Architecture:The Dutch Data Protection Authority's enforcement of payment data minimization compels terminal vendors to embed privacy-by-design encryption, creating replacement demand for legacy PCI-DSS systems.
- Tableside Commerce Expansion:Dutch hospitality chains are deploying mobile POS units for curbside and in-venue checkout, driving hardware procurement across Rotterdam's dense restaurant clusters.
- Contactless Tap-to-Pay Normalization:Consumer behavior in Netherlands urban centers now defaults to contactless transactions, forcing terminal upgrades to NFC-enabled form factors.
Market Restraints
- Semiconductor Supply Concentration:ARM-based processor sourcing remains concentrated among Asian foundries, exposing Dutch terminal assemblers to input volatility and extended lead times.
- Certification Friction Under PSD2:De Nederlandsche Bank's supervision of payment system integrity imposes multi-stage compliance timelines that delay product launches by quarters.
- Cloud-Native Substitute Threat:Soft-POS applications running on standard smartphones are displacing dedicated hardware in micro-merchant segments.
Strategic Opportunities
- EU AI Act Compliance Positioning:Fraud-detection algorithms embedded in smart terminals will require algorithmic transparency certification, creating first-mover advantage for vendors with embedded audit capabilities.
- Logistics-Adjacent Ruggedization:Warehouse and last-mile delivery use cases in Eindhoven and Utrecht industrial zones remain underpenetrated by specialized mobile POS hardware.
- Unified Commerce Stack Convergence:Integration of inventory management, loyalty, and payment routing into single-platform architectures opens margin expansion in mid-market Dutch retail.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for PCI-DSS compliant encryption modules faces acute shortage in Netherlands technical labor markets.
- Legacy ERP Integration Complexity:Supermarket chains operating decades-old backend systems require costly middleware development for modern terminal connectivity.
- GDPR Breach Liability Exposure:Terminal vendors assume downstream legal risk for merchant data handling errors, necessitating expanded cyber insurance coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands POS Terminal Market |
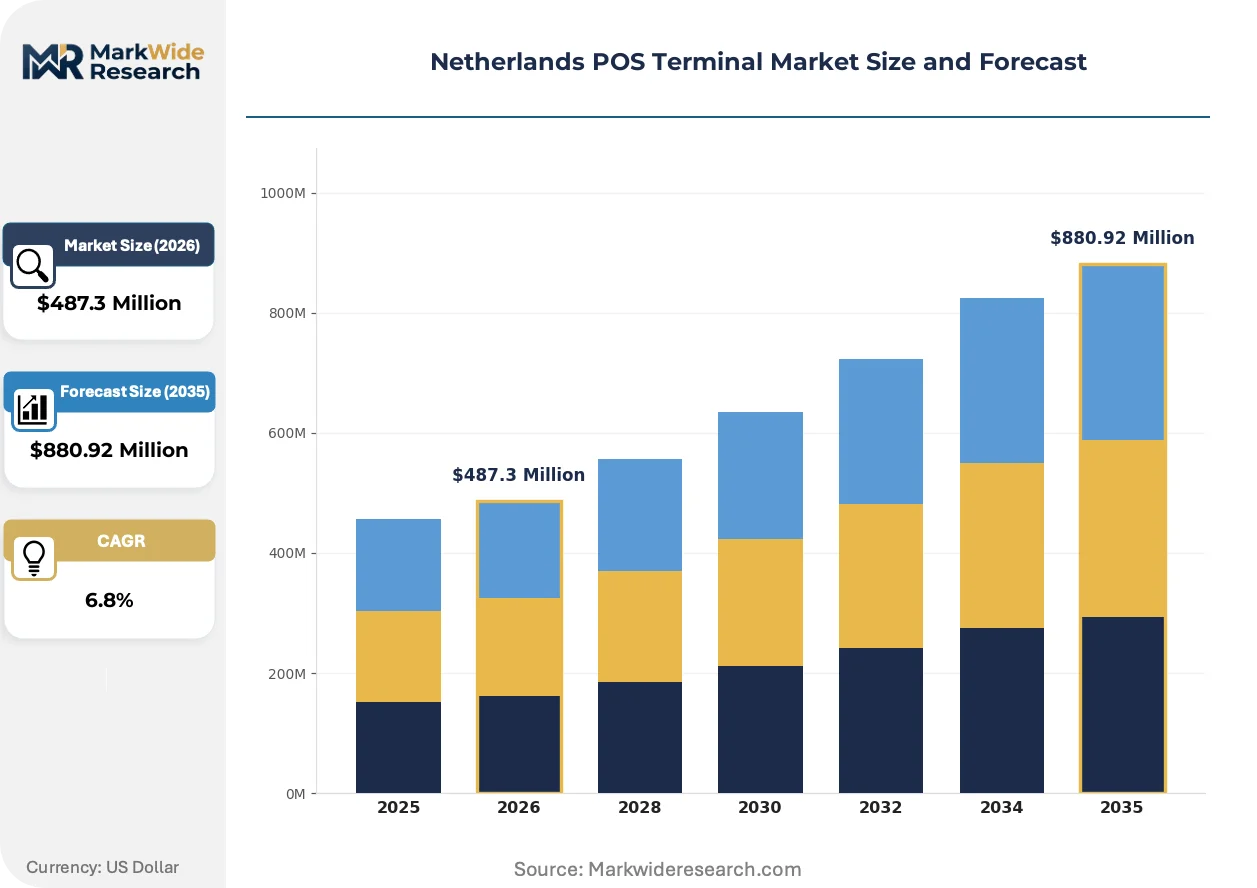
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Wireless POS, Self-service Kiosks End User: Retail, Hospitality, Transportation, Healthcare Technology: Contactless, Chip & PIN, NFC, EMV Distribution Channel: Online, Retail Stores, Distributors, Value-added Resellers |
| Companies Covered | Ingenico ePayments, Verifone Payments BV, Spire Corp, Newland Europe BV, myPOS World Ltd, Adyen, Urovo Technology Corp Ltd, PayPlaza (CM.com), Diebold Nixdorf, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands POS Terminal Market Shifts & Advancements
Three intersecting forces are restructuring Netherlands POS terminal procurement: embedded AI for real-time fraud detection, regulatory pressure for algorithmic transparency, and the unbundling of hardware from payment processing contracts.
Edge-based machine learning inference engines are automating transaction risk scoring directly on terminal hardware without cloud round-trips. Dutch quick-service restaurants are adopting these systems fastest to minimize checkout latency. This architecture is automating the shift from acquirer-hosted fraud rules to merchant-controlled risk parameters.
The EU AI Act's forthcoming classification of credit-scoring and fraud-detection algorithms as high-risk AI systems imposes conformity assessment obligations on terminal vendors. De Nederlandsche Bank is aligning PSD2 certification processes with these AI governance requirements. Smart terminal segments with embedded behavioral analytics face the steepest compliance redesign.
Hardware-as-a-service contracting is displacing perpetual purchase models among Dutch mid-market retailers. Leasing structures bundle terminal refresh cycles with software maintenance, compressing vendor cash conversion cycles. This financing shift is most visible in Amsterdam's independent fashion and specialty retail corridors.
Netherlands POS Terminal Market Segmentation
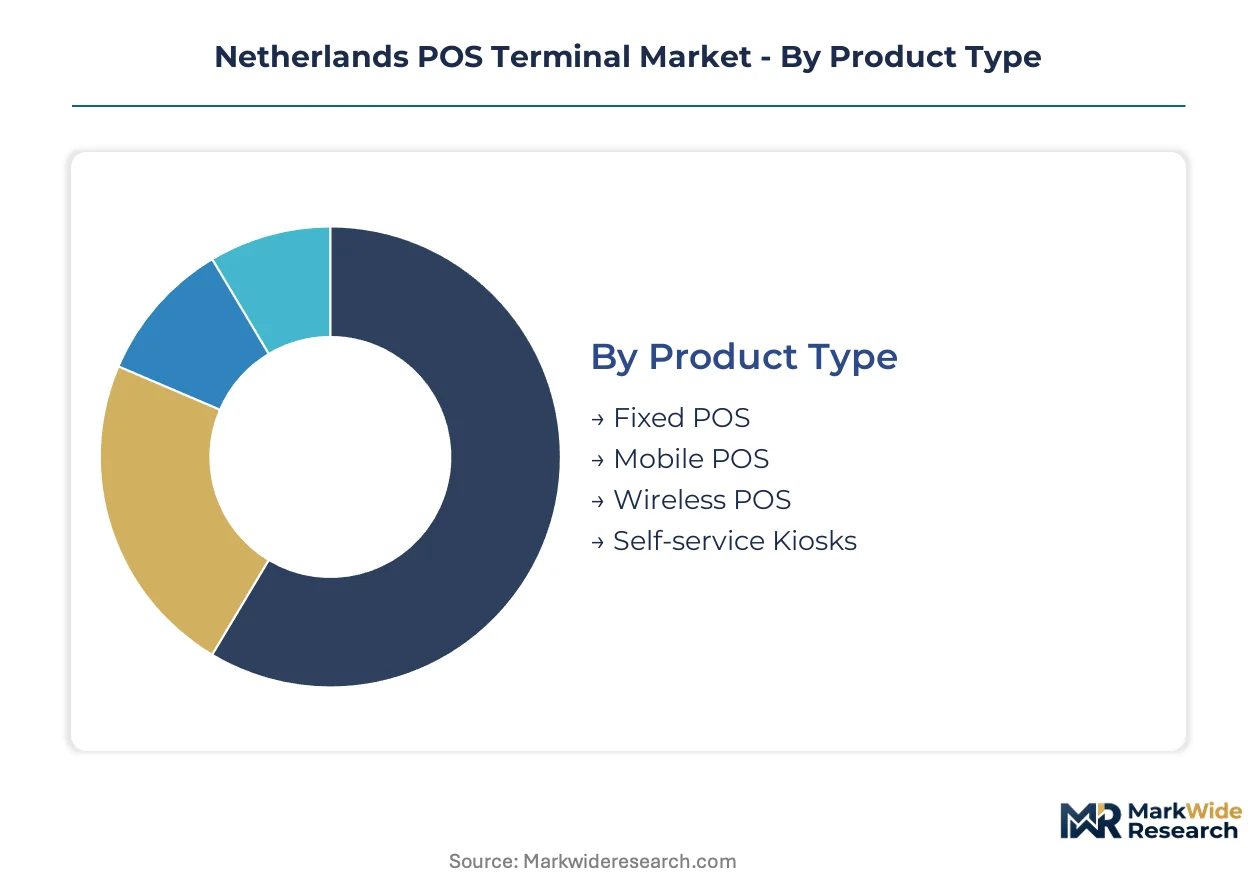
Segmentation in the Dutch POS terminal market reflects divergent procurement logics across merchant tiers. Hardware specifications, connectivity architectures, and compliance burdens vary sharply between supermarket chains and independent hospitality operators.
Product Type:
Customization versus standardization tension runs deepest here, with fixed installations demanding bespoke ERP integration while mobile units prioritize plug-and-play deployment speed.
- Fixed POS:Countertop terminals with Ethernet tethering and high-throughput thermal printers dominate Dutch supermarket chains. Albert Heijn and Jumbo Supermarkten drive refresh cycles in Amsterdam and Rotterdam corridors where lane speed governs checkout design.
- Mobile POS:Battery-powered units with cellular or Wi-Fi backhaul enable tableside and curbside commerce. Dutch hospitality chains in Rotterdam's dense restaurant clusters deploy these fastest as GDPR-compliant data minimization architectures mature.
- Wireless POS:Portable countertop devices with roaming connectivity serve mid-market retail with flexible floor plans.
- Self-service Kiosks:Integrated ordering and payment stations reduce labor exposure in Dutch quick-service restaurants.
Most installed capacity flows through Fixed POS. Expansion is steepest in Mobile POS.
End User:
Volume concentration versus margin extraction defines this split, with retail optimizing per-transaction cost and hospitality prioritizing checkout experience differentiation.
- Retail:High-volume merchants demand PCI-DSS Level 1 compliance and sub-second authorization speeds. Dutch supermarket operators in the Randstad urban belt anchor procurement volumes for fixed-terminal vendors.
- Hospitality:Restaurants, hotels, and cafes prioritize tipping workflows and split-check functionality. Tableside Mobile POS adoption accelerates across Amsterdam's independent dining corridor as labor costs rise.
- Transportation:Transit authorities and parking operators require ruggedized units with offline transaction caching.
- Healthcare:Clinics and pharmacies need HIPAA-aligned patient billing integration under Dutch Data Protection Authority supervision.
Retail commands the largest installed base. Hospitality shows the steepest expansion trajectory as mobile-first workflows normalize.
Technology:
Security architecture maturity separates this landscape, with legacy authentication giving way to tokenized and biometric-enabled protocols.
- Contactless:Tap-to-pay NFC transactions now default behavior among Dutch consumers in urban centers. Terminal upgrades to dual-interface card readers accelerate as De Nederlandsche Bank aligns PSD2 certification with contactless volume thresholds.
- Chip & PIN:EMV-compliant card insertion with PIN verification retains dominance in high-value transactions and age-restricted purchases.
- NFC:Near-field communication enables smartphone wallet acceptance and wearable payment devices.
- EMV:Europay-Mastercard-Visa chip standards underpin all modern terminal security architectures in the Netherlands.
Contactless technology carries the dominant transaction share. NFC-enabled acceptance is gaining share fastest as smartphone wallet penetration deepens.
Distribution Channel:
Service intensity versus transaction efficiency shapes channel selection, with complex integrations favoring intermediaries and standardized hardware moving direct.
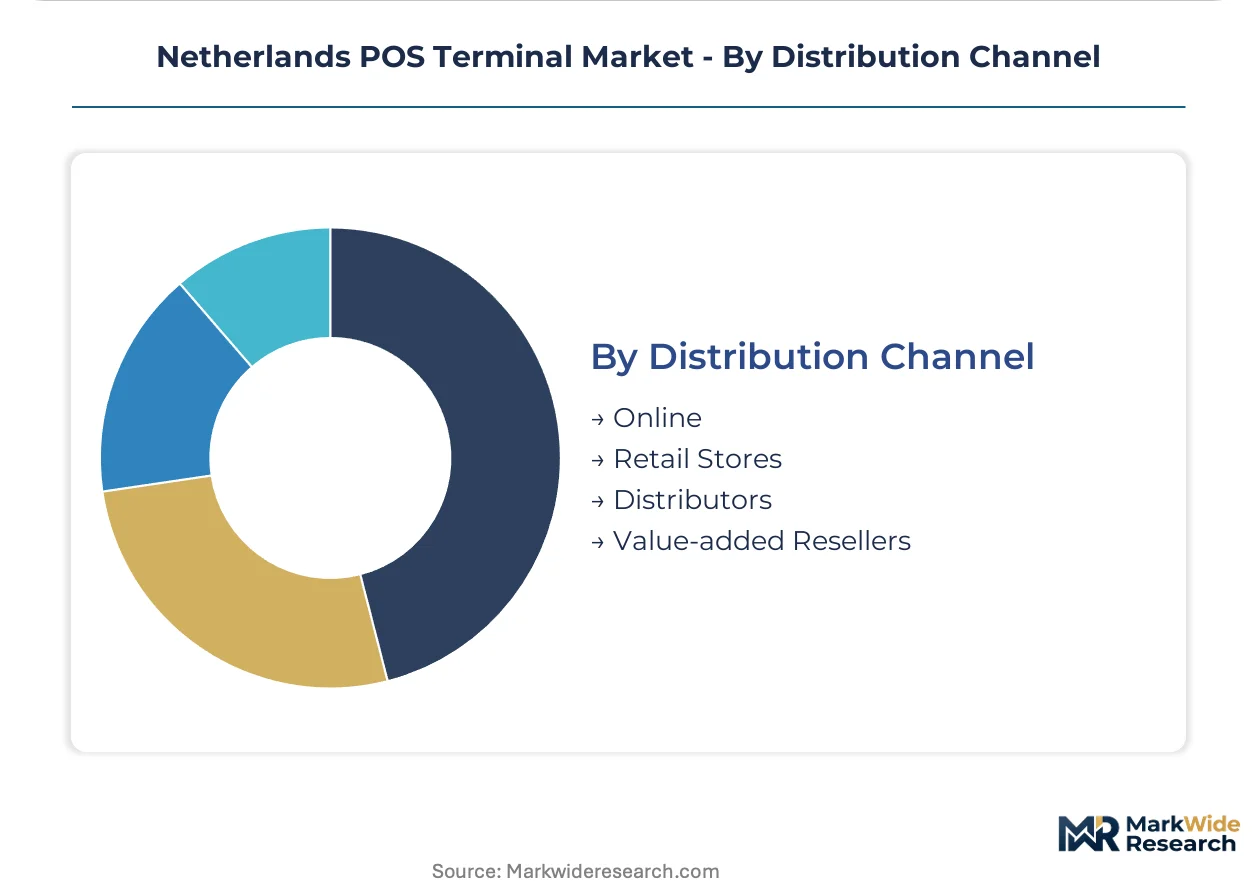
- Online:Direct-to-merchant digital procurement serves micro-businesses with standardized Mobile POS bundles. Dutch sole proprietors in Amsterdam's creative districts favor subscription-based terminal leasing through vendor portals.
- Retail Stores:Electronics retailers provide immediate hardware availability for urgent replacement scenarios.
- Distributors:Wholesale intermediaries aggregate mid-market hospitality demand across Rotterdam and The Hague metro areas.
- Value-added Resellers:Systems integrators bundle terminal deployment with ERP middleware and compliance consulting for Dutch supermarket chains.
Distributor networks handle the majority of hospitality sector volume. Online channels are climbing the fastest as hardware-as-a-service contracting normalizes among independent merchants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems talent clusters concentrate in the Randstad corridor, anchoring terminal firmware development and PCI-DSS compliance engineering for Dutch payment hardware vendors.
Randstad
Amsterdam and Rotterdam retail corridors drive terminal refresh cycles as supermarket chains and hospitality operators upgrade to contactless-enabled form factors. The Dutch Data Protection Authority enforces GDPR-mandated data minimization, compelling privacy-by-design hardware architectures. Dense urban retail in Amsterdam's independent fashion districts accelerates mobile POS procurement for tableside commerce.
Brabant
Eindhoven's semiconductor ecosystem supplies ARM-based processors to terminal assemblers, though Asian foundry concentration exposes Dutch vendors to input volatility. De Nederlandsche Bank supervises payment system integrity under PSD2, shaping certification timelines for hardware launches. Tilburg and Breda logistics hubs generate demand for ruggedized mobile units in warehouse-adjacent use cases.
Eindhoven Region
High-tech manufacturing campuses anchor terminal component sourcing and embedded engineering talent pools. The EU AI Act's forthcoming algorithmic transparency requirements are reshaping firmware development roadmaps for fraud-detection modules. ASML-adjacent precision electronics suppliers feed into terminal encryption module production.
Rotterdam Metro
Port logistics and dense hospitality clusters create dual demand streams for fixed countertop terminals and battery-powered mobile units. Rotterdam's restaurant density accelerates tableside checkout adoption as labor costs rise. The city's industrial zones require specialized hardware for last-mile delivery payment capture.
Northern Netherlands
Groningen and Friesland retail networks lag Randstad refresh cycles but present expansion opportunities for standardized mobile POS bundles. Regional bank branches and agricultural cooperatives drive demand for EMV-compliant chip and PIN terminals. Smaller merchant footprints favor subscription-based hardware-as-a-service contracting over perpetual purchase models.
Netherlands POS Terminal Market Competitive Landscape
Top-tier vendors anchor unified commerce stacks, while mid-market distributors and specialized hardware fabricators occupy distinct competitive tiers. The Dutch market exhibits tiered concentration with premium integrated platforms commanding high-margin relationships, broad-channel players serving hospitality scale, and ruggedization specialists targeting logistics niches. Strategic archetypes include full-stack payment platforms, distributor-dependent hardware vendors, and mobile-first specialists. Competitive moves center on hardware-as-a-service financing restructuring and AI Act compliance positioning for embedded fraud-detection algorithms.
Within the full-stack platform tier, Adyen exemplifies unified commerce convergence, while Verifone Payments BV occupies a position as a distributor-anchored hardware incumbent. Newland Europe BV represents the ruggedized mobile specialization archetype. These three anchors illustrate how Dutch terminal procurement splits between premium software-integrated relationships, broad mid-market channel coverage, and logistics-adjacent hardware durability requirements.
| Leading Market Players |
|---|
| Ingenico ePayments |
| Verifone Payments BV |
| Spire Corp |
| Newland Europe BV |
| myPOS World Ltd |
| Adyen |
| Urovo Technology Corp Ltd |
| PayPlaza (CM.com) |
| Diebold Nixdorf |
| Others |
Supply & Pricing Matrix
ARM-based processor miniaturization simultaneously compresses unit manufacturing costs and concentrates silicon sourcing among Asian foundries, reshaping how Dutch terminal vendors balance margin preservation against supply security. This technological transition feeds directly into procurement strategies across Amsterdam and Rotterdam retail corridors, where hardware-as-a-service contracting now dominates mid-market relationships.
Pricing Analysis
The bundled-vs-unbundled service split separates premium unified commerce platforms from commodity hardware vendors in Dutch POS procurement. Pricing stratifies across integrated software-hardware bundles, standalone terminal sales, and subscription-based leasing with maintenance inclusion. Cost compression in entry-tier mobile units intensifies as soft-POS applications on standard smartphones displace dedicated hardware among micro-merchants. Independent hospitality operators in Rotterdam's restaurant clusters exhibit highest price sensitivity, while Albert Heijn-scale supermarket chains prioritize throughput reliability over per-unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Dutch supermarket chains, while distributor networks aggregate mid-market hospitality volume across The Hague and Utrecht metro areas. ARM-based processor sourcing draws from Taiwan, South Korea, and China, with encryption module components anchored in German and Dutch precision electronics facilities. Single-source vulnerability in advanced semiconductor lithography exposes terminal assemblers to extended lead time volatility. Distribution runs through value-added resellers bundling ERP middleware for legacy system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands POS terminal market functions as a stable compounder, with regulatory-mandated refresh cycles under GDPR and PSD2 creating predictable replacement demand across Dutch merchant tiers.
For Market Incumbents: Hedge against soft-POS displacement by embedding fraud-detection algorithms that trigger EU AI Act compliance requirements, creating switching costs for merchants. Deepen vertical integration into PCI-DSS encryption module production to reduce exposure to semiconductor supply concentration. Prioritize channel control through exclusive distributor relationships in Rotterdam's dense hospitality clusters. For New Entrants and Emerging Players: Launch via hardware-as-a-service subscription models targeting independent retailers in Amsterdam's creative districts, where perpetual purchase friction remains highest. Logistics-adjacent ruggedized mobile units for Eindhoven warehouse and last-mile delivery use cases represent the most penetrable white space. Position around GDPR-compliant data minimization architectures as a differentiated compliance offering. For Investors and Strategic Acquirers: Valuations sit cheapest among distributor-dependent hardware vendors lacking unified commerce software integration. The five-to-ten year viability window favors platforms combining payment processing with inventory and loyalty convergence. Monitor De Nederlandsche Bank PSD2 certification timeline announcements as the key inflection signal for hardware launch cadence and vendor cash conversion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Positioning | Embedded audit capabilities for fraud-detection algorithms create first-mover certification advantage under De Nederlandsche Bank supervision. |
| Hardware-as-a-Service Restructuring | Subscription bundling of terminal refresh cycles with software maintenance compresses vendor cash conversion cycles in Amsterdam retail corridors. |
| Unified Commerce Stack Integration | Convergence of inventory management, loyalty, and payment routing opens margin expansion in mid-market Dutch hospitality. |
| Ruggedized Mobile Specialization | Dedicated units for Eindhoven logistics zones address underpenetrated warehouse and last-mile delivery payment capture use cases. |
| Privacy-by-Design Architecture | GDPR-mandated data minimization compliance creates replacement demand for legacy PCI-DSS systems across Dutch merchant tiers. |
Research Methodology
Multiple input streams — terminal vendor product roadmaps, merchant procurement pattern analysis, and regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary interviews with payment hardware engineering directors, Dutch supermarket chain IT procurement leads, hospitality operations managers, and distributor network heads were cross-validated against secondary sources including De Nederlandsche Bank PSD2 certification databases, Dutch Data Protection Authority enforcement records, and ARM Holdings ecosystem disclosures.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to model expansion across product type, end user, technology, and distribution channel dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market sizing. Forecast inputs incorporated GDPR compliance timeline assumptions, semiconductor supply lead time volatility, and soft-POS substitution elasticity parameters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or extended Asian foundry supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Africa Real Time Payments Market
Payments
Romania POS Terminals Market
Payments
Germany Payments Market
Payments
Gift Card and Incentive Card Market
Payments
Digital Payment in Healthcare Market
Payments
Global Real-Time Payments Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Hong Kong Credit Cards Market
Payments
Electronic Payment System for Transportation Market
Payments
Buy Now Pay Later Market
Payments
Mexico Payments Market
Payments
QR Codes Payment Market
Payments
Japan Payments Market
Payments
Fuel Cards Market