
 Taiwan Mobile Payments Market | 2026-2036
Taiwan Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Mobile Payments Market Analytics
Small businesses is redrawing competitive priorities away from large enterprises in Taiwan's mobile payments landscape. Taiwan Mobile Payment Co., Ltd. anchors the domestic infrastructure through its interoperable platform spanning multiple banking partners. LINE Pay Corporation leverages its messaging ecosystem to sustain merchant lock-in across convenience retail. JKOPay Co., Ltd. differentiates through hyper-localized rewards targeting night market vendors and food service operators.
Mobile payments encompass financial transactions executed through portable devices using encrypted tokenization, near-field communication, or Quick Response code scanning to transfer monetary value between parties without physical currency exchange. The primary commercial purpose centers on reducing friction in retail checkout, enabling real-time settlement, and capturing consumer behavioral data for targeted financial services. QR code methods dominate transaction volume in Taiwan's dense urban retail corridors where low-cost deployment suits micro-merchants. Digital wallet platforms command the strongest margin pools through stored-value float and interchange fee stacking. NFC-enabled contactless methods lead among transit-integrated payments in Taipei's metro and bus networks.
Taiwan's Financial Supervisory Commission enforces payment service operator licensing and capital reserve requirements that constrain foreign platform entry. The central bank's real-time gross settlement infrastructure underpins instant fund clearing for licensed mobile payment providers. The Personal Data Protection Act shapes how transaction data may flow between banks, telecoms, and platform operators. Stakeholders must monitor whether open banking API mandates will force incumbent banks to cede customer interface control to technology platforms.
Market Dynamics
Taiwan's Financial Supervisory Commission is forcing incumbent banks to open APIs through its open banking framework, compressing the competitive moat around legacy payment infrastructure and accelerating third-party platform entry.
Growth Catalysts
- QR Code Standardization Mandate:The central bank's unified QR specification eliminates merchant-side fragmentation. Night market vendors now deploy single-scan solutions across multiple wallet providers.
- Taipei Metro Transit Integration:NFC-enabled mobile ticketing binds daily commuters to stored-value wallets. Transit ridership exceeds two million daily trips, creating habitual payment behavior.
- Small Merchant Onboarding Incentives:Acquirers waive terminal fees for micro-businesses. Convenience store chains act as enrollment hubs, reducing KYC friction for unbanked sole proprietors.
Market Restraints
- Capital Reserve Requirements:The Financial Supervisory Commission mandates substantial escrow deposits for payment service operators. Foreign entrants face prohibitive liquidity thresholds.
- Telecom-Dependent Infrastructure:Mobile authentication relies on carrier-grade SIM security. Chunghwa Telecom and Far EasTone control the subscriber identity module layer, extracting tolls from wallet providers.
- Cash Persistence in Rural Counties:Taitung and Hualien maintain high physical currency preference. Elderly populations distrust biometric verification, capping digital wallet penetration outside northern urban corridors.
Strategic Opportunities
- Cross-Border Remittance Corridors:Southeast Asian migrant workers in Taoyuan and Kaohsiung send earnings to Indonesia and Vietnam. Blockchain-based settlement rails could undercut Western Union's correspondent banking fees.
- Embedded Finance in Night Markets:QR-enabled working capital advances tied to transaction history. Vendors access same-day liquidity without traditional credit scoring.
- Biometric Payment Convergence:Facial recognition at point-of-sale merges with palm-vein authentication. Department stores in Taipei's Xinyi District pilot multi-modal verification for high-value purchases.
Industry Challenges
- Legacy Core Banking Integration:Domestic banks operate on decades-old COBOL systems. Real-time wallet-to-account settlement requires expensive middleware development.
- Data Localization Compliance:The Personal Data Protection Act restricts cross-border transaction data flows. Cloud-hosted analytics engines must maintain Taiwan-based servers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Mobile Payments Market |
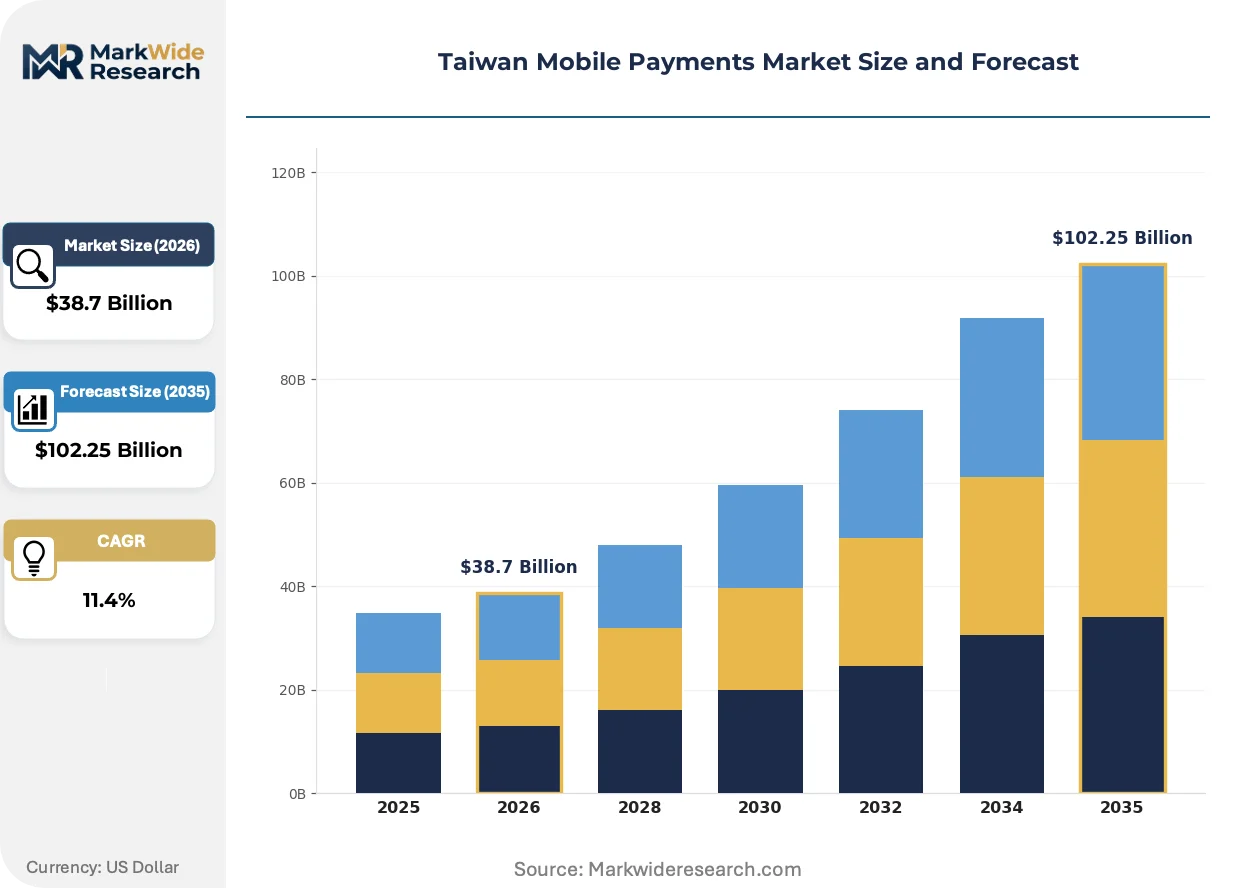
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, QR Code End User: Retail Customers, Online Shoppers, Small Businesses, Large Enterprises Technological Platform: Mobile App, Web Portal, POS Terminal, NFC Transaction Type: P2P Transactions, Bill Payments, In-store Purchases, E-commerce |
| Companies Covered | Alphabet Inc., Alibaba Group Holdings Limited, JKOPay Co., Ltd., PayPal Holdings, Inc., Tencent Holdings Limited, LINE Pay Corporation, Taiwan Mobile Payment Co., Ltd., Samsung Electronics Co., Ltd., Apple Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Mobile Payments Market Evolving Landscape
Payment authentication is fragmenting across multiple biometric modalities while regulatory pressure accelerates infrastructure interoperability. Merchant acquisition models are compressing toward zero-friction enrollment.
SoftPOS technology is bifurcating the merchant hardware market. Small vendors in Kaohsiung's Liouho Night Market now accept contactless payments through smartphone-only solutions. Traditional dedicated terminal manufacturers face margin compression as software-only deployment eliminates upfront device costs.
The Financial Supervisory Commission's open banking framework mandates standardized API access for licensed third-party providers. Incumbent banks must expose customer account data to vetted fintech platforms. Taipei-based digital wallets are capturing primary customer interface control previously held by branch networks.
Younger consumers in New Taipei City now initiate payments within super-app environments rather than standalone banking applications. LINE Pay and JKOPay embed financial services alongside messaging and food delivery. This behavioral shift concentrates transaction data within platform operators, eroding bank-owned customer intelligence.
Taiwan Mobile Payments Market Segmentation
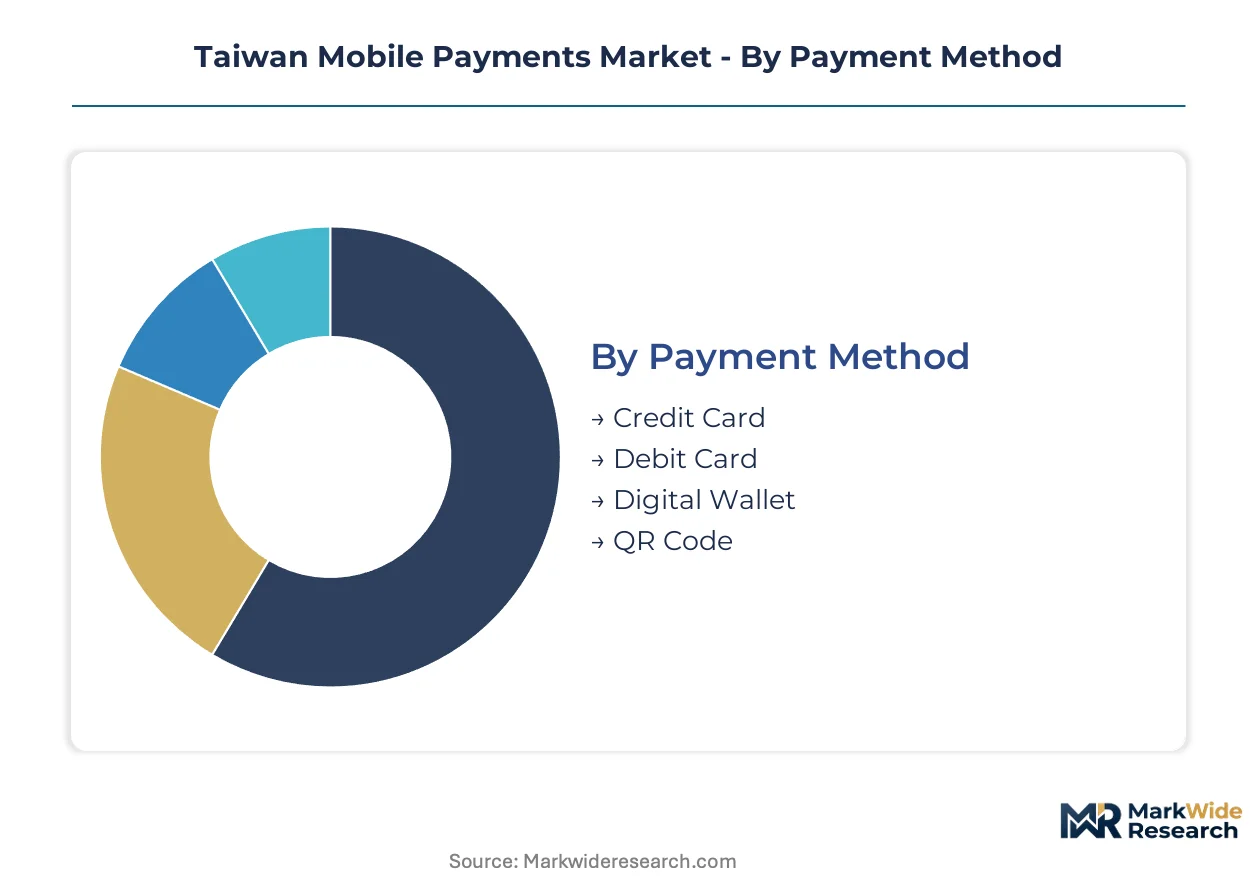
Taiwan's mobile payment infrastructure fragments across four distinct dimensions that shape platform architecture and merchant acquisition strategies. Payment method selection determines hardware requirements for night market vendors versus department stores. End user segmentation reveals divergent authentication needs between elderly cash users and digitally native consumers.
Payment Method:
Domestic demand concentrates in QR code and digital wallet solutions suited to Taiwan's dense urban retail corridors, while credit card integration serves cross-border e-commerce and international traveler segments.
- Credit Card:Tokenized card-on-file systems enable high-value transactions through 3D Secure authentication. Department stores in Taipei's Xinyi District and luxury retailers rely on this method for purchases exceeding stored-value wallet limits. The Financial Supervisory Commission's interchange fee caps compress issuer margins.
- Digital Wallet:Stored-value platforms dominate daily consumption through prepaid float and linked bank accounts. LINE Pay and JKOPay capture habitual usage across convenience retail and food service. Younger consumers in New Taipei City exhibit the strongest platform loyalty.
- QR Code:Merchant-presented codes eliminate terminal costs for micro-businesses. Night market vendors deploy unified specifications mandated by the central bank. Low deployment friction accelerates penetration among unbanked sole proprietors.
- Debit Card:Real-time account deduction appeals to budget-conscious users avoiding credit exposure. Integration with domestic ATM networks enables cash-out functionality at 7-Eleven and FamilyMart locations.
Digital wallet commands the established base. The steepest expansion runs through QR code.
End User:
Volume distribution skews toward high-frequency, low-value transactions among individual consumers, while enterprise adoption drives platform investment in API infrastructure and reconciliation tools.
- Retail Customers:Individual consumers executing daily purchases through smartphone applications. Taipei and New Taipei City residents generate the densest transaction volumes. Transit-integrated wallets create habitual payment behavior among commuters.
- Small Businesses:Night market vendors and independent retailers utilizing simplified onboarding through convenience store chains. The Financial Supervisory Commission's reduced KYC thresholds for micro-merchants accelerate enrollment. Cash flow visibility from digital records enables alternative credit scoring.
- Online Shoppers:E-commerce transactions requiring escrow protections and dispute resolution mechanisms. Cross-border purchases from mainland China and Southeast Asia drive foreign exchange integration demands.
- Large Enterprises:Corporate treasury departments seeking automated accounts payable and expense management. Manufacturing firms in Taoyuan and Kaohsiung integrate mobile payments into supplier settlement workflows.
Retail customers anchor transaction volume. Small businesses are gaining share fastest.
Technological Platform:
Merchant-side deployment costs create a bifurcation between software-only solutions for micro-vendors and dedicated hardware for high-volume retail environments.
- Mobile App:Consumer-facing applications dominate authentication and transaction initiation. Super-app environments consolidate messaging, payments, and food delivery. LINE Pay leverages its messaging ecosystem for merchant lock-in.
- NFC:Contactless infrastructure enables transit integration and high-speed retail checkout. Taipei Metro's two million daily trips condition commuter behavior. Department stores pilot biometric-linked NFC for purchases above wallet limits.
- POS Terminal:Dedicated hardware persists in high-volume retail and hospitality. Traditional terminal manufacturers face margin pressure from SoftPOS alternatives. Large supermarket chains maintain multi-payment acceptance.
- Web Portal:Browser-based interfaces serve bill payment and account management functions. Utility companies and telecommunications operators embed payment modules in customer service portals.
Mobile app holds the dominant position. NFC shows the steepest trajectory.
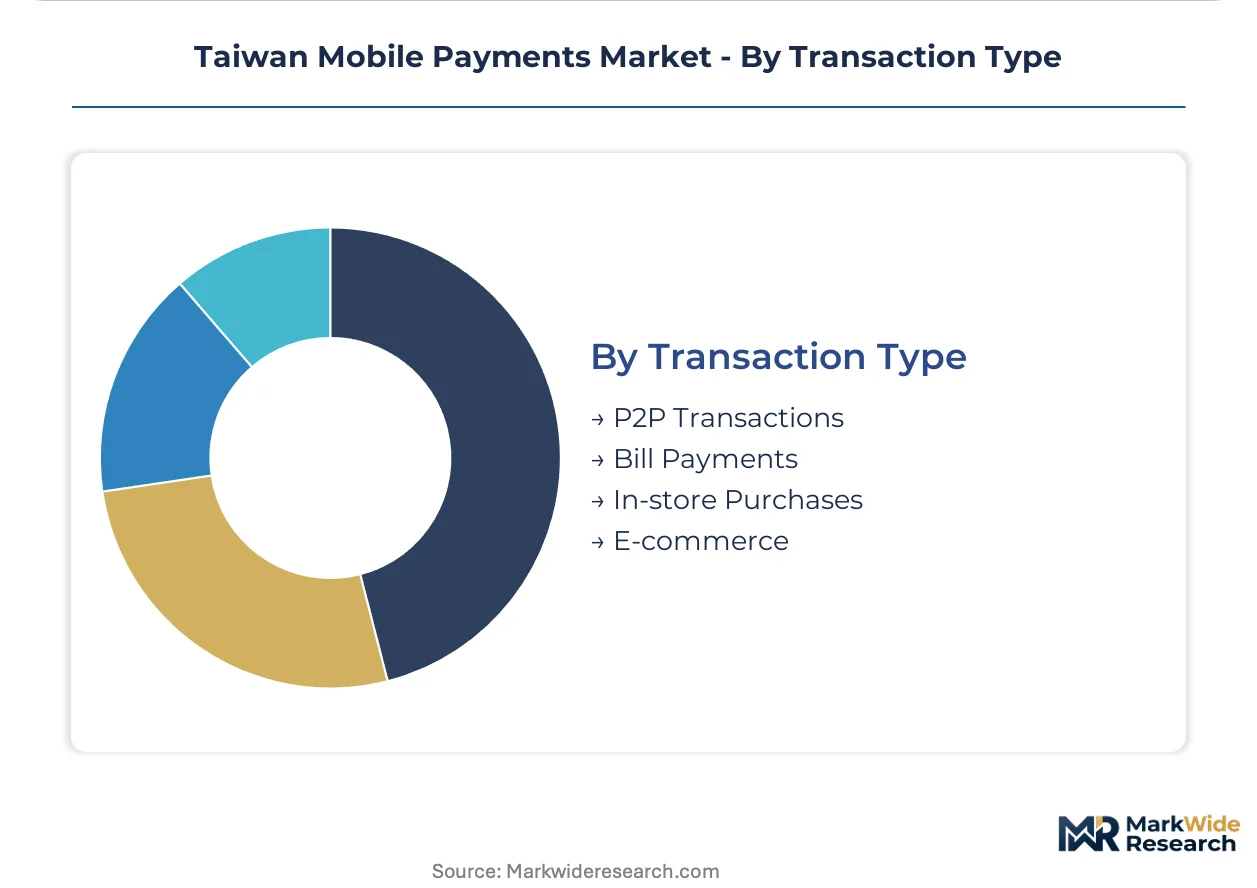
Transaction Type:
Platform economics vary sharply between low-margin, high-frequency purchases and higher-value transactions generating meaningful interchange revenue.
- In-store Purchases:Physical retail transactions across convenience stores, night markets, and department stores. QR code methods suit Taiwan's dense urban corridors with minimal merchant hardware investment.
- E-commerce:Online merchant transactions requiring fraud protection and buyer guarantees. Cross-border purchases from Southeast Asian platforms drive foreign payment method integration.
- P2P Transactions:Direct transfers between individuals for splitting expenses and informal settlements. Younger consumers prefer platform-based transfers over traditional bank remittance.
- Bill Payments:Recurring utility and telecommunications settlements through scheduled or on-demand initiation. Convenience store counters serve as cash-to-digital conversion points for unbanked users.
In-store purchases represent the volume anchor. E-commerce climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's mobile payment infrastructure exports technical specifications and interoperability frameworks to Southeast Asian markets, particularly Vietnam and Indonesia where Taiwanese fintech investment flows concentrate. The island's regulatory sandbox model influences Philippine and Malaysian central bank digital payment guidelines.
Taipei City
Taipei City's dense commercial corridors generate the highest transaction density per square kilometer in Taiwan. The Financial Supervisory Commission's sandbox licensing program permits controlled trials of facial recognition payments in Xinyi District department stores. Taipei Metro's two million daily commuters anchor habitual wallet usage among working-age professionals.
New Taipei City
New Taipei City's younger demographic profile drives super-app payment adoption rates above national averages. The municipal government's smart city initiative mandates QR code acceptance at all public parking facilities. Zhonghe and Banqiao districts host the densest concentrations of night market vendors deploying unified payment specifications.
Taoyuan
Taoyuan's industrial zones and international airport create unique cross-border payment corridors for Southeast Asian migrant workers. The central bank permits specialized remittance licenses for wallet providers serving Indonesian and Vietnamese labor communities. Taoyuan City Government partners with convenience store chains for cash-in/cash-out network expansion.
Kaohsiung
Kaohsiung's port economy and night market culture sustain high-velocity, low-value transaction volumes. The municipal transportation bureau integrated harbor ferry services into regional transit wallet systems. Liouho Night Market vendors pioneered SoftPOS deployment, eliminating dedicated terminal requirements for micro-merchants.
Taichung
Taichung's precision machinery sector drives enterprise-grade B2B payment platform demand for supplier settlements. The city's central geographic position makes it a testing ground for inter-regional wallet interoperability standards. Feng Chia Night Market serves as a benchmark for merchant onboarding efficiency metrics.
Taiwan Mobile Payments Market Competitive Landscape
Player mix skews toward domestic infrastructure operators and messaging-ecosystem platforms, with limited penetration by pure international payment networks. The competitive structure concentrates around three licensed domestic platforms controlling interoperable QR infrastructure. Two strategic archetypes dominate: telecom-bank consortium operators leveraging subscriber identity modules for authentication security, and super-app platforms embedding payments within messaging and social commerce. Competitive moves center on merchant acquisition cost compression and transit system exclusivity bidding.
Within the domestic infrastructure tier, Taiwan Mobile Payment Co., Ltd. anchors interoperable settlement rails across multiple banking partners. LINE Pay Corporation occupies the super-app integration position, leveraging messaging ecosystem lock-in for merchant retention. JKOPay Co., Ltd. exemplifies the hyper-localized rewards archetype, targeting night market vendor networks with transaction-based loyalty programs. These three entities represent distinct strategic positioning vectors: infrastructure neutrality, ecosystem enclosure, and vertical specialization.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Alibaba Group Holdings Limited |
| JKOPay Co., Ltd. |
| PayPal Holdings, Inc. |
| Tencent Holdings Limited |
| LINE Pay Corporation |
| Taiwan Mobile Payment Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
Platform scale economies in Taiwan's interoperable QR infrastructure compress merchant acquisition costs while elevating price floors for foreign entrants facing capital reserve mandates. Dense urban transaction volumes in Taipei and New Taipei City amortize fixed compliance investments across millions of daily scans, reinforcing domestic operator dominance.
Pricing Analysis
Current-generation SoftPOS deployment runs at zero hardware cost versus prior-generation dedicated terminals requiring upfront capital outlays, while next-generation biometric-linked authentication commands premium interchange rates. Three-tier pricing structure across premium, standard, and economy levels reflects settlement speed guarantees and fraud protection depth. Cost compression in the economy tier intensifies because acquirers waive terminal fees for micro-merchants. Night market vendors exhibit highest price sensitivity; department stores in Xinyi District show lowest, prioritizing biometric verification reliability.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for secure element chips, while China dominates QR code scanner module assembly and plastic housing production. Domestic supply draws from Chunghwa Telecom's subscriber identity module infrastructure and Far EasTone's authentication middleware. Single-source vulnerability concentrates in carrier-grade SIM security layers controlled by two telecom incumbents. Distribution runs through convenience store chains acting as cash-in/cash-out nodes and merchant enrollment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's mobile payment market functions as a service-attach opportunity where transaction data analytics and merchant working capital advances expand faster than core payment processing hardware. Recurring revenue from embedded finance layers outpaces one-time terminal deployment margins.
For Market Incumbents: Fortify interoperable QR infrastructure through deeper integration with the Financial Supervisory Commission's open banking APIs, neutralizing super-app platforms' customer interface control. Expand captive supply of biometric authentication modules to reduce telecom-dependent SIM security tolls. Prioritize transit system exclusivity bidding in Kaohsiung and Taichung before platform competitors anchor habitual commuter behavior. For New Entrants and Emerging Players: Merchant onboarding service gaps in Taitung and Hualien counties present white-space entry points where cash persistence has deterred incumbent investment. Target rural elderly populations with voice-guided authentication interfaces bypassing biometric distrust. Deploy agent-based enrollment through local temple associations and agricultural cooperatives as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized remittance infrastructure operators serving Southeast Asian migrant corridors over generalist wallet platforms. Long-term viability hinges on cross-border settlement license scalability and blockchain rail integration depth. Monitor Taoyuan City Government's specialized remittance license issuance velocity as the critical inflection signal for corridor profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Transit System Exclusivity Agreement | Taipei Metro's two million daily trips condition habitual wallet usage among working-age professionals. |
| Biometric Authentication Partnership | Facial recognition pilots in Xinyi District department stores merge with palm-vein verification for high-value purchases. |
| Cross-Border Remittance License Acquisition | Specialized permits for Indonesian and Vietnamese worker corridors undercut Western Union's correspondent banking fees. |
| Embedded Working Capital Platform | QR-enabled advances tied to transaction history provide same-day liquidity without traditional credit scoring. |
| SoftPOS Technology Integration | Smartphone-only solutions eliminate dedicated terminal costs for Liouho Night Market micro-merchants. |
Research Methodology
Operator-level perspectives from payment platform executives, Financial Supervisory Commission regulatory leads, night market merchant association representatives, and convenience store chain operations managers anchored the qualitative base. Primary interview insights combined with secondary validation from central bank QR specification documents, transit authority ridership disclosures, and telecom carrier authentication service filings. Bottom-up transaction volume modeling and top-down regulatory capacity analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against varying open banking API adoption timelines and transit integration penetration rates. Segmentation dimensions modeled include payment method, end user archetype, technological platform deployment cost tier, and transaction type velocity class. CAGRs derived from wallet penetration trajectory analysis and merchant onboarding efficiency metrics across Taipei, New Taipei City, and Kaohsiung corridor benchmarks. Industry-specific inputs incorporated the Financial Supervisory Commission's capital reserve requirement thresholds and Personal Data Protection Act localization mandates.
Forecasts assume regulatory continuity in Taiwan's Financial Supervisory Commission licensing regime and central bank real-time gross settlement infrastructure; material policy shifts would require re-modeling. Specific risk factors include open banking mandate acceleration forcing incumbent banks to cede customer interface control, and rural cash persistence caps constraining national penetration ceilings. Recalibration cycles align with material shifts in transit system exclusivity awards and cross-border remittance corridor licensing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America Accounts Payable Automation Market
Payments
Mobile Payment Transaction Market
Payments
QR Codes Payment Market
Payments
United Kingdom Mobile Payments Market
Payments
North America Payments Market
Payments
Japan Prepaid Cards Market
Payments
Portugal POS Terminals Market
Payments
Payment Security Software Market
Payments
Saudi Arabia Payments Market
Payments
US Buy Now Pay Later Services Market
Payments
Wireless POS Terminals Market
Payments
APAC Mobile Payments Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
NFC Payments Market
Payments
Instant Payments Market
Payments
Malta POS Terminal Market