
 Hungary POS Terminal Market | 2026-2036
Hungary POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary POS Terminal Market Foresight
Market Context
Buyer fragmentation across independent retailers and hospitality SMEs is expanding the addressable base for terminal vendors beyond legacy banking channels. Worldline SA leverages its European processing backbone to sustain merchant acquirer relationships across Hungarian urban centers. Ingenico anchors the high-volume supermarket segment with durable hardware platforms. myPOS competes aggressively on cloud onboarding speed for micro-merchants without traditional banking ties.
Technical Definition and Segment Structure
A POS terminal is an electronic device that captures payment card data, encrypts transaction information, and communicates with acquiring banks through secure networks, typically supporting EMV chip authentication and NFC proximity protocols for contactless settlement. Mobile POS dominates unit volume among street vendors and delivery services, while traditional POS retains margin concentration in hotel chains and large retail formats. Cloud-based delivery mode captures the fastest expansion as Hungarian merchants prioritize remote software updates and real-time sales analytics over on-premises server maintenance.
Regulatory Framework
The National Bank of Hungary governs payment system stability and terminal certification requirements, while PSD2 compliance obligations from EU financial regulators shape authentication protocols and data security standards for cross-border transactions. GDPR constraints on transaction data storage influence software architecture decisions for vendors serving European merchant bases. Stakeholders must monitor regulatory timing for instant payment mandates and assess whether hardware refresh cycles align with evolving certification thresholds.
Market Dynamics
The National Bank of Hungary's instant payment infrastructure mandate is compressing hardware refresh cycles and forcing terminal vendors to recertify devices for real-time settlement protocols, reshaping procurement priorities across Budapest's merchant acquirer networks.
Growth Catalysts
- Instant Payment Mandate:The National Bank of Hungary's regulatory push for real-time settlement infrastructure forces merchant acquirers to upgrade terminal fleets, creating replacement demand across retail and hospitality sectors.
- Contactless Protocol Adoption:NFC-enabled transaction volumes in Hungarian restaurants and cafes are accelerating terminal penetration among small-format food service operators previously reliant on cash.
- Cloud Delivery Preference:Hungarian merchants are prioritizing software-as-a-service POS architectures that enable remote firmware updates and eliminate on-premises server maintenance costs.
Market Restraints
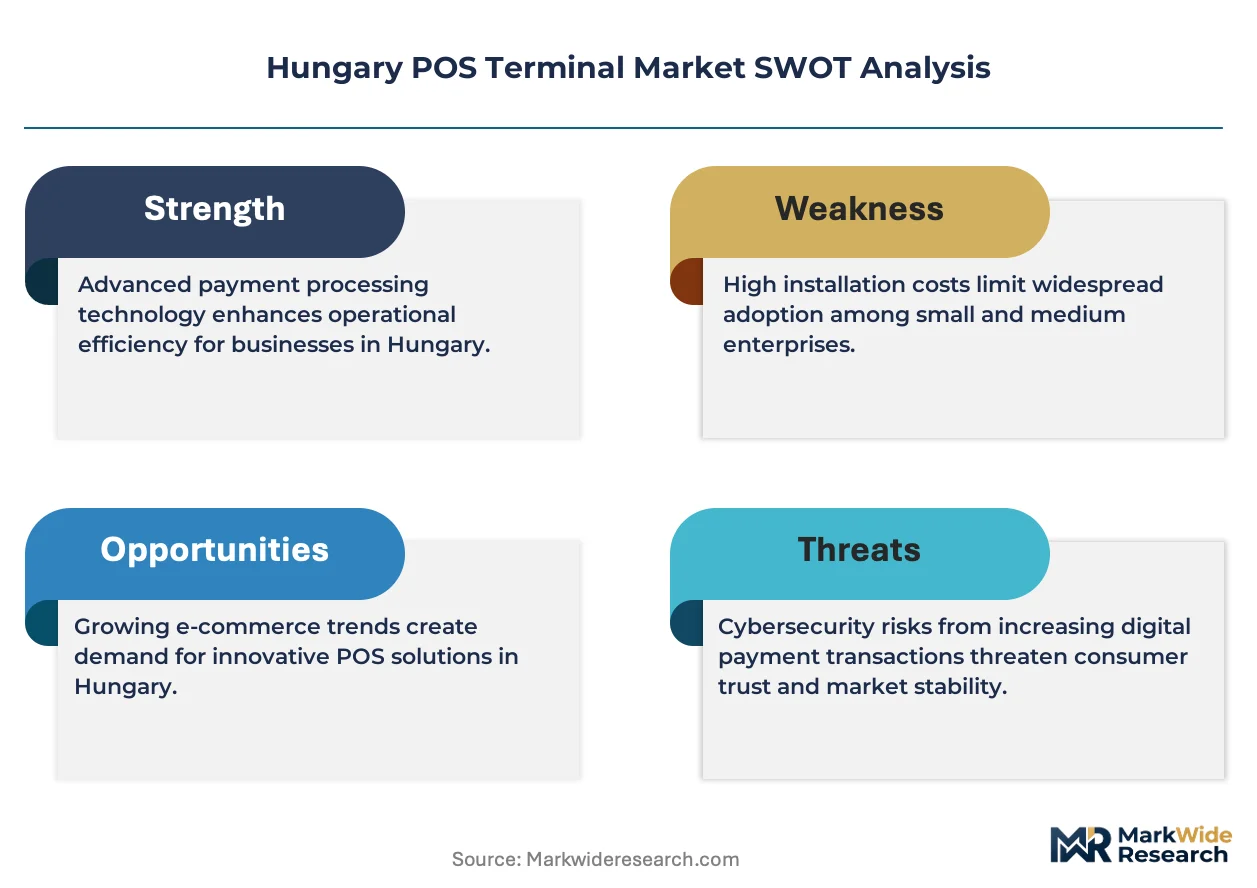
- Semiconductor Supply Concentration:Terminal manufacturers face input cost volatility from concentrated Asian chip foundry capacity, compressing hardware margins for European vendors serving Hungarian distribution channels.
- Certification Timeline Friction:EMVCo and PCI DSS compliance requirements extend product launch timelines by 8-14 months, delaying revenue recognition for new terminal form factors.
- Mobile Wallet Substitution:SoftPOS applications on consumer smartphones threaten dedicated terminal volumes among micro-merchants with transaction volumes below regulatory reporting thresholds.
Strategic Opportunities
- Central Transdanubia Expansion:Secondary urban centers including Székesfehérvár and Tatabánya remain underpenetrated by integrated POS systems, offering first-mover advantages for cloud-native terminal vendors.
- Hospitality Vertical Convergence:Tableside ordering applications combined with payment acceptance are creating bundled solution demand among Budapest's full-service restaurant operators.
- GDPR-Compliant Analytics:Transaction data monetization services that respect European data protection constraints represent an adjacent revenue stream for terminal vendors with captive merchant relationships.
Industry Challenges
- Embedded Systems Talent Scarcity:Hungarian terminal vendors compete with automotive and industrial automation sectors for firmware engineers proficient in secure element integration and NFC stack optimization.
- Legacy Protocol Integration:Merchants operating hybrid environments must reconcile instant payment APIs with decades-old property management and inventory systems, extending deployment timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary POS Terminal Market |
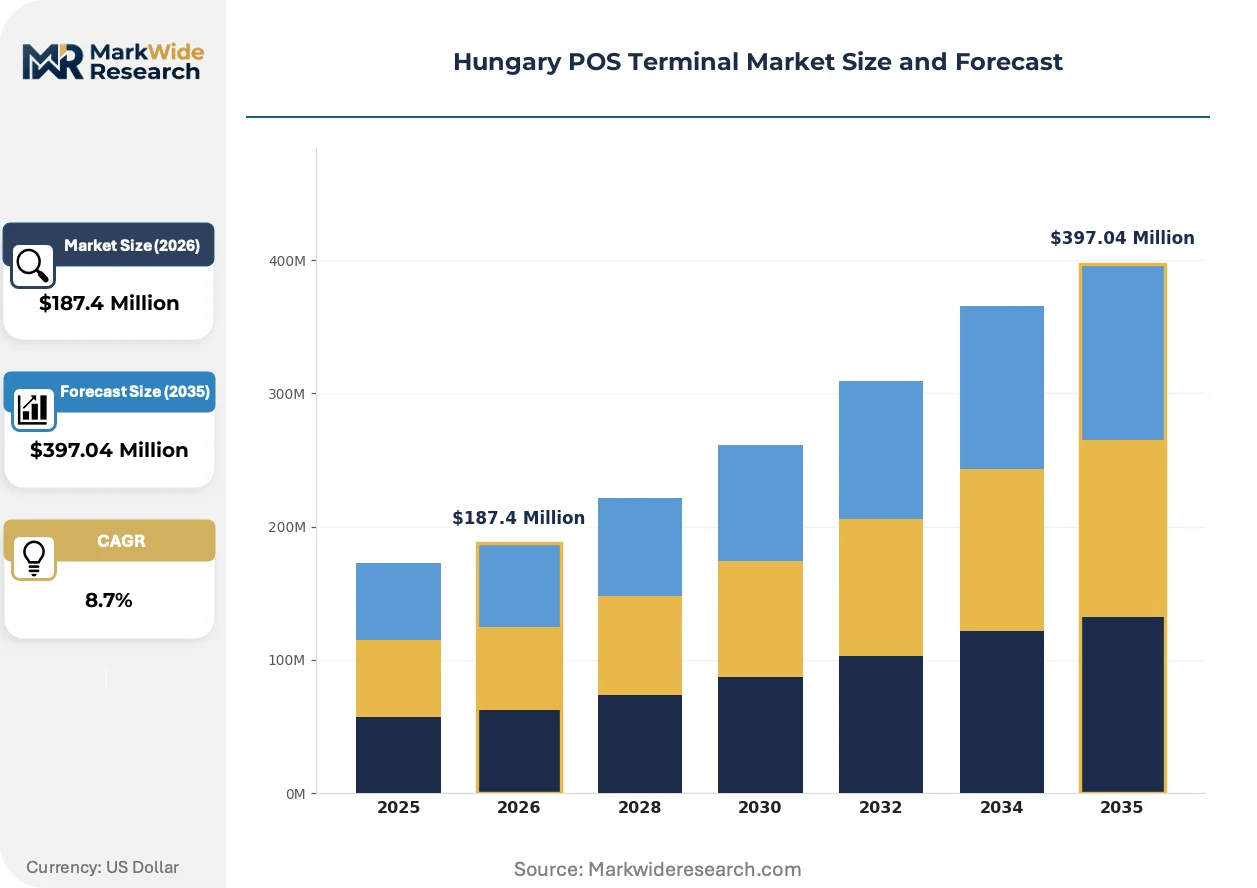
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Traditional POS, Self-Service Kiosk, POS Software Delivery Mode: Cloud-Based, On-Premises, Hybrid, Local Installation End User: Retail Stores, Restaurants, Hotels, Supermarkets Payment Method: Credit Card, Debit Card, Mobile Payments, Contactless |
| Companies Covered | B-Payment Szolgáltató Zrt, Bartimex Kft, Worldline SA, Ingenico, myPOS, Novopayment, Quadrapay, eService Sp z o o, SRS Informatika Kft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary POS Terminal Market Shifts & Advancements
Payment terminal architecture is pivoting from dedicated hardware toward software-defined platforms, with Hungarian merchant demand accelerating three concurrent shifts in form factor, regulatory compliance, and procurement behavior.
SoftPOS technology is automating merchant onboarding by converting standard Android devices into certified payment terminals without dedicated hardware procurement. Hungarian delivery services and street vendors are adopting this capability fastest, bypassing traditional banking relationships entirely. The technology is automating terminal distribution by eliminating physical supply chain dependencies and compressing time-to-first-transaction from weeks to hours.
PSD2 strong customer authentication requirements are mandating biometric verification modules and dynamic linking protocols for remote transactions. Terminal vendors serving Hungarian e-commerce merchants must integrate fingerprint sensors or facial recognition cameras into next-generation devices. The supermarket and large retail segments are absorbing these compliance costs earliest, passing authentication burden to device specifications rather than consumer friction.
Merchant procurement of payment infrastructure is consolidating through integrated software platforms rather than standalone hardware purchases. Hungarian hospitality operators are selecting terminal vendors based on native compatibility with reservation and kitchen display systems, not hardware specifications alone. This pattern is most visible in Budapest's district VII and district VI restaurant clusters, where POS replacement decisions follow property management system upgrade cycles.
Hungary POS Terminal Market Segmentation
POS terminal segmentation in Hungary reveals divergent hardware requirements across merchant tiers. Procurement patterns split between volume-driven micro-merchant adoption and premium integrated systems in Budapest's hospitality clusters.
Product Type:
Volume concentration favors portable hardware, while premium margins attach to fixed installations and software layers.
- Mobile POS:Compact Android-based terminals with integrated NFC readers and thermal printers dominate street vendor and delivery fleet procurement. Hungarian food trucks and courier services in Budapest's outer districts favor these units for their cellular connectivity and rapid merchant onboarding without fixed-line infrastructure.
- Traditional POS:Countertop devices with Ethernet connectivity, secure element chips, and EMV L1/L2 certification anchor supermarket checkout lanes and hotel front desks. The Central Transdanubia retail corridor sustains replacement demand as merchants upgrade for instant payment compliance.
- Self-Service Kiosk:Freestanding units with touchscreen interfaces and integrated card readers serve quick-service restaurants and cinema chains seeking labor cost reduction.
- POS Software:Middleware platforms handling transaction routing, inventory synchronization, and sales analytics command recurring revenue from multi-location restaurant operators.
Mature deployment sits with Traditional POS. Newer deployment is concentrated in Mobile POS.
Delivery Mode:
Cost tier differentiation separates subscription-based remote management from capital-intensive local infrastructure ownership.
- Cloud-Based:SaaS architectures with automatic firmware updates and centralized merchant dashboards eliminate on-premises server maintenance. Budapest's district VII restaurant cluster adopts these systems fastest, prioritizing real-time sales visibility across multiple locations.
- On-Premises:Dedicated server installations with local transaction storage appeal to large retailers with legacy ERP integration requirements and data sovereignty preferences.
- Hybrid:Split architectures process payments locally while syncing analytics to cloud instances serve merchants with intermittent connectivity.
- Local Installation:Single-device software deployments without network dependencies persist among seasonal market vendors and rural merchants with limited broadband access.
Established merchants favor On-Premises control. Expansion is climbing the fastest in Cloud-Based delivery.
End User:
Application-specific workflows dictate terminal specification priorities across Hungarian commerce verticals.
- Retail Stores:Fashion boutiques and electronics shops in Budapest's Andrássy Avenue corridor prioritize compact terminals with inventory barcode integration and customer display screens.
- Restaurants:Full-service operators demand tableside payment capability, tip adjustment workflows, and kitchen printer connectivity. The National Bank of Hungary's instant payment mandate accelerates terminal refresh in this segment.
- Hotels:Property management system integration and multi-currency support drive procurement decisions among Budapest's district VI hospitality cluster.
- Supermarkets:High-throughput checkout environments require durable PIN pads, customer-facing displays, and loyalty program integration at scale.
Volume leadership belongs to Supermarkets. Technology upgrade urgency concentrates in Restaurants.
Payment Method:
Customer-facing interface requirements split terminal design between card-present hardware and contactless proximity protocols.
- Credit Card:Magnetic stripe and EMV chip transactions require certified card readers with PCI DSS compliance, sustaining hardware demand among merchants serving tourist and business traveler segments.
- Debit Card:Domestic scheme acceptance and instant payment protocol support dominate Hungarian merchant specifications under central bank regulatory pressure.
- Mobile Payments:QR code scanning and wallet app integration capabilities are expanding most quickly among younger demographic targets in Budapest's urban core.
- Contactless:NFC tap-to-pay functionality with sub-100ms transaction times has become baseline specification across all terminal categories serving Hungarian food service and retail.
Ubiquitous deployment covers Contactless. Steepest expansion trajectory appears in Mobile Payments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant demand for integrated POS systems concentrates in Budapest and the Central Transdanubia region, with secondary urban centers emerging as priority expansion targets for cloud-native terminal vendors.
Budapest
The capital's district VI and district VII restaurant clusters drive premium terminal procurement tied to property management system upgrades. The National Bank of Hungary's instant payment mandate accelerates hardware refresh cycles among full-service operators. Andrássy Avenue fashion boutiques prioritize compact terminals with barcode integration and customer-facing displays.
Central Transdanubia
Székesfehérvár and Tatabánya retail corridors sustain replacement demand for traditional countertop devices with EMV certification. Merchants in this corridor upgrade terminal fleets to comply with real-time settlement protocols. Supermarket checkout lanes and hotel front desks anchor hardware volume in this sub-region.
Western Transdanubia
Győr-based logistics and manufacturing SMEs generate demand for mobile POS units with cellular connectivity. The region's delivery services and courier fleets favor rapid merchant onboarding without fixed-line infrastructure. Seasonal market vendors in rural pockets persist with local-installation software deployments.
Southern Great Plain
Kecskemét and Szeged hospitality operators are adopting tableside ordering applications bundled with payment acceptance. The National Bank of Hungary's regulatory pressure shapes authentication protocol specifications across this agricultural and food-processing hub. Quick-service restaurants and cinema chains drive self-service kiosk interest for labor cost reduction.
Hungary POS Terminal Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native onboarding speed for micro-merchants outside traditional banking channels. The vendor base splits between European processing backbone operators and regional specialists serving Hungarian distribution channels. Two strategic archetypes dominate: merchant acquirer-aligned hardware platforms and software-defined terminal aggregators. Competitive moves concentrate on geographic expansion into underpenetrated secondary urban centers and portfolio diversification toward hospitality vertical convergence.
Within the European processing tier, Worldline SA and Ingenico occupy positions anchored to merchant acquirer relationships and high-volume supermarket segments respectively. myPOS exemplifies the cloud-native archetype competing on rapid micro-merchant onboarding without traditional banking ties. Regional specialists including B-Payment Szolgáltató Zrt and SRS Informatika Kft represent Hungary-based service providers navigating the National Bank of Hungary's certification requirements.
| Leading Market Players |
|---|
| B-Payment Szolgáltató Zrt |
| Bartimex Kft |
| Worldline SA |
| Ingenico |
| myPOS |
| Novopayment |
| Quadrapay |
| eService Sp z o o |
| SRS Informatika Kft |
| Others |
Supply & Pricing Matrix
The National Bank of Hungary's instant payment mandate compresses hardware refresh cycles, forcing terminal vendors to absorb recertification costs while merchants demand cloud-native subscription models over capital-intensive purchases.
Pricing Analysis
Volume concentration in mobile POS units for street vendors and delivery fleets runs on thin per-unit margins, while fixed traditional POS installations for Budapest hotel chains and supermarket operators capture premium pricing through bundled software layers and multi-year service contracts. Price differentiation hinges on EMV certification tier and after-sales support bundling, with PCI DSS Level 1 compliance commanding substantial premiums over basic EMV L1-only devices. Cost compression in entry-level hardware is intensifying because semiconductor input volatility from Asian foundries squeezes European vendor margins. Micro-merchants without banking relationships exhibit highest price sensitivity, driving myPOS and similar aggregators toward zero-upfront SaaS tiers; large retail chains with dedicated procurement teams show lowest sensitivity, prioritizing integration reliability over unit cost.
Supply Chain Analysis
Domestic-content requirements under EU procurement directives reshape sourcing strategies, though Hungary's limited semiconductor fabrication capacity forces terminal assemblers to maintain concentrated dependence on Taiwan, South Korea, and China for secure element chips, NFC controllers, and thermal printer mechanisms. Raw material dependencies center on rare earth elements for magnetic components, copper for circuit boards, and specialized plastics for durable casings. Single-source vulnerability in advanced chip foundry capacity represents the dominant structural risk, with any geopolitical disruption to Taiwan Strait logistics cascading through European terminal production schedules. Distribution runs through Budapest-based merchant acquirer networks and regional IT distributors serving Central Transdanubia retail corridors, with direct-to-merchant cloud onboarding bypassing traditional hardware channels fastest among micro-merchant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop hardware pricing, creating a supply-constrained market where procurement timing and supplier relationships determine competitive position more than feature differentiation alone.
For Market Incumbents: Anticipate margin compression from SoftPOS substitution by accelerating firmware development for biometric authentication modules that satisfy PSD2 strong customer authentication requirements before compliance deadlines. Deepen backward integration into secure element supply through strategic partnerships with European chip designers, reducing exposure to Taiwan foundry concentration. Defend merchant acquirer channel relationships in Budapest's district VI and VII hospitality clusters through native property management system integrations that raise switching costs. For New Entrants and Emerging Players: Enter via cloud-native onboarding platforms targeting Székesfehérvár and Tatabánya in Central Transdanubia, where integrated POS penetration remains lowest among secondary urban centers. Prioritize tableside ordering application bundles for full-service restaurants in Southern Great Plain cities Kecskemét and Szeged, where labor cost reduction pressures drive hospitality technology refresh. Pursue direct digital distribution models that compress time-to-first-transaction below traditional banking channels' multi-week onboarding timelines. For Investors and Strategic Acquirers: The window for entry favors software-defined terminal aggregators with captive micro-merchant relationships and GDPR-compliant analytics capabilities over hardware-centric legacy vendors. Long-term viability rests on owning merchant data flows rather than device shipments, with recurring SaaS revenue multiples substantially exceeding hardware margin profiles. Monitor National Bank of Hungary regulatory timing announcements as the critical inflection signal, as instant payment mandate acceleration would force replacement demand spikes favoring vendors with pre-certified device inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | SaaS architectures eliminate on-premises server costs for Budapest multi-location restaurant operators. |
| Biometric Module Integration | PSD2 compliance drives fingerprint sensor adoption in supermarket and large retail terminal specifications. |
| Secondary Urban Expansion | First-mover positioning in Székesfehérvár and Tatabánya captures underpenetrated Central Transdanubia demand. |
| Vertical Software Bundling | Native property management system compatibility secures Budapest district VI hospitality procurement decisions. |
| GDPR-Compliant Analytics Development | Transaction data monetization services respect European data protection while creating adjacent revenue streams. |
Research Methodology
Independent corroboration across merchant acquirer procurement directors, terminal vendor product managers, and National Bank of Hungary regulatory officials underwrites the qualitative findings, with secondary validation drawing from EU payment system directives, EMVCo certification databases, and Hungarian central bank policy releases. Primary fieldwork encompassed interviews with hospitality technology buyers in Budapest's district VII cluster, retail operations heads across Central Transdanubia supermarket chains, and firmware engineering leads at regional terminal assemblers. Bottom-up terminal shipment estimates triangulate against top-down merchant acquirer transaction volume disclosures.
Rate-of-change decomposition separates volume growth drivers by product type, delivery mode, and end-user vertical across the analysis window, with CAGRs derived from logistic adoption curve fitting and replacement cycle modeling. Segmentation dimensions include hardware form factor, software architecture, merchant size tier, and geographic density cluster. Forecast inputs incorporate regulatory mandate implementation timelines, semiconductor supply lead times, and cloud migration adoption velocities specific to Hungarian SME digitization patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated instant payment mandate enforcement or prolonged chip shortage conditions. Analytical boundaries exclude adjacent payment acceptance technologies such as pure-play SoftPOS applications without dedicated hardware, and exclude cross-border merchant acquiring outside Hungarian regulatory jurisdiction. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Payment Data Protection Market
Payments
Freight Audit and Payment Service Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Kenya Mobile Money Market
Payments
Direct Carrier Billing Market
Payments
Spain POS Terminals Market
Payments
Global Payment Gateways Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Global Utility Billing Software Market
Payments
Spain Mobile Payment Market
Payments
Subscription Billing Management Market
Payments
Ghana Mobile Money Market
Payments
Norway POS Terminals Market
Payments
Germany Real Time Payments Market
Payments
Proximity Payment Market
Payments
United States POS Terminals Market