
 Netherlands Mobile Payments Market | 2026-2036
Netherlands Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Mobile Payments Market Foresight
Developer talent scarcity in Dutch fintech is collapsing as universities expand quantum cryptography and blockchain curricula. Adyen sustains its merchant-acquiring dominance through in-house risk engines that process transactions across European corridors. iDEAL BV anchors domestic bank-to-bank transfers with near-universal Dutch banking coverage, while Tikkie competes in social peer-to-peer payments through seamless WhatsApp integration.
Netherlands mobile payments encompass digital fund transfers executed through smartphone applications, near-field communication protocols, or QR-code interfaces, with transaction authentication relying on tokenized credentials and biometric verification rather than physical card presentation. These systems serve retail commerce, utility settlement, and interpersonal remittance by replacing cash and card-present interactions with encrypted, real-time electronic clearing. Mobile wallet deployment leads transaction volume growth as consumers consolidate cards and loyalty credentials within single applications, while bank transfer mechanisms retain structural importance for high-value B2B settlements. Developer-facing API layers represent the fastest-expanding segment as enterprises embed payment orchestration directly into proprietary commerce platforms.
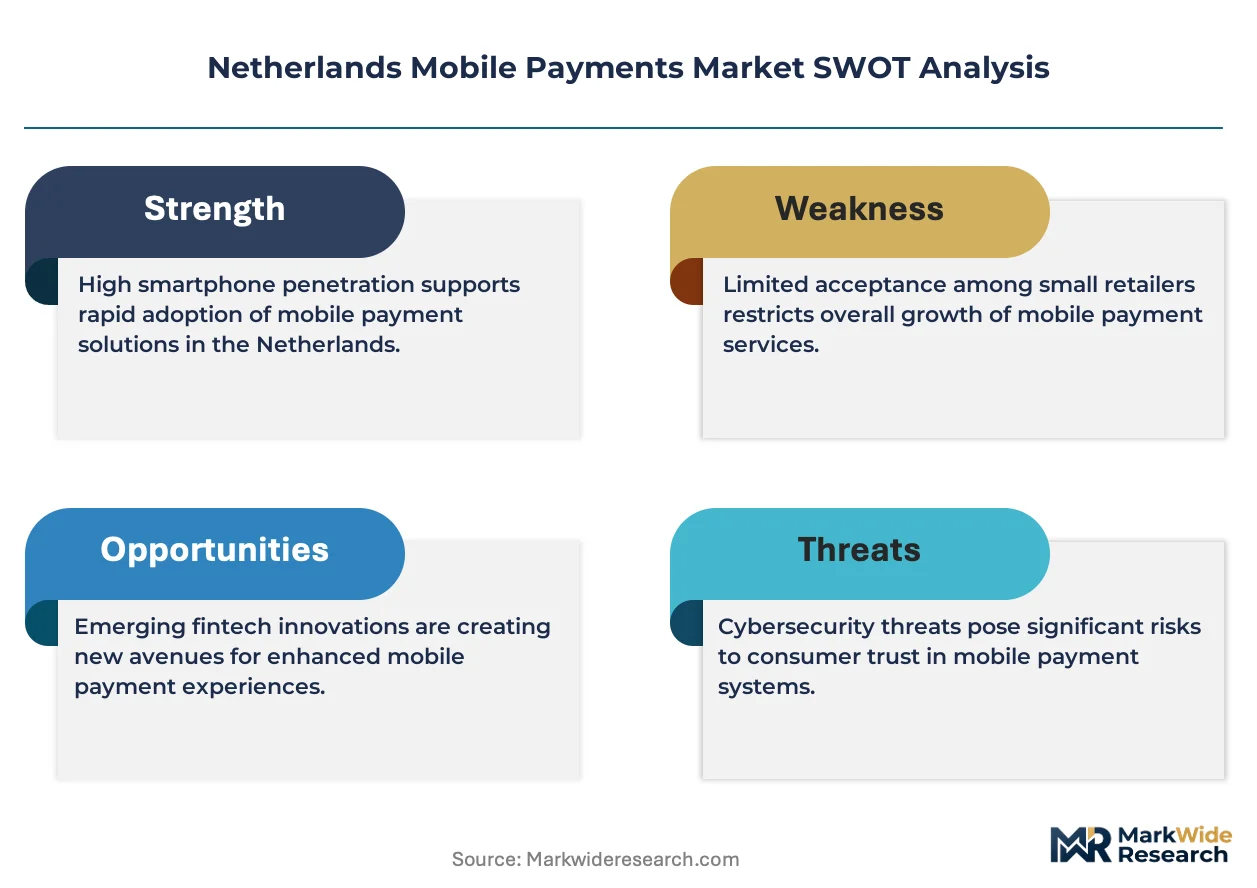
De Nederlandsche Bank enforces anti-money laundering directives and payment institution licensing under PSD2 transposition, while the Dutch Data Protection Authority applies GDPR constraints to transaction data retention and profiling algorithms. These frameworks elevate compliance costs for new entrants but reinforce incumbent trust advantages among risk-averse merchant segments. Stakeholders must monitor forthcoming instant payment settlement mandates and central bank digital currency pilots that could recast interoperability requirements.
Market Dynamics
PSD2 Strong Customer Authentication mandates are compressing checkout friction tolerance among Dutch consumers, forcing merchants to abandon legacy redirect flows in favor of embedded tokenized payment experiences.
Growth Catalysts
- Instant Payment Settlement:The European Central Bank's TARGET Instant Payment Settlement (TIPS) infrastructure enables real-time euro clearing, eliminating settlement risk for Dutch e-commerce merchants and B2B platforms.
- Biometric Authentication:Fingerprint and facial recognition protocols embedded in Dutch banking apps reduce transaction abandonment at digital checkout points.
- Rotterdam Port-Commerce Digitization:Container logistics operators in the Netherlands' largest port cluster are adopting mobile wallet integrations for customs duties and terminal handling charges.
Market Restraints
- GDPR Transaction Data Retention:The Dutch Data Protection Authority's strict interpretation of profiling restrictions limits merchant analytics capabilities and increases compliance overhead.
- iDEAL Network Concentration:Domestic bank-to-bank transfer infrastructure remains controlled by a single clearing entity, creating single-point-of-failure vulnerability for Dutch digital commerce.
- Legacy POS Hardware Depreciation Cycles:Small Dutch retailers face stranded asset risk from contactless terminal investments made under pre-PSD2 technical standards.
Strategic Opportunities
- Cross-Border Eurozone Expansion:Dutch payment orchestration platforms can leverage SEPA harmonization to capture merchant-acquiring volume in Belgium and Germany.
- Central Bank Digital Currency Pilots:De Nederlandsche Bank's experimental digital euro programs create first-mover positioning for wallet providers in programmable money infrastructure.
- API-First B2B Integration:Enterprise treasury departments in Amsterdam's fintech corridor seek embedded payment workflows for supplier financing and automated reconciliation.
Industry Challenges
- Quantum-Resistant Cryptography Talent:Dutch universities are expanding blockchain curricula but graduating insufficient engineers to meet fintech security demands.
- PSD2 Compliance Architecture Migration:Payment service providers must rebuild authentication stacks to accommodate forthcoming instant payment settlement mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Mobile Payments Market |
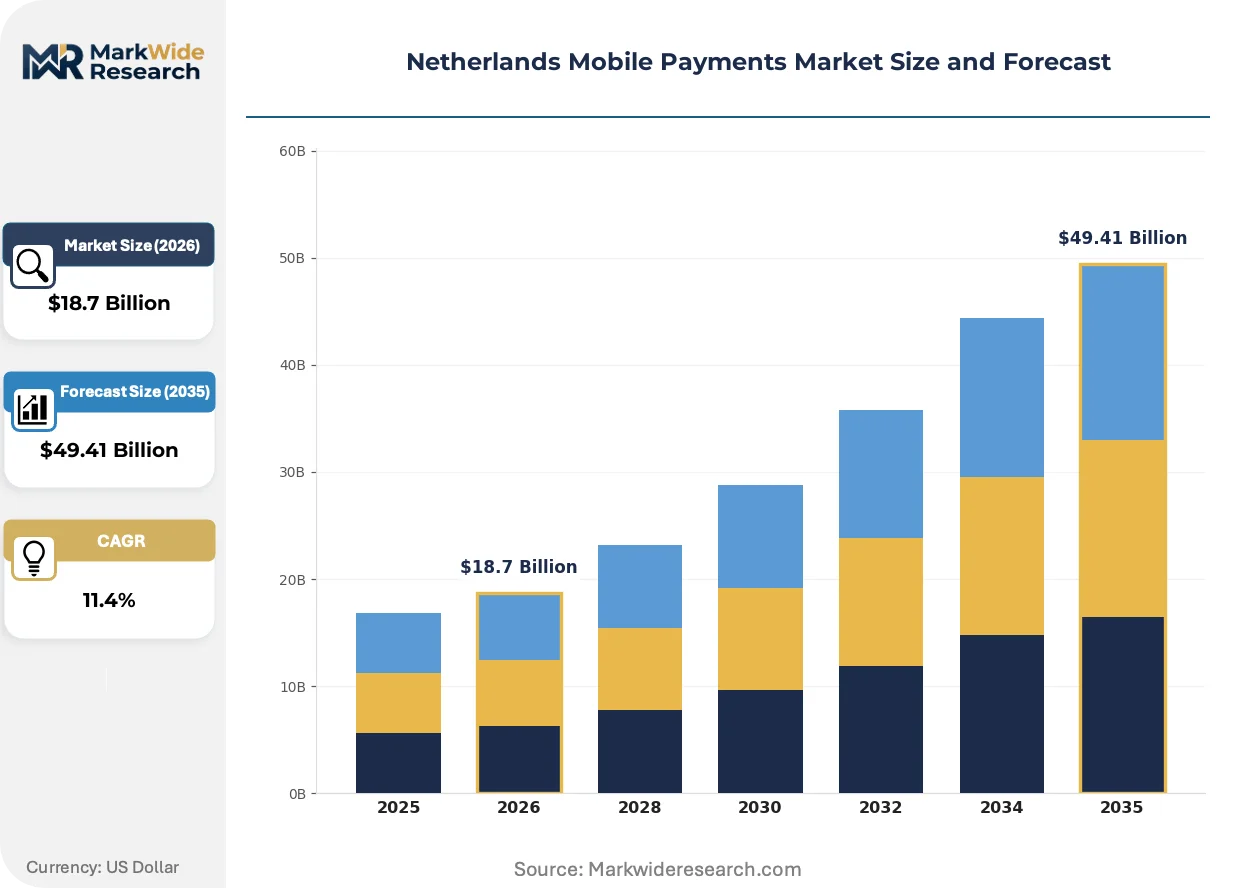
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer User Type: Consumer, Merchant, Business, Developer Transaction Type: In-Store Purchase, Online Purchase, Bill Payment, Fund Transfer Service Provider: PayPal, Apple Pay, Google Pay, Samsung Pay |
| Companies Covered | Visa Inc., PayPal Holding Inc., Klarna, iDEAL BV, Tikkie (ABN AMRO), Adyen, Apple Inc., Alphabet Inc. (Google), MasterCard International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Mobile Payments Market Shifts & Advancements
Tokenized credential vaulting is compressing consumer card-not-present fraud exposure while enabling loyalty program convergence within single mobile interfaces. Dutch merchants and infrastructure providers are racing to deploy next-generation authentication protocols ahead of regulatory deadlines.
SoftPOS technology is supplanting dedicated hardware terminals among Dutch micro-merchants and pop-up retailers. Street vendors in Amsterdam's Nine Streets district and seasonal operators at Rotterdam's Markthal now convert NFC-enabled smartphones into payment acceptance devices without dedicated terminal procurement. This shift collapses merchant onboarding timelines from weeks to hours and eliminates hardware leasing overhead.
De Nederlandsche Bank's implementation of PSD2 Strong Customer Authentication is forcing Dutch payment service providers to abandon static password flows. Merchants serving risk-averse demographic segments—particularly elderly consumers in rural Gelderland and Overijssel provinces—are experiencing elevated cart abandonment during multi-factor authentication steps. Providers are responding with behavioral biometrics and device fingerprinting to reduce explicit consumer friction.
Subscription bundling is reshaping Dutch consumer payment preferences as households consolidate streaming, mobility, and insurance services within single wallet applications. Young professionals in Utrecht and Eindhoven increasingly demand unified billing interfaces that aggregate recurring charges across verticals. This pattern pressures standalone payment apps to integrate with super-app ecosystems or cede primary interface positioning to consolidated platforms.
Netherlands Mobile Payments Market Segmentation
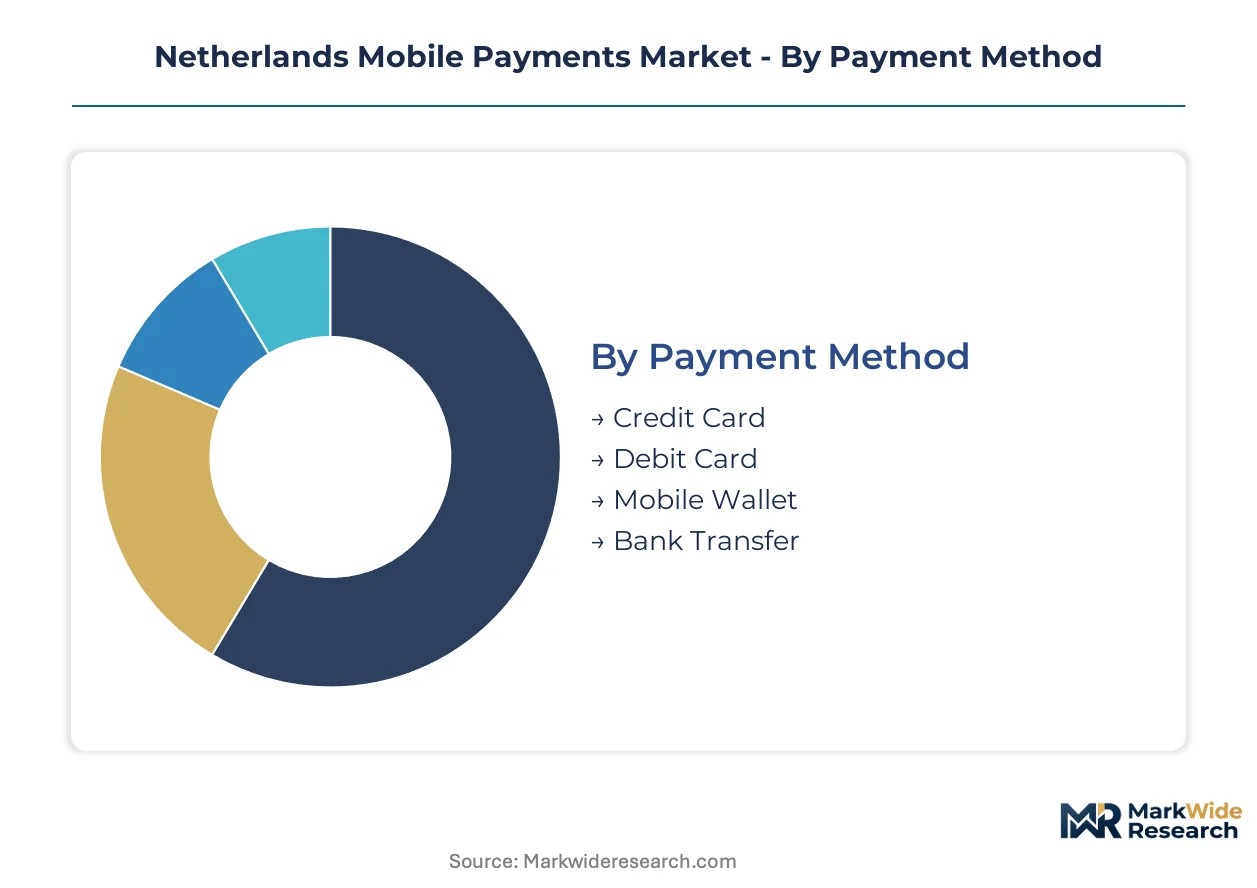
Dutch mobile payment flows fragment across four structural dimensions that determine authentication architecture, settlement velocity, and API integration requirements. Each segmentation axis carries distinct regulatory exposure and merchant onboarding friction profiles.
Payment Method:
Mobile wallets face the strongest substitution pressure from embedded bank-to-bank rails, while card-based instruments confront PSD2 Strong Customer Authentication compliance costs.
- Credit Card:Tokenized credential vaulting within Dutch banking apps preserves card-not-present transaction flows. Demand concentrates among Amsterdam hospitality merchants serving international tourists unfamiliar with domestic iDEAL infrastructure.
- Debit Card:Real-time euro clearing through SEPA Instant enables sub-second settlement for Dutch retail purchases. Rotterdam port-commerce operators favor debit rails for customs duty payments requiring immediate fund verification.
- Mobile Wallet:Consolidated loyalty and payment credential storage drives consumer preference among Utrecht young professionals.
- Bank Transfer:Direct account-to-account clearing dominates B2B settlements across Gelderland manufacturing corridors.
Bank Transfer anchors the volume base while Mobile Wallet gains share at the steepest rate.
User Type:
Enterprise treasury departments command premium pricing for API orchestration layers, whereas consumer-facing applications compete on transaction fee compression.
- Consumer:Biometric authentication adoption peaks among Eindhoven tech sector employees demanding seamless checkout across streaming and mobility subscriptions.
- Merchant:SoftPOS deployment accelerates among Amsterdam street vendors eliminating dedicated terminal procurement.
- Business:Automated reconciliation workflows attract Rotterdam logistics operators managing multi-currency supplier payments.
- Developer:Payment orchestration API integration commands highest margin tiers within Amsterdam fintech corridor enterprises.
Consumer interfaces deliver the volume foundation while Developer tools climb the fastest.
Transaction Type:
In-store NFC adoption is displacing QR-code interfaces as contactless terminal penetration saturates Dutch retail.
- In-Store Purchase:Near-field communication protocols dominate Rotterdam Markthal seasonal vendor transactions through smartphone acceptance.
- Online Purchase:Embedded checkout experiences replace legacy redirects among risk-averse elderly consumers in rural Overijssel.
- Bill Payment:Utility settlement automation concentrates demand among Utrecht household subscription bundling preferences.
- Fund Transfer:Peer-to-peer social payment integration through messaging platforms drives Tikkie adoption.
Online Purchase commands current volume leadership while In-Store Purchase expands most quickly.
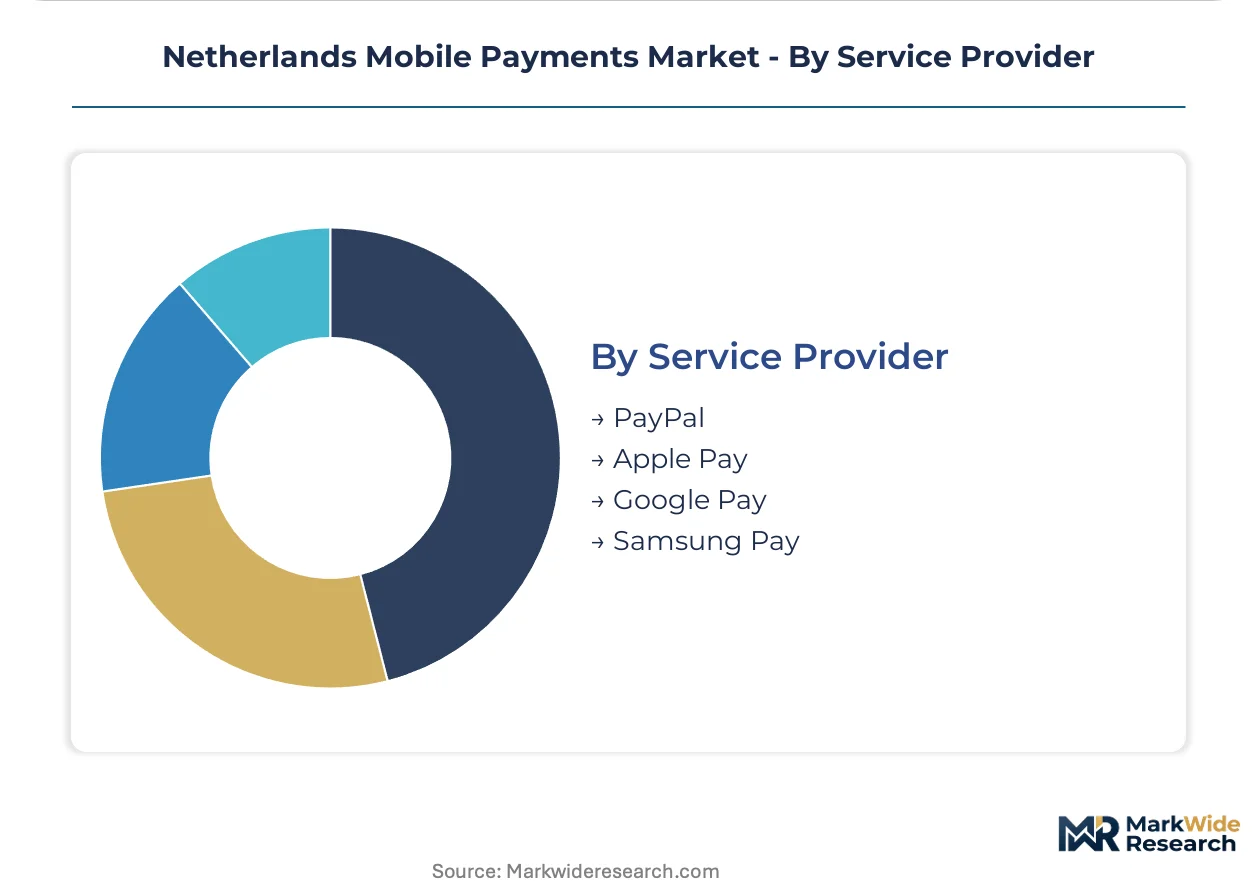
Service Provider:
Device-embedded wallets leverage hardware security modules against cloud-based platform vulnerabilities.
- PayPal:Cross-border merchant acquiring strength serves Dutch exporters penetrating Belgian and German e-commerce corridors.
- Apple Pay:Secure Element authentication satisfies De Nederlandsche Bank PSD2 compliance requirements for high-value transactions.
- Google Pay:Android device penetration dominates among Rotterdam port logistics workforce demographics.
- Samsung Pay:MST fallback technology preserves utility among legacy terminal infrastructure in rural Gelderland retail.
Apple Pay anchors premium transaction value while Google Pay shows the steepest user acquisition trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Dutch provinces, with Randstad metropolitan corridors driving mobile wallet adoption while rural peripheries retain bank-transfer dominance for high-value settlements.
Randstad
Amsterdam's fintech corridor concentrates developer-facing API demand as enterprises embed payment orchestration into proprietary platforms. De Nederlandsche Bank's PSD2 enforcement elevates compliance costs for new entrants. Rotterdam's port-commerce ecosystem digitizes container logistics through mobile wallet integrations for customs duties.
North Brabant
Eindhoven's tech sector workforce demands biometric authentication across streaming and mobility subscription bundles. The Dutch Data Protection Authority's GDPR interpretation limits merchant analytics capabilities. Tilburg's retail operators deploy SoftPOS terminals to eliminate dedicated hardware procurement for seasonal vendors.
Utrecht
Young professionals consolidate recurring charges across insurance and mobility services within unified billing interfaces. The European Central Bank's TIPS infrastructure enables real-time euro clearing for local e-commerce merchants. The city's central location anchors B2B payment automation for supplier financing workflows.
Gelderland
Manufacturing corridors favor direct account-to-account clearing for high-value B2B settlements over card-based rails. De Nederlandsche Bank's anti-money laundering directives enforce strict payment institution licensing. Nijmegen's logistics operators manage multi-currency supplier payments through automated reconciliation systems.
Northern Netherlands
Elderly consumers in rural Overijssel provinces experience elevated cart abandonment during multi-factor authentication steps. PSD2 Strong Customer Authentication mandates compress checkout friction tolerance among risk-averse demographics. Groningen's university spin-offs expand quantum cryptography curricula to address fintech security talent scarcity.
Netherlands Mobile Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with merchant-acquiring platforms and bank-owned domestic rails commanding distinct competitive vectors. The upper tier consolidates around payment orchestration engines and device-embedded wallets, while specialists cluster in social peer-to-peer and B2B automation niches. Two strategic archetypes dominate: vertically integrated acquirers processing transactions across European corridors, and bank consortium utilities anchoring domestic account-to-account infrastructure. Competitive moves concentrate on API-first embedding and biometric authentication stack upgrades.
Within the integrated acquirer tier, Adyen and iDEAL BV occupy positions that exemplify divergent structural approaches—one spanning pan-European merchant services, the other anchoring domestic bank-to-bank concentration. Among messaging-integrated specialists, Tikkie represents the social payment archetype through seamless platform embedding. These three entities collectively illustrate how Dutch market structure fragments between international scale and domestic utility control.
| Leading Market Players |
|---|
| Visa Inc. |
| PayPal Holding Inc. |
| Klarna |
| iDEAL BV |
| Tikkie (ABN AMRO) |
| Adyen |
| Apple Inc. |
| Alphabet Inc. (Google) |
| MasterCard International Inc. |
| Others |
Supply & Pricing Matrix
SoftPOS terminal substitution for dedicated hardware is compressing merchant onboarding costs while redistributing supply value toward smartphone OEMs and away from traditional terminal manufacturers. This shift simultaneously concentrates component sourcing in East Asian electronics corridors and erodes leasing-based pricing models that once anchored Dutch micro-merchant payment acceptance.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise payment orchestration pricing, while transactional per-unit models prevail among micro-merchants. Three-tier pricing structure across premium API access, standard dashboard tools, and economy self-serve tiers reflects vertical integration depth and support bundling. Pricing pressure stems from PSD2 compliance cost absorption by providers competing for merchant-acquiring volume. Small retailers in rural Gelderland exhibit highest price sensitivity, whereas Amsterdam fintech corridor enterprises prioritize integration speed over fee compression.
Supply Chain Analysis
Just-in-time component procurement dominates Dutch payment terminal assembly, though strategic stockpiling of secure element chips has intensified following semiconductor allocation constraints. Hardware manufacturing concentrates in China, Taiwan, and Vietnam, with final assembly and firmware customization anchored in the Netherlands and Germany. Secure element and NFC controller dependencies create single-source vulnerability exposure for European terminal vendors. Distribution runs through value-added resellers and direct API provisioning channels serving distinct merchant scale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch mobile payment incumbents face sustained substitution pressure from instant bank-to-bank rails and embedded wallet infrastructure that threaten to disintermediate traditional acquiring relationships.
For Market Incumbents: Compound authentication stack investments to defend merchant relationships against embedded-finance entrants. Prioritize biometric behavioral analytics deployment to reduce PSD2-induced cart abandonment among elderly demographics. Deepen vertical integration into token vaulting infrastructure to capture margin pools currently ceded to cloud security providers. For New Entrants and Emerging Players: API orchestration gaps in B2B supplier financing workflows present immediate white-space opportunity. Target Rotterdam logistics operators managing multi-currency settlement automation as the most penetrable enterprise segment. Pursue partnership-first go-to-market positioning with existing ERP vendors rather than direct merchant acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed payment orchestration platforms seeking geographic expansion capital. Five-to-ten year viability hinges on SEPA Instant infrastructure penetration and programmable money protocol adoption. Monitor De Nederlandsche Bank central bank digital currency pilot announcements as definitive inflection signal for wallet provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Stack Upgrade | PSD2 compliance deadlines force merchant-facing providers to eliminate static password flows entirely. |
| API-First B2B Integration | Enterprise treasury departments in Amsterdam's fintech corridor demand embedded supplier financing workflows. |
| SoftPOS Technology Deployment | Street vendors across Rotterdam Markthal eliminate hardware procurement through smartphone acceptance conversion. |
| Cross-Border Eurozone Expansion | SEPA harmonization enables Dutch orchestration platforms to capture Belgian and German merchant volume. |
| Central Bank Digital Currency Readiness | De Nederlandsche Bank experimental programs create first-mover positioning for programmable money infrastructure. |
Research Methodology
Desk research of ECB payment statistics, De Nederlandsche Bank regulatory filings, and SEPA infrastructure disclosures preceded structured interviews with payment service provider executives, merchant acquiring leads, fintech platform engineers, and enterprise treasury managers. Primary fieldwork combined with secondary validation against SEC filings of listed payment processors and European Banking Authority supervision reports. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored value estimates.
Variance decomposition across payment method, user type, transaction type, and service provider segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory mandate implementation schedules. Forecast inputs incorporated TIPS infrastructure penetration rates and biometric authentication deployment timelines specific to Dutch banking app ecosystems.
Forecasts assume regulatory continuity in PSD2 transposition and GDPR enforcement; material policy shifts would require re-modeling. Specific risks include instant payment settlement mandate acceleration, central bank digital currency interoperability requirements, and quantum-resistant cryptography standard adoption. Revision becomes warranted when biometric authentication abandonment rates or merchant API integration velocity crosses thresholds outside modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Electronic Payment Processing Software Market
Payments
Smart Home Payments Market
Payments
In-Vehicle Payment Services Market
Payments
M Commerce Payment Market
Payments
Canada POS Terminal Market
Payments
France Buy Now Pay Later Services Market
Payments
China Virtual Cards Market
Payments
South Korea Mobile Payment Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Singapore Remittance Market
Payments
Middle East and Africa Payments Market
Payments
Portugal POS Terminals Market
Payments
Global Digital Wallets Market
Payments
Ghana Mobile Money Market
Payments
Southeast Asia POS Terminal Market